
 AI Voice Cloning Market | 2026-2036
AI Voice Cloning Market Size, Share, and Industry Trends Forecast 2026-2036
AI Voice Cloning Market Analytics
Multi-source API aggregation is realigning how enterprises procure voice synthesis capabilities, shifting from single-vendor lock-in toward modular stacks that mix specialized providers. Google LLC leverages its tensor processing infrastructure to anchor cloud-based training pipelines for high-fidelity voice models. ElevenLabs differentiates through granular emotional control parameters that attract independent creators and mid-sized studios. Amazon.com, Inc. sustains dominance in conversational AI channels by integrating cloned voices tightly with its Alexa developer ecosystem.
AI voice cloning synthesizes human speech patterns using deep neural networks trained on acoustic features such as mel-frequency cepstral coefficients and prosodic timing maps, producing output indistinguishable from source speakers for commercial applications including automated narration, accessibility tools, and localized content production. Cloud-based deployment captures the largest revenue share as enterprises prioritize elastic compute scaling over capital-intensive on-premise GPU clusters. Text-to-Speech solutions lead volume adoption in customer service and e-learning verticals, while speech-to-speech transformation commands premium pricing in entertainment dubbing where real-time voice preservation matters most.
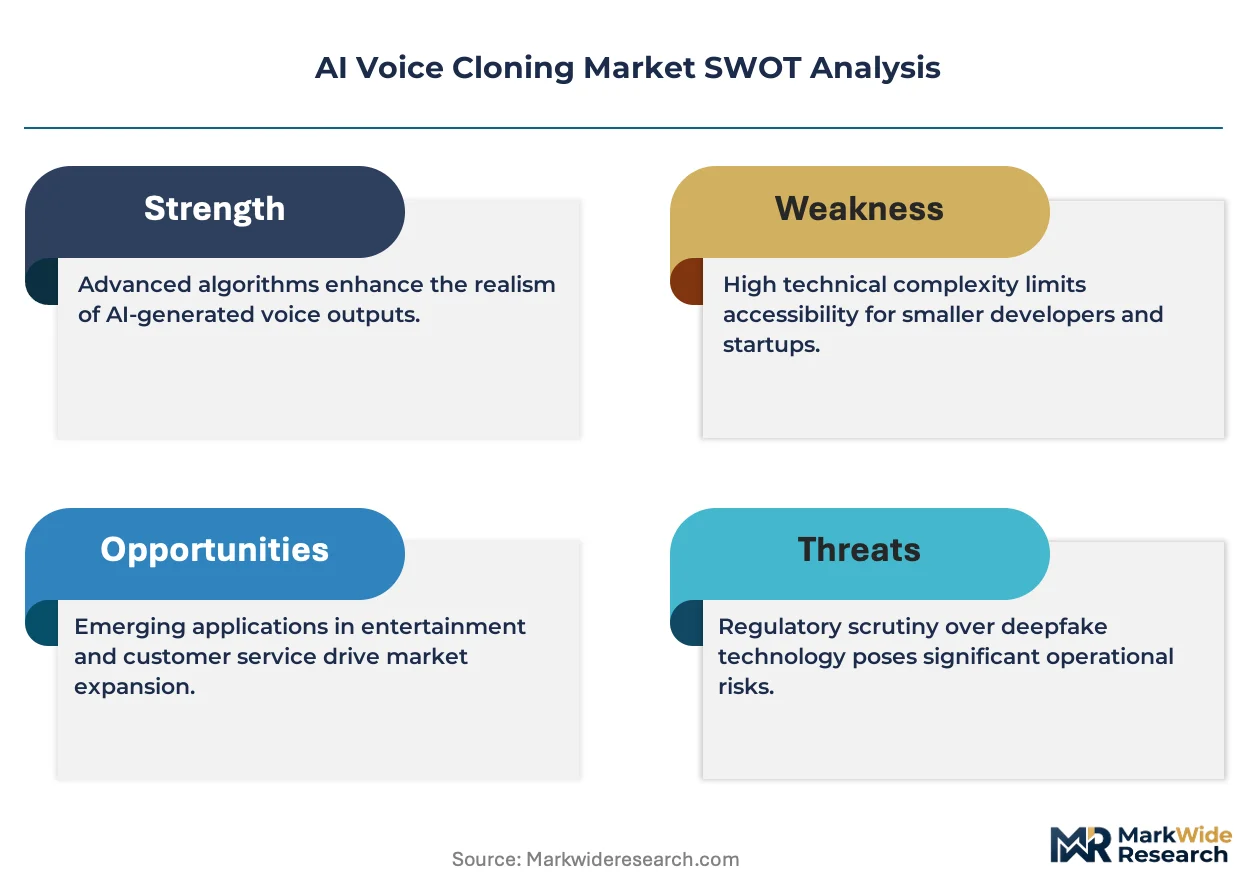
The Federal Trade Commission in the United States scrutinizes deceptive synthetic media disclosures, while the EU AI Act mandates transparency labeling for AI-generated audio content deployed in European markets. China's Cyberspace Administration imposes content review requirements on voice synthesis services, creating compliance layers that favor domestic platform operators. Stakeholders must monitor evolving biometric privacy statutes and emerging deepfake liability frameworks as jurisdictions race to define accountability boundaries for synthetic voice deployment.
Market Dynamics
Neural codec compression is collapsing training data requirements from hours to minutes, forcing studios in Los Angeles and Mumbai to restructure localization workflows around real-time voice synthesis pipelines rather than traditional talent contracts.
Growth Catalysts
- EU AI Act transparency mandates:Disclosure requirements for synthetic audio create compliance software demand that platforms bundle with core voice services.
- Neural TTS architectures:Transformer-based acoustic models slash inference latency below 200 milliseconds, enabling live dubbing for streaming content.
- Accessibility regulations:Section 508 refresh and WCAG 3.0 guidelines in the United States mandate screen reader compatibility that cloned voices satisfy at lower cost than human narration.
Market Restraints
- GPU supply concentration:Cloud training clusters depend on NVIDIA H100 allocations concentrated in Taiwan and South Korea foundries, creating capacity bottlenecks.
- Biometric privacy statutes:Illinois BIPA and Texas biometric laws impose per-violation damages that chill voice dataset commercialization.
- Emotional fidelity ceilings:Prosodic modeling still struggles with sarcasm detection and micro-emotion rendering in non-Indo-European languages.
Strategic Opportunities
- India's dubbing localization gap:22 official languages and fragmented talent pools create white space for synthetic voice deployment in Bollywood and regional streaming.
- Voice biometric authentication:Convergence of synthesis and speaker verification techs opens financial services applications for liveness detection.
- Japan's aging narrator workforce:Retiring seiyuu create replacement demand that synthetic voices address with rights-holder licensing frameworks.
Industry Challenges
- Phonetic linguist scarcity:Low-resource language coverage requires native speaker linguists for phoneme inventory construction, talent concentrated in academic programs.
- Legacy broadcast integration:SDI and AES67 audio infrastructure in established studios demands custom middleware for real-time synthesis insertion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Voice Cloning Market |
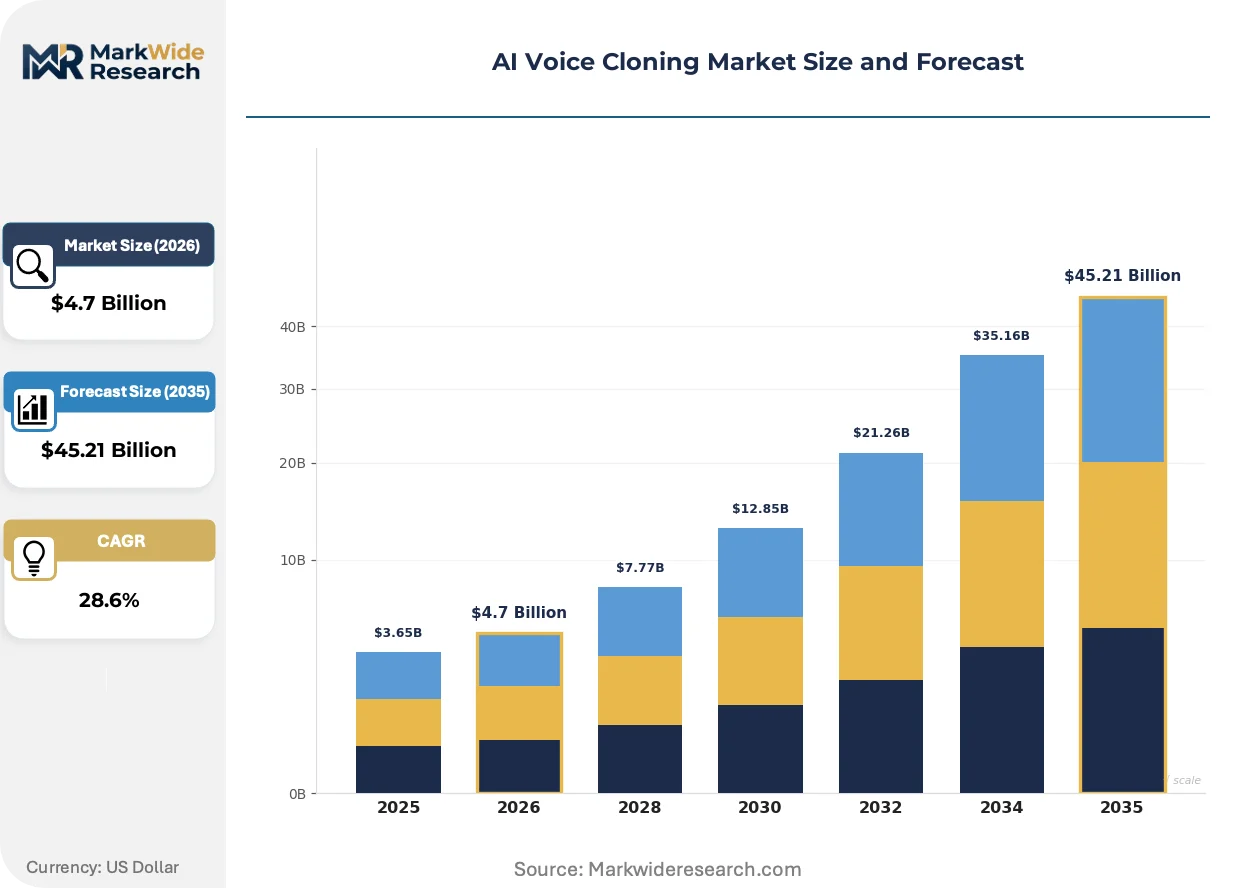
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Text-to-Speech, Speech-to-Speech, Voice Synthesis, Voice Transformation Deployment Model: Cloud-Based, On-Premise, Hybrid, Edge Computing End User: Media, Entertainment, Healthcare, Customer Service Application Area: Gaming, E-Learning, Virtual Assistants, Advertising |
| Companies Covered | Google LLC, Microsoft Corporation, Amazon.com, Inc., IBM Corporation, Descript, Inc., LumenVox LLC, ElevenLabs, Nuance Communications, Baidu, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Voice Cloning Market Evolving Landscape
Generative audio architectures are compressing production timelines from weeks to hours, forcing entertainment studios to renegotiate talent agreements and restructure post-production floor plans around synthetic voice workstations.
Diffusion-based neural vocoders is overtaking autoregressive waveform generators for final-stage audio synthesis. Los Angeles dubbing houses now deploy these models for same-day localization of streaming episodic content. The technology is overtaking traditional ADR booth scheduling by eliminating the need for physical talent presence during mixing sessions.
The EU AI Act's synthetic media labeling requirements took effect in 2024, forcing platforms to embed provenance metadata in generated audio files. European streaming services now filter uploads through automated detection pipelines. German broadcasters have responded by establishing internal ethics review boards for voice cloning project approval.
Enterprise buyers now unbundle voice synthesis from bundled creative suites, contracting directly with specialized API providers for emotional parameter control. Mid-sized podcast networks in the United Kingdom lead this disintermediation, bypassing legacy audio software vendors. The shift concentrates procurement decisions with technical audio leads rather than traditional IT purchasing departments.
AI Voice Cloning Market Segmentation
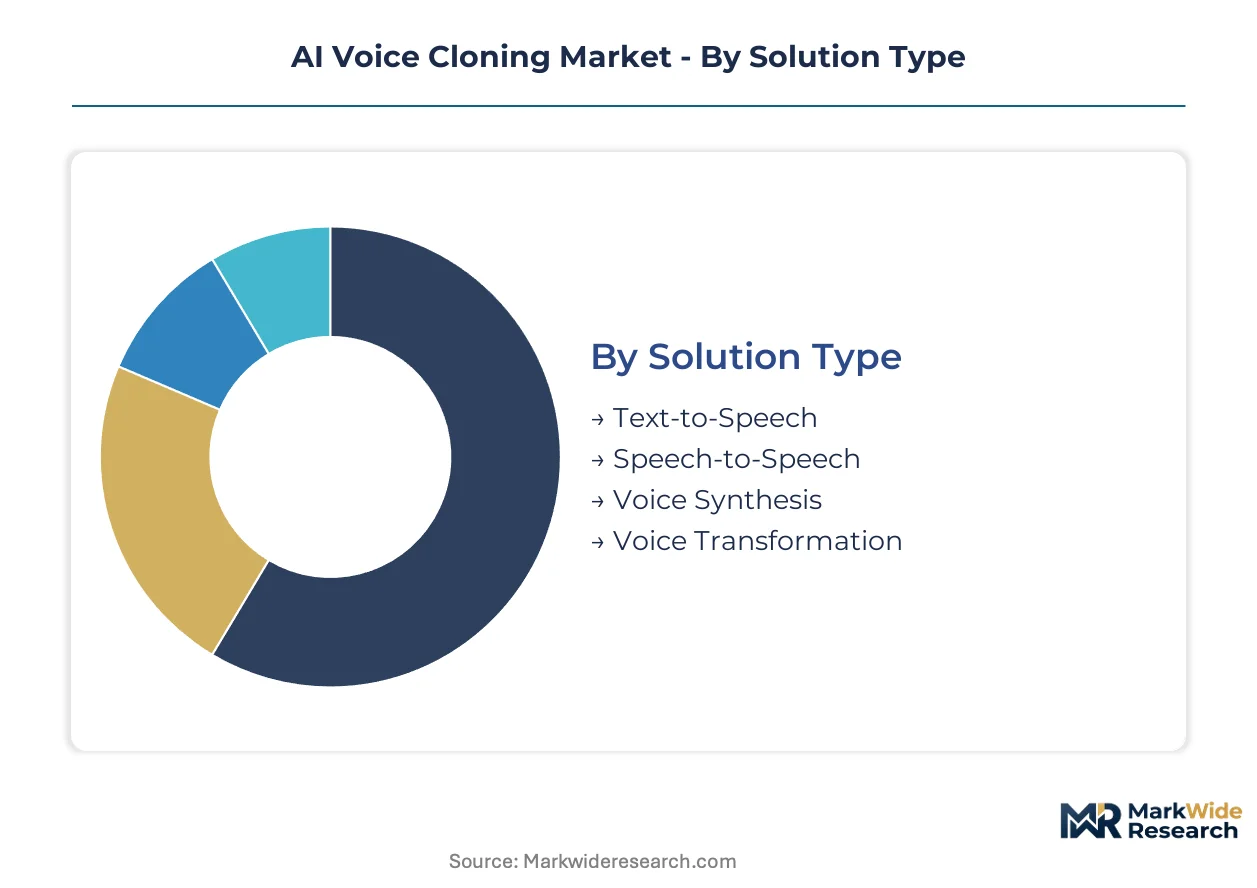
Segmentation in AI voice cloning reveals how technical specifications, infrastructure preferences, and use-case intensity shape procurement patterns. Buyers select solutions based on latency requirements, data sovereignty constraints, and content production workflows rather than generic feature checklists.
Solution Type:
Buyers differentiate primarily by whether they need static audio generation or real-time voice manipulation capabilities.
- Text-to-Speech:Converts written text into synthesized speech using neural acoustic models trained on phoneme-to-spectrogram mappings. Studios in Mumbai deploy TTS for rapid localization of streaming catalogs where script translation precedes voice generation. Cloud inference costs under $0.001 per thousand characters enable high-volume content pipelines.
- Speech-to-Speech:Transforms source speaker audio into target voice characteristics while preserving prosodic timing and emotional inflection. Los Angeles dubbing houses adopt this for same-day celebrity voice replacement in episodic television. Real-time processing demands GPU clusters with sub-200ms latency budgets.
- Voice Synthesis:Generates novel speech from learned speaker embeddings without reference audio input. Academic researchers and accessibility tool developers represent concentrated demand.
- Voice Transformation:Modifies existing recordings to match target speaker traits through style transfer architectures. Podcast networks in the United Kingdom use this for anonymous contributor protection.
Text-to-Speech leads volumes today; Speech-to-Speech is gaining share fastest.
Deployment Model:
Infrastructure choices track data sensitivity thresholds and capital expenditure preferences across enterprise segments.
- Cloud-Based:Elastic compute scaling through tensor processing infrastructure eliminates upfront GPU procurement. Entertainment studios in Los Angeles and Mumbai prioritize this for burst workloads during content release windows. API consumption models align costs with production schedules rather than fixed depreciation.
- On-Premise:Dedicated hardware clusters in enterprise data centers satisfy biometric privacy statutes and content confidentiality requirements. Healthcare systems processing patient voice data favor this architecture.
- Hybrid:Combines cloud training pipelines with on-premise inference nodes for sensitive deployment stages. Mid-sized studios use this to balance cost efficiency with talent contract confidentiality.
- Edge Computing:Localized inference on device hardware enables offline voice synthesis for automotive and mobile applications. Latency-sensitive gaming integrations drive adoption.
Cloud-Based dominates current procurement; Edge Computing shows steepest expansion trajectory among emerging architectures.
End User:
Vertical-specific compliance requirements and content velocity demands create distinct purchasing behaviors.
- Media:News organizations and publishing houses deploy cloned voices for automated article narration and accessibility compliance. Section 508 refresh mandates in the United States accelerate procurement.
- Entertainment:Film studios and streaming platforms use synthetic voices for dubbing, ADR replacement, and deceased performer digital resurrection. Rights-holder licensing frameworks in Japan address retiring seiyuu replacement demand.
- Healthcare:Clinical documentation and patient communication tools leverage voice cloning for personalized health coaching. HIPAA compliance requirements favor on-premise deployment architectures.
- Customer Service:Contact centers integrate cloned voices into IVR systems and virtual agent interactions. Amazon's Alexa developer ecosystem anchors this vertical.
Entertainment captures the largest revenue concentration; Healthcare is expanding most quickly as regulatory clarity emerges.
Application Area:
Use-case maturity varies by technical feasibility and commercial model validation.
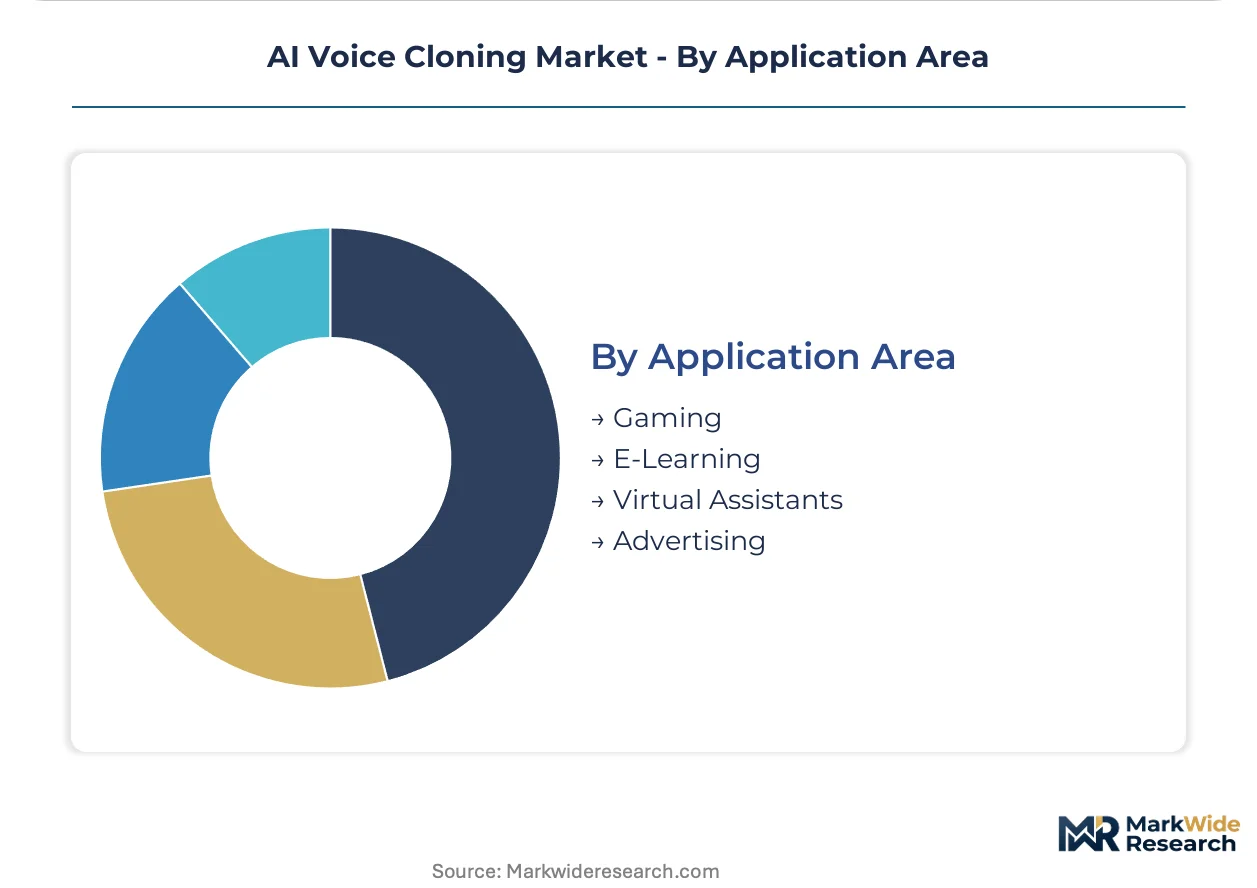
- Gaming:Dynamic dialogue generation enables branching narrative trees without voice actor re-recording. Procedural content pipelines in role-playing game development integrate synthetic voice middleware.
- E-Learning:Automated course narration reduces production costs for multilingual educational content. Corporate training departments in the United Kingdom lead adoption.
- Virtual Assistants:Conversational AI platforms embed cloned voices for brand-consistent user interactions. Smart speaker ecosystem integration drives volume.
- Advertising:Personalized audio creative generation at scale enables dynamic insertion of brand messaging. Programmatic audio platforms test synthetic voice for localized campaign variants.
E-Learning leads current deployment volumes; Gaming is climbing the fastest as real-time synthesis latency improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles entertainment studios anchor the industry's geographic concentration, with Mumbai and London forming secondary hubs where localization demand intersects with technical infrastructure deployment.
United States
Hollywood studios and streaming platforms drive demand for real-time dubbing and deceased performer digital resurrection. The Federal Trade Commission scrutinizes deceptive synthetic media disclosures under Section 5 authority, creating compliance software bundling opportunities. Los Angeles dubbing houses now deploy diffusion-based neural vocoders for same-day episodic localization.
China
Domestic streaming giants and gaming publishers consume synthetic voice capacity for multilingual content pipelines. The Cyberspace Administration imposes content review requirements on voice synthesis services, favoring domestic platform operators with established compliance layers. Beijing and Shenzhen clusters concentrate talent for low-resource language phoneme construction.
United Kingdom
Mid-sized podcast networks and corporate training departments lead procurement disintermediation, contracting directly with specialized API providers. The UK Information Commissioner's Office applies GDPR biometric data principles to voice dataset commercialization. London-based audio production houses restructure post-production floor plans around synthetic voice workstations.
India
Bollywood studios and regional streaming platforms address 22 official languages through synthetic deployment where talent pools fragment. The Telecom Regulatory Authority of India monitors cross-border data flows in voice synthesis services. Mumbai localization facilities restructure workflows around real-time pipelines rather than traditional talent contracts.
Japan
Retiring seiyuu create replacement demand that synthetic voices address through rights-holder licensing frameworks. The Ministry of Economy, Trade and Industry promotes AI adoption in content industries under digital transformation initiatives. Tokyo animation studios negotiate talent agreements that accommodate synthetic voice substitution clauses.
AI Voice Cloning Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and emotional parameter specialization. The vendor base stratifies into tensor-processing hyperscalers, granular control specialists, and conversational AI integrators. Three archetypes dominate: hyperscale cloud providers anchoring training pipelines, independent platforms offering emotional granularity, and ecosystem-integrated incumbents locking distribution channels. Competitive moves concentrate on API unbundling and modular stack assembly rather than single-vendor lock-in.
Within the hyperscale tier, Google LLC and Amazon.com, Inc. occupy positions defined by infrastructure ownership and ecosystem integration respectively. ElevenLabs exemplifies the specialist archetype through its positioning around creator-accessible emotional control parameters. Microsoft Corporation and IBM Corporation represent enterprise-facing portfolios where conversational AI and vertical solutions anchor competitive positioning. Baidu, Inc. captures domestic Chinese demand under regulatory frameworks that favor local operators.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| Amazon.com, Inc. |
| IBM Corporation |
| Descript, Inc. |
| LumenVox LLC |
| ElevenLabs |
| Nuance Communications |
| Baidu, Inc. |
| Others |
Value Network & Pricing Analysis
Diffusion-based neural vocoder deployment is collapsing training timelines from weeks to hours, simultaneously compressing per-unit synthesis costs and concentrating GPU-dependent supply chains among tensor-processing hyperscalers with secured H100 allocations.
Pricing Analysis
Input-cost pass-through from NVIDIA H100 GPU scarcity drives cloud inference pricing stratification. Three-tier pricing structure across premium, standard, and economy levels separates real-time speech-to-speech transformation from batch TTS processing. Cost compression in economy-tier TTS is intensifying because neural codec advances slash compute requirements per thousand characters. Mid-sized podcast networks exhibit highest price sensitivity; Hollywood studios negotiating deceased performer licensing show lowest.
Supply Chain Analysis
Phonetic linguist scarcity in Taiwan, South Korea, and the United States constrains low-resource language model development. GPU fabrication draws from TSMC foundries in Taiwan and Samsung facilities in South Korea, with NVIDIA packaging concentrated in Malaysia. Single-source vulnerability in advanced node semiconductor manufacturing threatens capacity expansion timelines. Distribution runs through hyperscaler cloud marketplaces and direct API contracts with specialized providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI voice cloning operates as a regulatory compounder where EU AI Act synthetic media labeling mandates create bundled compliance software demand that platforms now attach to core voice services.
For Market Incumbents: Extend emotional parameter granularity into micro-emotion rendering for non-Indo-European languages before ElevenLabs captures creator loyalty. Consolidate through backward integration into phonetic linguist training programs at Beijing and Shenzhen academic clusters. Defend against modular API unbundling by embedding provenance metadata pipelines directly into cloud training infrastructure.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in real-time speech-to-speech transformation offers white-space entry for sub-200ms latency specialists. India's 22-language dubbing localization gap presents the most penetrable geography where fragmented talent pools resist traditional contracting. Pursue direct API relationships with United Kingdom mid-sized podcast networks bypassing legacy audio software vendors.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid deployment specialists bridging cloud training with on-premise inference for healthcare HIPAA compliance. Five-to-ten-year viability hinges on biometric privacy statute navigation rather than pure technical differentiation. Monitor Illinois BIPA and Texas biometric law damage award precedents as inflection indicators for dataset commercialization risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Codec Patent Licensing | ElevenLabs and Google LLC weaponize compression IP to extract royalties from downstream API providers. |
| Phonetic Linguist Training Partnerships | Academic alliances in Mumbai and Beijing secure low-resource language coverage before talent scarcity intensifies. |
| Provenance Metadata Standardization | EU AI Act compliance bundling creates switching costs that lock streaming platforms into integrated pipelines. |
| Seiyuu Rights-Holder Licensing Frameworks | Tokyo animation studios negotiate synthetic substitution clauses addressing Japan's aging narrator workforce. |
| Edge Computing Inference Deployment | Automotive and gaming integrations demand localized processing that bypasses cloud latency constraints. |
Research Methodology
Direct dialogue with CTOs at Los Angeles dubbing houses, platform engineers at cloud API providers, regulatory affairs leads navigating EU AI Act implementation, and channel partners distributing synthetic voice middleware grounded qualitative findings. Secondary validation drew from SEC filings of hyperscaler infrastructure providers, FTC Section 5 enforcement actions, EU AI Act transparency mandate documentation, and TRAI cross-border data flow consultations. Bottom-up and top-down triangulation cross-checked segment-level demand against aggregate cloud inference consumption metrics.
Bottom-up modeling tracked deployment model, solution type, end-user vertical, and application area dimensions across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating neural codec compression timelines and regulatory compliance software bundling trajectories. Industry-specific inputs included GPU allocation queue lengths at major cloud providers and phonetic linguist graduation rates from named academic programs.
Caveats apply where Illinois BIPA damage award precedents, Taiwan semiconductor export restrictions, or transformer architecture breakthroughs could materially shift the outlook. Forecasts embed assumptions about regulatory enforcement consistency and foundry capacity expansion that may require revision. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Decision Intelligence Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
Intelligent Personal Assistant Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
AI Task Manager App Market