
 Europe Nutricosmetics Market | 2026-2036
Europe Nutricosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nutricosmetics Market Foresight
Modular sachet-and-serum bundles is realigning how consumers purchase nutricosmetics across Europe. Beiersdorf AG leverages its derma-cosmetic heritage to bridge ingestible and topical skincare. L'Oreal SA anchors its position through pharmacy-exclusive collagen protocols. BASF SE differentiates via bioactive peptide supply to third-party formulators.
Nutricosmetics encompass ingestible formulations containing vitamins, minerals, antioxidants, and bioactive peptides designed to enhance skin elasticity, hair density, and nail integrity through systemic delivery. Collagen hydrolysates with molecular weights below 10 kDa dominate functional efficacy claims in European formulations. Skin Supplement leads product type revenue pools due to established consumer familiarity with anti-aging ingestibles. Gummies within the Formulation segment represent the fastest-growing configuration as taste-masked delivery attracts younger demographics. Pharmacies retain margin concentration through pharmacist-guided recommendations despite Online Retail volume acceleration.
EFSA substantiation requirements for health claims under EU Regulation 1924/2006 constrain permissible marketing language and elevate clinical trial investment thresholds. REACH and the EU Green Deal's emerging microplastic restrictions in rinse-off products indirectly pressure sustainable packaging transitions for liquid wellness drinks. France's ANSM and Germany's BfArM maintain divergent enforcement intensities for novel food ingredient approvals, fragmenting launch timelines. Stakeholders must monitor EFSA's evolving position on collagen peptide-specific claims to preempt reformulation cycles.
Market Dynamics
The EU Green Deal's ingredient traceability mandates are forcing simultaneous reformulation and packaging overhauls across French, German, and Italian manufacturing bases. REACH compliance costs and EFSA substantiation thresholds now determine which bioactive peptides survive commercialization pipelines.
Growth Catalysts
- EFSA pathway clarity:The European Food Safety Authority's evolving guidance on collagen peptide-specific claims is reducing regulatory ambiguity for formulators investing in clinical trials.
- Pharmacy channel authority:Germany's Apotheke network leverages pharmacist trust to convert skeptical consumers into repeat buyers of derma-nutrition protocols.
- Molecular weight optimization:Hydrolysis technologies producing sub-10 kDa collagen fragments are unlocking superior bioavailability data for premium positioning.
Market Restraints
- Marine collagen supply volatility:North Atlantic fishery quotas and Baltic Sea environmental regulations constrain consistent raw material sourcing for peptide manufacturers.
- EFSA substantiation costs:The clinical investment required for Article 13 health claims under EU Regulation 1924/2006 excludes mid-tier competitors from premium positioning.
- Plant-based substitution pressure:Algae-derived alternatives and fermented amino acid complexes are capturing ethical-consumption segments in Scandinavian markets.
Strategic Opportunities
- Direct-to-consumer subscriptions:French digital-native brands are bypassing pharmacy markups through personalized sachet-and-serum bundling with AI-driven skin assessment tools.
- CSRD-aligned sustainability:The Corporate Sustainability Reporting Directive creates first-mover advantage for brands with verified supply chain transparency from marine harvest to finished good.
- Microbiome convergence:Synbiotic formulations combining collagen with targeted probiotic strains are opening dermatological indication expansion beyond aesthetic claims.
Industry Challenges
- Cross-border formulation drift:France's ANSM and Germany's BfArM maintain divergent novel food approval timelines, fragmenting pan-European launch synchronization.
- Clinical talent scarcity:The specialized expertise required for nutricosmetic-specific trial design sits concentrated within a handful of CROs in Switzerland and the Netherlands.
- Legacy packaging retooling:EU Green Deal microplastic restrictions on rinse-off products are forcing liquid wellness drink manufacturers into costly sustainable material transitions without proven shelf-life data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nutricosmetics Market |
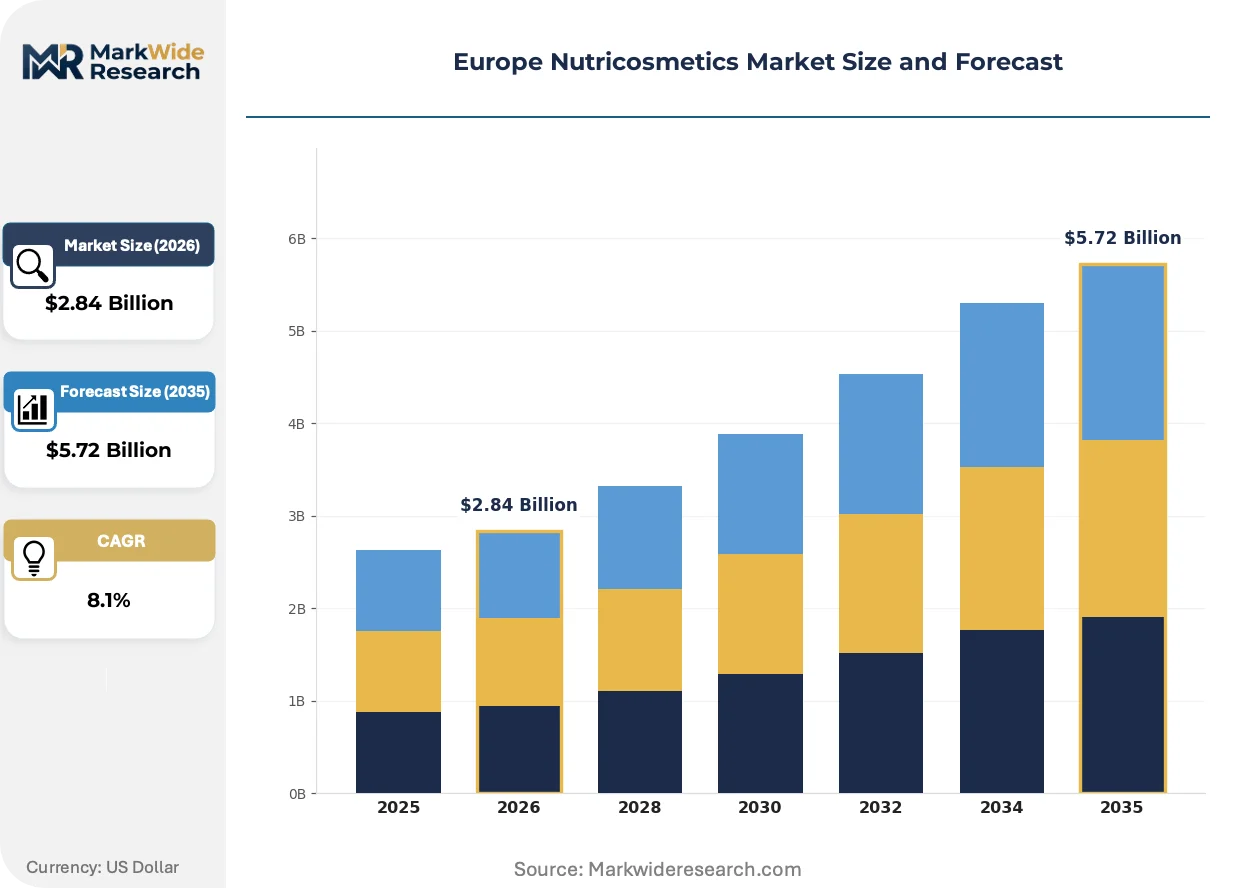
| Market Size in 2026 | $2.84 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Supplement, Hair Supplement, Nail Supplement, Wellness Drink Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies End User: Women, Men, Seniors, Athletes Formulation: Pill, Powder, Liquid, Gummies |
| Companies Covered | Beiersdorf AG, Pfizer Inc., Nestlé SA, L'Oreal SA, Lonza Group Ltd., Amway Corporation, Herbalife Nutrition Ltd, Bayer AG, BASF SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nutricosmetics Market Shifts & Advancements
Modular delivery systems and bioactive peptide engineering are compressing development cycles while expanding addressable consumer segments beyond traditional anti-aging demographics.
Artificial intelligence-driven formulation platforms are automating the optimization of collagen peptide molecular weight distributions for specific dermal penetration targets. Mid-sized manufacturers in the Netherlands and Belgium are adopting these tools to compress 18-month development timelines into 6-month cycles. The technology is automating previously manual stability-testing protocols, enabling faster response to EFSA feedback on claim substantiation packages.
REACH amendments targeting microplastic contamination in cosmetic rinse-off products are cascading into nutricosmetic liquid drink packaging requirements. The European Chemicals Agency's draft restrictions on synthetic polymer additives are forcing Italian and Spanish manufacturers toward glass and aluminum alternatives ahead of formal enforcement. Premium collagen shot producers in France are absorbing 15-20% packaging cost increases to maintain pharmacy shelf placement ahead of competitors.
Subscription-based personalization is displacing one-time pharmacy purchases among urban French consumers aged 25-35. Direct-to-consumer platforms using at-home skin hydration testing kits are converting trial users into 12-month commitments with monthly sachet-and-topical bundles. This behavioral shift concentrates most visibly in Paris and Lyon, where digital pharmacy challengers now capture 30% of new customer acquisition in the skin supplement category.
Europe Nutricosmetics Market Segmentation
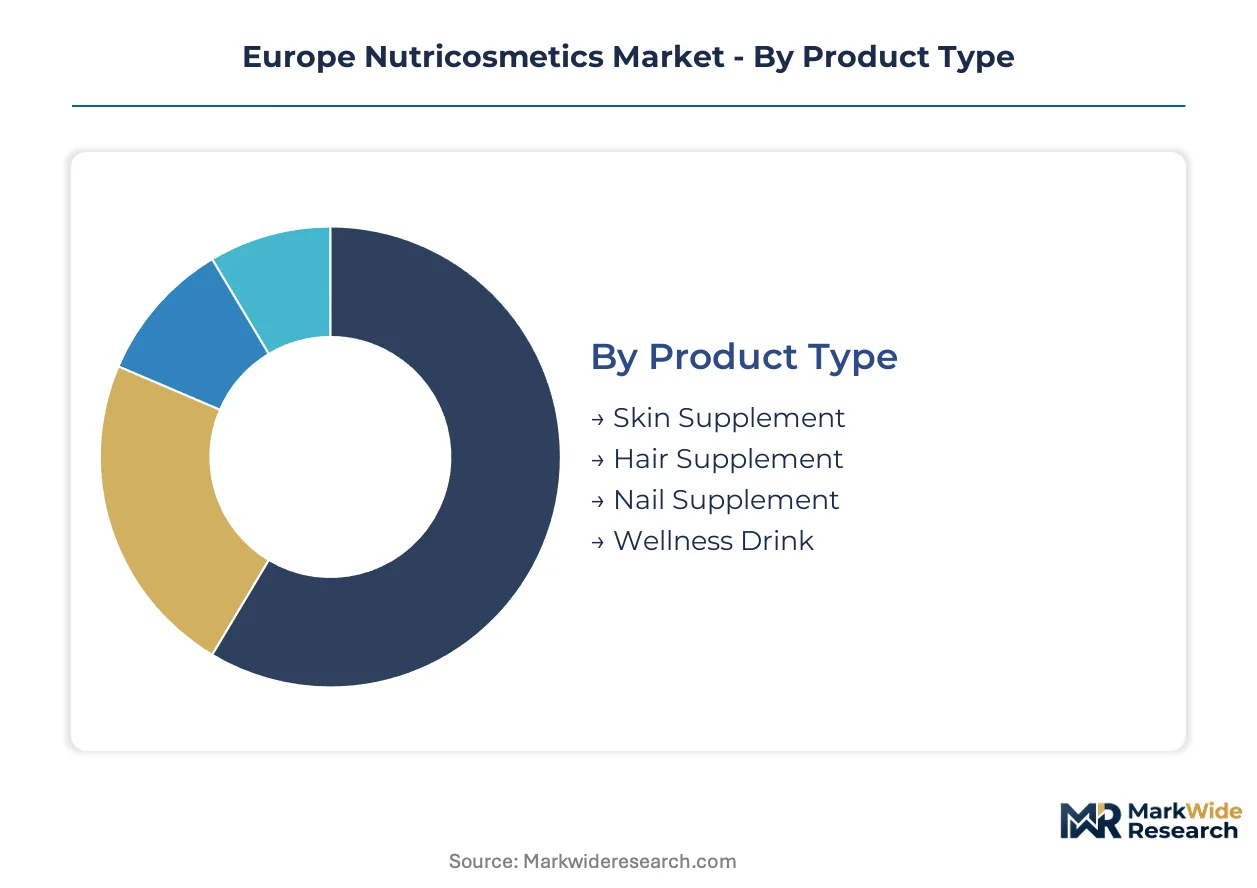
Nutricosmetics manufacturers must align production assets with distinct technical requirements across four segmentation axes. Each category imposes different regulatory burdens, shelf-life constraints, and channel economics that determine viable competitive positioning.
Product Type:
Capital deployment varies sharply across product types, with liquid formulations demanding sterile processing infrastructure while solid formats require compression and coating equipment.
- Skin Supplement:Collagen hydrolysates with sub-10 kDa molecular weights dominate formulation R&D investment. German pharmacy chains and French direct-to-consumer platforms concentrate demand for anti-aging ingestibles with EFSA-substantiated claims.
- Hair Supplement:Biotin and keratin peptide complexes require distinct stability testing protocols. Italian manufacturers lead keratin sourcing from wool processing byproducts, serving Mediterranean cosmetic brands with shorter supply chains.
- Nail Supplement:Silicon and cysteine-based formulations occupy niche positioning with lower clinical substantiation thresholds.
- Wellness Drink:Ready-to-digest liquid collagen requires aseptic filling lines and refrigerated distribution networks.
Skin Supplement absorbs the bulk of installed capacity; Wellness Drink is expanding most quickly.
Distribution Channel:
Channel selection determines margin structure and consumer education burden, with pharmacist-guided sales commanding premium pricing against self-directed online purchases.
- Pharmacies:Germany's Apotheke network leverages professional credibility to convert skeptical first-time buyers. EFSA-compliant health claims and pharmacist training investments create defensive moats against digital competitors.
- Online Retail:French subscription platforms bypass traditional markups through AI-driven skin assessment bundling. Paris and Lyon urban clusters show highest conversion rates for sachet-and-serum monthly commitments.
- Specialty Stores:Sephora and Douglas beauty retailers emphasize experiential sampling for premium collagen brands.
- Supermarkets:Mass-market gummy formats penetrate price-sensitive segments with limited clinical positioning.
Pharmacies retain the highest margin concentration; Online Retail is gaining share fastest among urban demographics.
End User:
Demographic targeting shapes formulation potency, packaging aesthetics, and marketing language compliance under EU Regulation 1924/2006.
- Women:Anti-aging collagen protocols drive the majority of segment revenue, with French and German consumers aged 35-55 showing strongest repeat purchase behavior for premium peptide products.
- Athletes:Recovery-focused amino acid blends with added electrolytes are penetrating sports nutrition crossover segments. Scandinavian markets show particular receptivity to performance-positioned nutricosmetics.
- Men:Hair density and stress-adaptogen formulations attract emerging interest with minimalist packaging preferences.
- Seniors:Joint-skin combination products with glucosamine co-formulation address mobility-aesthetic convergence needs.
Women account for dominant revenue share; Athletes demonstrate the steepest expansion trajectory as sports nutrition boundaries blur.
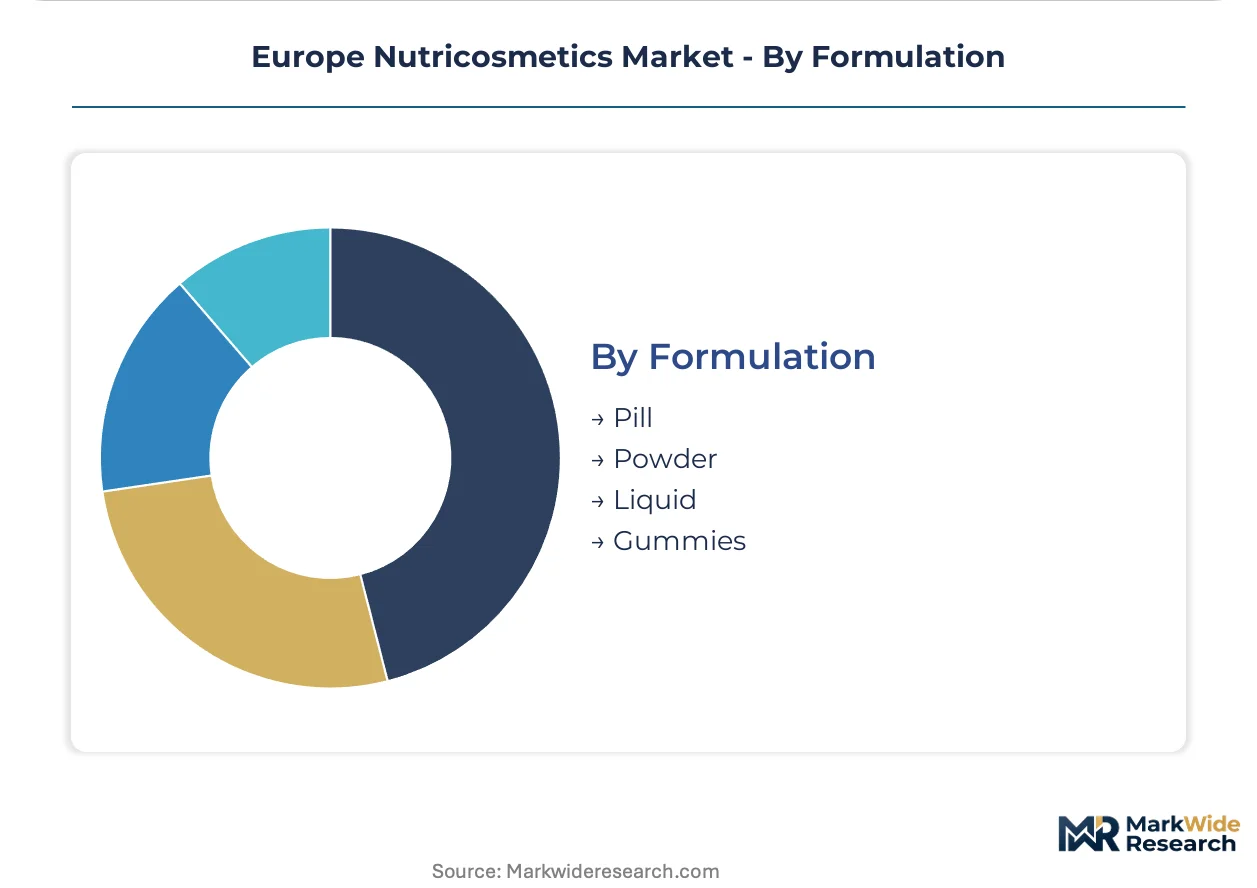
Formulation:
Delivery format selection involves trade-offs between bioavailability evidence, production complexity, and consumer compliance preferences.
- Gummies:Taste-masked delivery systems attract younger demographics with lower pill burden tolerance. Dutch and Belgian contract manufacturers have invested heavily in sugar-free pectin-base production lines.
- Pill:Tablet and capsule formats offer longest shelf stability and lowest per-unit shipping costs. German manufacturers dominate effervescent tablet production for pharmacy channels.
- Powder:Sachet formats enable flexible dosing and flavor customization for direct-to-consumer personalization platforms.
- Liquid:Shot-sized collagen drinks require cold chain infrastructure but command premium positioning in Italian and Spanish pharmacy segments.
Pill formats retain manufacturing scale advantages; Gummies are climbing the fastest as taste-driven trial conversion improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Parc d'Activités de Sophia Antipolis clusters AI-driven nutricosmetic startups alongside established derma-cosmetic R&D centers, concentrating venture funding and formulation talent within a single tax-advantaged zone.
Germany
Germany's Apotheke network converts skeptical first-time buyers through pharmacist-guided collagen consultations. BfArM maintains stringent novel food approval timelines that fragment pan-European launch synchronization. The Rhine-Ruhr metropolitan region hosts BASF SE's bioactive peptide supply operations serving third-party formulators across Western Europe.
France
French direct-to-consumer platforms bypass pharmacy markups through AI-driven skin assessment bundling. ANSM enforces divergent enforcement intensities for novel food ingredient approvals compared to German counterparts. Paris and Lyon urban clusters capture 30% of new customer acquisition in the skin supplement category through digital-native subscription services.
Italy
Italian manufacturers lead keratin sourcing from wool processing byproducts for Mediterranean cosmetic brands. REACH amendments targeting microplastic contamination cascade into liquid drink packaging requirements ahead of formal enforcement. The Lombardy region concentrates aseptic filling infrastructure for premium collagen shot production serving pharmacy segments.
Netherlands
Dutch contract manufacturers invested heavily in sugar-free pectin-base production lines for gummy format expansion. EFSA substantiation requirements under EU Regulation 1924/2006 constrain permissible marketing language for Amsterdam-based digital brands. The Randstad corridor clusters mid-sized manufacturers adopting AI-driven formulation platforms to compress development timelines.
Spain
Spanish manufacturers absorb 15-20% packaging cost increases to maintain pharmacy shelf placement ahead of competitors. The EU Green Deal's emerging microplastic restrictions pressure sustainable material transitions for liquid wellness drinks without proven shelf-life data. Catalonia hosts reformulation facilities adapting to stricter ingredient traceability mandates.
Europe Nutricosmetics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's nutricosmetics value chain. The market structures around three tiers: multinational consumer goods conglomerates with cross-category R&D budgets, mid-sized derma-cosmetic houses with pharmacy channel relationships, and agile direct-to-consumer startups leveraging digital acquisition. Strategic moves concentrate on M&A for peptide technology access and backward integration into marine collagen sourcing.
Within the conglomerate tier, Nestlé SA and L'Oreal SA occupy positions spanning ingestible and topical beauty protocols. BASF SE anchors the bioactive ingredient supply layer, serving third-party formulators with peptide engineering capabilities. Beiersdorf AG exemplifies the derma-cosmetic specialist archetype, bridging pharmacy authority with nutricosmetic innovation.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Pfizer Inc. |
| Nestlé SA |
| L'Oreal SA |
| Lonza Group Ltd. |
| Amway Corporation |
| Herbalife Nutrition Ltd |
| Bayer AG |
| BASF SE |
| Others |
Supply & Pricing Matrix
Captive marine collagen sourcing from North Atlantic fisheries anchors both supply security and premium pricing power for European peptide manufacturers navigating EFSA substantiation costs and Baltic Sea environmental quotas.
Pricing Analysis
Short-lead-time premiums dominate collagen peptide procurement, with German pharmacy networks paying elevated rates for verified sub-10 kDa molecular weight batches against spot-market alternatives from unvalidated hydrolysis operations. Three-tier pricing structure across EFSA-substantiated premium, pharmacy-standard, and mass-market economy levels separates pharmacist-guided protocols from direct-to-consumer bundles and supermarket gummy formats. Cost compression in the economy tier is intensifying because Dutch and Belgian contract manufacturers have scaled sugar-free pectin production lines. Athletes and sports nutrition crossovers show least price sensitivity due to performance-linked efficacy claims, while supermarket gummy purchasers exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with North Atlantic marine collagen harvesters facing quota restrictions from Norwegian and Icelandic fishery regulators. Raw material dependencies center on fish skin and scale byproducts, wool-derived keratin from Italian processors, and fermentation-grade amino acid precursors. Tariff exposure runs through post-Brexit UK-EU ingredient transit routes and emerging microplastic packaging restrictions under REACH amendments. Distribution runs through Germany's Apotheke network for premium positioning, French direct-to-consumer platforms for subscription bundling, and Sephora-Douglas specialty retail for experiential trial conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over marine collagen harvesting determines both cost position and EFSA claim substantiation credibility against plant-based substitutes.
For Market Incumbents: Extend pharmacist consultation protocols into AI-driven skin assessment tools to defend against French digital-native subscription challengers eroding pharmacy channel authority. Deepen captive sourcing from MSC-certified North Atlantic fisheries before Baltic Sea environmental regulations tighten further. Lock in exclusive peptide engineering partnerships with Dutch AI-formulation platforms to compress development timelines.
For New Entrants and Emerging Players: Enter via Scandinavian sports nutrition crossover segments where performance-positioned amino acid blends face minimal incumbent saturation and ethical-consumption premiums support pricing. Target male hair density formulations with minimalist packaging aesthetics as the most penetrable white-space demographic. Launch through at-home skin hydration testing kits bundled with personalized sachet subscriptions to bypass pharmacy markup structures.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by derma-cosmetic conglomerates seeking ingestible-topical protocol integration. Long-term viability hinges on CSRD-aligned supply chain transparency investments that create defensive moats under EU Green Deal enforcement. Watch EFSA's evolving position on collagen peptide-specific claims as the inflection signal determining which substantiation investments retain competitive value.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marine Collagen Sourcing | Captive supply from Norwegian fisheries insulates against quota volatility and EFSA traceability mandates. |
| AI-Driven Formulation Platform Adoption | Dutch manufacturers compress 18-month development cycles into 6-month timelines using automated peptide optimization. |
| Direct-to-Consumer Subscription Launch | French digital-native brands capture 30% of Paris-Lyon customer acquisition through sachet-and-serum bundling. |
| CSRD-Aligned Sustainability Certification | Verified supply chain transparency creates first-mover advantage under EU Green Deal enforcement. |
| Synbiotic Dermatological Formulation Expansion | Collagen-probiotic combinations open indication expansion beyond aesthetic claims into medical positioning. |
Research Methodology
Multi-period observation of EFSA claim approval timelines, pharmacy channel inventory turns, and direct-to-consumer subscription conversion rates anchored the trend analysis, supplemented by interviews with peptide R&D directors, regulatory affairs leads at French and German nutricosmetic firms, pharmacy category managers, and marine collagen procurement specialists. Secondary validation drew from EFSA health claim registers, ANSM and BfArM novel food approval databases, EU customs trade data for collagen peptide imports, and CSRD sustainability disclosure filings. Bottom-up manufacturer capacity assessments and top-down channel spending estimates were triangulated against consumption pattern surveys.
Segment-weighting across product type, distribution channel, end user demographic, and formulation format drove the analytical framework across the projection horizon. Skin supplement, hair supplement, nail supplement, and wellness drink categories were modeled separately with distinct margin and growth assumptions. Pharmacy, online retail, specialty store, and supermarket channels received differential weightings based on pharmacist authority erosion rates and AI-personalization adoption curves. CAGRs were derived from elasticity-adjusted price-volume trajectories incorporating EFSA substantiation cost pass-through and marine collagen supply volatility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA claim rejection scenarios, Baltic Sea fishery closure events, or accelerated plant-based substitution in Scandinavian markets. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Ayurvedic Products Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
Chondroitin Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
US Collagen Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
North America Nutraceuticals Market