
 Pycnogenol Market | 2026-2036
Pycnogenol Market Size, Share, and Industry Trends Forecast 2026-2036
Pycnogenol Market Analysis
French maritime pine bark harvest is rebalancing after climate-stressed growing seasons in the Landes forest. Horphag Research leverages its proprietary extraction patents to sustain supply continuity for pharmaceutical-grade material. NOW Foods anchors North American retail distribution through mass-market capsule formulations. Nourish Pharmaceutical Pvt. Ltd. competes on cost-optimized tablet production for Asian contract brands.
Pycnogenol denotes a standardized extract from Pinus pinaster bark containing 70±5% procyanidins, 15±5% phenolic acids, and 4±2% taxifolin, manufactured via water-ethanol extraction followed by spray-drying to preserve oligomeric proanthocyanidin bioactivity for vascular function and oxidative stress modulation. Capsule formats dominate volume as consumers prioritize precise dosing convenience, while skincare applications represent the fastest-expanding margin pool where topical delivery systems command formulation premiums. The dietary supplements segment occupies mature growth trajectories in Western Europe, whereas functional foods navigate stricter novel food classification pathways.
EMA guidelines on botanical drug substance quality and EFSA health claim authorization procedures govern European market access, with REACH compliance required for extraction solvent residues. The US FDA Dietary Supplement Health and Education Act creates a distinct regulatory bifurcation between supplement and drug positioning that shapes US label architecture. India's FSSAI and CDSCO maintain parallel oversight for nutraceutical versus pharmaceutical classifications, complicating cross-border formulation strategies. Stakeholders must monitor evolving pharmacovigilance reporting obligations for polyphenol extracts as regulators scrutinize botanical-drug interaction databases.
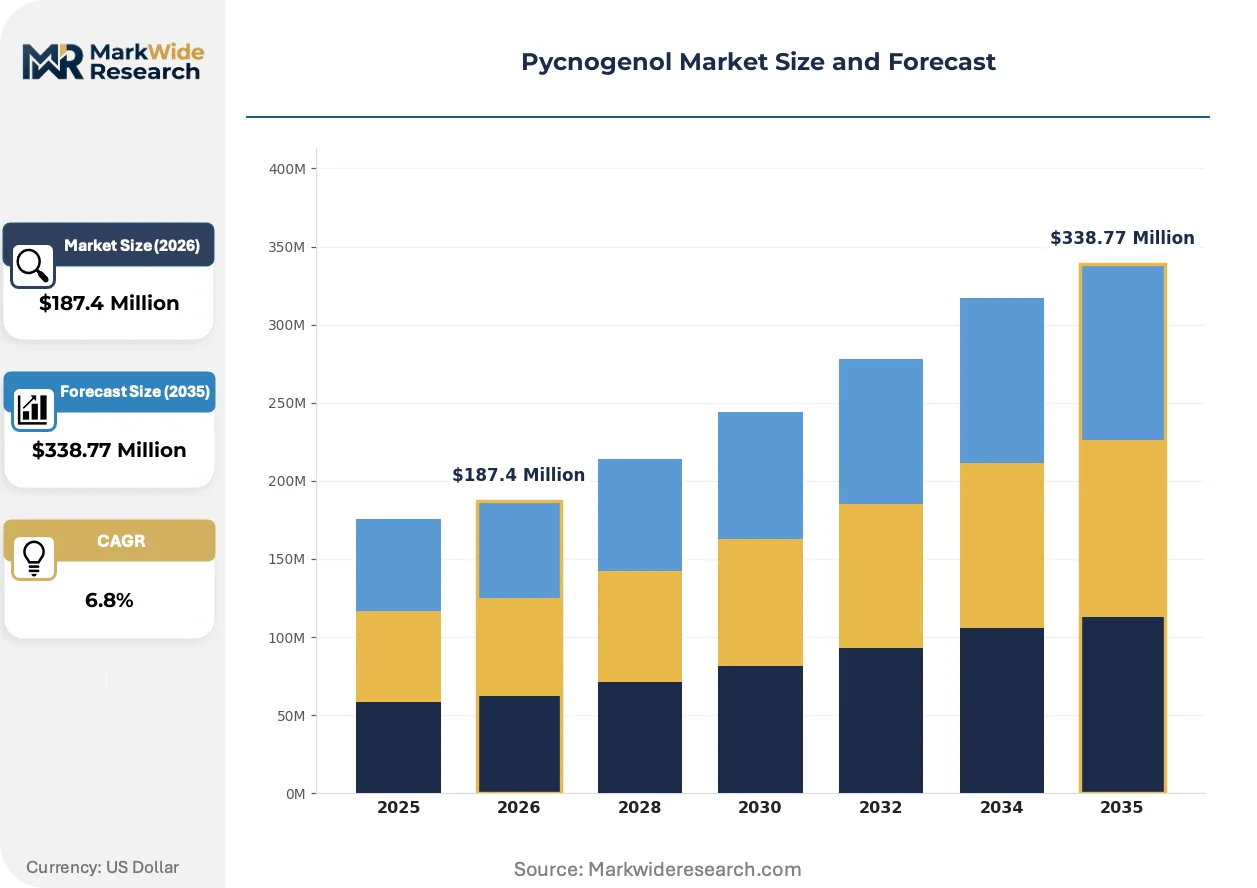
Market Dynamics
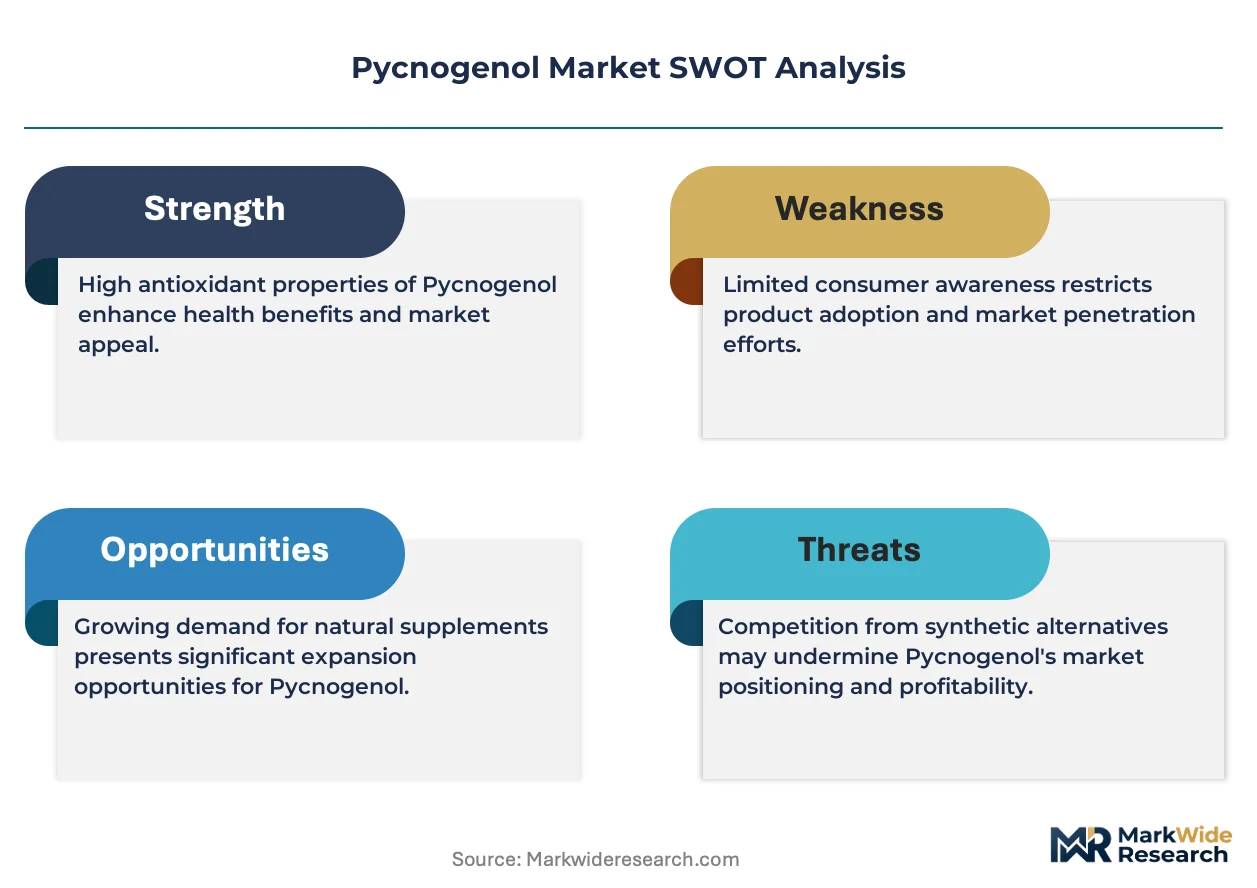
French maritime pine bark supply concentration in the Landes forest creates procurement bottlenecks as climate variability compresses harvest windows. Horphag Research's patent-controlled extraction infrastructure limits viable alternative sourcing for pharmaceutical-grade material.
Growth Catalysts
- EFSA health claim authorization:Article 13.1 generic claims for vascular function enable label differentiation in EU pharmacy channels. German pharmacist recommendation protocols amplify this regulatory tailwind.
- Topical delivery system innovation:Liposomal encapsulation technology expands dermal bioavailability for cosmetic applications. Skincare formulators in South Korea integrate these systems into premium anti-aging lines.
- India:FSSAI nutraceutical classification clarity reduces import friction for contract manufacturers. Nourish Pharmaceutical scales tablet production for Asian private-label brands.
Market Restraints
- Raw material geographic concentration:Landes forest monoculture exposes supply to drought-induced yield volatility. No alternative Pinus pinaster sourcing meets identical procyanidin standardization.
- REACH solvent residue compliance:ECHA monitoring of water-ethanol extraction byproducts adds analytical cost burdens. Small-scale extractors lack in-house testing infrastructure.
- Green tea extract substitution:EGCG-rich alternatives compete on cost in mass-market antioxidant positioning. Price-sensitive buyers in Asian contract manufacturing switch inputs.
Strategic Opportunities
- Functional food integration:EFSA novel food pathway for bark-derived polyphenols remains underutilized. Beverage brands in Spain explore fortified juice applications.
- Pharmacist-digital hybrid channels:Telehealth platforms in Germany integrate botanical recommendation algorithms. This bypasses traditional wholesale markups.
- CDSCO pharmaceutical classification:India's dual-track regulatory system permits prescription positioning for vascular indications. Domestic firms file drug master files for hospital procurement.
Industry Challenges
- Oligomeric proanthocyanidin analytical expertise:Quantification of procyanidin chain length distribution requires specialized HPLC-MS capability. Contract labs face 6-month qualification backlogs.
- Pharmacovigilance database integration:EMA botanical-drug interaction reporting obligations demand adverse event infrastructure. Mid-size supplement brands lack dedicated safety surveillance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pycnogenol Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powders, Liquids Application: Dietary Supplements, Skincare, Functional Foods, Pharmaceuticals Distribution Channel: Online, Pharmacies, Health Stores, Supermarkets End User: Health-conscious Individuals, Athletes, Seniors, Patients |
| Companies Covered | Nourish Pharmaceutical Pvt. Ltd., Amlin Health LLC, Horphag Research, SceletiumZA, Ochoa Laboratories Pvt. Ltd., Sun Pharmaceutical Industries Ltd., Superior Supplement Manufacturing, NOW Foods, Alkem Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pycnogenol Market Emerging Trajectories
Formulation science is compressing the boundary between oral and topical delivery systems. Patent-protected extraction methods now compete with delivery-technology differentiation for margin capture.
Liposomal encapsulation technology is integrating into cosmetic-grade Pycnogenol production. Premium skincare brands in South Korea and France adopt these systems to enhance dermal penetration of procyanidins. This convergence is integrating pharmaceutical delivery expertise into traditional botanical supply chains, compressing development timelines for functional topical products.
REACH Annex XVII restrictions on residual solvent thresholds tighten quality verification protocols. ECHA enforcement actions against non-compliant extractors accelerate lab consolidation. Pharmaceutical-grade material suppliers invest in in-house GC-MS testing to preempt regulatory detention at EU borders.
Pharmacist recommendation algorithms reshape German and Austrian purchasing patterns. Pharmacy chains deploy tablet-based consultation tools that rank botanicals by clinical evidence grade. This digital intermediation displaces traditional brand marketing in the highest-margin European channel.
Pycnogenol Market Segmentation
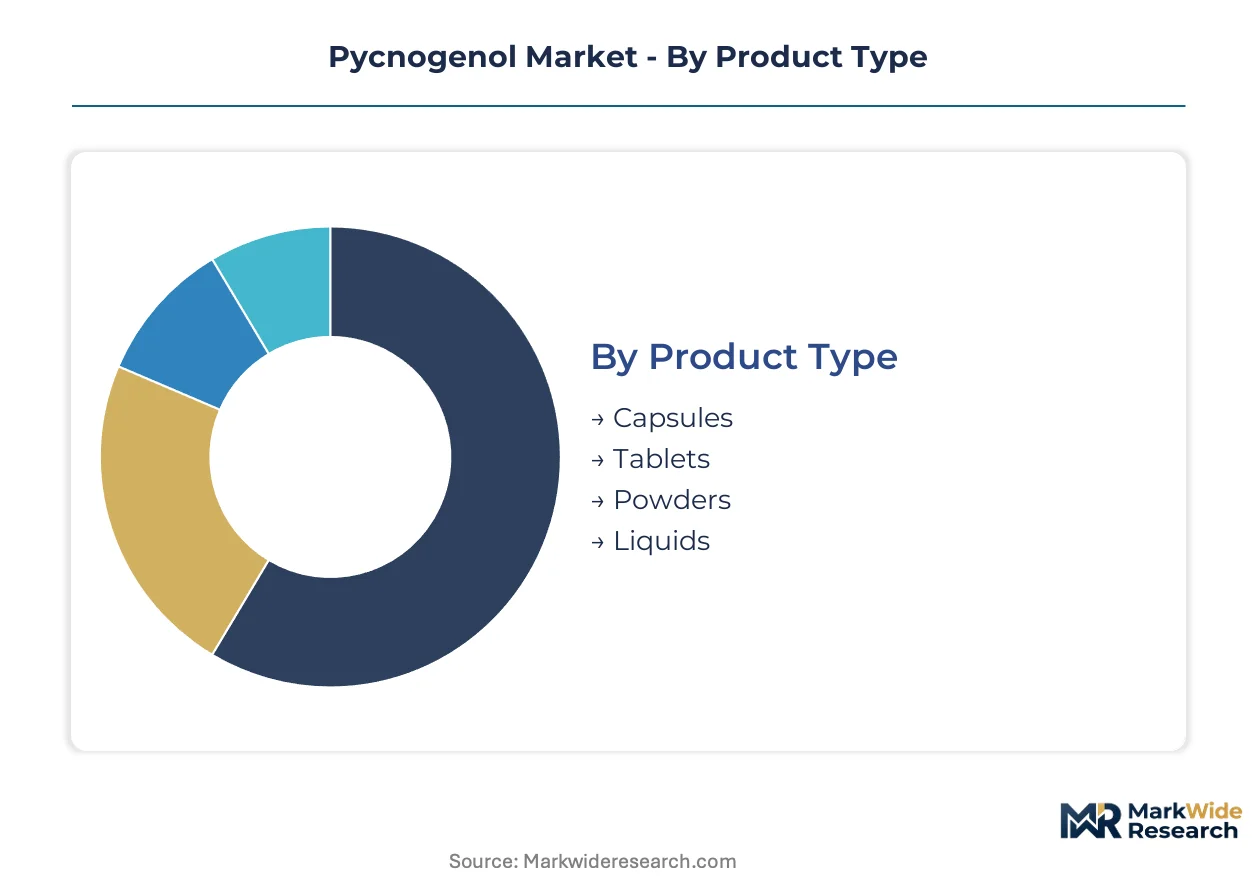
Pycnogenol's standardized procyanidin profile creates distinct formulation requirements across delivery formats. Supply chain configuration for pharmaceutical-grade material shapes competitive positioning within each segment category.
Product Type:
French maritime pine bark extraction capacity concentrates in Horphag Research's patented infrastructure, forcing format decisions around available standardization grades.
- Capsules:Gelatin and vegetable cellulose shells encapsulate standardized extract at 50-100mg doses for precise procyanidin delivery. German pharmacy chains prioritize capsule formats for their shelf stability and consumer familiarity with unit dosing.
- Tablets:Compressed formulations with excipient matrices enable cost-efficient mass production. Nourish Pharmaceutical scales tablet output for Asian contract manufacturers seeking economy positioning in private-label channels.
- Powders:Bulk extract enables beverage fortification and custom compounding applications.
- Liquids:Glycerin-based suspensions serve pediatric and geriatric populations with swallowing difficulties.
Capsules absorb the bulk of installed capacity; skincare-grade powders are expanding most quickly.
Application:
Margin structures diverge sharply between mature supplement channels and emerging therapeutic positioning.
- Dietary Supplements:Mature Western European markets navigate EFSA Article 13.1 health claim authorization for vascular function positioning. NOW Foods anchors North American retail distribution through mass-market capsule formulations with standardized 70% procyanidin content.
- Skincare:Liposomal encapsulation technology commands formulation premiums for dermal bioavailability. South Korean cosmetic manufacturers integrate these delivery systems into premium anti-aging lines targeting procyanidin antioxidant activity.
- Functional Foods:EFSA novel food classification pathways remain underutilized for bark-derived polyphenol fortification.
- Pharmaceuticals:CDSCO drug master file pathways in India enable prescription positioning for vascular indications requiring clinical-grade documentation.
Dietary supplements command current revenue concentration; skincare applications are climbing the fastest.
Distribution Channel:
Channel economics reflect regulatory compliance burdens and pharmacist intermediation power.
- Pharmacies:German and Austrian pharmacy chains deploy digital consultation tools ranking botanicals by evidence grade. Pharmacist recommendation protocols displace traditional brand marketing in these highest-margin European channels.
- Online:Direct-to-consumer platforms bypass wholesale markups but face REACH documentation requirements for cross-border EU sales.
- Health Stores:Specialized retailers cater to educated consumers seeking practitioner-grade formulations.
- Supermarkets:Mass-market placement demands price-competitive positioning against green tea extract substitutes.
Pharmacies retain premium positioning; online channels are gaining share fastest.
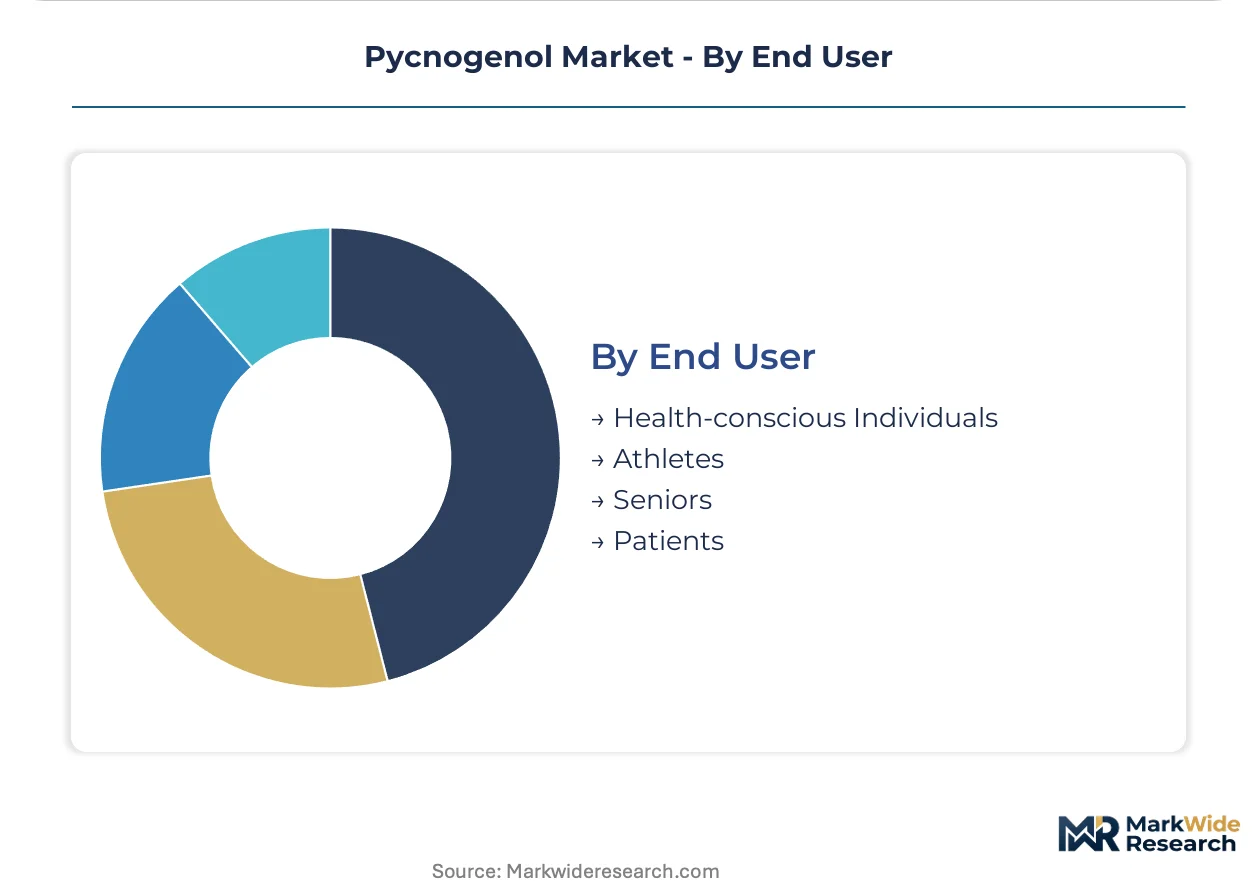
End User:
User segmentation aligns procyanidin dosing protocols with physiological targeting and compliance preferences.
- Health-conscious Individuals:Preventive consumption patterns favor convenient capsule formats with EFSA-authorized vascular claims. German consumers demonstrate highest willingness-to-pay for pharmacist-validated botanical sourcing.
- Seniors:Polypharmacy contexts drive demand for documented drug-interaction profiles. EMA pharmacovigilance reporting obligations for polyphenol extracts particularly affect this cohort's safety surveillance requirements.
- Athletes:Performance positioning emphasizes oxidative stress modulation for recovery applications.
- Patients:Clinical supervision enables higher-dose therapeutic protocols under pharmaceutical classification.
Health-conscious individuals represent the largest addressable base; senior-targeted formulations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Landes forest in southwestern France anchors Pycnogenol production geography, with Horphag Research's extraction infrastructure concentrated in this single maritime pine bark source zone. This supply localization shapes procurement patterns and regulatory compliance costs across consuming markets.
Germany
Pharmacist recommendation protocols drive premium positioning for vascular health botanicals in pharmacy chains. EFSA Article 13.1 health claim authorization enables label differentiation for procyanidin-standardized extracts. The Bavaria-based pharmaceutical distribution cluster processes specialized documentation for cross-border EU shipments.
United States
Mass-market capsule demand concentrates through health food retail and direct-to-consumer platforms. FDA Dietary Supplement Health and Education Act creates distinct regulatory bifurcation from pharmaceutical positioning. NOW Foods anchors distribution from its Illinois operations, serving pharmacy-adjacent supplement channels nationwide.
India
Contract manufacturing scale for tablet formulations attracts Asian private-label brands seeking cost-optimized production. FSSAI nutraceutical classification and CDSCO pharmaceutical pathways operate in parallel, complicating cross-border formulation strategies. Maharashtra-based production facilities file drug master files for hospital procurement channels.
South Korea
Premium skincare integration of liposomal encapsulation technology commands formulation premiums for dermal procyanidin delivery. MFDS cosmetic regulation shapes import documentation for botanical active ingredients. Seoul-based cosmetic manufacturers lead adoption of pharmaceutical-grade delivery systems in anti-aging product lines.
Spain
Functional food exploration for bark-derived polyphenol fortification navigates EFSA novel food classification pathways. Beverage brands in Catalonia pilot fortified juice applications pending regulatory authorization. Barcelona-area food technology clusters develop extraction protocols compatible with heat-stable liquid matrices.
Pycnogenol Market Vendor Landscape
Global majors compete with regional champions across extraction-grade standardization and distribution channel access. Market structure concentrates around patent-controlled raw material supply and pharmaceutical-grade certification tiers. Three archetypes dominate: proprietary extractors controlling bark sourcing, contract manufacturers scaling tablet and capsule output, and retail-brand distributors anchoring consumer-facing channels. Capacity expansion and delivery-system technology licensing represent the dominant competitive moves.
Within the proprietary extraction tier, Horphag Research exemplifies patent-controlled supply continuity for pharmaceutical-grade material. Among contract manufacturers, Nourish Pharmaceutical Pvt. Ltd. and Ochoa Laboratories Pvt. Ltd. occupy positions scaling cost-optimized production for Asian private-label brands. NOW Foods anchors North American retail distribution through mass-market capsule formulations.
| Leading Market Players |
|---|
| Nourish Pharmaceutical Pvt. Ltd. |
| Amlin Health LLC |
| Horphag Research |
| SceletiumZA |
| Ochoa Laboratories Pvt. Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Superior Supplement Manufacturing |
| NOW Foods |
| Alkem Labs |
| Others |
Supply Flow & Price Mechanics
Procyanidin-standardized extract from Landes forest bark moves through pharmaceutical-grade certification tiers before reaching pharmacy shelves in Germany or contract manufacturers in India. Water-ethanol extraction solvent costs cascade into REACH compliance testing fees, with Horphag Research's patent-controlled infrastructure capturing margin at each quality verification stage.
Pricing Analysis
Certificate of analysis bundling separates pharmaceutical-grade material from cosmetic and dietary supplement tiers, with EMA-compliant documentation commanding substantial premiums over mass-market capsule formulations. Price differentiation rests on procyanidin chain-length verification via HPLC-MS and EFSA Article 13.1 health claim authorization status. Cost compression in Asian contract manufacturing intensifies as green tea extract substitutes capture price-sensitive tablet buyers. German pharmacy channel consumers demonstrate lowest price sensitivity, prioritizing pharmacist-validated sourcing over economy positioning.
Supply Chain Analysis
Quality downgrade and reclassification flows from pharmaceutical to cosmetic grade occur when procyanidin standardization misses specification thresholds. Geographic supply concentration centers on France's Landes forest for raw bark, with extraction capacity in Switzerland and secondary processing in India and South Korea. Raw material dependencies include maritime pine bark monoculture, water-ethanol solvents, and spray-drying energy inputs. Single-source vulnerability from Horphag Research's patent-controlled infrastructure exposes buyers to allocation risk during climate-stressed harvests. Distribution runs through German pharmacy wholesale networks, direct-to-consumer platforms, and Asian contract manufacturing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into extraction infrastructure and captive bark sourcing defines competitive positioning in this market, with players racing to secure pharmaceutical-grade certification tiers that lock in pharmacy channel access.
For Market Incumbents: Acquire in-house HPLC-MS analytical capability to bypass six-month contract lab qualification backlogs threatening supply continuity. Secure long-term bark supply agreements with Landes forest cooperatives before climate variability compresses harvest windows further. Green tea extract substitution in Asian price-sensitive segments demands defensive EFSA health claim investment to maintain label differentiation. For New Entrants and Emerging Players: CDSCO pharmaceutical classification in India opens a window for prescription-positioned vascular indications requiring clinical-grade documentation. Target underpenetrated functional food applications in Spain navigating EFSA novel food pathways. Deploy liposomal encapsulation technology licensing to bypass Horphag Research's extraction patent barriers through delivery-system differentiation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale contract manufacturers with FSSAI nutraceutical clearance and idle tablet press capacity in Maharashtra. Long-term viability hinges on dual-track regulatory positioning spanning supplement and pharmaceutical classifications. Monitor EMA pharmacovigilance database expansion for botanical-drug interaction reporting obligations as the inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Patent Licensing for Extraction Technology | Horphag Research's proprietary methods enable pharmaceutical-grade supply continuity for EU pharmacy channels. |
| Liposomal Encapsulation Partnership | South Korean cosmetic manufacturers integrate dermal delivery systems for premium anti-aging line positioning. |
| CDSCO Drug Master File Submission | Indian domestic firms unlock hospital procurement pathways for prescription vascular indications. |
| REACH Compliance Infrastructure Investment | In-house GC-MS testing preempts ECHA enforcement actions at EU border checkpoints. |
| Telehealth Platform Integration | German pharmacy chains deploy digital consultation tools displacing traditional brand marketing intermediation. |
Methodological Framework
Multi-period observation of EFSA health claim authorization timelines, REACH enforcement actions, and CDSCO filing volumes anchored the trend analysis, supplemented by interviews with extraction facility managers, pharmacy chain procurement directors, FSSAI regulatory consultants, and cosmetic formulators at South Korean manufacturers. Secondary validation drew from EMA botanical drug substance guidelines, ECHA Annex XVII restriction updates, FSSAI nutraceutical classification circulars, and customs trade data for maritime pine bark extract shipments. Bottom-up segment sizing triangulated against top-down market aggregation across product type, application, and distribution channel dimensions.
Segment-weighting approaches applied differential growth assumptions to dietary supplement, skincare, functional food, and pharmaceutical application categories, with procurement channel splits between pharmacy, online, health store, and supermarket vectors. CAGRs derived from volume trajectory modeling across the projection horizon, incorporating EFSA authorization probability weightings and climate-adjusted bark yield scenarios. Forecast inputs included liposomal encapsulation adoption curves in cosmetic applications and telehealth platform penetration rates in German pharmacy channels.
The model assumes a particular technology adoption path for dermal delivery systems; alternative pathways for nano-encapsulation or transdermal patches would alter the outlook for skincare margin expansion. Forecasts reflect documented assumptions regarding EFSA novel food pathway timelines and CDSCO pharmaceutical classification clarity. Practitioners should monitor EMA pharmacovigilance database integration requirements and Landes forest drought severity indices for early signals of supply disruption or compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Piracetam Market
Nutraceuticals
Micro-Ecological Regulators Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Asia-Pacific Pet Nutraceuticals Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Chondroitin Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Hair Growth Supplement and Treatment Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Nattokinase Market
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market
Nutraceuticals
Fish-Oil Based Drugs Market