
 Chile E-Commerce Market | 2026-2036
Chile E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Chile E-Commerce Market Analysis
The gap between premium curated experiences and commodity price-driven transactions is broadening across Chile's online retail landscape. Falabella sustains its department-store heritage through integrated omnichannel fulfillment, while MercadoLibre dominates the marketplace infrastructure with logistics networks spanning the country's length. Walmart Chile competes on grocery frequency and last-mile density in urban centers.
E-commerce in Chile encompasses digitally mediated transactions for physical goods, facilitated by web platforms and mobile applications with real-time inventory synchronization, encrypted payment gateways, and algorithmic recommendation engines. Its commercial purpose centers on reducing friction between product discovery and doorstep fulfillment for consumers across diverse geographies. Electronics and home goods command the largest transaction volumes, while digital wallets and subscription services represent the fastest-expanding payment and sales channel segments respectively. Clothing retains mature profitability through return-rate management, and beauty products attract emerging direct-to-consumer entrants.
Chile's central bank regulates payment system stability, while the country's consumer protection agency oversees digital transaction transparency and refund obligations. Tax authority digitization of electronic invoicing tightens compliance requirements for cross-border sellers operating through marketplace platforms. Stakeholders must monitor regulatory evolution around data localization mandates and import duty structures affecting marketplace participants.
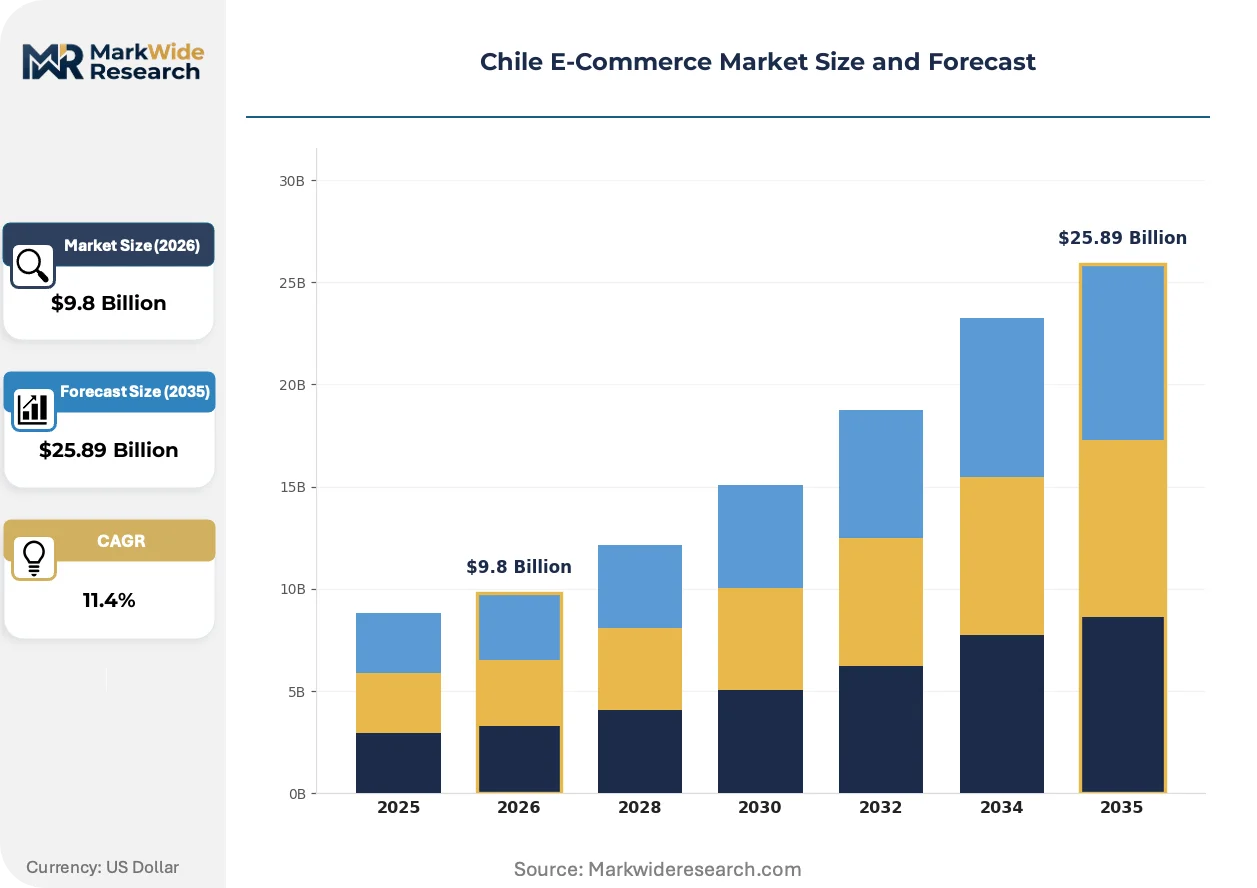
Market Dynamics
Chile's central bank digital payment infrastructure is compressing settlement friction for online merchants, while Santiago's metropolitan retail corridor concentrates fulfillment investment and shapes national logistics networks.
Growth Catalysts
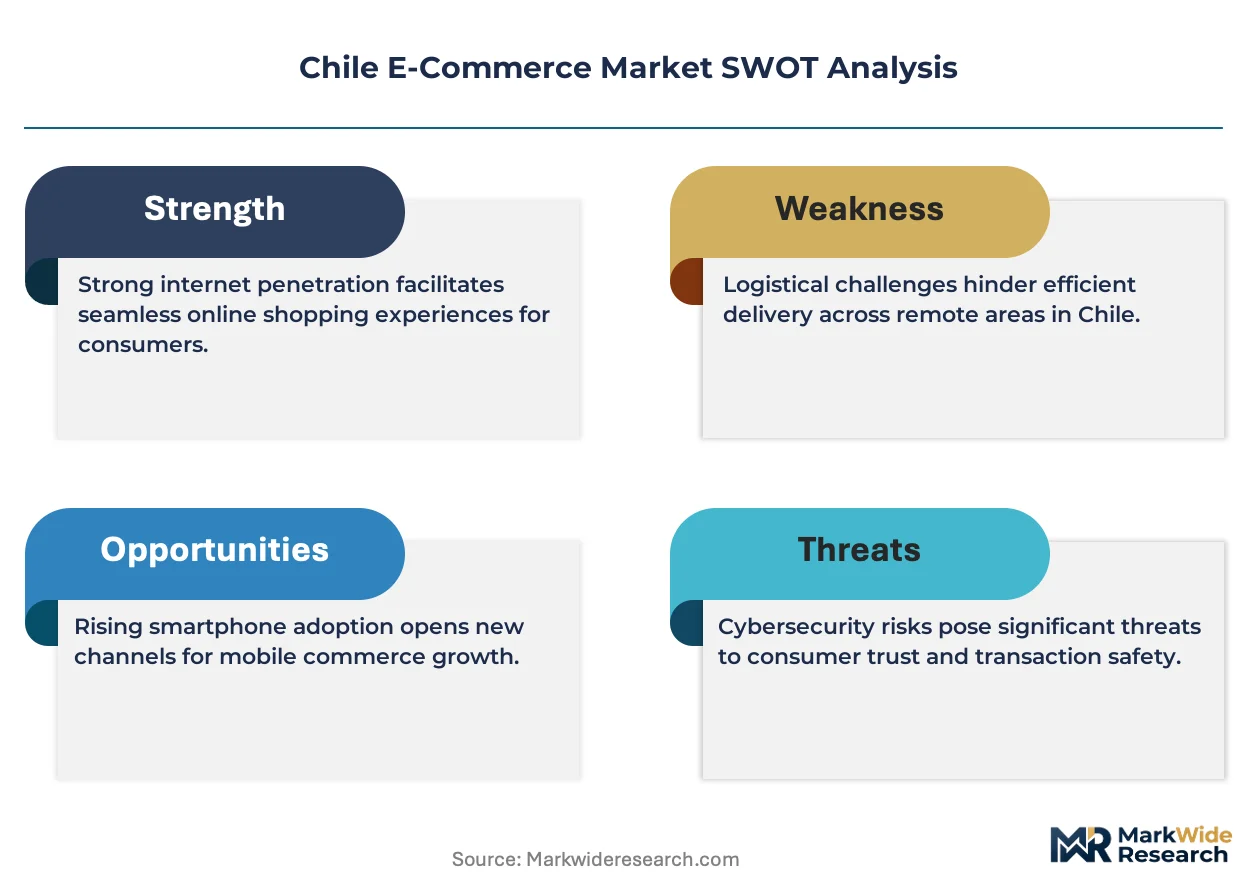
- Digital Wallet Penetration:Chile's central bank modernizes real-time settlement rails, enabling instant peer-to-peer transfers and merchant payments that reduce cart abandonment rates.
- Millennial and Gen Z Electronics Demand:Younger demographics drive transaction volume in smartphones, laptops, and smart home devices through mobile-first purchasing behaviors.
- Secondary City Logistics Expansion:Valparaíso and Concepción receive dedicated fulfillment centers that compress delivery windows for consumers outside Santiago's immediate radius.
Market Restraints
- Cross-Border Import Duty Complexity:Chile's tax authority digitization of electronic invoicing tightens compliance requirements for marketplace sellers sourcing inventory from overseas suppliers.
- Last-Mile Geography Constraints:The country's elongated territory and mountain barriers inflate fulfillment costs for deliveries to remote Patagonian and northern desert regions.
- Payment Infrastructure Fragmentation:Legacy banking systems in smaller municipalities create settlement delays that disadvantage regional merchants against Santiago-based competitors.
Strategic Opportunities
- Subscription Commerce Models:Beauty and personal care categories attract direct-to-consumer entrants deploying recurring revenue frameworks that improve customer lifetime value metrics.
- Data Localization Compliance Services:Evolving regulatory mandates around consumer data storage create advisory and infrastructure revenue streams for domestic technology providers.
- Omnichannel Return Integration:Department store heritage networks enable buy-online-return-in-store capabilities that reduce reverse logistics costs and drive foot traffic.
Industry Challenges
- Warehouse Automation Talent Scarcity:Robotics integration for Santiago fulfillment centers outpaces local supply of mechatronics technicians and systems integration specialists.
- Inventory Synchronization Complexity:Real-time stock visibility across physical stores, dark stores, and third-party marketplace listings demands middleware investments many mid-market merchants lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile E-Commerce Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Clothing, Home Goods, Beauty Products Customer Type: Millennials, Gen Z, Families, Senior Citizens Sales Channel: Direct-to-Consumer, Marketplaces, Social Media, Subscription Services Payment Method: Credit Cards, Cash on Delivery, Digital Wallets, Bank Transfers |
| Companies Covered | Falabella, MercadoLibre, Ripley, Paris (Cencosud), Walmart Chile (Lider), AliExpress, Shopee, Dafiti, Linio, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile E-Commerce Market Emerging Trajectories
Algorithmic personalization engines and embedded finance products are restructuring how Chilean consumers discover, finance, and receive physical goods through digital channels.
Real-time inventory synchronization systems are electrifying merchant operations by connecting warehouse management software directly to consumer-facing mobile applications. Mid-sized retailers in Santiago and Valparaíso adopt these platforms at accelerating pace to prevent stockout-driven cart abandonment. This technology is compressing the gap between order placement and fulfillment confirmation from hours to seconds, reshaping consumer expectations nationwide.
Chile's consumer protection agency oversight of digital transaction transparency and refund obligations tightens merchant accountability for product descriptions and return processing timelines. E-commerce platforms now embed automated dispute resolution workflows to preempt regulatory penalties. Marketplace participants face elevated compliance costs that favor scaled operators with dedicated legal and customer service infrastructure.
Subscription-based purchasing patterns displace one-time transactions in beauty, pet supplies, and household consumables categories. Direct-to-consumer brands bypass traditional retail markup structures by owning customer relationships through mobile applications. This shift concentrates most visibly in Santiago's upper-income districts where delivery density supports flexible scheduling and personalized curation services.
Chile E-Commerce Market Segmentation
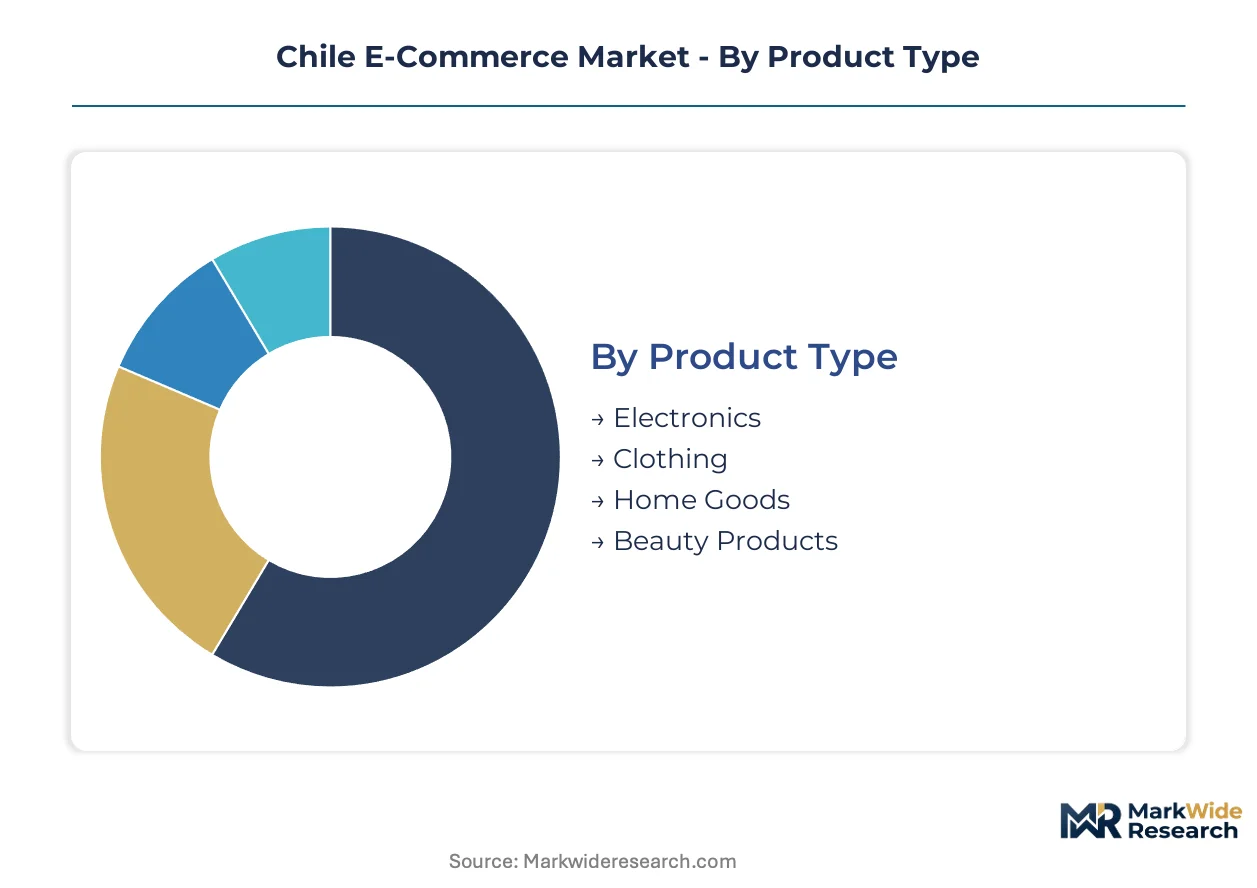
Segmentation reveals how Chile's e-commerce landscape fragments across generational purchasing behaviors, platform preferences, and payment infrastructure maturity. Understanding these divides allows merchants to align fulfillment capabilities with concentrated demand pockets and emerging transaction modalities.
Product Type:
Upgrade cycles and replacement velocity vary dramatically across merchandise categories, with technology refresh rates outpacing durable goods depreciation schedules.
- Electronics:Smartphones, laptops, and smart home devices dominate transaction values through compressed replacement cycles driven by 5G network expansion and remote work normalization. Santiago's metropolitan corridor concentrates demand for premium-tier devices with express fulfillment expectations.
- Clothing:Return-rate management defines profitability in this mature segment, with size-fit algorithms and virtual try-on tools reducing logistics friction. Secondary cities like Valparaíso and Concepción drive growth through expanding fulfillment infrastructure.
- Home Goods:Furniture and appliance purchases cluster around housing turnover and seasonal renovation cycles, with extended delivery windows accepted for bulky items.
- Beauty Products:Direct-to-consumer entrants deploy subscription frameworks that concentrate customer lifetime value in Santiago's upper-income districts.
Volume placements concentrate in Electronics; the faster expansion belongs to Beauty Products.
Customer Type:
Generational divides in platform fluency and payment trust shape merchant acquisition strategies and loyalty program design.
- Millennials:This cohort balances price sensitivity with convenience expectations, driving marketplace participation and mobile-first discovery behaviors across Chile's urban centers.
- Gen Z:Social commerce integration and embedded finance products attract this segment, with TikTok and Instagram shops gaining transaction share fastest in Santiago and Valparaíso metropolitan zones.
- Families:Bulk purchasing and subscription adoption for household consumables define this segment, with grocery frequency anchoring platform loyalty.
- Senior Citizens:Cash-on-delivery preference and customer service accessibility requirements shape platform design for this emerging digital adopter group.
Millennials anchor current transaction volumes; Gen Z is climbing the fastest as social commerce infrastructure matures.
Sales Channel:
Channel strategy determines margin capture versus reach trade-offs, with ownership of customer data becoming a decisive competitive variable.
- Direct-to-Consumer:Brand-controlled mobile applications enable first-party data accumulation and subscription revenue models, particularly effective in beauty and pet supplies categories.
- Marketplaces:MercadoLibre and Falabella's platforms provide logistics backbone and trust infrastructure that compresses merchant launch timelines for cross-border sellers.
- Social Media:Live commerce and influencer-driven discovery reshape impulse purchasing, with Instagram Shops and TikTok Storefront gaining traction among younger demographics.
- Subscription Services:Recurring revenue frameworks improve inventory predictability and customer lifetime value metrics in consumables categories.
Marketplaces capture the dominant transaction share; subscription services are gaining share fastest as merchants pursue predictable revenue streams.
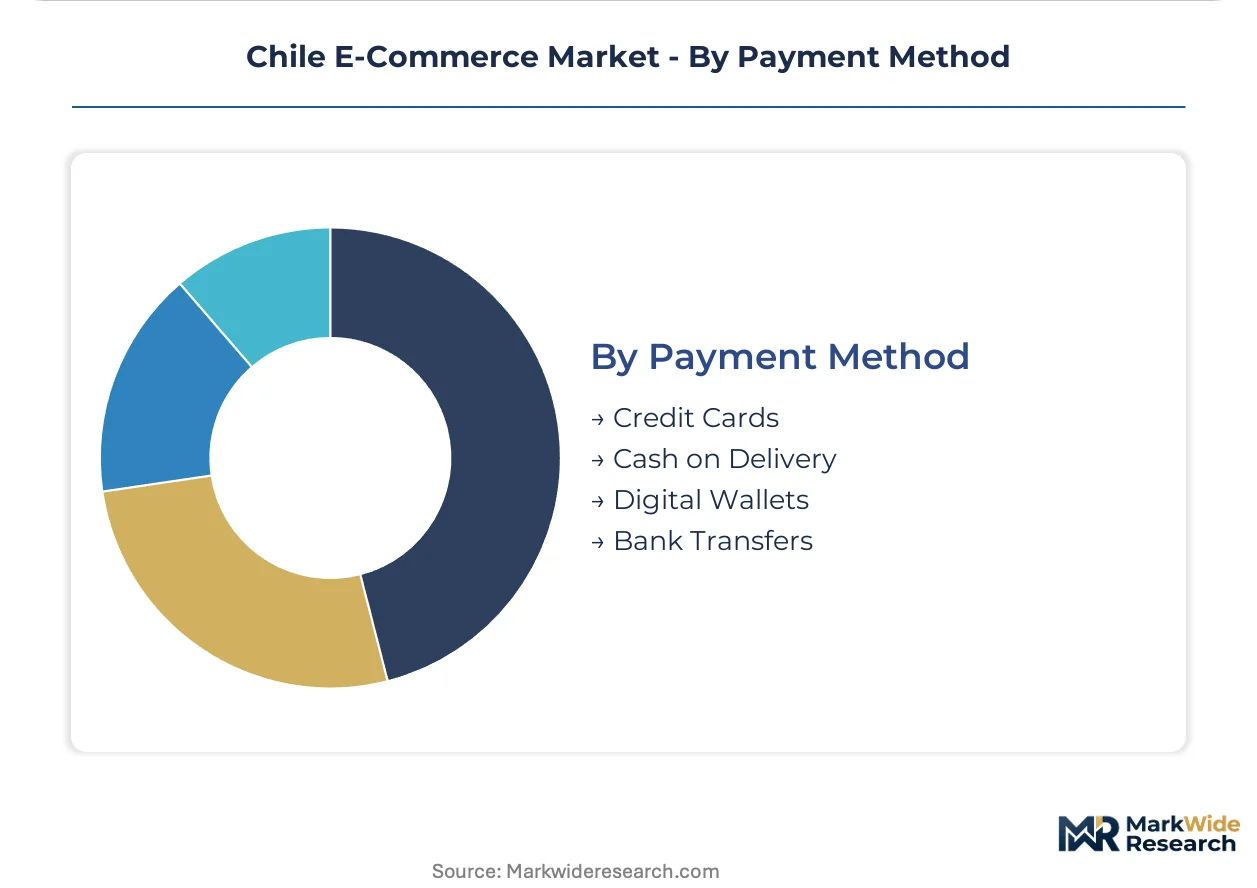
Payment Method:
Settlement infrastructure modernization by Chile's central bank is restructuring transaction cost structures and fraud exposure profiles across merchant categories.
- Credit Cards:Installment financing options drive higher average order values in electronics and appliance categories, with bank partnerships enabling interest-free periods.
- Digital Wallets:Real-time settlement rails reduce cart abandonment and merchant working capital requirements, with Mercado Pago and bank-owned wallets expanding penetration fastest.
- Cash on Delivery:Trust bridge for senior citizens and first-time online purchasers in smaller municipalities with legacy banking access constraints.
- Bank Transfers:Lower transaction fees attract price-sensitive merchants, though settlement delays disadvantage against instant-payment alternatives.
Credit cards retain the largest transaction volume; digital wallets are expanding most quickly as central bank infrastructure modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Santiago's metropolitan retail corridor concentrates Chile's e-commerce fulfillment investment, with secondary logistics nodes emerging in Valparaíso and Concepción to compress delivery windows for consumers outside the capital's immediate radius.
Santiago Metropolitan Region
Smartphone replacement cycles and remote work normalization drive electronics demand through Santiago's urban core. Chile's central bank digital payment infrastructure modernization enables instant settlement rails that reduce merchant working capital requirements. Dark store networks and automated fulfillment centers cluster in Pudahuel and Quilicura industrial zones, serving same-day delivery expectations for premium-tier consumers.
Valparaíso
Port logistics integration attracts cross-border marketplace sellers seeking customs clearance efficiency for imported inventory. The country's consumer protection agency mandates digital transaction transparency standards that elevate compliance costs for smaller merchants. Viña del Mar and Valparaíso proper host dedicated last-mile depots that compress delivery timelines for central coast consumers previously dependent on Santiago-based fulfillment.
Biobío and Concepción
University-town demographics concentrate Gen Z purchasing power in smartphones and social commerce discovery behaviors. Tax authority digitization of electronic invoicing tightens documentation requirements for marketplace participants sourcing from overseas suppliers. San Pedro de la Paz and Talcahuano logistics parks receive regional distribution center investment from national retailers pursuing geographic diversification.
Antofagasta
Mining sector wages support premium electronics and home goods purchasing above national averages. Legacy banking systems in smaller municipalities create settlement delays that disadvantage regional merchants against Santiago-based competitors. The city's isolation from main logistics corridors inflates last-mile costs, favoring marketplace platforms with dedicated freight contracts over independent merchants.
La Araucanía
Agricultural household structures drive bulk purchasing patterns for household consumables and subscription services. Payment infrastructure fragmentation in rural municipalities sustains cash-on-delivery preference among senior citizen demographics entering digital commerce. Temuco anchors regional fulfillment with cross-docking facilities that consolidate dispersed demand into economically viable delivery routes.
Chile E-Commerce Market Vendor Landscape
Premium-margin players sit above commodity-margin players across fulfillment speed and brand trust dimensions, with department-store heritage operators commanding loyalty through integrated omnichannel networks while marketplace infrastructure providers compete on merchant acquisition scale. The vendor base stratifies into three tiers: integrated retail conglomerates with physical store networks, pure-play marketplace platforms with captive logistics, and cross-border entrants competing on price-driven discovery. Consolidation pressure intensifies through strategic partnerships between domestic fulfillment operators and international technology providers, alongside vertical integration into last-mile delivery assets.
Within the integrated retail tier, Falabella and Paris exemplify department-store heritage operators leveraging physical footprint for buy-online-return-in-store capabilities. Among marketplace specialists, MercadoLibre anchors logistics infrastructure spanning Chile's elongated territory. On the cross-border vector, AliExpress and Shopee occupy positions competing through price-driven discovery and direct-from-Asia sourcing models that attract price-sensitive millennial and Gen Z segments in Santiago and Valparaíso metropolitan zones.
| Leading Market Players |
|---|
| Falabella |
| MercadoLibre |
| Ripley |
| Paris (Cencosud) |
| Walmart Chile (Lider) |
| AliExpress |
| Shopee |
| Dafiti |
| Linio |
| Others |
Supply Flow & Price Mechanics
Chile's consumer protection agency mandates on digital transaction transparency gate access to premium-tier merchant status and corresponding pricing power, compressing margins for non-compliant operators while rewarding scaled platforms with dedicated legal infrastructure.
Pricing Analysis
Delivery speed guarantees anchor value-based pricing tiers across Chile's e-commerce landscape, with same-day fulfillment commanding substantial premiums over standard 48-72 hour windows. Pricing stratifies across express, standard, and economy delivery tiers, with electronics and beauty categories showing widest spreads. Cost compression in standard-tier fulfillment intensifies because MercadoLibre and Falabella deploy automated Santiago facilities that regional merchants cannot match. Price-sensitive millennial shoppers in secondary cities drive marketplace participation, while affluent Santiago consumers absorb premium surcharges for curated subscription services.
Supply Chain Analysis
Direct-to-fulfillment-center channels handle hyperscale inventory flows from China, the United States, and Brazil into Santiago's Pudahuel and Quilicura industrial zones. Robotics integration for warehouse automation draws from German and Japanese equipment suppliers, with maintenance parts resting on single-source vulnerability for specialized mechatronics components. Distribution runs through dark store networks for same-day delivery, while cross-border marketplace sellers face customs clearance chokepoints at Valparaíso port. Last-mile density in Santiago's metropolitan corridor enables cost-efficient routing that remote Patagonian and northern desert regions cannot replicate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's e-commerce market sits in a mobile-first transition phase, with smartphone-native discovery behaviors displacing desktop-centric legacy purchasing patterns among younger demographics.
For Market Incumbents: Deploy fulfillment automation as the primary lever to defend against cross-border marketplace entrants exploiting direct-from-Asia cost structures. Incumbent retailers must consolidate dark store networks in Santiago's peripheral industrial zones and accelerate buy-online-return-in-store integration to leverage physical footprint advantages that pure-play platforms cannot replicate.
For New Entrants and Emerging Players: Enter via subscription commerce models in beauty and pet supplies categories, where customer lifetime value metrics remain underoptimized by established marketplace infrastructure. White-space concentration sits in Concepción and La Araucanía's university towns, where Gen Z social commerce adoption outpaces dedicated fulfillment investment from national retailers.
For Investors and Strategic Acquirers: Central bank real-time settlement rail expansion is the leading indicator that digital wallet penetration will displace legacy bank transfer dominance, favoring platforms with captive payment infrastructure. Acquisition targets should display integrated logistics assets spanning Chile's elongated territory, with inflection signals appearing in secondary city fulfillment center announcements from national retailers.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | Automated Santiago facilities enable same-day delivery promises that compress customer acquisition costs. |
| Subscription Commerce Launch | Recurring revenue frameworks in beauty categories improve inventory predictability and lifetime value metrics. |
| Payment Infrastructure Integration | Captive digital wallet deployment reduces cart abandonment and merchant working capital requirements. |
| Cross-Border Marketplace Partnership | Customs clearance efficiency at Valparaíso port accelerates overseas inventory availability for Chilean consumers. |
| Omnichannel Return Integration | Physical store networks enable buy-online-return-in-store capabilities that drive foot traffic and reduce reverse logistics costs. |
Methodological Framework
Multi-period observation of digital wallet transaction volumes, fulfillment center investment announcements, and marketplace seller registration patterns anchored the trend analysis, supplemented by interviews with e-commerce platform executives, logistics operations directors, consumer protection agency officials, and central bank payment system specialists. Secondary validation drew from Chile's tax authority electronic invoicing disclosures, customs import records, retail trade association reports, and mobile application download analytics. Bottom-up merchant capacity assessments and top-down consumer spending pattern analysis enabled triangulation across independent estimation approaches.
Segment-weighting applied product type, customer demographic, sales channel, and payment method dimensions across the modeling period, with electronics and beauty categories receiving distinct trajectory modeling due to diverging replacement cycle dynamics. CAGRs were derived through logistic diffusion curve fitting for technology adoption patterns and econometric demand elasticity estimation for price-sensitive categories. Forecast inputs incorporated central bank settlement infrastructure rollout timelines and secondary city logistics network expansion announcements from national retailers.
Revisions become necessary when regulatory mandates around data localization or import duty structures materialize with implementation timelines diverging from baseline assumptions. Forecasts reflect documented assumptions regarding digital wallet penetration curves and fulfillment automation deployment rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
E-Tailing Market
E-Commerce Solutions
E-Commerce Fashion Accessories Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
Digital Gift Cards (Egift Cards) Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
Latvia E-Commerce Market
E-Commerce Solutions
Automotive E-Commerce Market