
 Digital Gift Cards (Egift Cards) Market | 2026-2036
Digital Gift Cards (Egift Cards) Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Gift Cards (Egift Cards) Market Insights
EU Green Deal disclosure requirements for digital financial products is broadening accountability across egift card issuers. Blackhawk Network leverages its closed-loop processing infrastructure to sustain merchant network density across North America. InComm Payments anchors B2B platform distribution through proprietary API integrations with enterprise procurement systems. Amazon.com dominates consumer-facing egift card velocity through embedded checkout placement across its marketplace ecosystem.
Digital gift cards are electronically delivered stored-value instruments encoded with unique identifiers and redeemable through point-of-sale terminals, mobile wallets, or online checkout portals; they function as prepaid payment mechanisms without physical plastic substrate. Closed-loop configurations command margin concentration due to merchant-specific redemption capture and breakage revenue retention, while open-loop instruments tied to card network rails compete for corporate expense management volume. B2B platform distribution exhibits the fastest structural expansion as enterprises automate employee recognition and customer loyalty disbursements through integrated SaaS procurement workflows.
The Federal Reserve's Regulation E governs consumer liability limits for electronic fund transfers including egift instruments, while the Consumer Financial Protection Bureau enforces disclosure standards on dormancy fees and expiration terms. The EU's Payment Services Directive 2 mandates strong customer authentication for digital payment instruments, elevating issuer compliance investment thresholds. Stakeholders must monitor evolving state-level unclaimed property statutes that reclassify unredeemed balances as escheatable liabilities.
Market Dynamics
Mobile wallet integration is compressing redemption friction and anchoring consumer preference migration from physical to digital stored-value instruments across retail and corporate disbursement channels.
Growth Catalysts
- Strong Customer Authentication Mandates:The EU's Payment Services Directive 2 elevates issuer compliance investment thresholds while simultaneously building consumer trust in digital payment instruments through standardized security protocols.
- Corporate Procurement Automation:Technology firms anchor volume expansion through embedded SaaS workflows that automate employee recognition and customer loyalty disbursements at scale.
- Mobile Wallet Rails:Near-field communication infrastructure proliferation enables tap-to-redeem functionality that eliminates manual code entry and accelerates point-of-sale throughput.
Market Restraints
- Breakage Revenue Scrutiny:State-level unclaimed property statutes reclassify unredeemed balances as escheatable liabilities, compressing margin retention for closed-loop issuers.
- Network Concentration Risk:Card network dependency for open-loop instruments creates interchange fee exposure and rail access vulnerability concentrated among four dominant processors.
- Fraud Vector Proliferation:Account takeover attacks targeting stored-value balances exploit weaker authentication protocols on legacy redemption portals.
Strategic Opportunities
- API-Native B2B Platforms:Enterprise procurement system integration creates white space for issuers embedding programmable disbursement logic into HR and CRM workflows.
- Cross-Border Remittance Rails:Digital gift cards function as low-friction value transfer mechanisms in corridors with limited correspondent banking infrastructure.
- Carbon Disclosure Alignment:EU Green Deal requirements for digital financial products create competitive differentiation for issuers with transparent environmental accounting.
Industry Challenges
- Legacy System Integration Complexity:Enterprise clients demand real-time balance synchronization between egift platforms and existing ERP architectures, stretching implementation timelines.
- Compliance Talent Scarcity:Anti-money laundering directive expertise sits concentrated among specialists familiar with both payment rail regulation and digital asset tracing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Gift Cards (Egift Cards) Market |
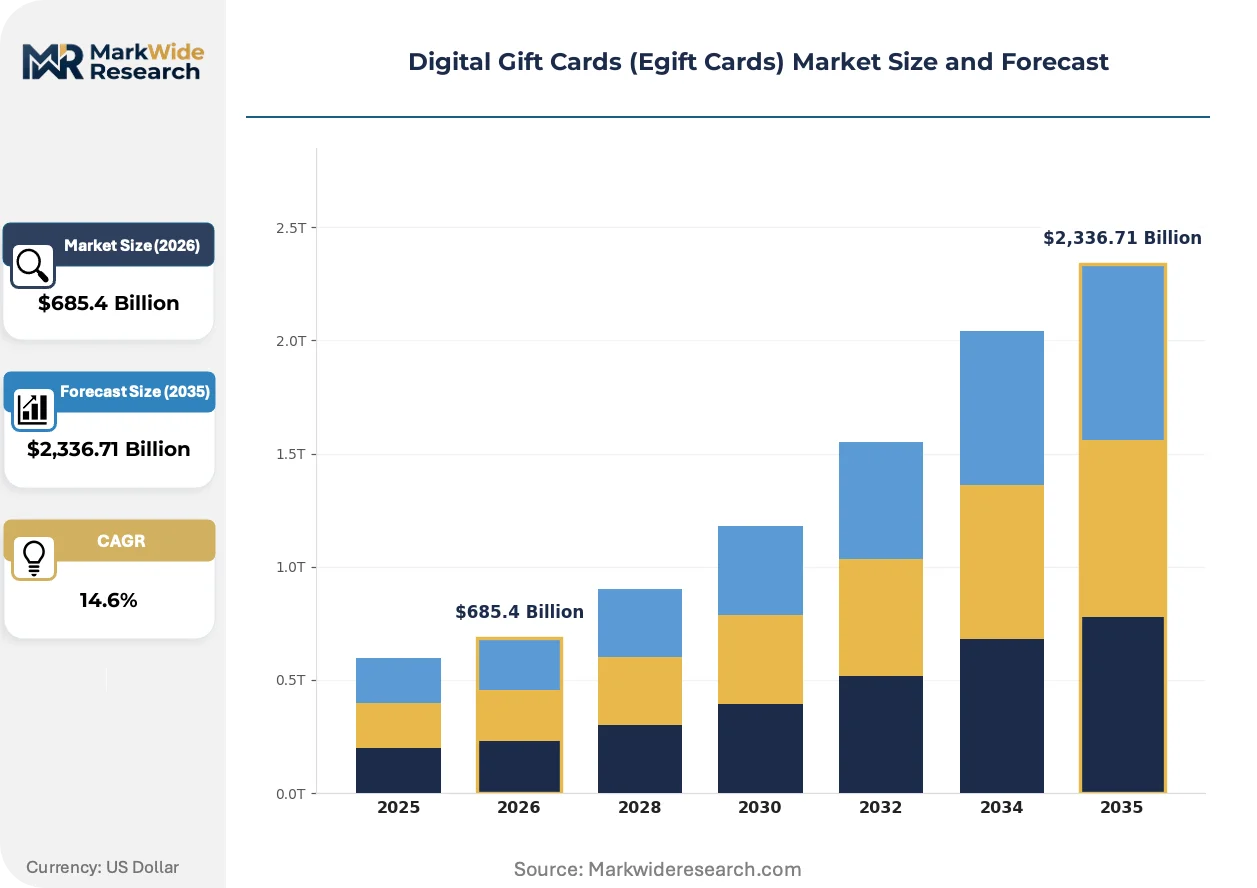
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $2,336.71 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed-loop, Open-loop, Private-label, Multi-brand Distribution Channel: Online Retailers, Brick-and-Mortar Stores, Mobile Apps, B2B Platforms Customer Type: Businesses, Consumers, Non-profits, Educational Institutions Usage Occasion: Holidays, Birthdays, Anniversaries, Corporate Gifts |
| Companies Covered | Blackhawk Network, InComm Payments, Loop Commerce, PayPal Holdings, Amazon.com, Apple, Walmart, Target Brands, Fiserv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Gift Cards (Egift Cards) Market Trends and Innovations
Tokenization architectures and programmable redemption logic are displacing static code-based systems, enabling dynamic balance management and contextual trigger-based disbursement across consumer and corporate segments.
Blockchain-based settlement infrastructure is modularizing back-end reconciliation processes for multi-merchant egift networks. Large retailers pilot distributed ledger rails to compress clearing cycles from days to minutes. This modularizing architecture reduces working capital requirements and enables real-time breakage recognition.
The EU's Payment Services Directive 2 mandates strong customer authentication for digital payment instruments, forcing issuers to retool authentication flows. Compliance investment thresholds have risen substantially. North American issuers are preemptively adopting comparable standards to maintain cross-border interoperability.
Subscription bundling models are displacing standalone egift purchases in consumer channels. Streaming services and meal kit platforms embed stored-value instruments into annual membership tiers. This shift concentrates redemption velocity within platform ecosystems and reduces customer acquisition costs for participating merchants.
Digital Gift Cards (Egift Cards) Market Segmentation
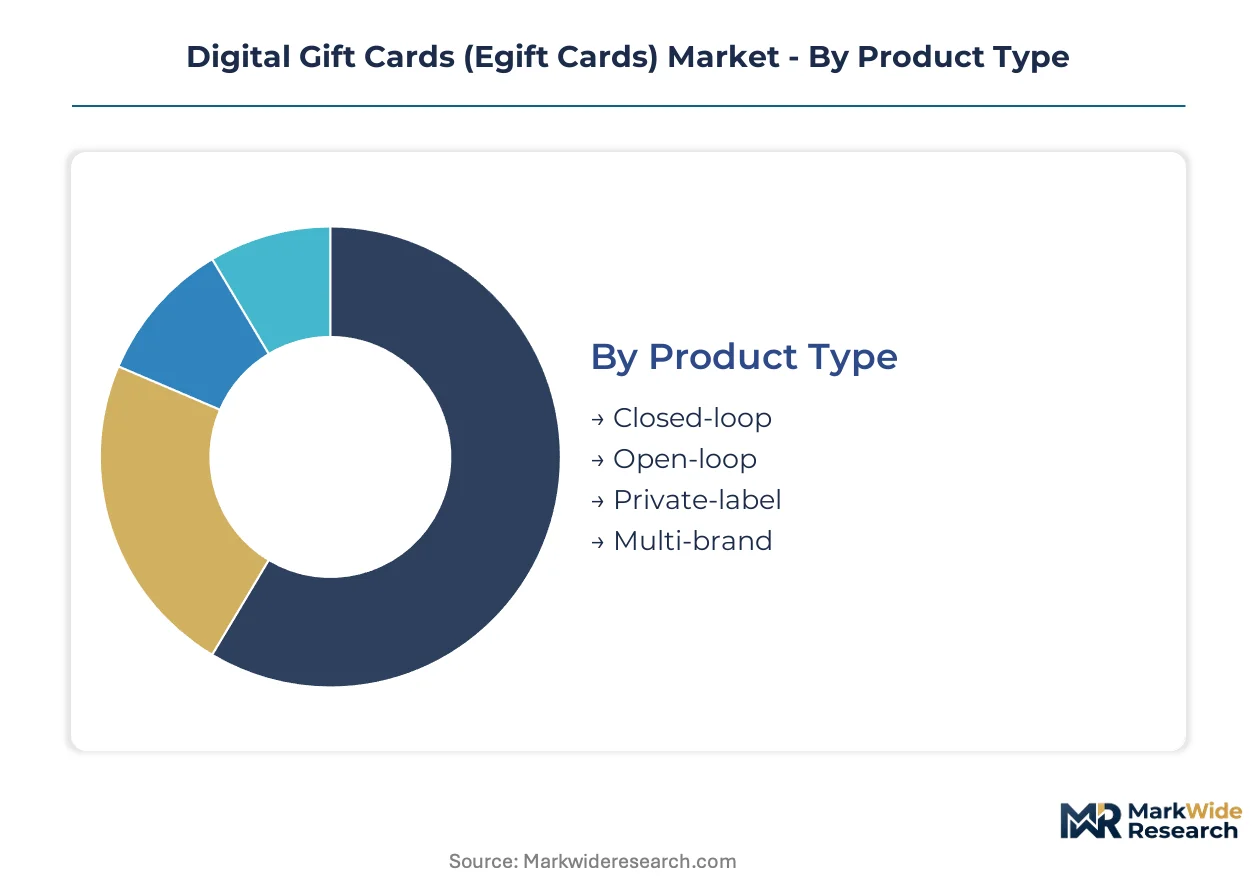
Segmentation in the egift card market reveals divergent margin structures and compliance burdens across product architectures. Issuers configure operational models around redemption control, distribution rails, and buyer procurement workflows rather than treating stored-value instruments as uniform commodities.
Product Type:
Technical specifications around redemption rails and merchant network access define competitive positioning across product architectures.
- Closed-loop:Instruments redeemable exclusively at a single merchant or affiliated brand network capture breakage revenue and transaction data within proprietary ecosystems. Technology firms in the United States anchor volume expansion through corporate gifting programs that leverage closed-loop processing infrastructure for employee recognition disbursements.
- Open-loop:Network-branded instruments tied to Visa, Mastercard, or American Express rails function as prepaid payment mechanisms accepted wherever card networks operate. Demand concentrates among enterprises automating expense management workflows, though interchange fee exposure compresses margins relative to closed-loop alternatives.
- Private-label:Co-branded configurations issued through retail partnerships enable merchants to capture customer data without building proprietary processing infrastructure.
- Multi-brand:Aggregated redemption options across non-affiliated merchants appeal to gift-givers seeking recipient flexibility, though clearing complexity elevates operational overhead.
Closed-loop leads on scale; open-loop leads on momentum.
Distribution Channel:
Cost tier differentiation separates high-touch enterprise procurement from low-friction consumer self-service pathways.
- Online Retailers:Embedded checkout placement across marketplace ecosystems drives velocity through reduced purchase friction. Amazon.com dominates this channel through algorithmic gift recommendations and one-click delivery mechanisms that compress decision cycles.
- B2B Platforms:API-native integration with enterprise HR and CRM systems enables programmable disbursement logic for employee recognition and customer loyalty at scale. This channel climbs the fastest as SaaS procurement workflows automate previously manual gift allocation processes.
- Mobile Apps:Near-field communication infrastructure enables tap-to-redeem functionality that eliminates manual code entry at point-of-sale terminals.
- Brick-and-Mortar Stores:Physical retail placement persists for cash-preferred demographics and last-minute purchase occasions, though volume share migrates steadily toward digital channels.
B2B platforms lead on margin expansion; online retailers lead on transaction velocity.
Customer Type:
Application focus varies sharply between procurement-automated enterprises and episodic individual purchasers.
- Businesses:Corporate gifting programs anchor structural volume expansion through recurring disbursement commitments and negotiated pricing tiers. Technology firms in particular drive platform adoption through integrated SaaS workflows.
- Consumers:Individual purchasers respond to mobile wallet integration and subscription bundling models that embed stored-value instruments into membership tiers.
- Non-profits:Donor incentive programs leverage egift cards for stewardship and retention, though compliance complexity around charitable disbursement reporting elevates operational burden.
- Educational Institutions:Student incentive and recognition programs represent emerging procurement volume with distinct seasonal concentration around academic calendars.
Businesses lead on contract value; consumers lead on transaction frequency.
Usage Occasion:
Volume concentration patterns align with calendar-driven gifting rituals and enterprise fiscal cycles.
- Holidays:Year-end gifting rituals concentrate redemption velocity in November and December, straining issuer processing infrastructure and customer service capacity.
- Corporate Gifts:Fiscal calendar alignment drives B2B disbursement timing, with budget exhaustion patterns elevating fourth-quarter volume.
- Birthdays:Recurring individual occasions sustain baseline consumer demand throughout the calendar year with lower per-transaction values.
- Anniversaries:Relationship-marking occasions support premium-tier product positioning and experiential redemption options.
Holidays lead on peak volume; corporate gifts lead on predictable recurrence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment technology talent clusters in the United States and European financial centers anchor regional market development, with compliance expertise concentrated among specialists navigating PSD2 and Regulation E frameworks.
United States
Mobile wallet integration and corporate gifting programs at technology firms drive consumer preference shifts toward digital stored-value instruments. The Federal Reserve's Regulation E governs consumer liability limits for electronic fund transfers, elevating issuer compliance investment. Silicon Valley and New York Metro anchor platform development, with Blackhawk Network leveraging closed-loop processing infrastructure to sustain merchant network density.
Germany
Enterprise procurement automation and B2B platform adoption accelerate as manufacturers integrate SaaS workflows for employee recognition. The EU's Payment Services Directive 2 mandates strong customer authentication, forcing retooling of authentication flows. Frankfurt's financial technology cluster hosts issuers preemptively adopting comparable standards to maintain cross-border interoperability with North American markets.
United Kingdom
Fintech innovation hubs drive API-native distribution channel expansion for corporate disbursement solutions. The Financial Conduct Authority enforces conduct standards on digital payment instruments, aligning with EU security protocols post-Brexit. London anchors B2B platform development, with issuers embedding programmable disbursement logic into HR and CRM workflows at scale.
Japan
Near-field communication infrastructure proliferation enables tap-to-redeem functionality across retail point-of-sale terminals. METI guidelines on digital payment security shape issuer authentication architecture investments. Tokyo and Osaka metropolitan areas concentrate mobile wallet integration development, with technology firms piloting tokenization architectures for dynamic balance management.
India
Digital payment adoption through unified payments interface rails creates white space for egift card distribution in underbanked corridors. RBI regulations on prepaid payment instruments govern issuer licensing and capital requirements. Bangalore and Mumbai anchor fintech platform development, with enterprises automating customer loyalty disbursements through integrated procurement systems.
Digital Gift Cards (Egift Cards) Market Competitive Landscape
Capital-heavy payment processors compete with asset-light platform designers across the egift card value chain, creating a tiered structure where closed-loop infrastructure owners capture margin concentration while open-loop network dependents absorb interchange exposure. The vendor base clusters around three strategic archetypes: merchant-integrated closed-loop specialists, card network-tethered open-loop distributors, and API-native B2B platform providers. Dominant competitive moves include strategic partnerships embedding disbursement logic into enterprise SaaS workflows and geographic expansion through cross-border remittance rail development.
Within the closed-loop infrastructure tier, Blackhawk Network and InComm Payments exemplify merchant network density strategies, with the former sustaining North American processing scale and the latter anchoring B2B platform distribution through proprietary API integrations. Amazon.com occupies a distinct position at the consumer-facing velocity end, leveraging embedded checkout placement across marketplace ecosystems to compress purchase decision cycles.
| Leading Market Players |
|---|
| Blackhawk Network |
| InComm Payments |
| Loop Commerce |
| PayPal Holdings |
| Amazon.com |
| Apple |
| Walmart |
| Target Brands |
| Fiserv |
| Others |
Pricing and Supply Chain Analysis
Corporate procurement automation at technology firms is compressing unit economics for issuers, forcing supply chain retooling toward API-native infrastructure and real-time balance synchronization that elevates platform investment thresholds.
Pricing Analysis
Bundled subscription models displace standalone transactional pricing as streaming services and meal kit platforms embed stored-value instruments into annual membership tiers. Three-tier pricing structure across premium experiential, standard retail, and economy digital-only levels separates breakage-retaining closed-loop configurations from interchange-exposed open-loop alternatives. Price differentiation hinges on merchant network exclusivity and embedded checkout placement depth. Cost compression in economy tiers is intensifying because mobile wallet integration commoditizes basic redemption functionality. Small and mid-sized merchants exhibit highest price sensitivity; enterprise technology firms with automated SaaS workflows demonstrate lowest sensitivity due to volume commitments.
Supply Chain Analysis
PCI-DSS certification and PSD2 strong customer authentication qualification gate access to enterprise procurement channels, concentrating viable issuer infrastructure among capital-heavy payment processors with compliance expertise. Processing infrastructure concentrates in the United States, Germany, and the United Kingdom where payment technology talent clusters anchor platform development. Raw material dependencies span cryptographic tokenization modules, NFC-enabled point-of-sale terminals, and cloud-native API gateway architectures. Single-source vulnerability sits with dominant card network rails for open-loop instruments. Distribution runs through embedded marketplace checkout placement, direct B2B platform integration, and mobile wallet native applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital gift cards rests on breakage revenue retention in closed-loop architectures and premium-tier subscription bundling that concentrates redemption velocity within platform ecosystems.
For Market Incumbents: Cement closed-loop merchant network density through exclusive processing infrastructure partnerships that lock in breakage revenue streams. Defend against API-native B2B platform entrants by embedding programmable disbursement logic directly into enterprise HR and CRM workflows at scale. Prioritize certification investment in PCI-DSS Level 1 and PSD2 compliance to maintain cross-border interoperability access. For New Entrants and Emerging Players: The price-point gap between premium experiential redemption options and economy digital-only tiers opens white space for mid-market positioning. Target educational institutions and non-profit donor incentive programs as underpenetrated procurement verticals with distinct seasonal disbursement patterns. Pursue white-label platform partnerships with established closed-loop infrastructure owners to bypass capital-heavy processing buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with API-native B2B platform providers possessing enterprise SaaS integration capabilities and programmable disbursement logic. Long-term viability over the coming decade favors issuers with diversified product architecture exposure across closed-loop, open-loop, and private-label configurations. Monitor mobile wallet native application penetration rates as the critical inflection signal for consumer channel displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native B2B Platform Integration | Embedded disbursement logic in Workday and Salesforce workflows automates enterprise gift allocation at scale. |
| Mobile Wallet Native Application Development | Apple Wallet and Google Pay integration eliminates manual code entry friction at point-of-sale terminals. |
| Blockchain Settlement Infrastructure Pilot | Distributed ledger rails compress multi-merchant clearing cycles from days to minutes for working capital efficiency. |
| Cross-Border Remittance Rail Expansion | Digital gift cards function as low-friction value transfer mechanisms in corridors with limited correspondent banking. |
| EU Green Deal Carbon Disclosure Alignment | Transparent environmental accounting creates competitive differentiation for ESG-mandated corporate procurement. |
Research Methodology
Multiple input streams — primary interviews with platform engineering leads, enterprise procurement officers, and payment compliance specialists, combined with secondary validation against SEC filings, PCI-DSS certification registries, and mobile wallet integration disclosure data — were reconciled through bottom-up transaction volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across product architecture segmentation, distribution channel dynamics, and customer type procurement patterns anchored the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory compliance investment cycles and mobile wallet adoption curves. Modeled inputs included closed-loop breakage recognition timing, open-loop interchange fee exposure, and B2B platform API integration velocity.
Caveats apply where PSD2 enforcement intensity, state-level unclaimed property statute revisions, or card network rail access restrictions could materially shift the outlook. A model refresh is warranted upon material change in mobile wallet native application penetration thresholds or enterprise SaaS procurement automation adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Search Software Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
C2C E-Commerce Market
E-Commerce Solutions
Global Ecommerce Platform Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
E-Commerce Apparel Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
E-Commerce Electronics Market