
 Slovakia E-Commerce Market | 2026-2036
Slovakia E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Slovakia E-Commerce Market Insights
The marketplace channel is reconfiguring how Slovak consumers discover and complete purchases, with platform aggregators displacing standalone retail sites. Alza.sk leverages its logistics infrastructure to sustain next-day delivery dominance across the republic. Mall.sk anchors its position through broad-category inventory depth and recurring promotional cycles. Heureka.sk competes as a price-comparison layer that influences final purchase decisions before checkout.
Slovakia E-Commerce denotes the digital exchange of goods and services through internet-enabled transaction platforms, encompassing web-based storefronts, mobile applications, and integrated payment gateways that process orders from product display through final settlement. The primary commercial purpose is to disintermediate traditional retail by reducing geographic friction and enabling inventory-light selling models. Clothing and Electronics command the largest transaction volumes, while Mobile Apps represent the fastest-growing sales channel as smartphone penetration deepens among Slovak shoppers. B2C transactions dominate value flows, though B2B procurement through digital channels is gaining structural importance among Slovak SMEs.
The EU Digital Services Act, GDPR, and Slovakia's national implementation of consumer protection standards under the EU Consumer Rights Directive collectively shape platform liability, data handling obligations, and return-policy enforcement. Slovak traders must navigate overlapping compliance requirements from Brussels and Bratislava's national trade inspectorate. Stakeholders should monitor how forthcoming EU AI Act provisions affect automated product recommendations and dynamic pricing algorithms deployed by major Slovak platforms.
Market Dynamics
Platform aggregators are compressing Slovakia's e-commerce landscape by concentrating consumer traffic into marketplace hubs that extract margin from standalone retailers while dictating fulfillment standards.
Growth Catalysts
- EU Digital Services Act:The DSA's transparency mandates for algorithmic recommendations are forcing Slovak platforms to upgrade disclosure infrastructure, creating compliance-driven investment cycles that modernize legacy systems.
- Smartphone penetration:Mobile-first purchasing behavior among Bratislava's younger demographics is migrating transaction volume from desktop environments, compressing checkout friction and expanding addressable reach.
- Logistics infrastructure:Dense warehouse networks around the capital corridor are enabling same-day fulfillment promises that lock in consumer loyalty and raise competitive barriers for entrants.
Market Restraints
- GDPR enforcement complexity:Slovakia's national data protection authority applies Brussels-mandated consent frameworks with limited local interpretive guidance, creating compliance uncertainty for cross-border sellers.
- Payment gateway concentration:Slovak e-commerce depends heavily on a narrow set of EU-licensed payment processors, exposing merchants to fee volatility and service disruption risks.
- Last-mile cost structure:Rural delivery density outside Bratislava's economic corridor inflates per-unit logistics costs, compressing margins on low-ticket items.
Strategic Opportunities
- Košice region:Eastern Slovakia's secondary urban centers remain underpenetrated by premium fulfillment networks, offering first-mover advantage for localized distribution investments.
- B2B procurement digitization:Slovak manufacturing SMEs currently source through legacy channels, presenting white space for platform-based vendor consolidation and automated reordering systems.
- EU AI Act preparation:Early alignment with forthcoming algorithmic auditing requirements positions compliant Slovak platforms to capture vendor migration from slower-adapting competitors.
Industry Challenges
- Technical talent scarcity:Bratislava's finite pool of platform engineers and data specialists commands premium compensation, inflating operational costs for scaling merchants.
- Legacy ERP integration:Established Slovak retailers operate on aging inventory management systems that resist real-time API connectivity with marketplace backends, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovakia E-Commerce Market |
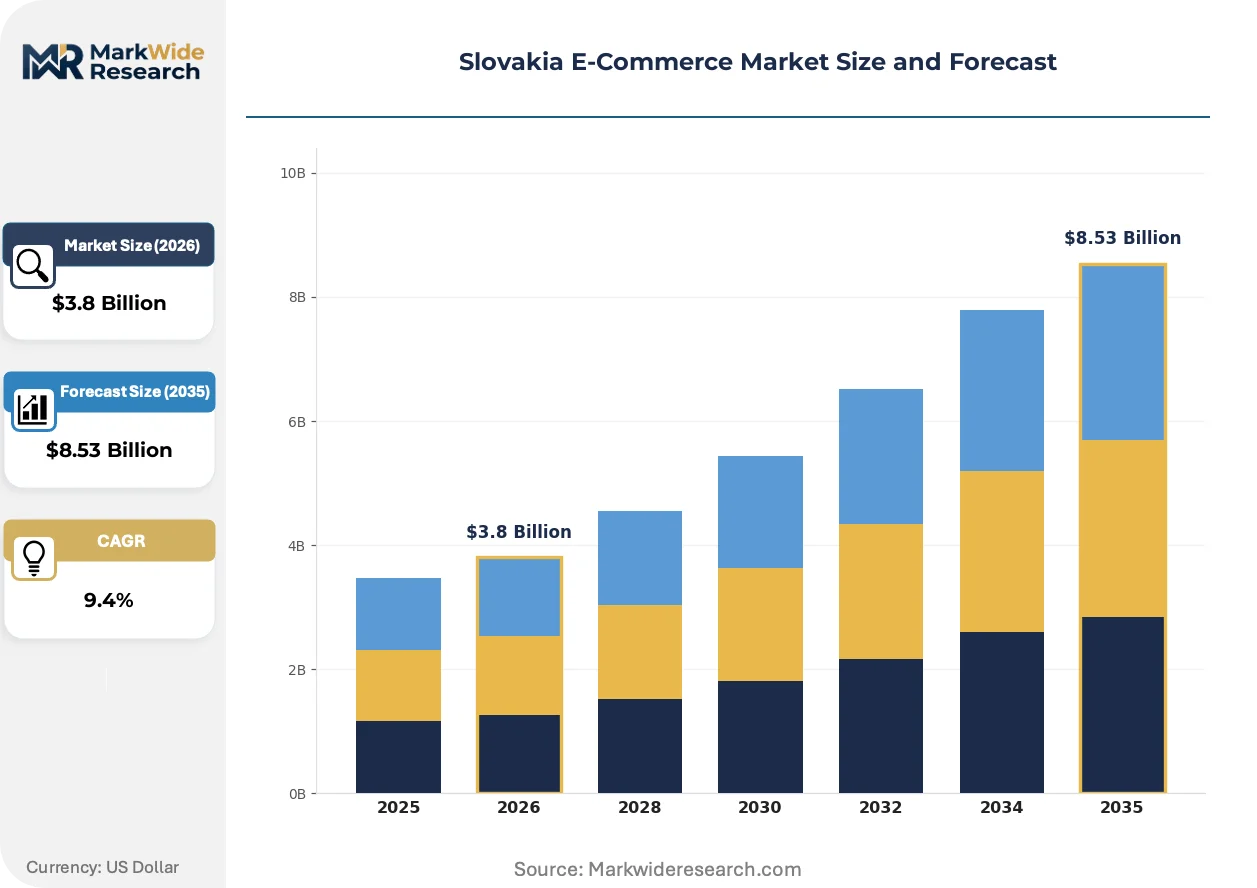
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Electronics, Home Appliances, Beauty Products Customer Type: B2B, B2C, C2C, C2B Sales Channel: Direct Sales, Marketplace, Social Media, Mobile Apps Payment Method: Credit Card, PayPal, Bank Transfer, Cash on Delivery |
| Companies Covered | Alza.sk, Mall.sk, Heureka.sk, Nay.sk, Itesco.sk, Bazos.sk, Temu.com, H&M, Kaufland.sk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovakia E-Commerce Market Trends and Innovations
Three forces are restructuring how Slovak consumers discover, evaluate, and complete purchases: mobile interface dominance, regulatory transparency mandates, and fulfillment speed compression.
Progressive web applications (PWAs) are migrating from experimental deployment to standard infrastructure across Slovak retail platforms. These browser-based apps deliver native-app performance without store-mediated distribution, enabling direct customer relationships. Mid-market fashion and electronics merchants in Bratislava are adopting PWAs fastest, stripping dependency on Apple and Google commission structures while capturing push-notification engagement previously reserved for installed applications.
The EU AI Act's risk-classification framework is reshaping how Slovak platforms deploy automated recommendation engines. High-risk systems—those influencing consumer purchasing decisions—face mandatory human oversight and algorithmic impact assessments. Slovak marketplace operators are reconfiguring dynamic pricing modules and personalized product feeds to pre-emptively meet documentation requirements, diverting engineering resources from feature development to compliance architecture.
Subscription-based replenishment models are displacing one-off purchasing in household consumables and pet supplies. Slovak consumers in urban centers are locking into automated delivery cycles for detergent, diapers, and specialty foods, trading purchase autonomy for price discounts and convenience. This behavioral shift concentrates inventory forecasting power with platform operators while compressing brand loyalty to fulfillment reliability rather than product differentiation.
Slovakia E-Commerce Market Segmentation
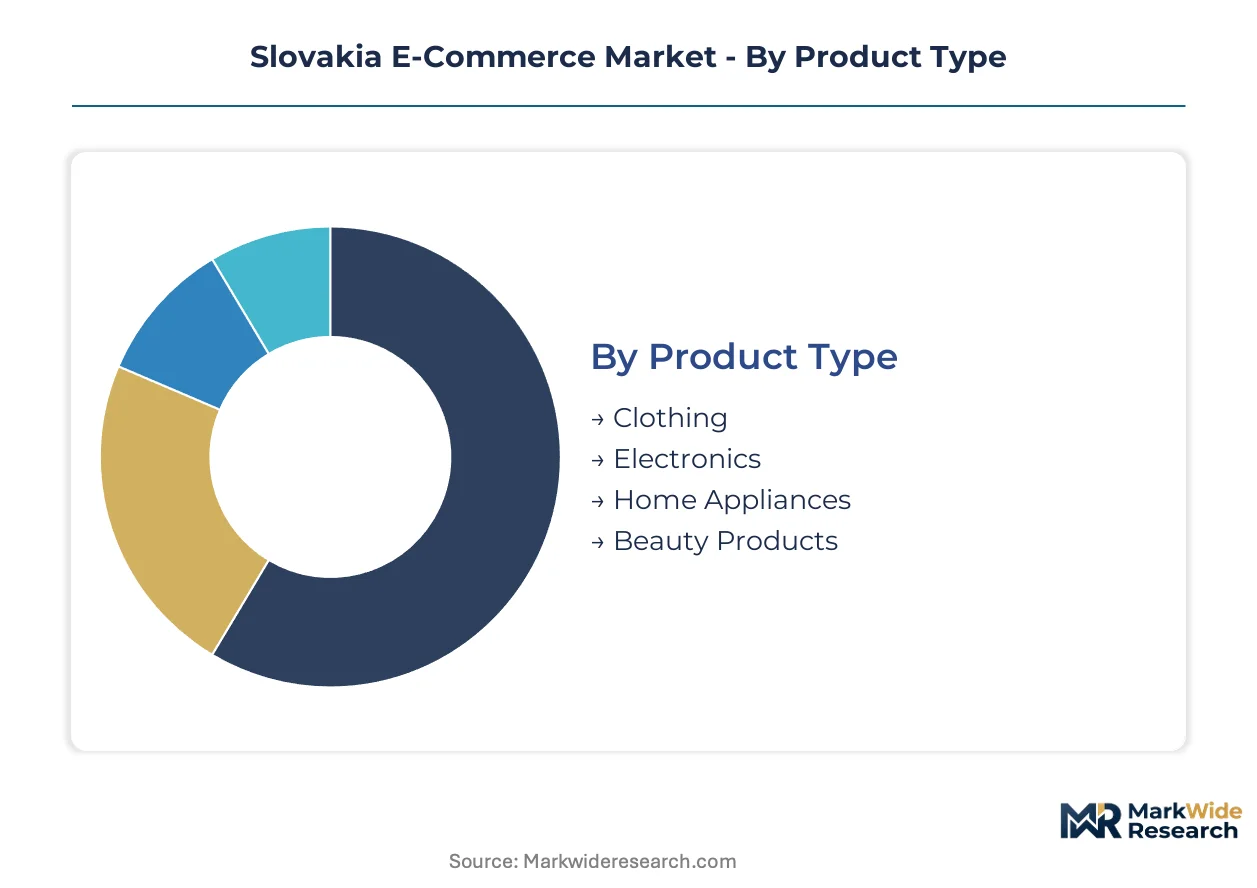
Slovakia's e-commerce segmentation reveals divergent service requirements across product categories and transaction modes. Platform operators must calibrate logistics intensity, return handling, and customer support protocols to match segment-specific expectations.
Product Type:
After-sales-service intensity varies dramatically across product categories, with Electronics demanding technical support infrastructure while Clothing prioritizes frictionless return logistics.
- Electronics:Complex warranty fulfillment and repair coordination dominate post-purchase operations. Bratislava's urban corridor concentrates demand for smartphones, laptops, and smart home devices, with consumers expecting same-day technical support and extended warranty activation.
- Clothing:Size-mismatch returns drive operational costs, requiring reverse logistics networks and inspection facilities. Slovak fashion e-commerce processes return rates substantially above other categories, compressing net margins despite high gross transaction volumes.
- Home Appliances:Installation scheduling and haul-away services differentiate competing platforms.
- Beauty Products:Authenticity verification and expiration-date transparency shape purchase confidence.
By volume, Clothing leads. By growth pace, Electronics is ahead.
Customer Type:
Cost tier stratification separates enterprise procurement platforms from consumer-facing marketplaces, with B2B transactions commanding premium service levels and dedicated account management.
- B2C:Individual consumers drive transaction frequency through impulse purchases and promotional responsiveness. Slovak households in Bratislava and Košice generate the majority of order volume, with mobile-first purchasing behavior reshaping platform interface investments.
- B2B:Manufacturing SMEs and retail chains source inventory through digitized procurement channels, requiring invoice financing, volume-tiered pricing, and integration with buyer ERP systems. This segment exhibits higher average order values and lower return rates than consumer transactions.
- C2C:Peer-to-peer marketplace activity concentrates in secondhand electronics and fashion resale.
- C2B:Individual sellers supplying business buyers remain nascent in Slovakia's e-commerce structure.
B2C captures the highest transaction frequency. B2B posts the steepest expansion trajectory as SME procurement digitizes.
Sales Channel:
Application context determines channel selection, with planned purchases flowing through marketplaces while discovery-driven buying migrates to social interfaces.
- Marketplace:Aggregator platforms consolidate vendor inventory under unified fulfillment promises. Slovak consumers default to marketplace hubs for price transparency and delivery reliability, concentrating traffic away from standalone merchant sites.
- Mobile Apps:Native and progressive web applications capture on-the-go purchasing moments. Younger demographics in Bratislava complete transactions predominantly through smartphone interfaces, driving platform investment in biometric checkout and push-notification engagement.
- Direct Sales:Brand-owned storefronts retain customer data and margin control.
- Social Media:Influencer-driven discovery and in-app checkout expand addressable audiences.
Marketplace dominates transaction value. Mobile Apps are climbing the fastest as smartphone penetration deepens.
Payment Method:
Customer type and purchase context dictate payment instrument selection, with B2B procurement favoring bank transfers while B2C transactions split across convenience and security preferences.
- Credit Card:Card networks dominate high-value transactions and cross-border purchases. Slovak issuers compete on cashback programs and installment options, embedding payment choice into platform checkout flows.
- Bank Transfer:Immediate payment systems and deferred invoice settlement serve B2B procurement and trust-sensitive consumers. Slovakia's banking infrastructure supports real-time transfer confirmation, reducing merchant settlement risk.
- PayPal:Cross-border transactions and buyer protection policies attract risk-averse shoppers.
- Cash on Delivery:Remaining penetration in rural corridors and among unbanked segments.
Credit Card leads by transaction volume. Bank Transfer is gaining share fastest in B2B digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bratislava-Záhorská Ves highway corridor and Vienna-Bratislava rail link anchor Slovakia's e-commerce logistics spine, connecting fulfillment centers to Central European distribution networks.
Bratislava Region
Urban density and household purchasing power concentrate transaction volume in Slovakia's capital corridor. GDPR enforcement by the national data protection authority shapes platform data handling practices here. Bratislava's warehouse clusters along the D2 motorway enable same-day delivery promises that lock in consumer loyalty.
Western Slovakia
Cross-border commuter flows from Austria and Czech Republic generate bilingual platform demand and multi-currency transaction complexity. The EU Consumer Rights Directive mandates return-policy transparency that Western Slovak platforms must display prominently. Trnava and Nitra host secondary fulfillment nodes extending next-day coverage beyond the capital.
Central Slovakia
Mountain geography inflates last-mile delivery costs and stretches fulfillment timelines for electronics and fashion purchases. Slovakia's trade inspectorate maintains regional offices in Žilina and Banská Bystrica monitoring distance-selling compliance. Žilina's automotive supplier base generates B2B procurement digitization opportunities.
Eastern Slovakia
Košice and Prešov remain underpenetrated by premium logistics networks, creating whitespace for localized distribution investments. EU cohesion fund infrastructure programs support broadband expansion enabling mobile commerce penetration. Košice's IT university graduate pipeline offers technical talent at lower cost than Bratislava.
Southern Slovakia
Agricultural supply chains and rural household dispersion sustain cash-on-delivery preferences in districts bordering Hungary. The EU Digital Services Act's platform transparency requirements apply equally here despite lower transaction density. Komárno and Dunajská Streda serve as cross-border fulfillment staging points for Hungarian market access.
Slovakia E-Commerce Market Competitive Landscape
On the supply side, the industry is consolidating around platform aggregators that concentrate consumer traffic while extracting margin from standalone retailers. Three archetypes dominate: marketplace hubs with captive logistics, price-comparison intermediaries, and vertically integrated electronics specialists. Competitive maneuvering centers on fulfillment speed investments and mobile-first interface development.
Within the domestic marketplace tier, Alza.sk and Mall.sk anchor platform infrastructure development, while Heureka.sk exemplifies the comparison-layer archetype influencing pre-checkout decisions. These Slovak-based entities occupy positions between pan-European entrants and emerging Chinese cross-border platforms.
| Leading Market Players |
|---|
| Alza.sk |
| Mall.sk |
| Heureka.sk |
| Nay.sk |
| Itesco.sk |
| Bazos.sk |
| Temu.com |
| H&M |
| Kaufland.sk |
| Others |
Pricing and Supply Chain Analysis
The Bratislava-Záhorská Ves highway corridor's freight cost dynamics concentrate supply power among logistics-heavy incumbents while forcing price differentiation between same-day and standard delivery tiers. Alza.sk's captive warehouse network along this spine extracts margin premiums from urban consumers while compressing rural price competitiveness.
Pricing Analysis
Volume-discount tiering structures separate enterprise B2B procurement contracts from individual consumer transactions. Pricing stratifies across premium same-day delivery, standard next-day fulfillment, and economy multi-day tiers. Cost compression in the economy tier intensifies because Temu.com's cross-border direct shipping bypasses Slovak VAT collection thresholds. B2B manufacturing buyers exhibit lowest price sensitivity due to invoice financing integration, while rural C2C sellers face highest sensitivity to cash-on-delivery surcharges.
Supply Chain Analysis
Tariff exposure between China and the EU dominates supply chain risk planning for Slovak electronics and fashion platforms. Inventory sourcing draws from Chinese manufacturing clusters for consumer electronics, Polish distribution hubs for fast fashion, and Czech automotive component networks for B2B procurement. Single-source vulnerability concentrates in EU-licensed payment processor dependencies. Distribution runs through Bratislava's D2 motorway warehouse clusters extending to Trnava and Nitra secondary nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slovakia's e-commerce fragmentation creates acquisition and entry opportunities as mobile-first purchasing behavior splinters demand across specialized vertical apps and generalized marketplace hubs.
For Market Incumbents: Build fulfillment speed moats through same-day delivery density investments in Bratislava and Košice. Alza.sk and Mall.sk should consolidate vendor onboarding infrastructure to raise switching costs against Temu.com's vendor poaching. GDPR compliance architecture serves as a defensive lever against cross-border entrants lacking EU-established legal representation. For New Entrants and Emerging Players: Eastern Slovakia's secondary urban centers represent the most penetrable entry point for localized distribution investments. B2B procurement digitization among Žilina automotive suppliers offers white-space targeting with lower competitive density than consumer marketplaces. A go-to-market angle anchored in Slovak-language ERP integration addresses legacy system pain points ignored by pan-European platforms. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy Slovak retailers operating captive e-commerce storefronts with underoptimized mobile interfaces. Long-term viability over the next decade hinges on platform aggregation economics displacing standalone merchant economics. The signal to watch is vendor migration velocity from independent sites to marketplace hubs as commission structures stabilize.| Strategic Initiative | Industry Significance |
|---|---|
| PWA Infrastructure Deployment | Browser-based apps bypass Apple and Google commission structures while capturing push-notification engagement. |
| Same-Day Fulfillment Network Expansion | Dense warehouse clusters along the D2 motorway lock in consumer loyalty and raise competitive barriers. |
| EU AI Act Compliance Architecture | Early algorithmic auditing alignment positions Slovak platforms to capture vendor migration from slower competitors. |
| B2B Procurement Platform Launch | Automated reordering systems address manufacturing SME sourcing inefficiencies currently served by legacy channels. |
| Košice Regional Distribution Investment | Eastern Slovakia's underpenetrated logistics networks offer first-mover advantage with lower talent costs than Bratislava. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with e-commerce platform executives, logistics operations directors, and SME procurement managers; and secondary validation against EU Digital Services Act implementation guidance, Slovak trade inspectorate enforcement patterns, and mobile commerce penetration statistics from national telecommunications regulators. Bottom-up vendor revenue estimates triangulated against top-down household expenditure surveys.
Forecast inputs incorporated product category growth differentials, smartphone penetration curves, and logistics infrastructure investment pipelines across the projection horizon. Segmentation modeling captured product type, customer type, sales channel, and payment method dimensions. CAGRs derived from historical transaction volume trajectories adjusted for regulatory compliance cost absorption and platform consolidation dynamics.
Macroeconomic conditions sit as an overlay; deviation in EU cohesion fund disbursement schedules or cross-border VAT enforcement intensity would shift the trajectory. Forecasts reflect assumptions about stable GDPR enforcement patterns and continued EU single market access. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
India E-Commerce Warehousing Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
E-Commerce Electronics Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market
E-Commerce Solutions
Global Live E-Commerce Market
E-Commerce Solutions
Estonia E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
E-Commerce in Nigeria Market
E-Commerce Solutions
Malta E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
UAE Ecommerce Market
E-Commerce Solutions
E-Commerce Logistics Market