
 Ghost Pepper Salt Market | 2026-2036
Ghost Pepper Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Ghost Pepper Salt Market Foresight
Gourmet home cooks is collapsing as the dominant buyer archetype while food manufacturers gain share in bulk procurement. McCormick & Company leverages its national distribution network to sustain shelf presence across mainstream retail channels. Spiceology differentiates through chef-driven formulations and direct-to-consumer engagement. Frontier Co-op anchors the organic and fair-trade segment with cooperative sourcing structures.
Ghost pepper salt combines dried Bhut Jolokia fruit (typically exceeding one million Scoville Heat Units) with crystalline sodium chloride through controlled blending or encapsulation processes, yielding a condiment that delivers intense capsaicin-driven heat with mineral salinity. The product serves commercial kitchens and retail consumers seeking precise, consistent heat application without liquid sauce variability. Granular and flaked product forms command premium positioning due to visual appeal and controlled dissolution rates on proteins. Application demand concentrates in barbecue and gourmet cooking segments where smoke-and-heat flavor layering drives repeat purchase behavior among enthusiasts.
FDA oversees capsaicin content disclosure and facility registration under the Food Safety Modernization Act, while USDA Organic certification governs a growing share of premium positioning. State-level cottage food laws in New Mexico and Texas create variable market access thresholds for artisan producers. Stakeholders must monitor evolving heat-unit labeling standards and regional craft food legislation to anticipate compliance costs and channel eligibility shifts.
Market Dynamics
FDA capsaicin disclosure mandates under the Food Safety Modernization Act are forcing reformulation investments across domestic manufacturing facilities, while specialty food store expansion creates shelf-space competition that rewards differentiated heat-forward positioning.
Growth Catalysts
- Chile-centric culinary tradition:American Southwest cooking culture sustains repeat purchase velocity for heat-forward salts in barbecue and gourmet applications. Regional cuisine preservation drives consumer loyalty.
- Encapsulation technology:Controlled-release capsaicin delivery systems enable precise heat dosing in commercial kitchens. Food manufacturers adopt these systems for batch consistency.
- USDA Organic certification:Premium positioning through certified organic sourcing commands retail price premiums. Cooperative sourcing structures expand certified acreage.
Market Restraints
- Bhut Jolokia supply concentration:Ghost pepper cultivation clusters in Assam and Nagaland regions of India, exposing processors to monsoon volatility and export tariff fluctuations.
- Capsaicin extraction cost structure:Labor-intensive drying and grinding of super-hot varieties requires protective equipment and ventilation infrastructure that elevates unit economics.
- Liquid hot sauce substitution:Sriracha and habanero-based condiments offer lower per-use cost and familiar heat profiles for mainstream consumers.
Strategic Opportunities
- Direct-to-consumer channel expansion:Chef-driven formulations bypass retail slotting fees through subscription and e-commerce platforms. Engagement models build brand equity.
- Smoke-and-heat convergence:Barbecue segment demand for layered flavor profiles creates formulation white space combining ghost pepper with mesquite and hickory notes.
- State cottage food law liberalization:New Mexico and Texas legislative amendments reduce market access thresholds for artisan producers. Home-kitchen commercialization expands supply base.
Industry Challenges
- Scoville Heat Unit standardization:Inconsistent laboratory testing methodologies across facilities create batch-to-batch variability claims. Dispute resolution burdens customer service functions.
- Allergen cross-contamination protocols:FDA facility registration requirements mandate segregated production lines for capsaicin-intensive products. Capital expenditure demands strain artisan operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghost Pepper Salt Market |
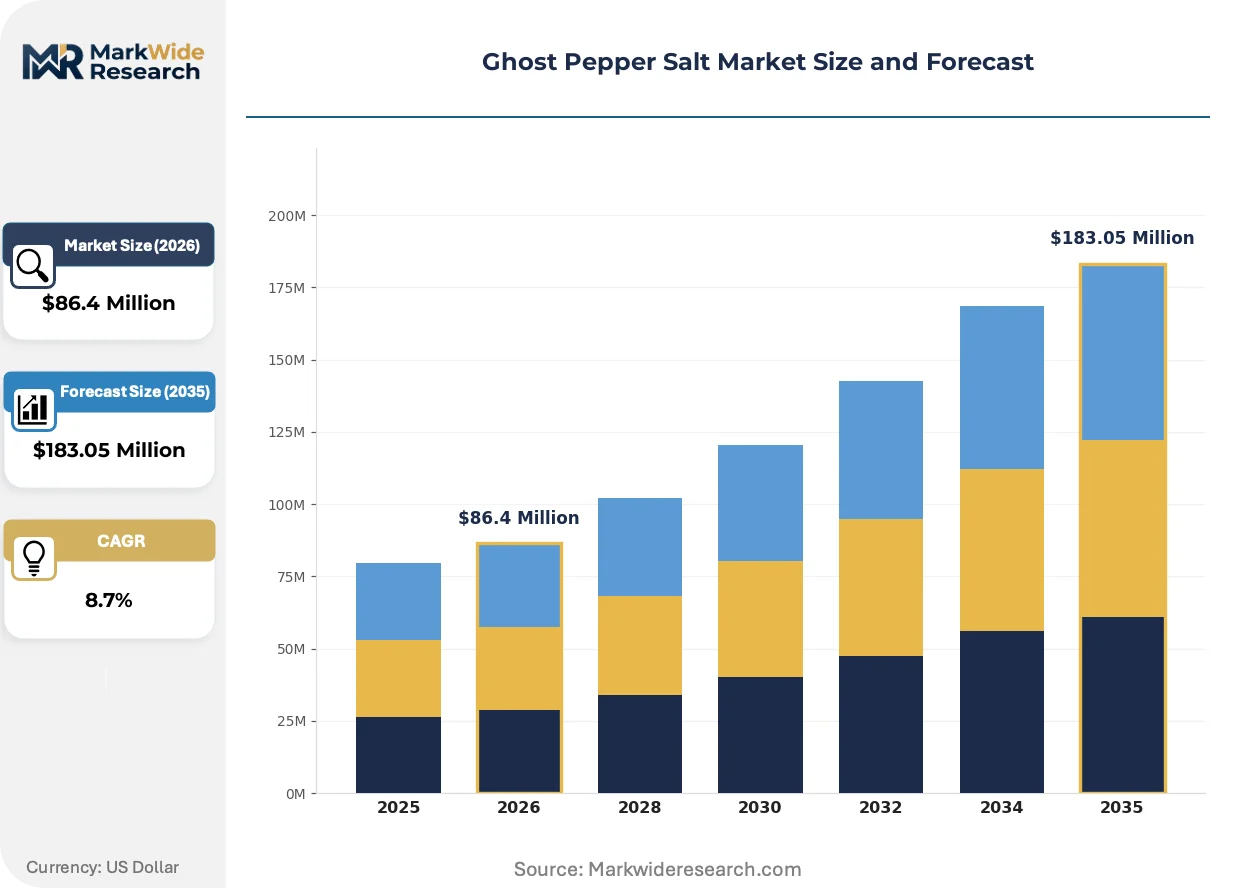
| Market Size in 2026 | $86.4 Million |
| Market Size in 2035 | $183.05 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Granular, Powdered, Flaked, Mixed Blend Application: Food Seasoning, Snack Flavoring, Barbecue, Marinades, Gourmet Cooking Customer Type: Restaurants, Food Manufacturers, Spice Retailers, Specialty Food Stores Packaging Type: Glass Jars, Plastic Containers, Sachets, Bulk Bags |
| Companies Covered | Spiceology, McCormick & Company, Badia Spices, The Spice Lab, Pendery's, World Spice Merchants, Frontier Co-op, Savory Spice Shop, Harry & David, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghost Pepper Salt Market Shifts & Advancements
Product format innovation and regulatory precision are reshaping competitive differentiation, with visual appeal and controlled dissolution becoming technical battlegrounds alongside compliance architecture.
Encapsulated capsaicin microspheres enable timed-release heat delivery that is supplanting traditional dry-blending in premium formulations. Commercial kitchen buyers adopt these systems for protein applications requiring surface browning before heat activation. The technology compresses variability complaints and reduces returns.
FDA draft guidance on capsaicin content quantification is tightening disclosure granularity for super-hot seasoning categories. Manufacturers must invest in third-party laboratory certification to maintain retail channel eligibility. The American Southwest market demonstrates earliest compliance adaptation due to established chile-testing infrastructure.
Visual merchandising now drives granular versus flaked format selection, with crystalline structure becoming a purchase trigger rather than purely functional attribute. Specialty food stores feature transparent packaging that showcases salt geometry. Barbecue enthusiasts in Texas and New Mexico markets demonstrate strongest responsiveness to aesthetic differentiation.
Ghost Pepper Salt Market Segmentation
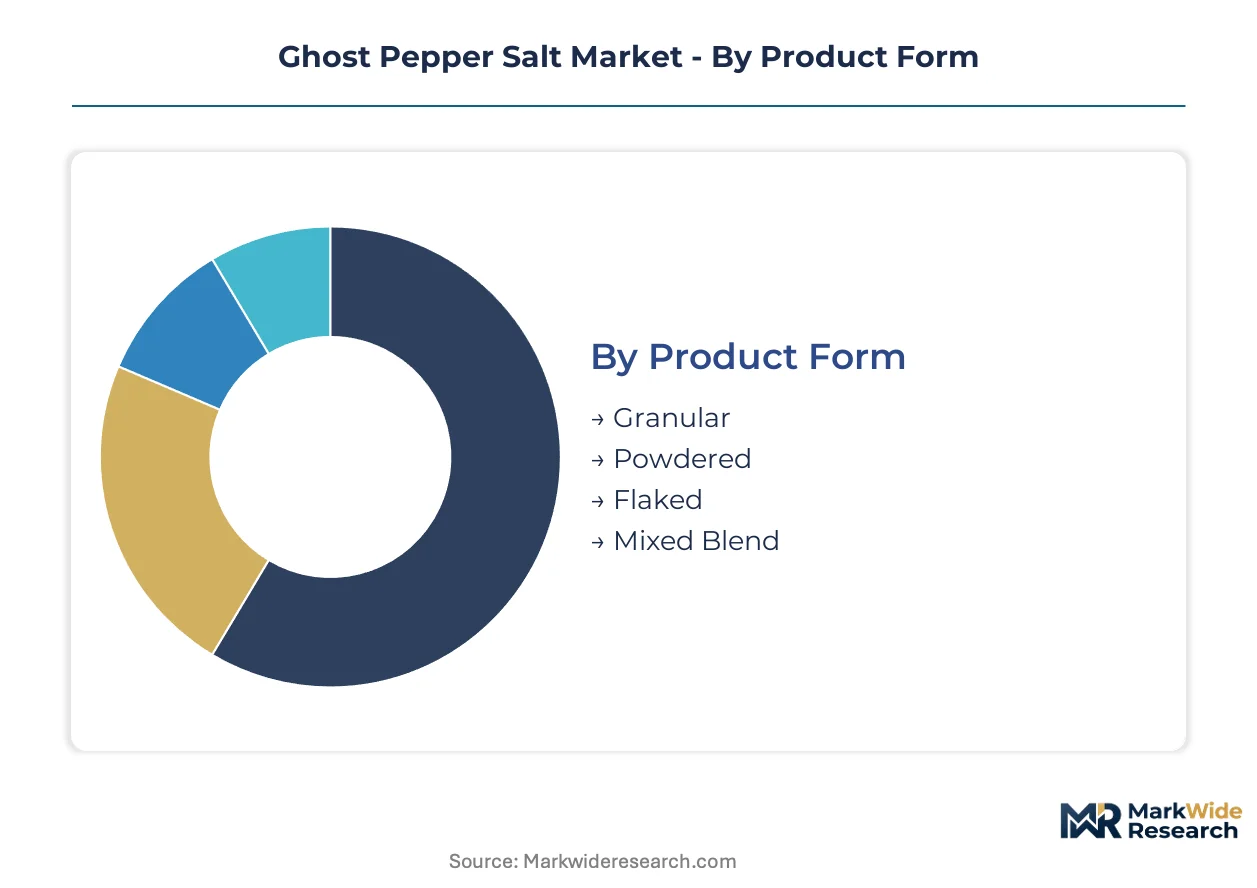
Ghost pepper salt producers navigate distinct demand profiles across product formats and buyer archetypes. Segmentation reveals where premium positioning commands margin versus where volume procurement dominates purchasing patterns.
Product Form:
Granular and flaked variants anchor domestic production lines serving American Southwest barbecue culture, while powdered formats drive export volume to food manufacturers seeking homogeneous blending properties.
- Granular:Crystalline structures exceeding two millimeters deliver controlled dissolution on grilled proteins. Texas and New Mexico pitmasters favor this format for visual texture and predictable heat release during smoke sessions.
- Flaked:Thin, irregular crystals maximize surface contact area for rapid salinity perception. Specialty food stores in Arizona and Colorado stock transparent packaging that showcases geometric structure to enthusiast buyers.
- Powdered:Micronized particles below 500 microns integrate uniformly into dry rub matrices and processed snack seasonings.
- Mixed Blend:Co-formulations with garlic, onion, or smoked paprika target home cooks seeking single-application convenience.
Granular commands the established base. The steepest expansion runs through flaked formats as visual merchandising gains retail influence.
Application:
Cost tier stratification separates commodity snack seasoning from premium culinary positioning, with barbecue applications occupying the high-margin middle ground.
- Barbecue:Smoke-and-heat layering drives repeat purchase among competition pitmasters and backyard enthusiasts. New Mexico's chile-centric culinary tradition sustains year-round demand velocity independent of seasonal grilling patterns.
- Gourmet Cooking:Precision heat application in fine dining kitchens requires consistent Scoville unit certification. FDA capsaicin disclosure mandates elevate formulation standards for this channel.
- Food Seasoning:Tabletop shaker applications compete with liquid hot sauce alternatives on per-use cost metrics.
- Snack Flavoring:Industrial-scale procurement by chip and nut processors prioritizes batch consistency over heat intensity.
- Marinades:Liquid-adjacent applications favor powdered formats for rapid hydration and even distribution.
Barbecue anchors revenue concentration. Gourmet cooking gains share fastest as chef-driven formulations bypass retail slotting fees through direct channels.
Customer Type:
Volume scale distinguishes bulk procurement patterns from artisan retail, with cooperative sourcing structures penetrating the organic-certified tier.
- Food Manufacturers:Encapsulation technology adoption centers on this segment for timed-release heat in processed protein applications. Batch consistency requirements drive third-party laboratory certification investments.
- Specialty Food Stores:Premium assortment expansion creates shelf-space competition rewarding differentiated heat-forward positioning and transparent packaging aesthetics.
- Restaurants:Commercial kitchen procurement emphasizes per-pound cost control and reliable supply continuity.
- Spice Retailers:Blended product margins support private-label development in regional grocery chains.
Food manufacturers dominate volume throughput. Specialty food stores expand most quickly as premium seasoning assortments proliferate.
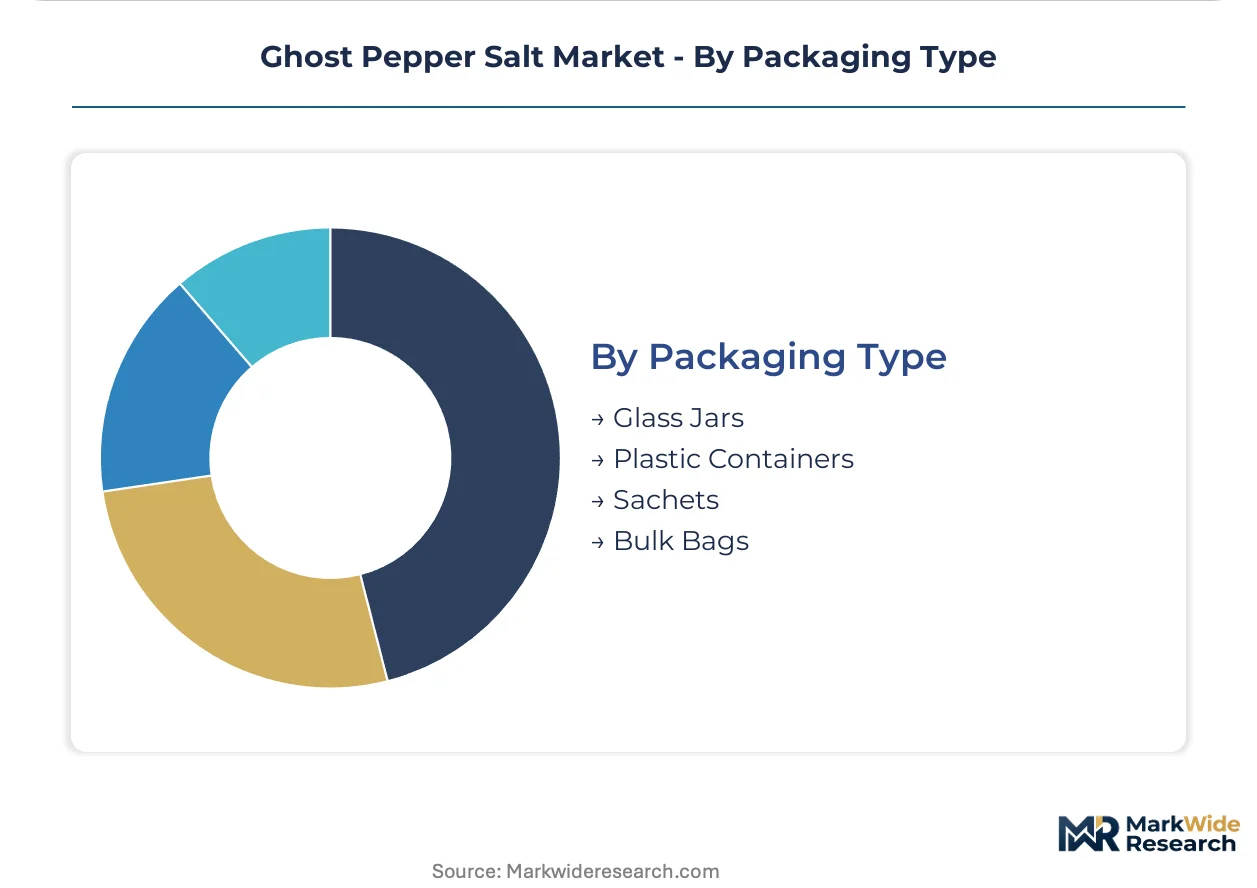
Packaging Type:
Maturity curves separate established glass formats from emerging sustainable alternatives, with bulk logistics determining export market access.
- Glass Jars:Premium positioning in specialty retail leverages visual product showcase and reusability signaling. Arizona and New Mexico consumers demonstrate strongest responsiveness to aesthetic differentiation.
- Bulk Bags:Food service and manufacturing procurement minimizes per-unit packaging cost. Export shipments to commercial kitchens concentrate in this format.
- Plastic Containers:Shatter resistance favors outdoor and barbecue segment distribution.
- Sachets:Single-use hospitality and airline catering applications prioritize portion control.
Glass jars hold the premium tier. Bulk bags climb the fastest as food manufacturer procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bhut Jolokia cultivation clusters in India's Assam and Nagaland regions, creating supply-chain exposure to monsoon volatility and export tariff fluctuations that ripple through downstream salt processing economics.
United States
Chile-centric culinary traditions in Texas and New Mexico sustain repeat purchase velocity for heat-forward salts among barbecue enthusiasts and competition pitmasters. FDA capsaicin disclosure mandates under the Food Safety Modernization Act force reformulation investments across domestic manufacturing facilities. Albuquerque and Austin host the densest concentrations of specialty food retailers featuring transparent packaging aesthetics.
India
Assam's Brahmaputra Valley and Nagaland's hill districts supply the majority of dried Bhut Jolokia fruit entering international seasoning supply chains. FSSAI food safety standards govern export processing facility certifications required for US and EU market access. Guwahati serves as the primary consolidation point for ghost pepper drying, grinding, and initial quality grading before ocean freight.
Germany
Gourmet cooking applications in Berlin and Munich drive demand for precision-dosed super-hot seasonings in fine-dining kitchens. EFSA novel food regulations and REACH chemical safety protocols shape import documentation requirements for capsaicin-intensive products. Hamburg's spice trading houses intermediate between Indian suppliers and European compounders.
United Kingdom
Barbecue culture adoption in Greater London and Manchester creates niche demand for smoke-and-heat layered formulations. Food Standards Agency allergen labeling rules mandate segregated handling declarations for capsaicin products. Bristol and Brighton specialty retailers curate premium seasoning assortments targeting enthusiast home cooks.
Canada
Cross-border culinary influence from the American Southwest extends into Alberta and British Columbia through barbecue competition circuits. Health Canada food additive regulations establish maximum capsaicin thresholds for retail seasoning products. Toronto's specialty food distributors stock ghost pepper salts for restaurant supply and direct-to-consumer channels.
Ghost Pepper Salt Market Competitive Landscape
Concentration sits with diversified spice conglomerates and artisan cooperative structures. The vendor base splits between national distribution networks capable of mainstream retail shelf presence and direct-to-consumer specialists leveraging chef-driven formulations. Three archetypes dominate: legacy seasoning houses with manufacturing scale, craft cooperatives emphasizing organic and fair-trade positioning, and digital-native brands bypassing retail slotting fees through subscription models. Competitive moves center on encapsulation technology licensing and specialty food store shelf-space expansion.
Within the legacy conglomerate tier, McCormick & Company anchors mainstream retail penetration through national distribution infrastructure. Spiceology occupies the chef-driven digital-native position with direct engagement models. Frontier Co-op represents the cooperative organic archetype with fair-trade sourcing structures. These three exemplify the strategic segmentation between scale, authenticity signaling, and mission-driven procurement that defines competitive positioning.
| Leading Market Players |
|---|
| Spiceology |
| McCormick & Company |
| Badia Spices |
| The Spice Lab |
| Pendery's |
| World Spice Merchants |
| Frontier Co-op |
| Savory Spice Shop |
| Harry & David |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Indian Bhut Jolokia consolidators and US seasoning processors lock in supply access and price visibility across monsoon cycles. These arrangements buffer American manufacturers from Assam export tariff fluctuations while embedding quality-grading premiums into contract structures.
Pricing Analysis
FDA capsaicin disclosure mandates under the Food Safety Modernization Act dictate the pricing tier structure across the ghost pepper salt market. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified products from conventional formulations and bulk industrial grades. Price differentiation rests on certification level and volume scale, with artisan producers facing cost compression from encapsulation technology investments. Food manufacturers exhibit lowest price sensitivity due to batch consistency requirements, while tabletop seasoning buyers compete directly with liquid hot sauce on per-use cost metrics.
Supply Chain Analysis
India's Assam and Nagaland regions anchor global Bhut Jolokia supply, producing dried fruit that feeds international seasoning processors. Raw material dependencies center on monsoon-dependent ghost pepper harvests, labor-intensive drying infrastructure, and ocean freight consolidation through Guwahati. Single-source vulnerability concentrates in the Brahmaputra Valley, where flood risk disrupts annual drying cycles. Distribution runs through Hamburg trading houses for European compounders and direct ocean freight to US Gulf Coast ports for domestic processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ghost pepper salt market is recovering from supply-side disruptions as American Southwest barbecue culture sustains repeat purchase velocity through cyclical grilling seasons.
For Market Incumbents: Consolidate procurement relationships with Assam drying cooperatives to secure Bhut Jolokia supply ahead of monsoon volatility. Lock in encapsulation technology licensing to defend against liquid hot sauce substitution in commercial kitchen segments. Expand USDA Organic certified acreage through cooperative sourcing structures to capture premium positioning.
For New Entrants and Emerging Players: Differentiate on chef-driven formulations targeting direct-to-consumer subscription channels, bypassing retail slotting fees that burden established distribution. Target Texas and New Mexico specialty food stores with transparent packaging aesthetics showcasing flaked salt geometry. Pursue smoke-and-heat convergence formulations combining ghost pepper with mesquite notes for barbecue enthusiasts.
For Investors and Strategic Acquirers: Capital is best deployed toward digital-native seasoning brands with established direct engagement models and encapsulation technology capabilities. Long-term viability over the next decade hinges on regulatory compliance infrastructure for FDA capsaicin disclosure mandates. Watch for inflection signals in state cottage food law liberalization across New Mexico and Texas that expand artisan supply base access.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Enables timed-release heat delivery for commercial kitchen batch consistency requirements. |
| USDA Organic Certification Program | Commands retail price premiums through cooperative sourcing structures in premium channels. |
| Direct-to-Consumer Channel Launch | Bypasses specialty food store slotting fees while building brand equity through subscription. |
| Smoke-and-Heat Formulation Extension | Captures barbecue segment demand for layered flavor profiles in Texas and New Mexico. |
| Assam Supply Agreement | Secures Bhut Jolokia access ahead of monsoon volatility and export tariff fluctuations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA facility registration databases, FSSAI export certification records, and specialty food retail audit data. Primary interviews engaged seasoning formulation chemists, specialty food store category buyers, barbecue competition pitmasters, and Indian spice trading house procurement leads. Secondary validation drew from customs trade records, USDA Organic certification directories, and state cottage food legislation filings. Bottom-up demand modeling triangulated against top-down supply chain capacity assessments.
Segmentation dimensions modeled include product form granularity, application category, customer type archetype, and regional regulatory cluster across the analysis window. CAGRs were derived from trend extrapolation of historical volume flows and pricing trajectory analysis. Industry-specific forecast inputs incorporated monsoon pattern variability in Assam and FDA draft guidance evolution on capsaicin quantification standards.
Material uncertainties — monsoon disruption severity, tariff policy shifts, and heat-unit labeling standardization delays — sit outside the modeled envelope. Forecasts reflect assumptions about sustained American Southwest culinary tradition and encapsulation technology adoption curves. Recalibration cycles align with material shifts in FDA regulatory guidance and Indian export policy amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
Savoury Seasoning Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Nutmeg Oil Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Espresso Salt Market