
 Cattle Feeder Panels Market | 2026-2036
Cattle Feeder Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Feeder Panels Market Outlook
Commercial feedlot operators is unwinding the historical dominance of small-scale ranch purchasers in cattle feeder panel procurement. Behlen Manufacturing Company leverages its integrated steel fabrication network to serve large-capacity yard builds across the central United States. Priefert Manufacturing anchors its position through welded-joint engineering and direct-to-ranch distribution infrastructure. Tarter Farm and Ranch Equipment competes on modular portability, appealing to rotational grazing operations that reconfigure handling systems seasonally.
Cattle feeder panels are structural barriers, typically fabricated from galvanized or powder-coated steel tubing in gauges ranging from 14 to 18, designed to contain, direct, and protect livestock during feeding and handling operations. Portable panels dominate replacement demand among rotational operators, while heavy-duty stationary configurations command premium positioning in permanent feedlot infrastructure where animal density and impact loads are highest. Steel remains the baseline material across all product tiers, though aluminum segments gain traction where transport weight reduction justifies cost premiums.
The US Department of Agriculture and OSHA set baseline structural integrity and worker-safety thresholds that panel fabricators must satisfy for commercial deployment. State-level agricultural equipment codes in Texas, Kansas, and Nebraska impose additional load-testing requirements that filter out non-compliant imports. Buyers should monitor evolving corrosion-resistance standards and traceability rules for imported steel substrates, as these will reshape supplier qualification criteria and total cost of ownership calculations across the procurement cycle.
Market Dynamics
Herd consolidation across the North American beef supply chain is concentrating purchasing power among fewer, larger commercial feedlot operators who demand standardized, corrosion-resistant panel systems at volume scale.
Growth Catalysts
- OSHA Worker-Safety Mandates:Federal structural integrity thresholds for livestock handling equipment are compelling feedlot operators to replace aging wooden and untreated metal barriers with engineered steel systems that reduce liability exposure.
- Powder-Coating Technology Diffusion:Advanced electrostatic application methods are extending panel service life beyond fifteen years in high-corrosion environments, justifying premium positioning against galvanized alternatives.
- Texas Panhandle Feedlot Density:The concentration of finishing operations across the High Plains corridor sustains continuous replacement cycles and bulk procurement contracts that anchor manufacturer capacity planning.
Market Restraints
- Steel Price Volatility:Fluctuations in hot-rolled coil pricing transmit directly to panel fabrication costs, compressing margins for distributors serving price-sensitive rotational grazing operations.
- Import Traceability Requirements:USDA documentation rules for foreign-sourced steel substrates are extending supplier qualification timelines and disqualifying low-cost offshore fabricators from commercial feedlot tenders.
- Aluminum Substitution Ceiling:Transport weight advantages of aluminum panels fail to offset cost premiums at animal densities above fifteen head per pen, limiting addressable market penetration.
Strategic Opportunities
- Nebraska-Iowa Expansion Corridor:Emerging large-scale yard construction in the western Corn Belt offers first-mover positioning for panel suppliers with regional fabrication footprints.
- Rotational Grazing Modular Systems:Portable panel configurations with quick-connect hardware are capturing seasonal reconfiguration demand from cow-calf operators transitioning to intensive grazing management.
- USDA Climate-Smart Commodity Grants:Federal cost-share programs for infrastructure improvements are lowering effective purchase prices for qualifying feedlot operators, stimulating upgrade cycles.
Industry Challenges
- Welding Certification Bottlenecks:AWS D1.1 structural welding qualifications required for permanent feedlot installations are constraining installer capacity and extending project timelines.
- Legacy System Integration Friction:Retrofitting powder-coated panels into existing concrete bunks and waterline configurations demands custom fabrication that erodes standard product margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Feeder Panels Market |
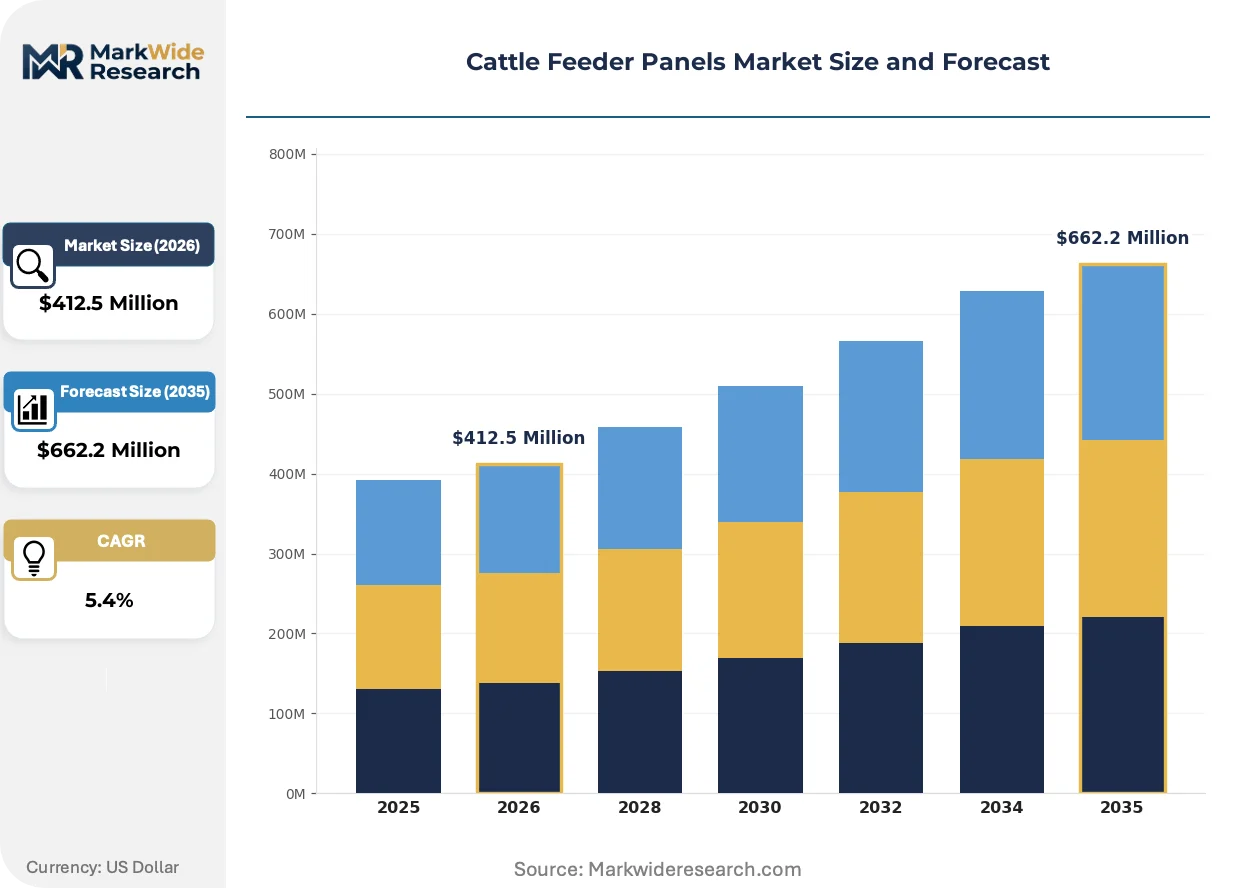
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Panels, Stationary Panels, Heavy-Duty Panels, Adjustable Panels Material: Steel, Plastic, Wood, Aluminum End User: Dairy Farmers, Ranchers, Livestock Handlers, Agricultural Co-ops Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale Distributors |
| Companies Covered | Behlen Manufacturing Company, Priefert Manufacturing, Tarter Farm and Ranch Equipment, Arrowquip, Hi-Hog Farm & Ranch Equipment, Cargill, Powder River, Sioux Steel Company, Lely, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Feeder Panels Market Strategic Shifts
Engineering priorities in cattle feeder panels are pivoting from raw material cost minimization toward lifecycle durability and rapid field assembly, reshaping how fabricators design product portfolios and service delivery models.
Automated pulse-arc welding systems are replacing manual stick welding in panel fabrication, delivering consistent joint penetration across high-volume production runs. Commercial feedlot contractors with multi-thousand-head yard projects are specifying automated-welded panels in tender documents to reduce field failure rates. The fabrication technology base is bifurcating between automated-capable suppliers capturing permanent infrastructure contracts and manual shops relegated to portable replacement demand.
USDA Agricultural Marketing Service rules on steel substrate country-of-origin documentation are tightening import qualification pathways for panel fabricators. Domestic mills with melt-and-pour traceability systems are securing preferred supplier status with publicly traded feedlot operators facing shareholder supply-chain scrutiny. Texas and Nebraska state agricultural equipment codes are incorporating these federal documentation standards into their load-testing certification requirements, accelerating compliance investments across the supplier base.
Direct-to-feedlot contracting is displacing traditional agricultural supply house distribution for large-capacity yard builds. Procurement teams at consolidated operators are negotiating multi-year panel supply agreements with volume pricing and dedicated fabrication slots. This channel restructuring is most visible across the Texas Panhandle and Kansas feedlot corridor, where three operators control over forty percent of regional finishing capacity and have established captive supplier relationships.
Cattle Feeder Panels Market Segmentation
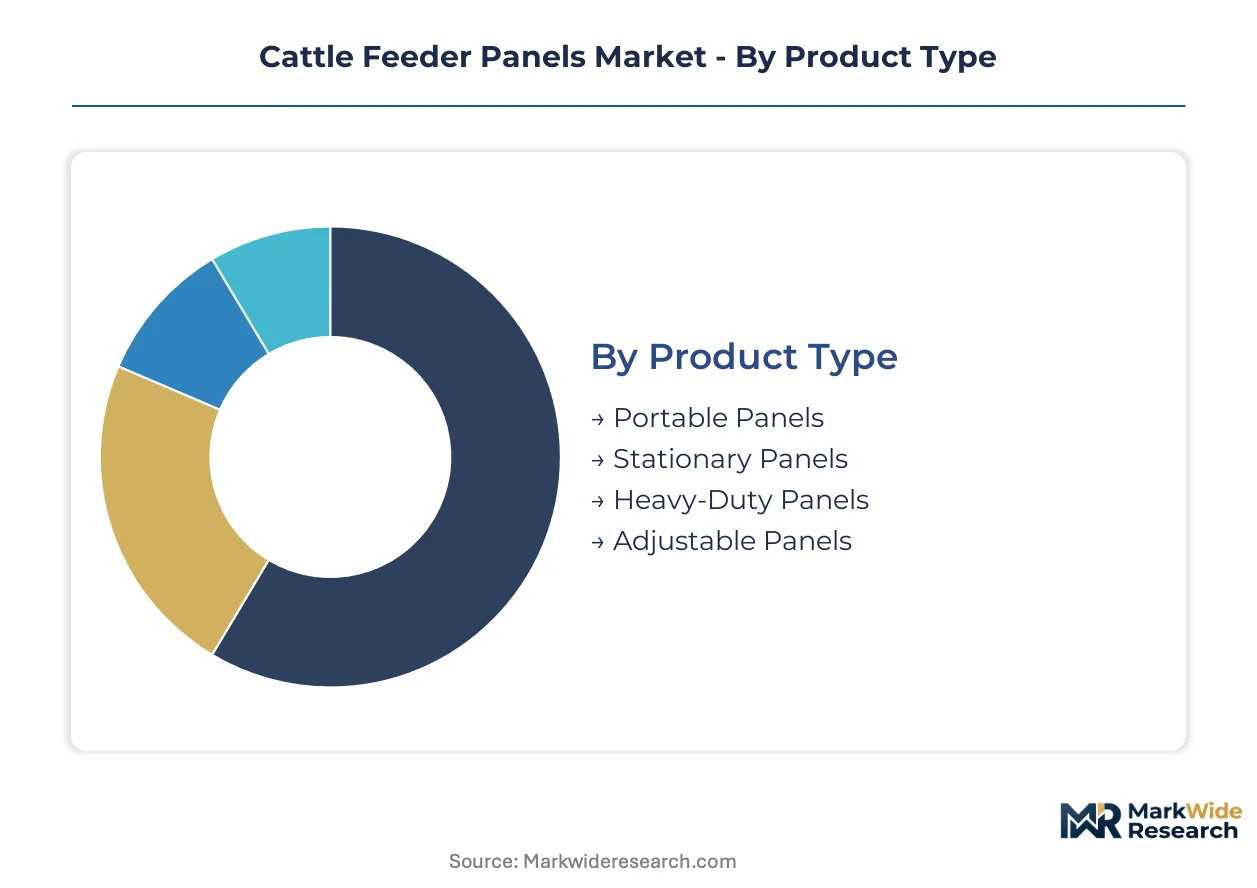
Cattle feeder panel procurement patterns diverge sharply across operational contexts. Understanding these divides reveals where substitution threats concentrate and where supplier lock-in remains strongest.
Product Type:
Portable configurations face the most acute substitution pressure from alternative containment systems, while permanent infrastructure segments defend position through embedded concrete integration.
- Portable Panels:Fabricated from 14-16 gauge galvanized or powder-coated steel tubing with quick-connect pin hardware. Rotational grazing operations across the Texas Panhandle and Nebraska Sandhills drive replacement demand, though aluminum transport trailers and temporary electric fencing erode share in low-density applications.
- Stationary Panels:Welded rigid-frame construction anchored to concrete footings, specified for permanent feedlot infrastructure. OSHA structural integrity mandates and USDA load-testing requirements in Kansas and Nebraska sustain demand despite higher upfront capital requirements versus modular alternatives.
- Heavy-Duty Panels:Reinforced 12-gauge steel with additional cross-bracing for high-impact environments.
- Adjustable Panels:Modular height and width configurations for mixed livestock operations.
Stationary panels anchor the volume base while portable configurations gain share at the steepest rate.
Material:
Cost tier stratification determines competitive dynamics, with premium substrates defending position through lifecycle economics rather than purchase price.
- Steel:Hot-rolled and cold-formed tubular construction remains the baseline across all product tiers. Powder-coated variants command 15-20% premiums over galvanized in commercial feedlot tenders, justified by fifteen-plus year service life in High Plains corrosion environments.
- Aluminum:Extruded 6061-T6 alloy delivers 40% weight reduction for transport-intensive rotational operations. Cost premiums fail to amortize at pen densities above fifteen head, limiting penetration to cow-calf and backgrounding segments.
- Plastic:High-density polyethylene and composite formulations for temporary isolation and veterinary handling.
- Wood:Treated lumber and laminated posts retained in legacy installations and organic-certified operations.
Steel dominates installed value while aluminum expands most quickly in transport-weight-sensitive applications.
End User:
Customer type concentration reshapes procurement patterns as herd consolidation eliminates marginal purchasers.
- Livestock Handlers:Commercial feedlot operators and custom yard contractors with multi-thousand-head capacity. Direct-to-feedlot contracting with volume pricing and dedicated fabrication slots displaces traditional supply house distribution across the Texas Panhandle corridor.
- Ranchers:Cow-calf and stocker operators with seasonal reconfiguration needs. Price sensitivity and credit constraints sustain retail and wholesale distributor relationships despite consolidation pressure.
- Dairy Farmers:Confinement and freestall operations with specialized handling requirements.
- Agricultural Co-ops:Pooled procurement for member operations with standardized specifications.
Livestock handlers anchor the volume base while agricultural co-ops climb the fastest as consolidation drives collective purchasing.
Distribution Channel:
Supply chain configuration determines margin capture, with channel control shifting toward manufacturers in high-volume segments.
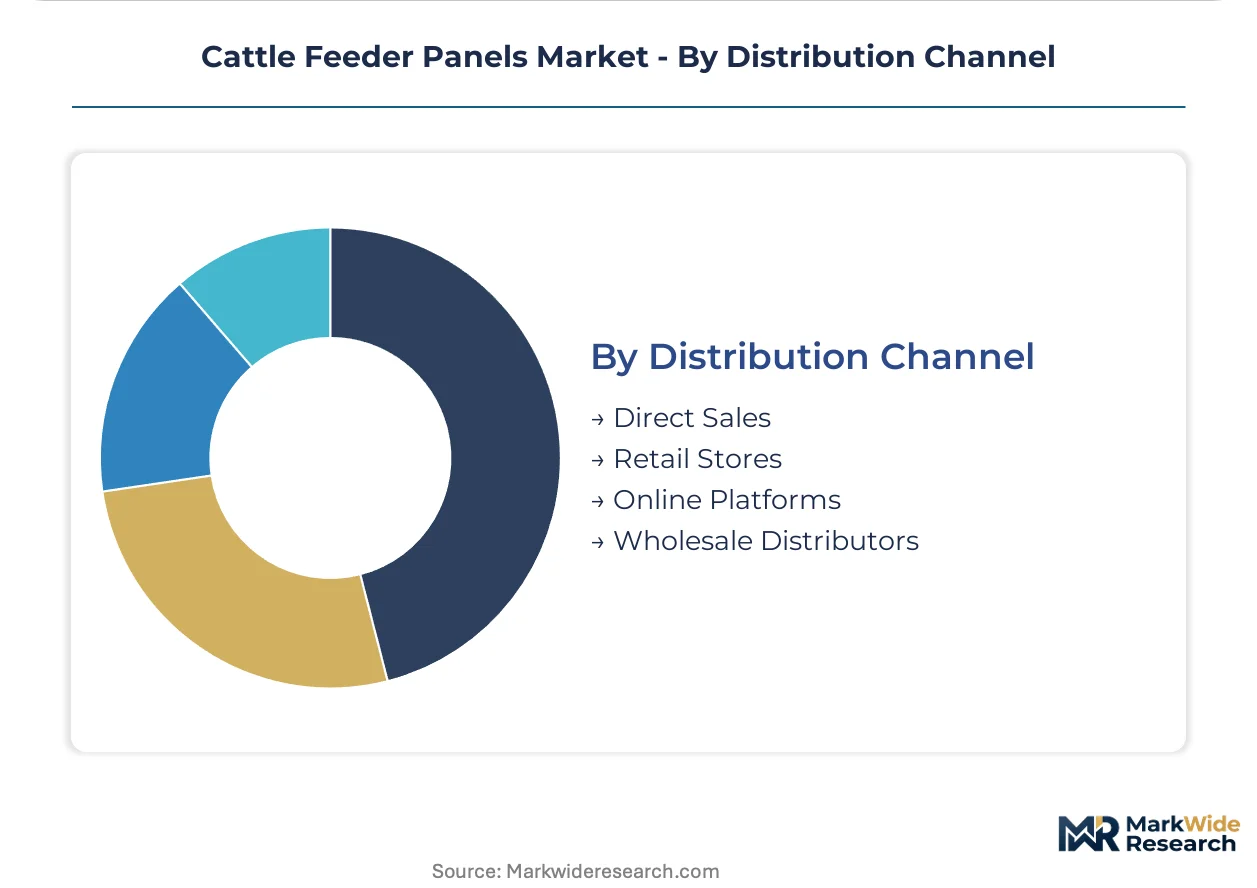
- Direct Sales:Manufacturer-to-feedlot contracting for permanent yard construction. Multi-year supply agreements with captive fabrication slots lock in capacity for consolidated operators controlling forty-plus percent of regional finishing volume.
- Wholesale Distributors:Regional inventory positioning for replacement demand and mid-scale ranch procurement. Steel price volatility compresses margins when hot-rolled coil spikes transmit through to panel pricing.
- Retail Stores:Farm supply and agricultural equipment dealers serving small-scale operators.
- Online Platforms:E-commerce portals with freight logistics for remote ranch locations.
Direct sales anchors the volume base while online platforms expand most quickly in underserved geographic pockets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication capacity for cattle handling equipment clusters in the North American Great Plains, with regulatory compliance requirements in Texas, Kansas, and Nebraska filtering supplier participation. The geographic concentration reflects feedlot density patterns and the regional specialization of agricultural equipment manufacturing.
United States
The Texas Panhandle hosts the densest concentration of commercial feedlot finishing operations, driving continuous panel replacement cycles and bulk procurement contracts. OSHA structural integrity mandates for livestock handling equipment compel operators to upgrade aging wooden barriers to engineered steel systems. Amarillo and surrounding High Plains counties anchor manufacturer capacity planning through multi-year supply agreements with consolidated yard operators.
Canada
Alberta's cattle ranching sector sustains demand for portable panel configurations suited to rotational grazing across prairie provinces. Health Canada's agricultural equipment safety standards align with US OSHA thresholds, enabling cross-border supplier qualification. Calgary-based distributors serve the western Canadian market with inventory positioning for seasonal replacement demand.
Mexico
Northern border states concentrate cattle feeding infrastructure serving export-oriented beef production. Mexican agricultural equipment regulations emphasize structural load-testing for imported steel substrates, extending supplier qualification timelines. Chihuahua and Sonora feedlots source panels through US-based fabricators with established cross-border distribution networks.
Brazil
Mato Grosso and São Paulo states drive cattle handling equipment demand from integrated beef operations expanding finishing capacity. ANVISA's agricultural machinery safety protocols create compliance barriers for non-certified imports. Campinas industrial corridor hosts domestic fabricators serving the Mercosur market with regionally adapted panel specifications.
Australia
Queensland and New South Wales cattle stations demand corrosion-resistant panel systems for harsh rangeland conditions. The TGA's agricultural equipment standards incorporate ISO structural integrity benchmarks for livestock handling infrastructure. Roma and Dubbo serve as procurement hubs for outback operations requiring freight-efficient modular configurations.
Cattle Feeder Panels Market Competitive Environment
Concentration sits with integrated steel fabricators serving large-capacity feedlot construction. The supplier base stratifies between automated-welding-capable manufacturers capturing permanent infrastructure contracts and manual shops relegated to portable replacement segments. Three archetypes dominate: integrated steel processors with captive fabrication networks, specialized agricultural equipment builders with direct distribution infrastructure, and regional metal fabricators competing on price for seasonal ranch demand. Competitive moves center on backward integration into steel substrate sourcing and dedicated fabrication slot contracting with consolidated operators.
Among North American fabricators, Behlen Manufacturing Company exemplifies the integrated steel processing archetype through its captive supply chain control. Priefert Manufacturing occupies a position within specialized agricultural equipment builders emphasizing welded-joint engineering standards. Tarter Farm and Ranch Equipment represents the modular portability segment, serving rotational grazing operators with reconfigurable handling systems. These three anchors illustrate how supplier positioning diverges across operational contexts from permanent feedlot infrastructure to seasonal ranch reconfiguration.
| Leading Market Players |
|---|
| Behlen Manufacturing Company |
| Priefert Manufacturing |
| Tarter Farm and Ranch Equipment |
| Arrowquip |
| Hi-Hog Farm & Ranch Equipment |
| Cargill |
| Powder River |
| Sioux Steel Company |
| Lely |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day fabrication lead times for powder-coated steel panels concentrate pricing power with domestic mills holding melt-and-pour traceability systems. This inventory compression amplifies cost pass-through when hot-rolled coil pricing spikes, while also rewarding feedlot operators who lock multi-year supply agreements with dedicated fabrication slots.
Pricing Analysis
OSHA structural integrity mandates dictate the pricing tier structure across the cattle feeder panel market. Three-tier pricing stratifies across premium powder-coated systems, standard galvanized configurations, and economy-grade untreated steel for replacement demand. Price differentiation hinges on corrosion-resistance certification levels and volume scale in procurement contracts. Cost compression in economy tiers is intensifying because aluminum trailers and temporary electric fencing erode share among rotational operators. Small-scale ranchers exhibit acute price sensitivity, while consolidated commercial feedlot operators absorb premiums for lifecycle durability.
Supply Chain Analysis
Sixty-to-ninety-day fabrication lead times tether procurement planning to steel mill production schedules and AWS D1.1 welding certification bottlenecks. Supply concentrates in the United States, Canada, and Mexico, with Texas Panhandle fabrication clusters serving the densest feedlot corridor. Raw material flows draw from domestic hot-rolled coil producers, powder-coating chemical suppliers, and traceability documentation systems for imported substrates. Tariff exposure on foreign-sourced steel substrates creates qualification delays that filter low-cost offshore fabricators from commercial tenders. Distribution runs through direct manufacturer-to-feedlot contracting for permanent infrastructure, with wholesale distributors capturing replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across rotational grazing applications creates niche opportunities as cow-calf operators abandon fixed infrastructure for modular reconfiguration systems.
For Market Incumbents: Consolidate backward integration into steel substrate sourcing to neutralize hot-rolled coil volatility and USDA import traceability risks. Lock multi-year fabrication slot agreements with consolidated Texas Panhandle operators to defend capacity utilization against emerging Nebraska-Iowa corridor entrants. Certification investment in automated pulse-arc welding systems separates permanent infrastructure suppliers from manual shops relegated to portable replacement segments. For New Entrants and Emerging Players: Quick-connect hardware compatibility gaps in legacy panel systems offer service-layer entry points where incumbents under-serve rotational grazing operators. Target Nebraska Sandhills and western Iowa cow-calf segments with aluminum portable configurations emphasizing transport weight reduction. Pursue agricultural co-op pooled procurement channels as the most penetrable route to volume scale without direct confrontation with established feedlot supplier relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated-welding-capable fabrication footprints as AWS D1.1 certification requirements constrain installer capacity. Five-to-ten-year viability favors suppliers with captive steel sourcing and direct-to-feedlot channel control over distributor-dependent models. Watch Nebraska-Iowa yard construction permit filings as the signal indicating regional demand inflection and first-mover positioning value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Substrate Sourcing | Captive supply from domestic mills with melt-and-pour traceability neutralizes USDA import documentation risks. |
| Automated Pulse-Arc Welding Deployment | Consistent joint penetration satisfies commercial feedlot tender specifications and reduces field failure liability. |
| Direct-to-Feedlot Contracting Expansion | Multi-year supply agreements with dedicated fabrication slots lock in capacity from consolidated operators. |
| Nebraska-Iowa Regional Fabrication Footprint | Proximity to emerging large-scale yard construction lowers freight costs and accelerates project timelines. |
| Quick-Connect Modular System Development | Hardware compatibility with seasonal reconfiguration demand captures rotational grazing upgrade cycles. |
Study Parameters
A standing panel of feedlot procurement directors, agricultural equipment distributors, steel fabrication plant managers, and USDA compliance officers provided ongoing calibration across primary data collection. Secondary validation drew from OSHA enforcement records, USDA Agricultural Marketing Service substrate documentation rules, state-level equipment codes in Texas and Nebraska, and SEC filings from publicly traded beef processors. Bottom-up unit economics from panel fabrication cost structures were triangulated against top-down demand estimates from regional feedlot capacity data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type permanence, material substrate tier, end-user scale concentration, and distribution channel control. CAGRs were derived from replacement cycle frequencies, herd consolidation trajectories, and corrosion-resistance upgrade penetration curves. Forecast inputs incorporated steel price volatility bands, welding certification capacity constraints, and climate-smart infrastructure grant uptake rates.
Forecasts assume regulatory continuity in OSHA structural integrity mandates and USDA steel traceability regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Hog Feeder Market
Livestock Equipment
Hydraulic Squeeze Chute Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
Cattle Supplies Market