
 Hog Feeder Market | 2026-2036
Hog Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Hog Feeder Market Foresight
Market Context
ISO 9001 quality management certification is redrawing competitive boundaries in hog feeder manufacturing, favoring suppliers with documented traceability and repeatability in welded stainless-steel fabrication. Big Dutchman leverages its German engineering heritage and captive control over galvanized feed pan production to command premium positioning in European and North American contract grower markets. Osborne sustains technology leadership through its weight-sorting electronic sow feeder systems, which dominate large-scale commercial farm retrofits. Nedap N.V. competes on sensor integration, embedding RFID and weight-acquisition modules directly into feeder hardware to capture real-time intake data for integrator analytics platforms.
Technical Definition and Structural Segments
A hog feeder is a purpose-built dispensing device designed to deliver measured rations of dry, liquid, or wet-dry feed to swine across growth stages, typically constructed from corrosion-resistant stainless steel or high-density polyethylene with adjustable flow gates and anti-waste lips to minimize feed spillage and optimize feed conversion ratios. Automatic feeders now lead product type segmentation as labor scarcity and precision nutrition protocols push commercial farms toward sensor-enabled, demand-driven dispensing systems that reduce overconsumption and sort animals by intake pattern. Stainless steel dominates material selection in mature markets where biosecurity washdown protocols and decade-long depreciation schedules justify higher first cost, while plastic feeders occupy smallholding and starter-pig niches where capital constraints and lighter duty cycles predominate. Direct sales channels control the largest margin pools in commercial farm procurement, bypassing distributor markups through integrator-level volume contracts and on-site installation services bundled with feeder hardware.
Regulatory Framework and Outlook
The EPA enforces Clean Water Act CAFO permitting that mandates nutrient management plans, directly shaping feeder specification by requiring systems that eliminate feed waste and reduce phosphorus runoff into watersheds. USDA biosecurity guidelines and state-level foreign animal disease preparedness protocols in Iowa, Minnesota, and North Carolina further gate market access by specifying non-porous, sanitizable feeder surfaces and feed delivery segregation between barn zones. Stakeholders must monitor how pending EPA effluent limitation guidelines for swine operations will recalibrate feeder design priorities toward closed-loop liquid feeding and precision additive dosing.
Market Dynamics
Precision feeding automation is restructuring capital deployment across commercial swine operations as labor scarcity and packer sustainability contracts force rapid feeder modernization.
Growth Catalysts
- EPA CAFO Rule Compliance:The EPA's revised Clean Water Act Concentrated Animal Feeding Operation rules mandate nutrient management plans that eliminate feed waste, compelling feeder upgrades across Iowa and North Carolina integrator networks.
- RFID Sensor Integration:Real-time intake monitoring through embedded weight-acquisition modules is enabling data-driven ration adjustments that optimize feed conversion ratios in large-scale sow operations.
- Upper Midwest Consolidation:Integrator consolidation of sow barns across Minnesota and Illinois is driving retrofit demand for automated dry and wet-dry feeder lines in existing facilities.
Market Restraints
- Stainless Steel Input Volatility:Fluctuations in nickel and chromium prices directly compress margins for welded fabrication, forcing manufacturers to absorb cost spikes or risk contract losses.
- Galvanized Component Concentration:Captive supply of corrosion-resistant feed pans remains concentrated among vertically integrated German suppliers, limiting sourcing flexibility for North American producers.
- Biosecurity Surface Mandates:USDA non-porous sanitization requirements eliminate lower-cost plastic alternatives from commercial farm procurement, raising minimum viable product specifications.
Strategic Opportunities
- Closed-Loop Liquid Feeding:Pending EPA effluent limitation guidelines for swine operations will recalibrate design priorities toward precision additive dosing systems that capture nutrient runoff.
- Wet-Dry Convergence:Integration of liquid feed delivery with dry ration dispensing is creating hybrid system demand among contract growers seeking single-source equipment suppliers.
- Direct Channel Expansion:Volume contracts bundled with on-site installation services are bypassing traditional distributor markups and capturing integrator-level margin pools.
Industry Challenges
- Welding Certification Timelines:ISO 9001 traceability documentation for stainless-steel fabrication extends qualification periods, delaying supplier onboarding for urgent retrofit projects.
- Legacy Barn Integration:Retrofitting automated feeder lines into 1990s-era farrowing facilities requires structural modifications that compound capital intensity and extend payback periods.
- Sensor Calibration Expertise:Shortage of technicians capable of configuring RFID and weight-acquisition modules is constraining deployment velocity for precision feeding installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hog Feeder Market |
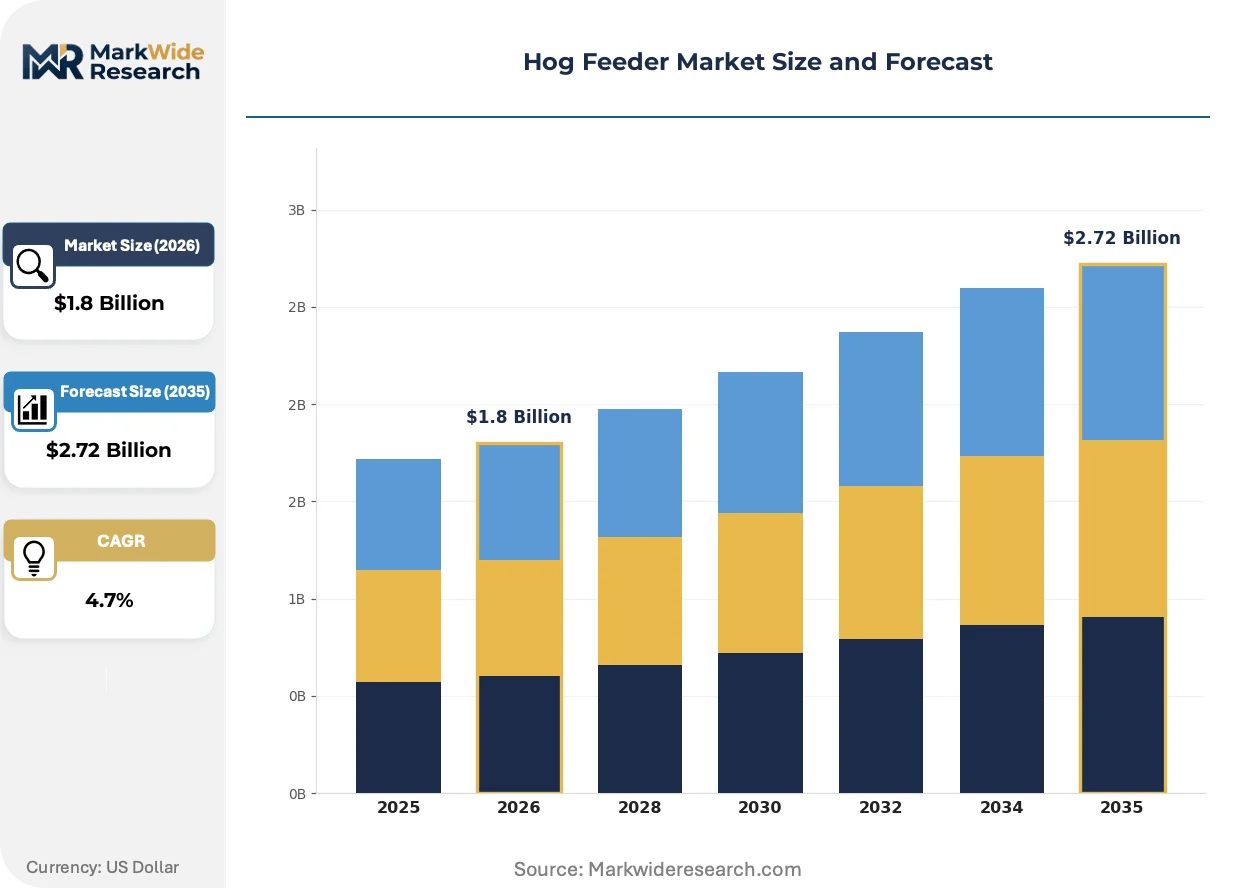
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Feeders, Manual Feeders, Dry Feeders, Liquid Feeders Material: Plastic, Metal, Stainless Steel, Fiberglass End User: Commercial Farms, Smallholdings, Research Institutions, Livestock Organizations Distribution Channel: Online Retail, Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Big Dutchman, Chore-Time, Osborne, Nedap N.V., CTB, Roxell, JYGA Technologies, Big Herdsman, YingZi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hog Feeder Market Shifts & Advancements
Feeder hardware is converging with data infrastructure as real-time intake analytics become prerequisites for packer contract eligibility and operational insurance underwriting.
Electronic sow feeders equipped with individual animal identification and automated sort gates are supplanting manual feeding protocols in commercial farrowing operations. Large-scale integrators in Iowa and North Carolina are deploying these systems at accelerated cadences to meet packer data transparency requirements. The technology is supplanting labor-dependent batch feeding and compressing the competitive window for suppliers lacking embedded sensor capabilities.
REACH chemical compliance and the EU Green Deal's farm-to-fork sustainability targets are reshaping material specifications for exported feeder components. European contract growers now demand documented carbon footprints for galvanized steel and polymer feed pans, forcing manufacturers to requalify supply chains. Stainless-steel fabricators with ISO 14001 environmental management certification are capturing preferential placement in cross-border procurement.
Integrator-level volume contracting is consolidating purchasing authority away from independent contract growers toward centralized procurement departments. Direct sales channels with bundled installation and calibration services are displacing traditional agricultural distributor networks. This concentration is most visible across the Upper Midwest, where three large integrators now control feeder specification for the majority of new barn construction and retrofit activity.
Hog Feeder Market Segmentation
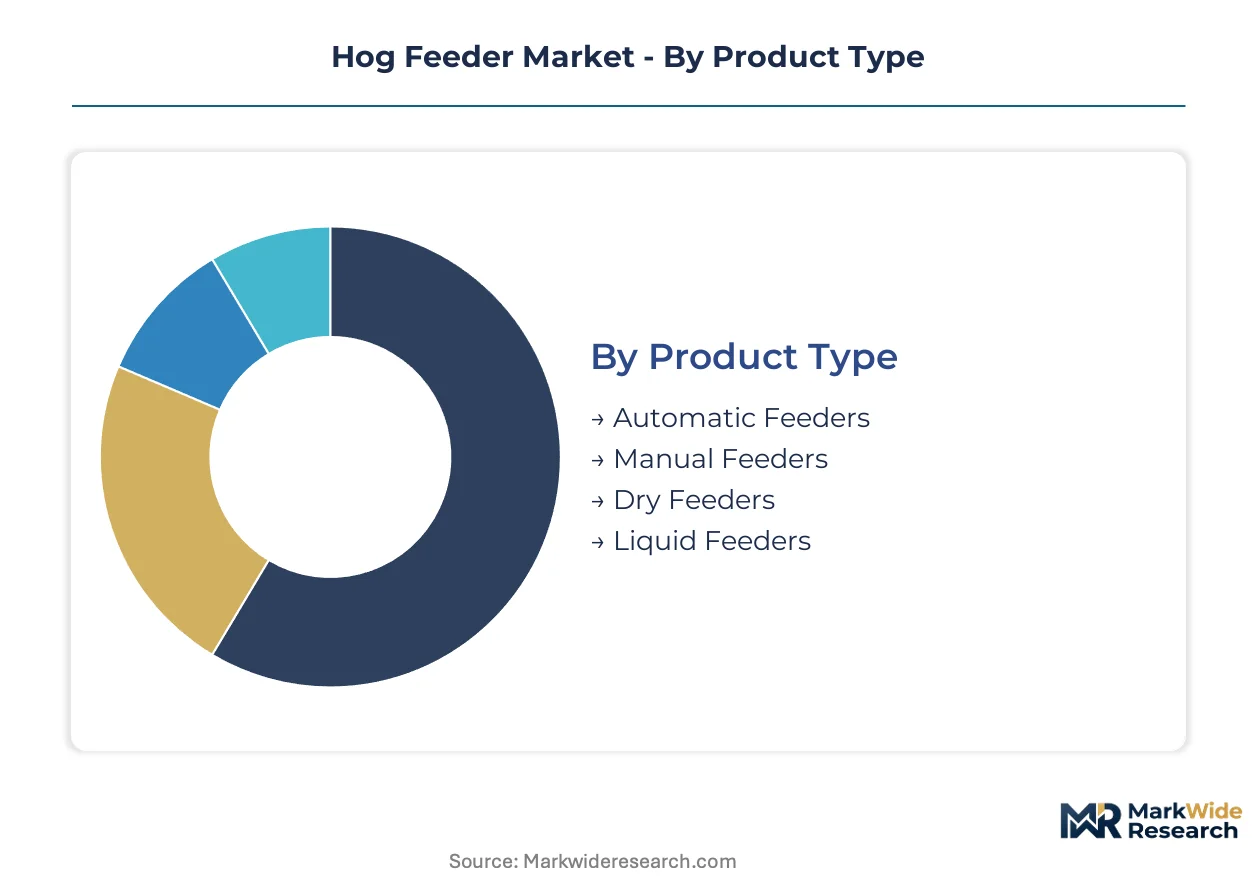
Hog feeder segmentation reveals how capital intensity, biosecurity mandates, and labor economics partition procurement behavior across farm scales. Material selection and distribution channel access function as gatekeepers that separate integrator-level volume buyers from price-sensitive smallholders.
Product Type:
Automatic feeder systems face substitution pressure from retrofitted manual systems in legacy barns where structural modifications prove cost-prohibitive.
- Automatic Feeders:Sensor-enabled dispensing systems integrate RFID and weight-acquisition modules for real-time intake monitoring. Demand concentrates in Iowa and North Carolina integrator networks where packer sustainability contracts mandate data transparency.
- Dry Feeders:Gravity-fed dispensing systems with adjustable flow gates dominate starter-pig and grower operations. Commercial farms across Minnesota and Illinois favor these for decade-long depreciation cycles and simplified washdown protocols.
- Manual Feeders:Labor-dependent batch feeding systems retain foothold in smallholdings with limited capital budgets and low animal counts.
- Liquid Feeders:Closed-loop nutrient delivery systems address pending EPA effluent guidelines by capturing phosphorus runoff before watershed discharge.
Automatic feeders retain volume leadership; liquid feeders hold the steepest expansion curve.
Material:
Cost tier stratification separates premium stainless-steel fabrication from economy plastic alternatives based on washdown frequency and biosecurity protocol intensity.
- Stainless Steel:Welded fabrication with documented ISO 9001 traceability supports repeated caustic washdowns without corrosion. Upper Midwest integrators specify this material for farrowing facilities under USDA foreign animal disease preparedness protocols.
- Plastic:High-density polyethylene construction serves starter-pig niches and smallholdings where capital constraints outweigh durability requirements.
- Metal:Galvanized steel feed pans with corrosion-resistant coating occupy mid-tier contract grower procurement.
- Fiberglass:Lightweight composite construction targets mobile feeding applications and temporary barn installations.
Stainless steel commands the premium tier; plastic alternatives capture the widest smallholding penetration.
End User:
Customer type determines specification rigor, with commercial farms driving embedded sensor adoption while smallholdings prioritize first-cost minimization.
- Commercial Farms:Large-scale integrators in Iowa and North Carolina deploy precision feeding systems to meet packer contract eligibility. These buyers specify automated dry and wet-dry feeder lines with bundled installation and calibration services.
- Smallholdings:Independent operators with limited animal counts favor manual and plastic feeder systems available through agricultural distributor networks.
- Research Institutions:Controlled environment facilities require documented feed conversion accuracy for academic and pharmaceutical studies.
- Livestock Organizations:Cooperative buying groups aggregate demand across member farms to access volume pricing tiers.
Commercial farms drive technology adoption; smallholdings represent the largest addressable unit count.
Distribution Channel:
Supply concentration among integrator procurement departments is displacing traditional distributor networks through direct manufacturer relationships.
- Direct Sales:Volume contracts with on-site installation and technician calibration bypass distributor markups. Three large Upper Midwest integrators now control specification authority for majority retrofit and new construction activity.
- Distributors:Agricultural supply networks retain relevance in smallholding and independent contract grower segments where fragmented demand resists direct manufacturer engagement.
- Online Retail:E-commerce platforms serve replacement part procurement and entry-level plastic feeder sales with limited technical support.
- Specialty Stores:Regional agricultural equipment dealers provide localized inventory and emergency replacement services.
Direct sales capture integrator margin pools; distributors defend smallholding access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US EPA CAFO enforcement and EU Green Deal sustainability mandates are redrawing procurement geography for precision feeding equipment, concentrating demand in jurisdictions with binding nutrient management obligations.
United States
Iowa and North Carolina integrators are retrofitting sow barns with automated wet-dry feeder lines to satisfy packer sustainability contracts and EPA Clean Water Act permits. The USDA's foreign animal disease preparedness protocols mandate non-porous sanitizable surfaces in Upper Midwest farrowing facilities. Minnesota integrators are consolidating procurement authority through direct manufacturer contracts that bundle installation with hardware.
Germany
German engineering heritage in galvanized fabrication anchors European supply for corrosion-resistant feed pan production. REACH chemical compliance and the EU Green Deal's farm-to-fork targets now require documented carbon footprints for exported components. Bavarian fabricators with ISO 14001 certification are capturing preferential placement in cross-border procurement.
China
Domestic integrators in Sichuan and Shandong are scaling automated dry feeder deployments to meet national food security targets and rural labor shortage pressures. The Ministry of Ecology and Environment's dual carbon goals are tightening effluent standards for concentrated swine operations. Yangtze River Delta equipment manufacturers are backward integrating into stainless-steel component production.
Brazil
Commercial farms in Mato Grosso and Paraná are importing European precision feeding systems to satisfy EU export market biosecurity requirements. ANVISA veterinary oversight and state-level environmental licensing are converging on washdown-capable equipment specifications. São Paulo-based integrators are piloting RFID-enabled sow feeders for contract grower networks.
Netherlands
Dutch sensor specialists are embedding weight-acquisition modules into feeder hardware for real-time intake analytics demanded by Northern European integrators. The EU's CSRD reporting requirements and national nitrogen emission caps are accelerating wet-dry system adoption. Eindhoven-region technology clusters are supplying RFID integration for German and Danish barn retrofits.
Hog Feeder Market Competitive Landscape
Player mix skews toward vertically integrated European fabricators and sensor-technology specialists, with mid-tier metalworkers defending regional contract grower relationships. German and Chinese manufacturers anchor supply for corrosion-resistant components, while Dutch and US firms dominate data-integrated feeding systems. Competitive positioning hardens around ISO 9001 welding certification timelines and captive galvanizing capacity. Consolidation pressure is mounting through integrator-level volume contracting and direct channel expansion.
Among German engineering-led fabricators, Big Dutchman anchors premium positioning through captive control over galvanized feed pan production. Osborne and Nedap N.V. occupy the precision-technology tier, representing divergent approaches to sensor integration and data capture for commercial sow operations. Chinese fabricators including Big Herdsman exemplify scale-driven competition for domestic and emerging market procurement.
| Leading Market Players |
|---|
| Big Dutchman |
| Chore-Time |
| Osborne |
| Nedap N.V. |
| CTB |
| Roxell |
| JYGA Technologies |
| Big Herdsman |
| YingZi |
| Others |
Supply & Pricing Matrix
Sixty-day galvanized steel feed pan lead times from German fabricators concentrate pricing power among vertically integrated suppliers with captive corrosion-coating capacity. Iowa integrators facing urgent EPA CAFO retrofit deadlines absorb premium markups rather than risk installation delays that void packer sustainability contracts.
Pricing Analysis
Certification level creates the primary spread, with ISO 9001-traceable stainless-steel fabrication commanding premium positioning against uncertified alternatives. Three-tier pricing structure separates premium sensor-integrated systems from standard dry feeders and economy plastic manual units. Cost compression in mid-tier galvanized equipment is intensifying because nickel price volatility forces manufacturers to absorb input spikes or lose integrator volume contracts. Smallholdings remain most price-sensitive, deferring replacement cycles until failure, while commercial farms prioritize total cost of ownership over first cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes extend component delivery windows for RFID modules sourced from Dutch sensor specialists. Manufacturing gravity centers on Germany for galvanized feed pan production, China for stainless-steel component fabrication, and the Netherlands for weight-acquisition electronics. The supply chain rests on nickel and chromium feedstock from Indonesian and South African mining operations. Single-source vulnerability concentrates in German captive galvanizing capacity. Distribution runs through direct manufacturer relationships with Upper Midwest integrators, bypassing traditional agricultural distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision feeding automation sits in early-cycle expansion as EPA effluent guidelines and packer data transparency requirements force rapid retrofit adoption across Iowa and North Carolina integrator networks.
For Market Incumbents: Compound technology leadership through backward integration into sensor module production, reducing dependency on Dutch RFID suppliers. Deepen ISO 14001 environmental certification to capture EU Green Deal procurement preferences. Defend against Chinese scale competitors by embedding predictive analytics software into feeder hardware, creating switching costs that raw hardware rivals cannot replicate.
For New Entrants and Emerging Players: Differentiate on wet-dry hybrid system integration, where incumbent product lines remain bifurcated between liquid and dry specialists. Target smallholding segments in Brazil and Eastern Europe where price-sensitive demand resists direct manufacturer engagement. Pursue distributor partnership models that bundle installation training with hardware sales, avoiding capital-intensive field service buildout.
For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural equipment conglomerates with underoptimized feeder divisions lacking sensor integration capabilities. Long-term viability favors precision-feeding specialists with software recurring revenue streams over pure hardware fabricators. Watch for inflection when EPA effluent limitation guidelines trigger mandatory closed-loop liquid feeding upgrades across Minnesota and Illinois operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Module Backward Integration | Captive RFID production insulates margins from Dutch supplier concentration and accelerates deployment timelines for urgent retrofit projects. |
| ISO 14001 Environmental Certification | Documented carbon footprint compliance unlocks preferential placement in EU Green Deal procurement and REACH-compliant export channels. |
| Wet-Dry System Convergence | Hybrid liquid-dry delivery addresses pending EPA effluent guidelines while consolidating contract grower procurement onto single-source suppliers. |
| Direct Channel Expansion | Volume contracts bundled with on-site calibration capture integrator-level margin pools and displace traditional agricultural distributor networks. |
| Predictive Analytics Software Embedding | Real-time intake data platforms create switching costs that defend against Chinese hardware competitors and support recurring revenue models. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial farm operations managers, integrator procurement directors, feeder manufacturing plant engineers, and agricultural equipment distributor principals. Secondary validation drew from EPA CAFO permitting databases, USDA biosecurity guideline publications, SEC filings of publicly listed agricultural equipment manufacturers, and customs trade records for stainless-steel component imports. Bottom-up unit deployment estimates across Iowa, North Carolina, Minnesota, and Illinois operations were triangulated against top-down market value reconstruction.
Across the analysis window, projections model feeder unit demand by product type, material specification, and end-user scale, with cross-segment validation against integrator capital expenditure disclosures. CAGRs derive from regression analysis of historical replacement cycles, regulatory compliance deadlines, and packer contract adoption curves. Industry-specific inputs include EPA effluent guideline implementation timelines, nickel price volatility bands, and RFID sensor cost decline trajectories.
Forecasts assume regulatory continuity in EPA CAFO enforcement and EU REACH compliance regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
Cattle Feeder Panels Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Robotics Milking Systems Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Horse Bunk Feeder Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Russia Horse Riding Equipment Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Sheep Creep Feeder Market
Livestock Equipment
Horse Bell Boots Market
Livestock Equipment
Animal Feed Mixer Market