
 Global Smart Lecture Capture System Market | 2026-2036
Global Smart Lecture Capture System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Lecture Capture System Market Foresight
ISO/IEC 27001 certification for information security management is bifurcating the competitive landscape into qualified enterprise vendors and uncertified regional suppliers. Panopto leverages its cloud-native architecture to sustain multi-tenant deployments across large research universities. Kaltura anchors its position through deep Learning Management System integration that controls institutional switching costs. Sonic Foundry specializes in appliance-based hardware capture systems that dominate legacy campus infrastructure retrofits.
Smart lecture capture systems combine audio-visual recording hardware, real-time streaming software, and AI-driven indexing engines to produce searchable, timestamped educational content from live instruction. These systems typically encode video at 1080p resolution with synchronized slide capture and automated speech-to-text transcription for accessibility compliance. Software platforms command the dominant margin pool as recurring SaaS contracts displace one-time hardware sales across higher education buyers. Artificial Intelligence integration represents the fastest-expanding technology segment as automated chaptering and sentiment analysis tools displace manual post-production workflows. Hardware Devices remain mature with pricing pressure from commoditized camera and microphone components.
The U.S. Department of Education enforces Section 508 accessibility standards that mandate closed captioning and audio description capabilities in federally funded educational technology procurements. The EU AI Act imposes risk-classification requirements on automated transcription and student analytics features, forcing European vendors to redesign algorithmic transparency controls. China's GB standards for educational informatization specify interoperability protocols that constrain foreign platform architectures. Stakeholders must monitor evolving procurement qualification criteria as accessibility mandates and algorithmic accountability rules expand across jurisdictions.
Market Dynamics
AI-enabled transcription engines are compressing post-production timelines from days to minutes, forcing vendors to restructure service delivery models around real-time indexing rather than batch processing workflows.
Growth Catalysts
- Section 508 Mandates:U.S. Department of Education accessibility requirements for closed captioning and audio description are accelerating replacement cycles across federally funded institutions.
- Hybrid Learning Infrastructure:Universities are consolidating dispersed AV investments into unified capture platforms that support simultaneous in-person and remote instruction.
- EU AI Act Risk Classification:Automated student analytics features face new algorithmic transparency requirements that favor vendors with pre-built compliance architectures.
Market Restraints
- Semiconductor Component Volatility:Camera sensor and encoder chip supply from East Asian foundries creates hardware delivery uncertainty for appliance-based systems.
- ISO/IEC 27001 Certification Barriers:Information security management certification costs and audit timelines exclude smaller regional software vendors from enterprise procurement shortlists.
- Learning Management System Lock-in:Deep integration with incumbent platforms like Canvas and Blackboard raises switching costs that slow platform migration decisions.
Strategic Opportunities
- India Higher Education Digitization:National Education Policy implementation is driving smart classroom investments across state universities with limited legacy infrastructure to displace.
- K-12 District Expansion:Secondary education procurement remains underpenetrated relative to higher education, with simpler deployment requirements and faster decision cycles.
- Speech-to-Text and Sentiment Analysis Convergence:Combined AI engines enable real-time engagement scoring that differentiates premium platform tiers.
Industry Challenges
- Multimodal AI Engineering Talent:Scarce expertise in audio-visual synchronization and natural language processing constrains product development velocity.
- Legacy Hardware Retrofit Complexity:Aging campus AV infrastructure requires custom integration work that erodes margin on appliance-based deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Lecture Capture System Market |
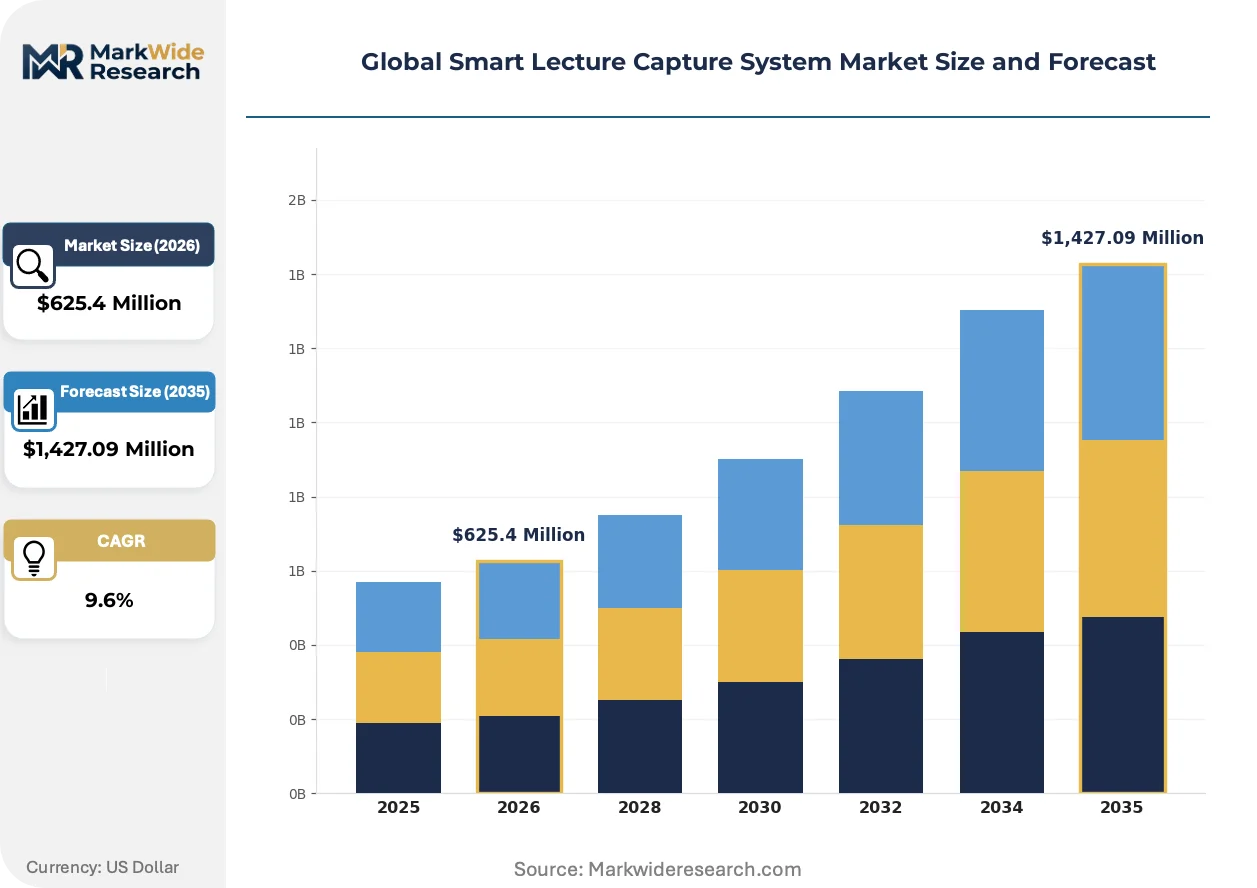
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,427.09 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Devices, Software Platforms, Cloud Solutions, Digital Recorders, Control Consoles Technology: Artificial Intelligence, Video Analytics, Speech Recognition, Learning Management System Integration, Augmented Reality Application: Higher Education, Corporate Training, Continuing Education, K-12 Education, Professional Certification End User: Universities, Training Institutes, E-Learning Providers, Seminar Organizers, Research Centers |
| Companies Covered | Panopto, Kaltura, Echo360, YuJa, Sonic Foundry, TechSmith, Cisco Systems, Crestron Electronics, Haivision Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Lecture Capture System Market Shifts & Advancements
Real-time AI processing at the network edge is eliminating latency barriers that previously forced trade-offs between capture quality and immediacy, enabling new use cases in live remote instruction.
Edge-based inference engines running on capture appliances are displacing cloud-only transcription architectures that introduced unacceptable delays for live captioning. Large research universities in the United States are piloting these systems for real-time accessibility compliance. The shift is compressing vendor R&D roadmaps toward on-device AI acceleration rather than centralized processing.
The EU AI Act's risk-classification framework for educational analytics is forcing algorithmic transparency disclosures that exceed previous GDPR documentation requirements. Vendors serving European higher education must now maintain technical files explaining training data provenance and bias testing protocols. This regulatory layer is advantaging established platforms with dedicated compliance functions over newer entrants.
Subscription-based SaaS contracts are displacing perpetual licensing with maintenance agreements that dominated pre-2020 procurement. Chief information officers at U.S. public universities now prioritize predictable operational expenditure over capital budget requests. This preference shift is visible most acutely in California and Texas systems where centralized IT governance has accelerated standardization around cloud-native platforms.
Global Smart Lecture Capture System Market Segmentation
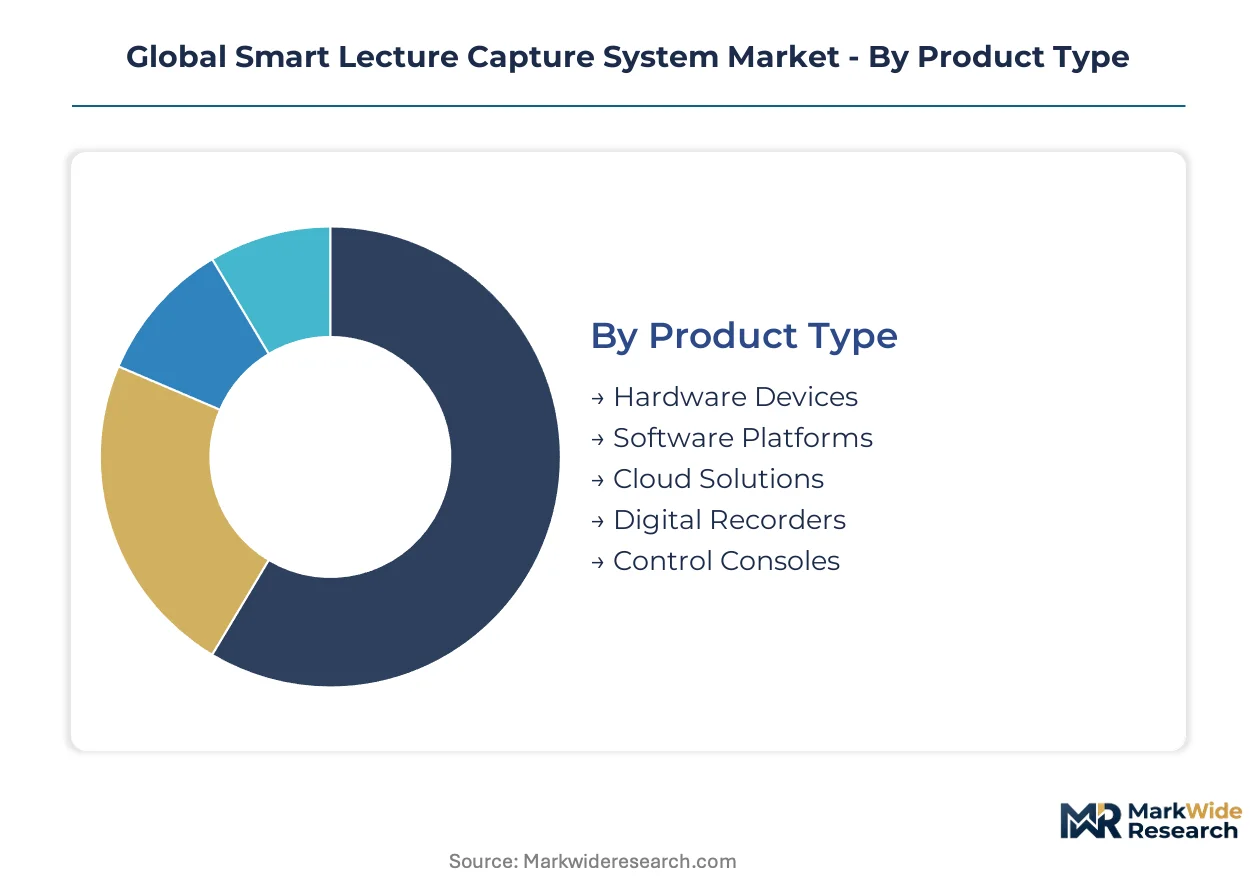
Smart lecture capture systems serve divergent infrastructure maturity levels across education and enterprise verticals. Procurement patterns split between institutions seeking turnkey hardware deployments and those prioritizing scalable software architectures. Understanding these segment boundaries clarifies where vendors must configure specialized go-to-market approaches.
Product Type:
Hardware Devices and Software Platforms anchor domestic procurement in North American and European markets, while Cloud Solutions and Digital Recorders flow disproportionately to export-led deployments across Asia-Pacific and Latin America.
- Hardware Devices:Appliance-based capture systems integrate dedicated encoders, camera arrays, and audio processing units for on-premise deployment. Large research universities in the United States favor these systems for legacy AV infrastructure retrofits where network bandwidth constraints limit cloud dependency. Semiconductor supply volatility from East Asian foundries creates delivery uncertainty for vendors dependent on commoditized sensor components.
- Software Platforms:Cloud-native architectures deliver multi-tenant SaaS contracts with recurring revenue models that displace perpetual licensing. Chief information officers at U.S. public universities prioritize these platforms for predictable operational expenditure over capital budget requests. Deep Learning Management System integration raises institutional switching costs and slows competitive displacement.
- Cloud Solutions:Fully managed services eliminate on-premise maintenance burdens for mid-tier institutions with limited IT staffing.
- Digital Recorders:Portable capture units serve seminar organizers and mobile training environments requiring rapid deployment flexibility.
- Control Consoles:Centralized management interfaces unify dispersed capture endpoints across multi-building campus deployments.
Software Platforms hold the largest share; momentum sits with Cloud Solutions.
Technology:
Cost tier stratification separates premium AI-enabled transcription engines from standardized video analytics packages, with Speech Recognition and LMS Integration occupying mid-market positioning.
- Artificial Intelligence:Automated chaptering, sentiment analysis, and real-time engagement scoring compress post-production timelines from days to minutes. Edge-based inference engines on capture appliances are displacing cloud-only architectures that introduced unacceptable latency for live captioning. EU AI Act risk-classification requirements favor vendors with pre-built algorithmic transparency controls.
- Video Analytics:Computer vision algorithms track attendance patterns, gaze direction, and classroom movement to generate engagement metrics. Corporate training divisions leverage these tools for compliance documentation and instructor effectiveness scoring. Privacy regulations in Germany and France constrain biometric data retention policies.
- Speech Recognition:Automated transcription engines convert audio streams to searchable text with timestamp synchronization.
- Learning Management System Integration:Canvas, Blackboard, and Moodle connectors embed captured content directly into course workflows.
- Augmented Reality:Overlay systems project supplemental content onto recorded instruction for enhanced review experiences.
Artificial Intelligence commands premium pricing; Video Analytics is expanding most quickly.
Application:
Volume concentration tilts toward Higher Education, while K-12 Education and Corporate Training represent underpenetrated expansion corridors with simpler deployment requirements.
- Higher Education:Research universities and teaching hospitals drive the deepest functional requirements including multi-camera switching, slide synchronization, and accessibility compliance. U.S. Department of Education Section 508 mandates accelerate replacement cycles across federally funded institutions. Hybrid learning infrastructure investments continue at scale in California and Texas university systems.
- Corporate Training:Fortune 500 learning and development departments prioritize rapid deployment and mobile accessibility over production polish. Financial services and pharmaceutical sectors in Switzerland and the United Kingdom lead compliance-driven archiving requirements. Faster procurement cycles and centralized IT governance distinguish enterprise buyers from academic institutions.
- Continuing Education:Professional development programs require asynchronous access for working adult learners.
- K-12 Education:Secondary school districts remain underpenetrated relative to higher education with standardized deployment templates.
- Professional Certification:Licensing bodies mandate recorded instruction for audit trails and quality assurance.
Higher Education absorbs the dominant volume; Corporate Training is gaining share fastest.
End User:
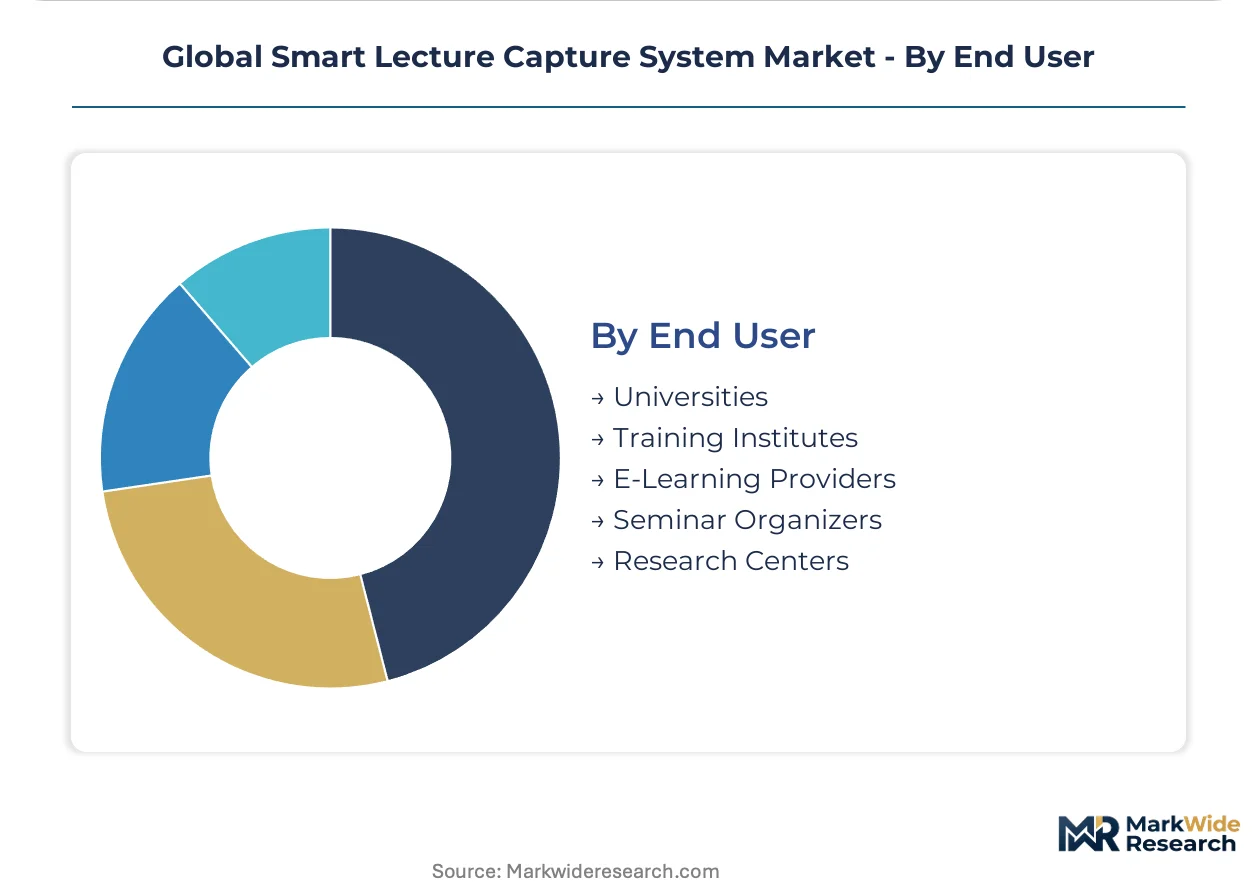
Customer type fragmentation spans centralized university IT departments, decentralized training institutes, and platform-agnostic e-learning aggregators with divergent integration requirements.
- Universities:Centralized procurement functions at large state systems standardize around cloud-native platforms with ISO/IEC 27001 certification. Multi-campus deployments require enterprise-grade security architectures and dedicated customer success functions. India's National Education Policy implementation is driving smart classroom investments across state universities with limited legacy infrastructure to displace.
- Training Institutes:Commercial skills providers prioritize rapid content turnaround and branded player experiences over deep LMS integration. German vocational training centers and Japanese corporate academies represent concentrated demand clusters with specialized localization requirements. Subscription flexibility and usage-based pricing accelerate vendor selection timelines.
- E-Learning Providers:Platform aggregators require API-first architectures for content syndication across multiple distribution channels.
- Seminar Organizers:Event-based capture demands portable equipment and rapid on-site technical support.
- Research Centers:Scientific collaboration facilities prioritize high-resolution archival standards and long-term preservation protocols.
Universities represent the largest addressable base; Training Institutes show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Section 508 accessibility mandates from the U.S. Department of Education are accelerating procurement cycles across federally funded institutions. The EU AI Act's risk-classification framework is forcing algorithmic transparency redesigns among European vendors. India's National Education Policy implementation is channeling smart classroom investments toward state universities with minimal legacy infrastructure displacement.
United States
Large research universities in California and Texas are consolidating dispersed AV investments into unified capture platforms. The Department of Education enforces Section 508 standards mandating closed captioning and audio description in all federally funded educational technology procurements. Boston's higher education cluster is piloting edge-based inference engines for real-time accessibility compliance in live remote instruction.
Germany
Vocational training centers prioritize rapid content turnaround with specialized localization requirements for technical instruction. The EU AI Act imposes risk-classification requirements on automated student analytics features that exceed previous GDPR documentation obligations. Berlin-Brandenburg's corporate academy concentration is driving compliance-driven archiving investments from financial services and pharmaceutical sectors.
India
State universities under the National Education Policy are deploying smart classroom infrastructure without legacy systems to displace. The Bureau of Indian Standards specifies interoperability protocols for educational informatization that constrain foreign platform architectures. Maharashtra's higher education institutions are accelerating digitization procurement with centralized IT governance models.
United Kingdom
Fortune 500 learning and development departments in London prioritize rapid deployment and mobile accessibility over production polish. The Information Commissioner's Office enforces algorithmic accountability rules that expand documentation requirements for educational analytics platforms. Scotland's university research clusters are standardizing around cloud-native platforms with ISO/IEC 27001 certification.
Japan
Corporate academies and technical training institutes demand subscription flexibility with usage-based pricing models. METI guidelines shape educational technology procurement standards with emphasis on long-term preservation protocols. The Kansai region's manufacturing training centers are investing in high-resolution archival systems for compliance documentation.
Global Smart Lecture Capture System Market Competitive Landscape
Listed leaders compete with private specialists across cloud-native and appliance-based deployment architectures. The competitive structure bifurcates between ISO/IEC 27001-certified enterprise vendors and uncertified regional software suppliers. Three archetypes dominate: cloud-native SaaS platforms with deep LMS integration, hardware appliance specialists serving legacy retrofits, and hybrid solutions combining edge AI with centralized management. Strategic moves concentrate on algorithmic transparency pre-certification for EU AI Act compliance and edge-based inference engine development for real-time processing.
Within the cloud-native tier, Panopto and Kaltura exemplify multi-tenant SaaS architectures that raise institutional switching costs through LMS integration. Sonic Foundry occupies a position among appliance-based hardware specialists serving bandwidth-constrained campus environments. These three anchors represent the dominant competitive vectors: software platforms commanding recurring revenue pools, hardware systems capturing legacy retrofit demand, and hybrid approaches bridging real-time AI processing with centralized management consoles.
| Leading Market Players |
|---|
| Panopto |
| Kaltura |
| Echo360 |
| YuJa |
| Sonic Foundry |
| TechSmith |
| Cisco Systems |
| Crestron Electronics |
| Haivision Systems |
| Others |
Supply & Pricing Matrix
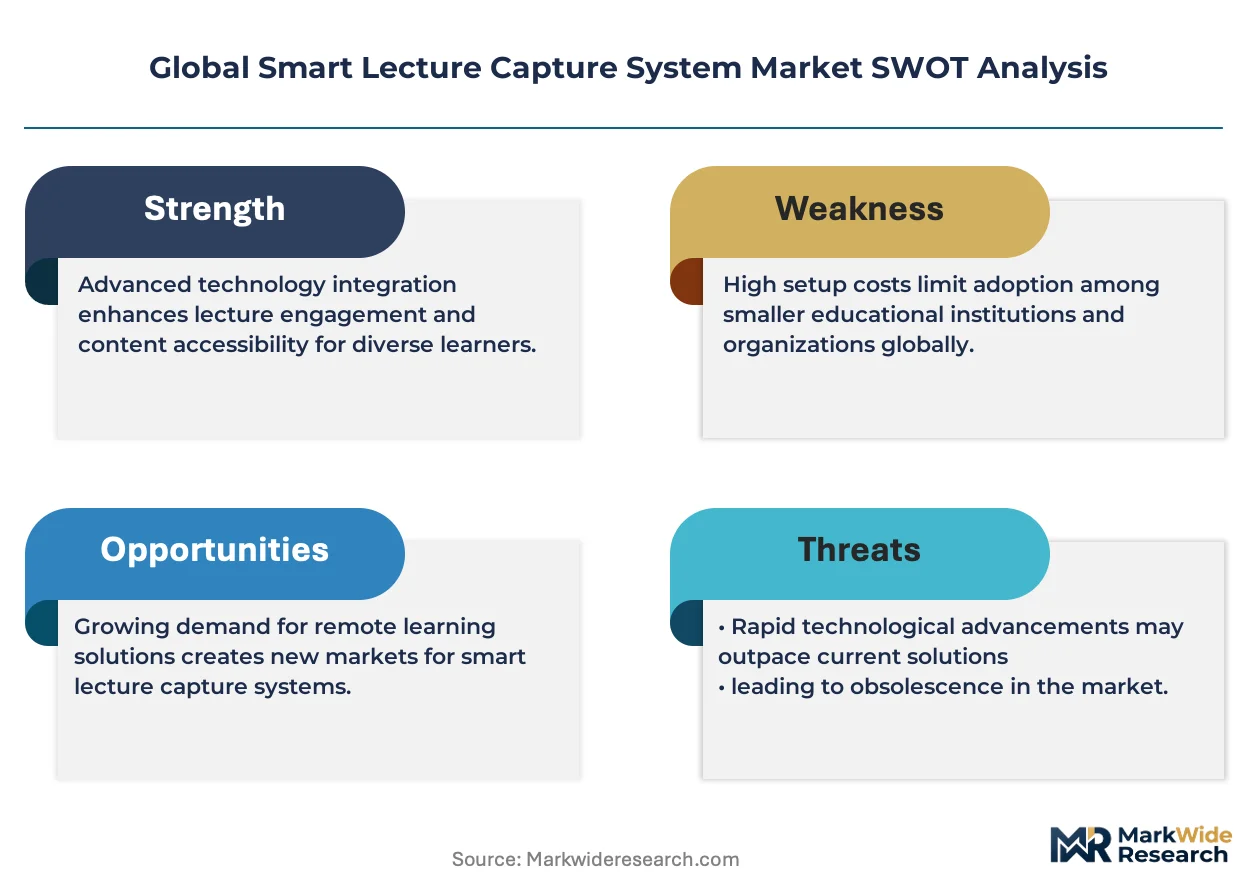
ISO/IEC 27001 certification gates both supply qualification and price differentiation across the smart lecture capture landscape, bifurcating vendors into enterprise-grade and regional tiers while compressing margins for uncertified competitors excluded from procurement shortlists.
Pricing Analysis
Certification level creates the primary spread between enterprise and regional vendor tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO/IEC 27001 compliance status, deep LMS integration depth, and edge-AI processing capability. Cost compression in hardware appliances intensifies because commoditized camera sensor and encoder chip pricing from East Asian foundries eliminates brand premiums. K-12 districts demonstrate highest price sensitivity due to constrained capital budgets, while research universities prioritize operational expenditure predictability over unit economics.
Supply Chain Analysis
Taiwanese semiconductor foundries and South Korean memory fabricators anchor component supply for encoder chips and edge inference accelerators. Camera sensor arrays draw from Japanese precision optics manufacturers and Chinese CMOS foundries. Single-source vulnerability concentrates in advanced node AI accelerators where NVIDIA and Qualcomm dominate edge deployment. Distribution runs through direct enterprise sales teams for large university systems, with value-added resellers penetrating mid-tier institutions and regional training institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across deployment architectures creates niche opportunities as hybrid learning infrastructure investments accelerate procurement cycle divergence between cloud-native and appliance-first buyers.
For Market Incumbents: Secure algorithmic transparency pre-certification pathways for EU AI Act compliance before risk-classification deadlines constrain European market access. Deepen vertical integration into edge inference hardware to defend margin position against cloud-only entrants exploiting commoditized transcription APIs. Lock in multi-year SaaS contracts with California and Texas university systems where centralized IT governance accelerates standardization. For New Entrants and Emerging Players: Lead with K-12 district expansion where deployment simplicity and faster procurement cycles offset incumbent LMS integration advantages. Target Indian state universities under National Education Policy implementation with appliance-light cloud solutions that bypass legacy infrastructure retrofit complexity. Position around real-time engagement scoring as premium tier differentiation absent from established platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native software platforms as recurring SaaS revenue displaces hardware-heavy deployment models. Acquire mid-tier vendors with ISO/IEC 27001 certification gaps but strong regional customer relationships, then bridge compliance to unlock enterprise procurement pipelines. Monitor EU AI Act technical file submission volumes as inflection indicator for vendor readiness stratification.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Algorithmic Transparency Pre-Certification | Technical file maintenance for automated transcription features gates European higher education procurement access. |
| Edge AI Inference Engine Development | On-device processing eliminates cloud latency barriers for live captioning compliance with Section 508 mandates. |
| Deep LMS Integration Partnership | Canvas and Blackboard connector depth raises institutional switching costs and slows competitive displacement. |
| K-12 District Channel Expansion | Simplified deployment templates and faster decision cycles penetrate underpenetrated secondary education vertical. |
| India Smart Classroom Infrastructure Capture | National Education Policy implementation channels procurement toward vendors without legacy displacement burden. |
Research Methodology
The analysis maps hardware appliance, cloud-native SaaS, and hybrid deployment architectures, each validated through chief information officers at U.S. public universities, procurement directors at European vocational training centers, and integration specialists at Indian state universities. Primary interview intelligence triangulates against secondary validation from U.S. Department of Education Section 508 guidance documents, EU AI Act risk-classification technical standards, and Bureau of Indian Standards interoperability protocols. Bottom-up segment sizing and top-down market reconciliation ensure cross-verification consistency.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, technology tier, application vertical, and end-user governance structure as core segmentation dimensions. CAGRs derive from installation base growth rates, replacement cycle compression from accessibility mandate enforcement, and AI feature penetration curves. Forecast inputs incorporate hybrid learning infrastructure investment trajectories at California and Texas university systems and EU AI Act compliance timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained federal education funding levels or accelerated EU enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding semiconductor supply normalization and cloud migration velocity across bandwidth-constrained campuses. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and edge AI cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Logistics Software Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Morocco ICT Market
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
Europe API Management Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Global Service Integration and Management Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Global Digital Business Card Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Barcode Software Market
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Change Management Software Market
Digital Solutions
Online Advocacy Platform Market