
 Europe Olive Market | 2026-2036
Europe Olive Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Olive Market Foresight
Extra-virgin olive oil certification premiums is reshaping margin distribution across the Europe Olive Market. Deoleo S.A. leverages its multi-brand portfolio to dominate Iberian retail shelves. Borges International Group anchors Mediterranean supply through its Catalonian crushing and blending facilities. Monini differentiates via regional estate labeling and DOP-protected sourcing claims.
Europe's olive sector encompasses the cultivation, processing, and commercialization of Olea europaea fruit and its derivatives, with extra-virgin grades requiring maximum free acidity of 0.8% and cold-extraction below 27 degrees Celsius to preserve polyphenol content and organoleptic integrity. Olive Oil commands the dominant value share as health-conscious households trade up from seed oils, while Table Olives sustain steady food service pull through Mediterranean diet positioning. Online Retail is expanding fastest as direct-to-producer platforms bypass traditional wholesale markups, though Supermarkets still control the bulk of packaged volume.
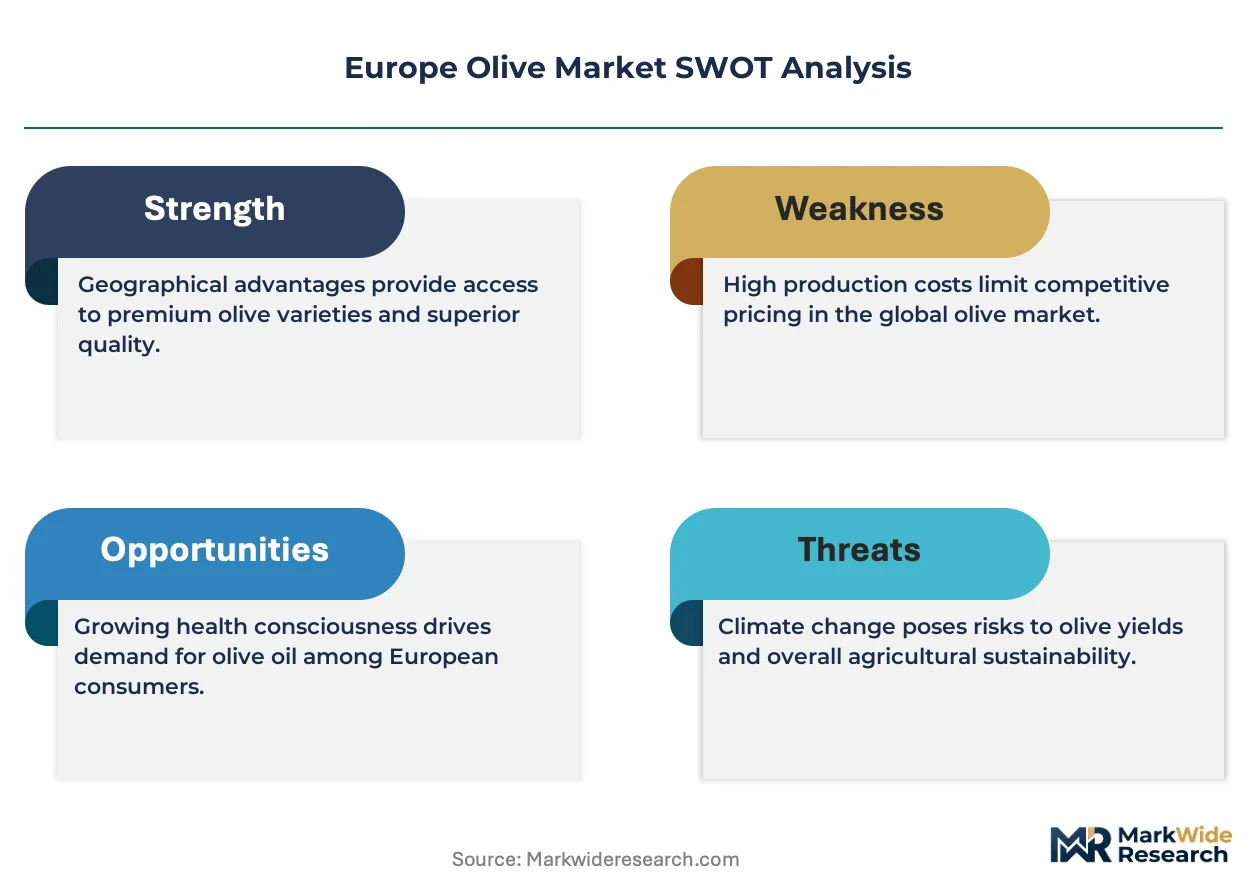
EU Green Deal farm-to-fork targets and EFSA pesticide residue benchmarks are tightening maximum residue limits and mandating blockchain traceability from orchard to shelf. REACH compliance on packaging materials and CSRD sustainability reporting obligations are adding compliance layers for mid-sized bottlers. Stakeholders must monitor how digital product passports and evolving organic certification thresholds alter procurement strategies and supplier qualification criteria.
Market Dynamics
EU Green Deal farm-to-fork mandates are compressing pesticide residue thresholds while mandating blockchain traceability from orchard to shelf, forcing cooperatives and bottlers to reconfigure procurement and quality assurance workflows.
Growth Catalysts
- EU Green Deal pesticide limits:EFSA benchmarks are tightening maximum residue limits, driving certified organic acreage expansion as growers seek compliance premiums.
- Health-conscious substitution:Spanish and Italian households are displacing seed oils with extra-virgin grades, concentrating volume pull through Iberian retail channels.
- Cold-extraction technology:Sub-27 degree Celsius processing preserves polyphenol content, enabling organoleptic differentiation that commands shelf price separation.
Market Restraints
- Input cost volatility:Glass and tin packaging materials fluctuate with energy prices, squeezing mid-sized bottler margins during harvest-to-bottling cycles.
- Andalusian supply concentration:Roughly half of continental production volume flows through Spanish cooperatives, creating geographic risk during drought or frost events.
- Seed oil substitution threat:Sunflower and rapeseed oils undercut olive oil on price in food service bulk purchasing, limiting penetration in institutional catering contracts.
Strategic Opportunities
- Portuguese organic expansion:Alentejo estates are converting conventional groves to certified organic, capturing EU CAP subsidy streams and premium export positioning.
- Direct-to-producer platforms:Online retail channels bypass traditional wholesale markups, enabling estate-label producers to capture margin previously lost to intermediaries.
- CSRD sustainability reporting:Corporate sustainability disclosure obligations create demand for verified carbon-footprint labeling, rewarding early adopters with B2B contract preference.
Industry Challenges
- Polyphenol testing skill scarcity:Laboratory capacity for organoleptic certification and chemical verification lags behind expanding DOP-protected sourcing claims.
- Blockchain traceability capex:Orchard-to-shelf digital passport systems require sensor deployment and data infrastructure investment that strains cooperative balance sheets.
- REACH packaging compliance:Chemical safety registration for imported glass and caps adds documentation burden and supplier qualification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Olive Market |
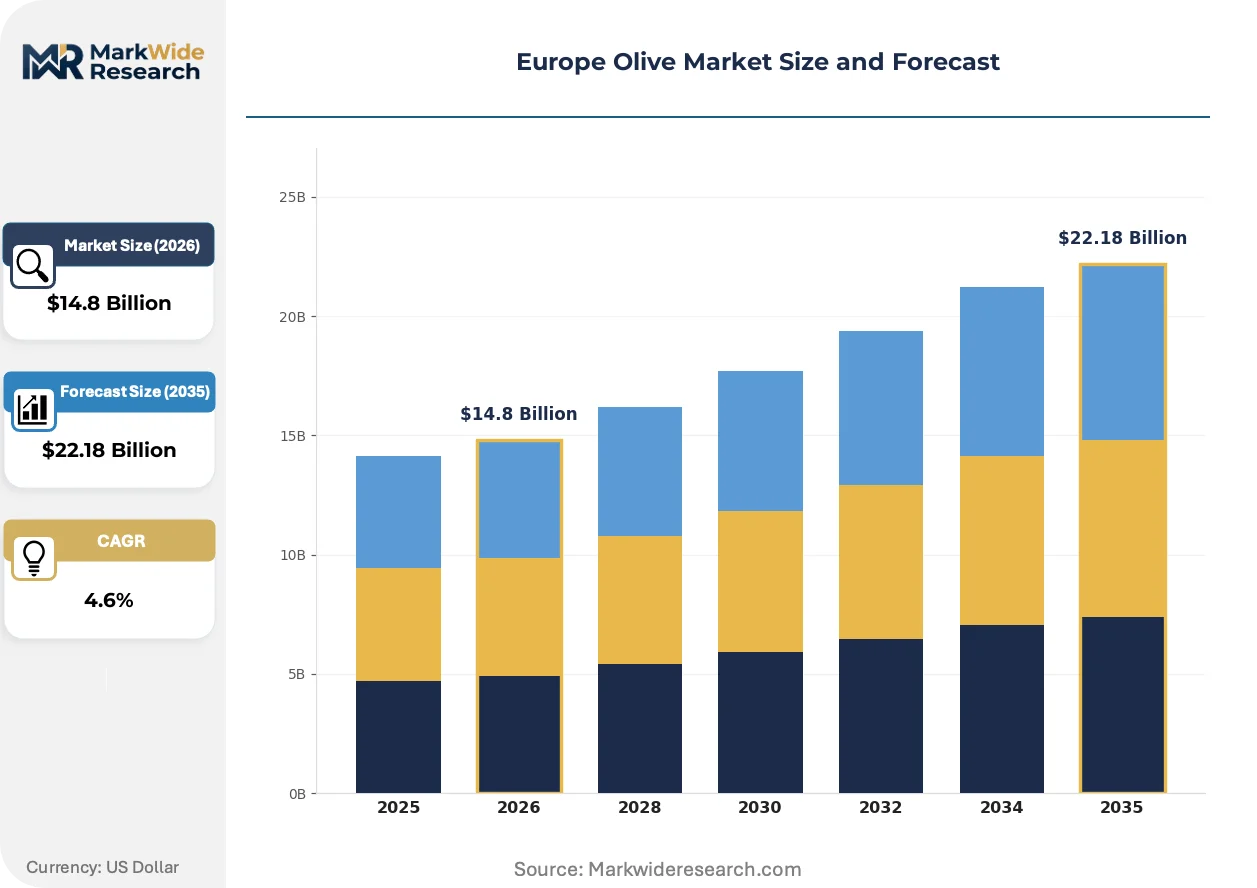
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table Olives, Olive Oil, Olive Paste, Olive Tapenade Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Food Service End User: Households, Restaurants, Food Manufacturers, Caterers Packaging Type: Glass Bottles, Cans, Tubs, Pouches |
| Companies Covered | Deoleo S.A., Cargill, Incorporated, Borges International Group, Gallo Worldwide, Salov S.p.A., Sovena Group, Bunge Global, Fresh Del Monte Produce Inc, Monini, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Olive Market Shifts & Advancements
Sustainability verification technologies and procurement transparency tools are compressing traditional quality assurance timelines while enabling new forms of origin-based differentiation.
Near-infrared spectroscopy is hybridizing with blockchain verification to create real-time polyphenol content authentication. Andalusian cooperatives are deploying these systems at crushing facilities to accelerate batch certification. The technology is hybridizing quality control and marketing functions, compressing the gap between laboratory analysis and consumer-facing provenance claims.
EU Green Deal farm-to-fork targets are mandating digital product passports for agricultural imports. These requirements force bottlers to integrate sensor networks across crushing, blending, and packaging stages. Spanish DOP-protected estates face the steepest compliance curves as they retrofit legacy operations with traceability infrastructure.
Specialty food retailers are consolidating olive oil SKU counts while expanding direct sourcing from named estates. Italian and Greek consumers increasingly bypass supermarket private labels for cooperatives with verified single-origin claims. This pattern concentrates volume with producers who control crushing and bottling within protected designation boundaries.
Europe Olive Market Segmentation
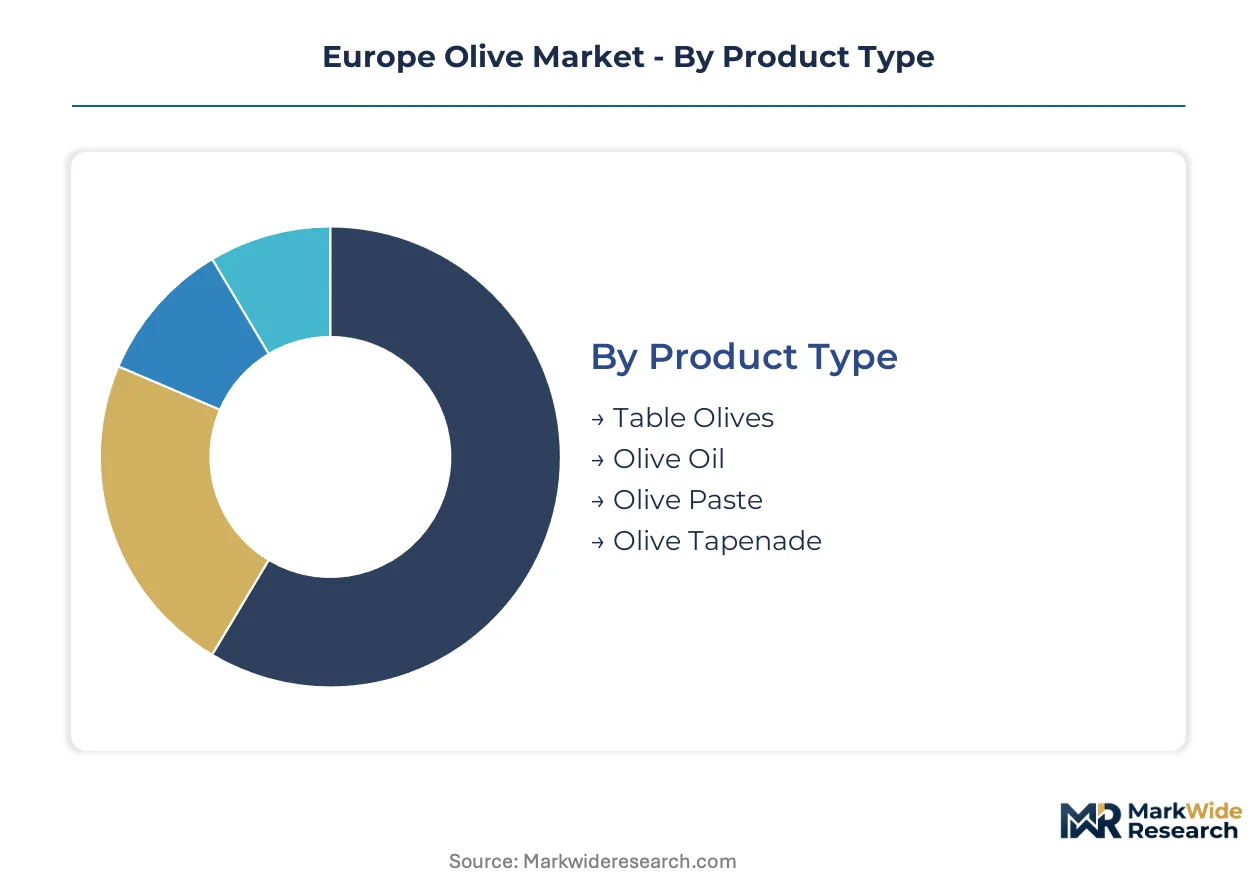
Segmentation in the Europe Olive Market reveals how certification grades, channel control, and packaging formats determine margin capture. Understanding these divisions exposes where value concentrates and where intermediaries still extract rents.
Product Type:
Cost tier separates commodity bulk grades from estate-labeled premiums that command shelf price separation.
- Table Olives:Brined and fermented whole fruit sold in retail jars and food service bulk formats. Spanish Manzanilla and Greek Kalamata varieties anchor Mediterranean food service demand through diet-positioning menus.
- Olive Oil:Cold-extracted liquid grades spanning extra-virgin through refined, with free acidity thresholds defining legal categories. Extra-virgin pulls volume through Iberian and Italian retail as households displace seed oils.
- Olive Paste:Milled olive flesh for spreads and ingredient applications. Industrial buyers in France and Germany source paste for processed food manufacturing.
- Olive Tapenade:Provençal-style blended spreads incorporating capers and anchovies. French and Italian specialty retailers stock regional recipe variants.
Olive Oil holds installed capacity. Table Olives is rotating up the share rankings.
Distribution Channel:
Channel control determines whether producers capture margin or surrender it to wholesale intermediaries.
- Supermarkets:Mass retail chains controlling packaged volume through private-label and branded shelf placement. Carrefour and Mercadona listings remain essential for Spanish and French volume targets.
- Specialty Stores:Delicatessen and gourmet food retailers curating DOP-protected and single-origin SKUs. Italian consumers increasingly bypass supermarkets for cooperative direct sourcing.
- Online Retail:Direct-to-producer platforms and marketplace storefronts. Estate-label producers use these channels to bypass wholesale markups and capture margin previously lost to intermediaries.
- Food Service:Restaurant and institutional catering procurement. Sunflower oil undercutting limits olive penetration in bulk catering contracts across Germany and Northern Europe.
Supermarkets hold installed capacity. Online Retail is expanding most quickly.
End User:
Customer type dictates whether procurement prioritizes price, provenance, or processing convenience.
- Households:Health-conscious consumers trading up from seed oils to extra-virgin grades. Spanish and Italian households drive the steepest volume concentration through retail channels.
- Restaurants:Food service operators sourcing bulk and bottled grades for menu execution. Mediterranean diet positioning sustains steady pull through mid-tier dining.
- Food Manufacturers:Industrial processors using olive oil and paste as ingredients. German and Dutch manufacturers blend olive oil into margarine and prepared foods.
- Caterers:Institutional meal providers balancing cost and menu claims. Price pressure from seed oils constrains olive adoption in contract catering.
Households hold installed capacity. Restaurants are climbing the fastest.
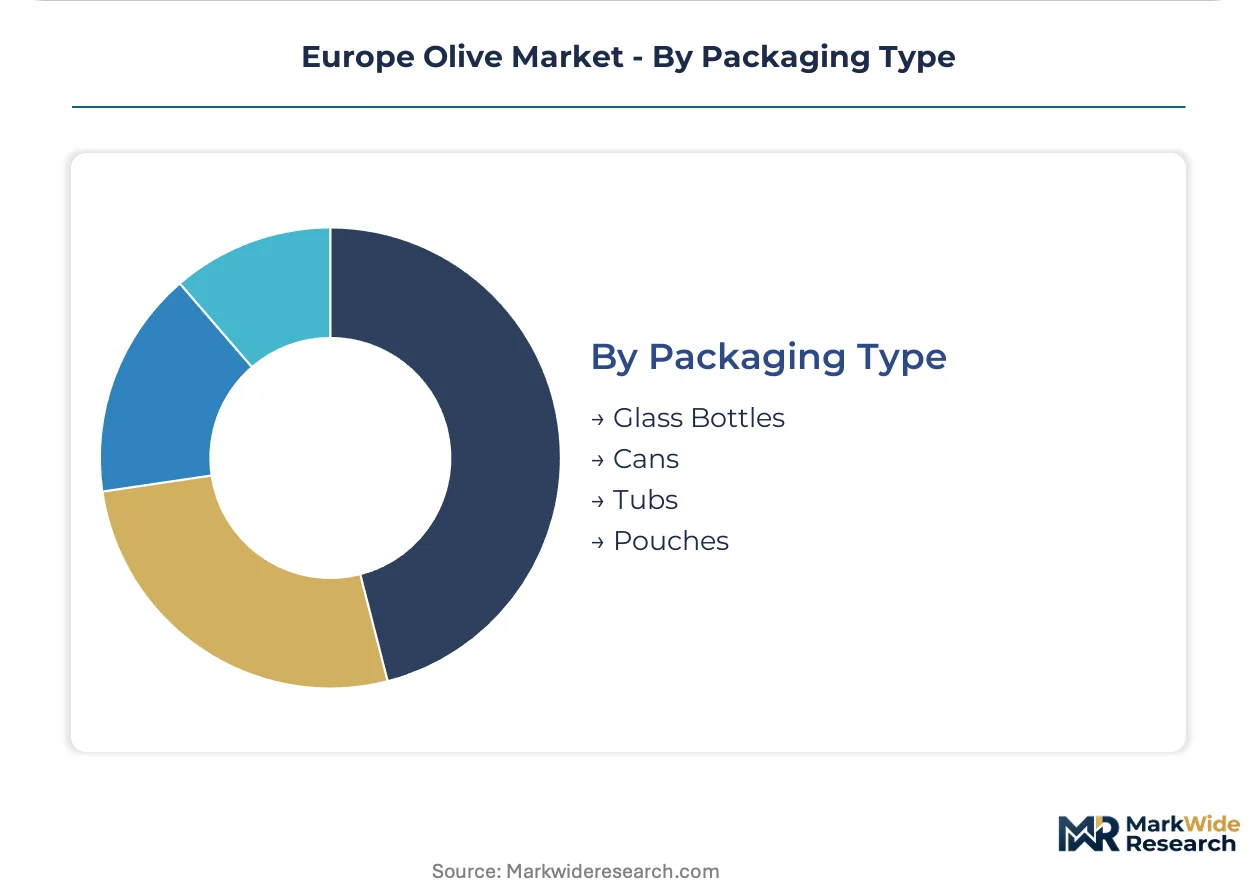
Packaging Type:
Material selection reflects shelf-life requirements, premium positioning, and REACH compliance burdens.
- Glass Bottles:Premium positioning for extra-virgin and DOP-protected oils. Dark glass preserves polyphenol content while satisfying retailer sustainability expectations.
- Cans:Tinplate containers for food service bulk and export markets. Andalusian cooperatives favor cans for harvest-to-bottling cycles due to lower breakage rates.
- Tubs:Plastic containers for table olives and paste applications. Retail private-label table olive volume concentrates in this format.
- Pouches:Flexible packaging for food service and value-tier retail. Emerging format for single-serve and portion-control applications.
Glass Bottles hold installed capacity. Pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the continent. Southern European households absorb extra-virgin premiums with minimal volume contraction, while Northern European food service buyers switch to seed oils when olive prices spike.
Spain
Andalusian cooperatives channel roughly half of continental production through Jaén and Córdoba crushing facilities. The EU Green Deal's farm-to-fork pesticide limits are accelerating organic conversion in Alentejo-bordering estates. Blockchain traceability pilots at Seville-based bottlers are compressing certification timelines from harvest to export.
Italy
Apulian and Calabrian estates are capturing premium positioning through DOP-protected labeling claims. EFSA residue benchmarks are tightening maximum limits for pyrethroids and organophosphates, forcing laboratory capacity expansion in Bari. Tuscan cooperatives are consolidating direct-to-retail relationships with specialty food chains in Florence and Rome.
Greece
Peloponnese growers are displacing Turkish imports in German retail through single-origin estate branding. The country's national agricultural regulator is aligning organic certification thresholds with EU CAP subsidy streams. Crete-based producers are deploying cold-extraction infrastructure to preserve polyphenol content for Nordic export markets.
Portugal
Alentejo estates are converting conventional groves to certified organic at rates exceeding Spanish neighbors. EU CAP direct payments are subsidizing irrigation modernization in Évora and Beja districts. Port-based exporters are bypassing traditional wholesale channels through direct-to-producer platforms targeting UK and French online retail.
France
Provençal tapenade processors are sourcing bulk olive paste from Spanish cooperatives to manage input costs. REACH compliance on imported glass packaging is adding documentation burden to Marseille and Nice bottling operations. Corsican DOP-protected estates are limiting volume to preserve price premiums in Parisian specialty retail.
Europe Olive Market Competitive Landscape
Capability concentration sits with estate-level producers commanding DOP-protected sourcing claims; scale advantage sits with multi-brand bottlers dominating Iberian retail shelf placement. The market structures around three tiers: cooperative federations controlling Andalusian crush capacity, integrated trading houses managing cross-border bulk flows, and estate-label specialists capturing direct-to-consumer premiums. M&A activity concentrates on crushing facility consolidation, while portfolio diversification into organic and carbon-verified lines represents the second dominant competitive move.
Within the multi-brand bottler tier, Deoleo S.A. and Borges International Group occupy positions defined by retail channel control and geographic origin concentration. Monini represents the estate-label archetype, with regional naming conventions suggesting Italian provenance and protected designation positioning. These three exemplify how scale-driven and provenance-driven strategies coexist without direct overlap in customer targeting or margin capture mechanics.
| Leading Market Players |
|---|
| Deoleo S.A. |
| Cargill, Incorporated |
| Borges International Group |
| Gallo Worldwide |
| Salov S.p.A. |
| Sovena Group |
| Bunge Global |
| Fresh Del Monte Produce Inc |
| Monini |
| Others |
Supply & Pricing Matrix
Andalusian cooperative concentration creates geographic chokepoint risk that compresses margin distribution across extra-virgin, standard, and economy grade tiers while forcing downstream bottlers into backward integration or captive supply arrangements. EU Green Deal traceability mandates amplify this structural tension by layering compliance capex onto already thin cooperative balance sheets.
Pricing Analysis
After-sales service contracts and estate-label direct sourcing drive lifetime value capture for premium producers. Three-tier pricing structure across extra-virgin DOP-protected, standard cold-extracted, and refined economy grades anchors the market. Price differentiation rests on polyphenol certification thresholds and blockchain-verified origin claims. Cost compression in economy tiers intensifies as seed oils undercut olive oil in institutional catering procurement. Northern European food service buyers exhibit highest price sensitivity, while Southern European households absorb premium spreads with minimal volume contraction.
Supply Chain Analysis
Contract crushing capacity concentrates with Andalusian cooperative federations and Catalonian blending facilities that anchor Iberian supply. Spain, Italy, and Greece feed downstream distribution, with raw material flows drawing from olive fruit harvests, glass packaging from Murano and Catalonia, and tinplate from Northern European foundries. Single-source vulnerability runs through Jaén and Córdoba crush corridors during drought or frost events. Distribution runs through supermarket private-label channels for volume, specialty retail for premium capture, and direct-to-producer platforms for margin retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story where DOP-protected designation control and EU-mandated traceability infrastructure create switching costs that lock in cooperative incumbents and raise barriers for unverified entrants.
For Market Incumbents: Entrench position through backward integration into crushing capacity in Alentejo and Apulia, capturing organic conversion subsidies while seed oil substitution threatens food service share. Lock in specialty retail shelf space via blockchain-verified single-origin SKUs that preempt private-label encroachment. Prioritize laboratory capacity expansion for polyphenol certification to accelerate batch release timelines.
For New Entrants and Emerging Players: Portuguese organic estates with EU CAP subsidy access and underdeveloped export channels represent the most penetrable entry point for premium positioning. Nordic online retail platforms seeking verified carbon-footprint labeling offer direct-to-consumer bypass of wholesale markups. Lead with CSRD-compliant sustainability reporting to capture B2B contract preference from institutional buyers.
For Investors and Strategic Acquirers: Estate-label specialists with DOP-protected crushing and bottling within protected designation boundaries command scarcity premiums in a consolidating landscape. Long-term viability hinges on climate adaptation infrastructure and digital passport compliance capex absorption. Watch for inflection in EFSA residue benchmark tightening timelines that would accelerate laboratory capacity bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Grove Conversion | Alentejo estates capture EU CAP subsidy streams while meeting tightening EFSA residue limits. |
| Blockchain Traceability Deployment | Seville-based bottlers compress orchard-to-shelf certification timelines for export readiness. |
| Direct-to-Producer Platform Launch | Estate-label producers bypass wholesale markups previously captured by intermediaries. |
| Laboratory Capacity Expansion | Bari facilities address polyphenol testing scarcity lagging behind DOP-protected sourcing claims. |
| Carbon-Footprint Labeling Program | Early CSRD adopters secure B2B contract preference from sustainability-mandated procurement. |
Research Methodology
The analysis maps extra-virgin certification tiers, cooperative crushing capacity, and channel control structures, each validated through cooperative federation managers, specialty retail category buyers, EFSA compliance officers, and bottler procurement leads. Primary interview findings triangulate against EU customs trade data, EFSA residue benchmark publications, SEC filings for listed bottlers, and organic certification registry databases. Bottom-up volume builds from grove-level production estimates reconcile with top-down category spend analysis.
Assumptions around EU Green Deal implementation pace, CAP subsidy continuity, and EFSA residue threshold tightening trajectories were held fixed across baseline scenarios while organic conversion rates and direct-to-producer channel penetration were stress-tested. Segmentation dimensions span product grade tier, distribution channel control, end-user procurement type, and packaging material compliance burden. CAGRs derive from trend extrapolation calibrated to historical volume elasticity and substitution pattern modeling.
Practitioners should monitor EFSA benchmark revision timelines, drought severity indices for Andalusia, and seed oil price spreads for early signals of forecast deviation. Quarterly review of organic certification conversion rates, blockchain traceability deployment capex, and specialty retail SKU consolidation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
Grapefruit Peel Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Coconut Products Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Grapes Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Spring Market