
 Thailand Skin Care Products Market | 2026-2036
Thailand Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Skin Care Products Market Insights
E-commerce is rewriting how Thai consumers discover and purchase skin care products. L'Oréal S.A. leverages its direct-to-consumer platforms to capture first-party data on Bangkok's beauty shoppers. Beiersdorf AG anchors its NIVEA portfolio through pharmacy partnerships that sustain trust among dermatology-conscious buyers. Kao Corporation specializes in sensorial textures tailored to tropical humidity conditions.
Thailand skin care products encompass topical formulations designed to cleanse, protect, or improve skin appearance through active ingredients such as niacinamide, hyaluronic acid, and titanium dioxide. These products serve commercial purposes across daily hygiene routines, photoprotection regimens, and aesthetic maintenance for consumers in tropical climates. Moisturizers occupy the largest revenue pool as Thai consumers prioritize hydration in high-humidity environments. Serums represent the fastest-growing product type as concentrated actives displace basic creams among urban professionals. Online distribution channels capture expanding margin pools through subscription models and influencer-driven conversion funnels.
Thailand's FDA under the Ministry of Public Health enforces cosmetic ingredient disclosure and safety assessment protocols that elevate compliance costs for imported formulations. The ASEAN Cosmetics Directive harmonizes labeling standards across regional trade corridors, enabling cross-border distribution for compliant manufacturers. Stakeholders must monitor evolving biotech ingredient classifications and local sourcing requirements that will determine which product portfolios secure shelf space in Thai retail.
Market Dynamics
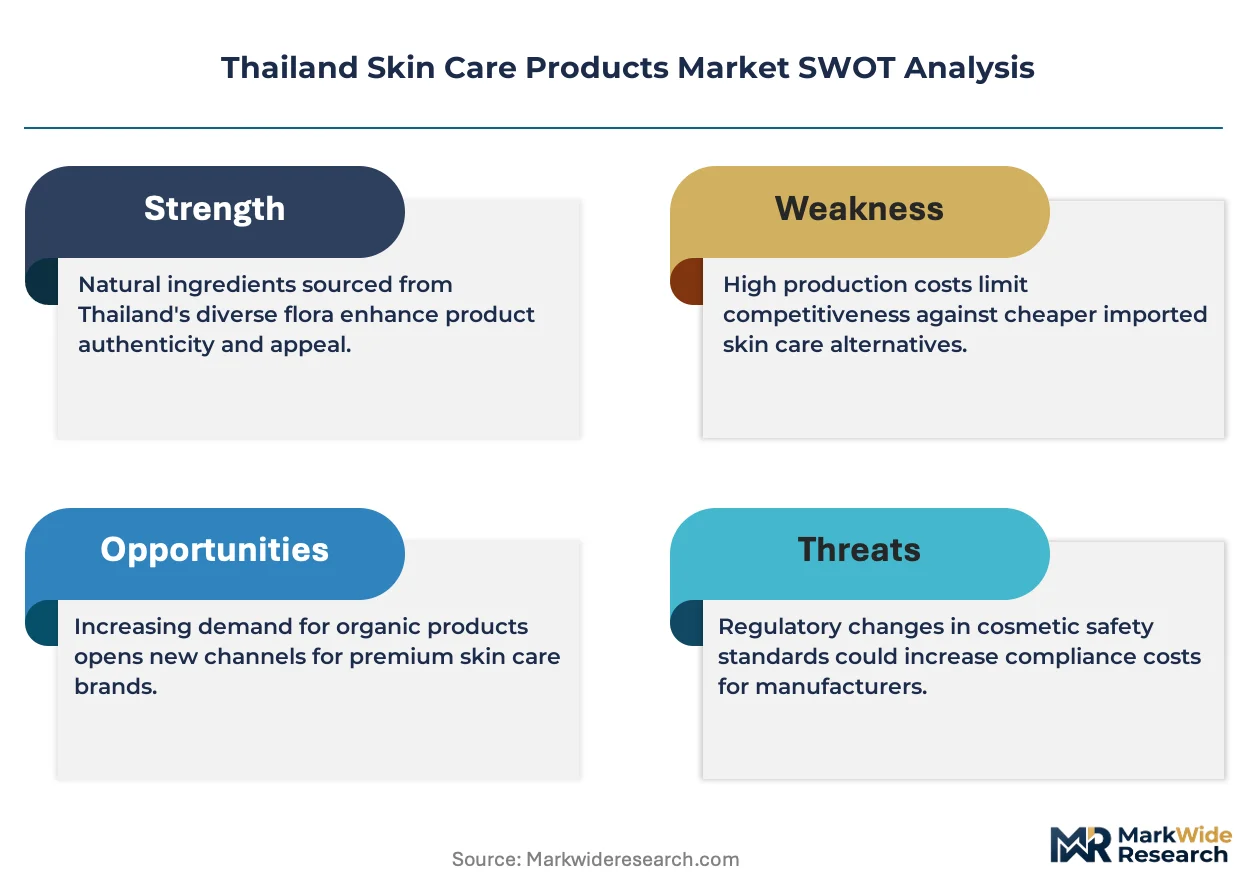
Thailand's FDA cosmetic registration protocols under the Ministry of Public Health are compressing product development timelines while elevating formulation standards across imported and domestic portfolios.
Growth Catalysts
- ASEAN Cosmetics Directive harmonization:Cross-border labeling standardization enables Thai manufacturers to distribute compliant products into Vietnam, Indonesia, and Philippines without reformulation costs.
- Urban professional women:Bangkok's working demographic drives concentrated demand for photoprotection and anti-aging actives, expanding the premium serum category faster than mass-market alternatives.
- Niacinamide and hyaluronic acid penetration:Biotech-derived actives displace basic moisturizing ingredients, commanding higher per-unit margins and repeat purchase rates among digitally-engaged consumers.
Market Restraints
- Imported raw material dependency:Thailand sources over 70% of active ingredients from South Korea and Japan, exposing formulators to yen and won volatility plus shipping disruptions through the Strait of Malacca.
- FDA safety assessment protocols:Extended ingredient disclosure timelines delay product launches by 8-14 months compared to pre-2020 benchmarks, compressing first-mover advantages.
- Climate-adapted substitutes:Local herbal formulations using turmeric and tamarind extracts compete with synthetic actives on price and cultural resonance in rural provinces.
Strategic Opportunities
- Chiang Mai and Phuket sub-markets:Secondary urban centers show underpenetrated professional skincare demand relative to Bangkok saturation, offering whitespace for regional distribution partnerships.
- Subscription commerce models:Recurring delivery platforms capture higher lifetime value from millennial consumers while reducing customer acquisition costs through influencer referral loops.
- Thailand Board of Investment incentives:Tax privileges for biotechnology R&D facilities encourage domestic production of active ingredients currently imported from Northeast Asia.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in tropical-stability science remains concentrated in Bangkok, limiting regional manufacturing expansion.
- Legacy pharmacy channel integration:Traditional retail partners resist inventory digitization, creating data blind spots in consumer preference tracking outside e-commerce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Skin Care Products Market |
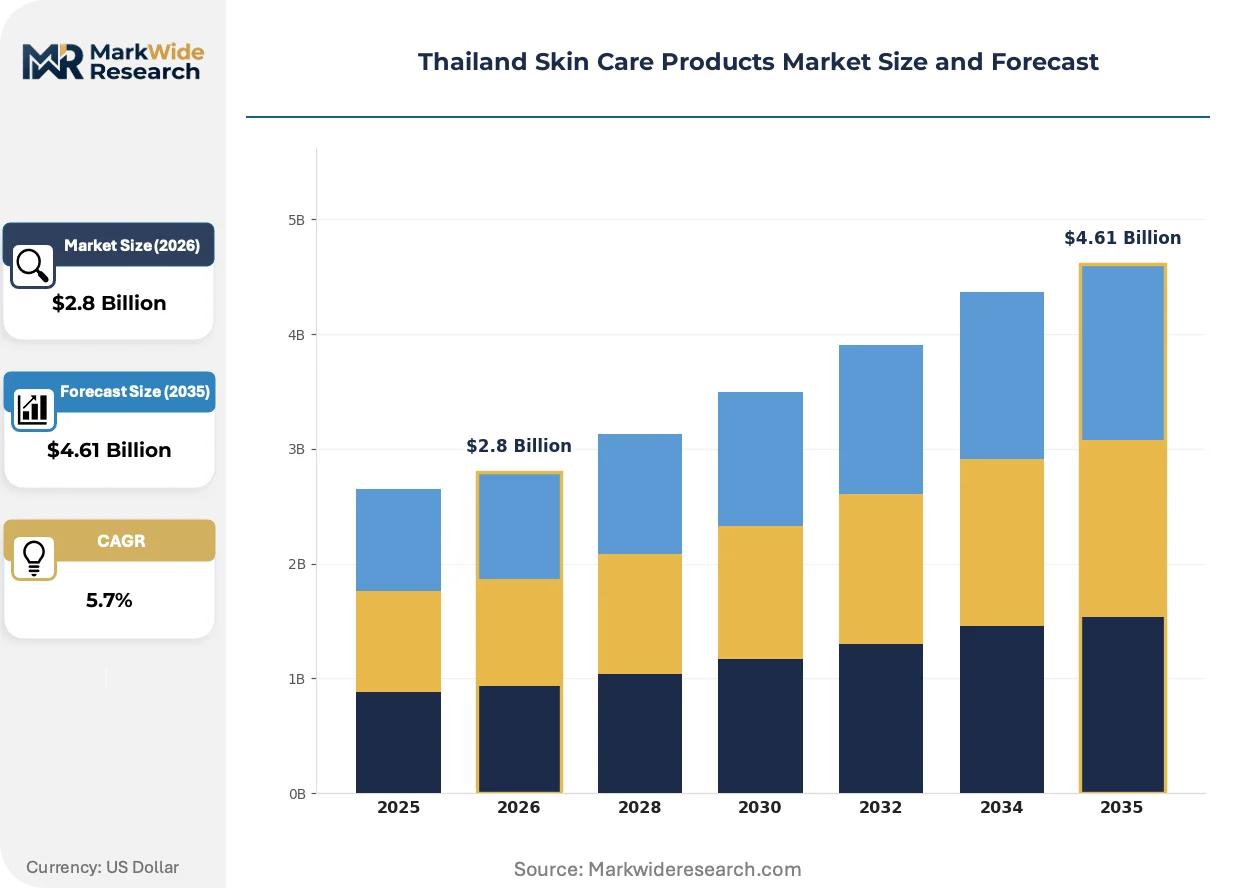
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Sunscreens, Serums End User: Females, Males, Teens, Professionals Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores Form: Gel, Cream, Lotion, Foam |
| Companies Covered | L'Oréal S.A., Beiersdorf AG, Kao Corporation, The Estée Lauder Companies Inc., Shiseido Company Limited, Unilever PLC, Procter & Gamble, Mistine, Do Day Dream Plc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Skin Care Products Market Trends and Innovations
Digital-native discovery mechanisms and biotech ingredient transparency are restructuring how Thai consumers evaluate efficacy claims and allocate spending across product tiers.
Artificial intelligence skin diagnostic tools is digitizing the consultation experience. Bangkok dermatology clinics and pharmacy chains deploy camera-based analysis to recommend personalized regimens. Younger consumers adopt these assessments at triple the rate of shoppers over 40, compressing the traditional trial-and-error purchase cycle.
Thailand's FDA under the Ministry of Public Health mandates granular ingredient disclosure and safety documentation for all cosmetic registrations. This elevates compliance costs for imported brands while creating competitive shelter for domestic manufacturers with established local testing relationships. Premium serums face the steepest documentation burdens due to concentrated active concentrations.
Live commerce and short-form video platforms now drive discovery for skincare purchases among urban millennials. Traditional television advertising loses share to influencer-led demonstrations on mobile-first channels. Bangkok and Chiang Mai exhibit the highest conversion rates from content engagement to subscription sign-ups, reshaping brand media allocation away from legacy broadcast.
Thailand Skin Care Products Market Segmentation
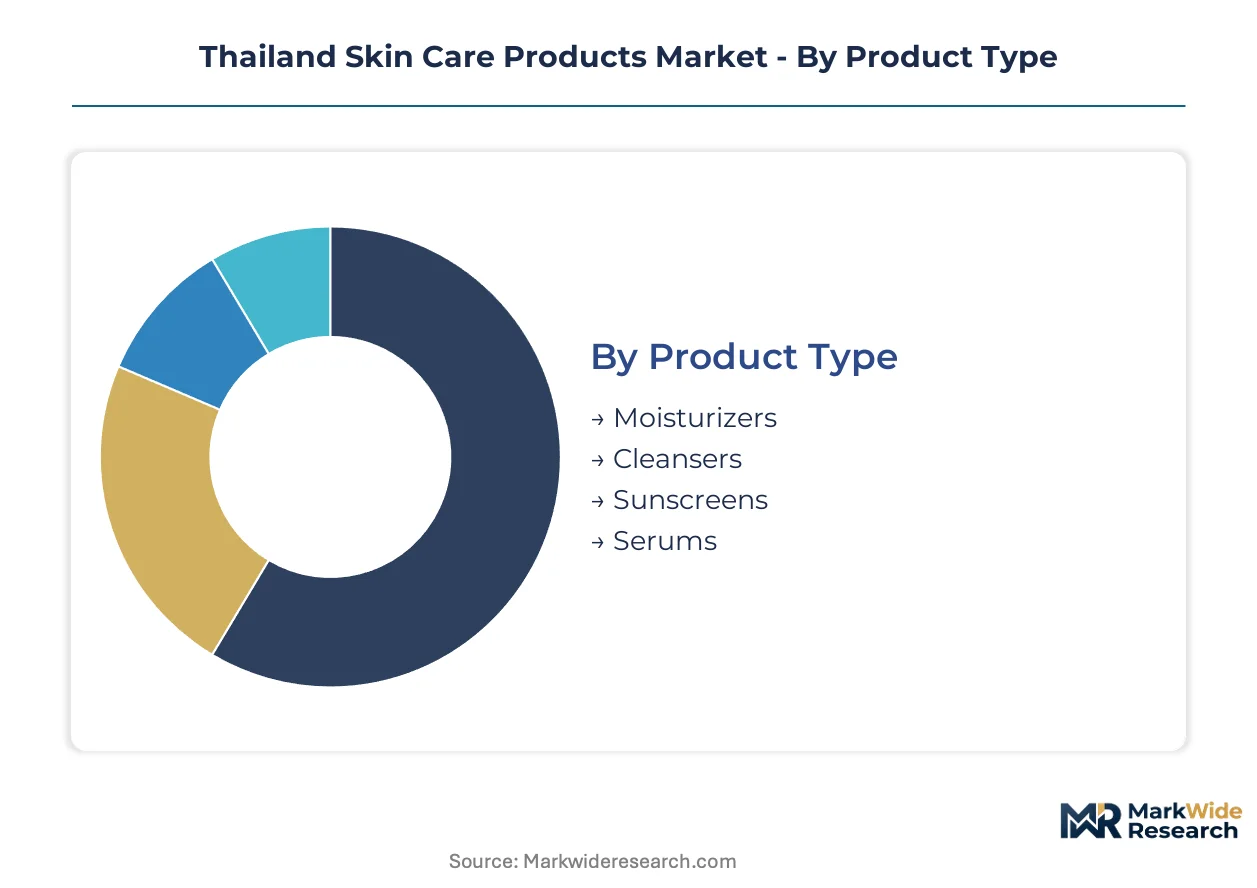
Thailand's skin care market fragments across four critical dimensions that determine formulation priorities, channel economics, and customer lifetime value. Understanding segment velocity—how quickly consumer preferences shift between product types, user demographics, and purchase channels—enables portfolio allocation that matches Bangkok's rapid digital adoption with provincial stability patterns.
Product Type:
Cycle times vary dramatically: moisturizers and cleansers turn over fastest through repeat purchase, while serums and sunscreens exhibit slower replacement but higher trial conversion investment.
- Moisturizers:Occlusive and humectant-based formulations dominate daily routines in Thailand's high-humidity climate. Bangkok's professional working women drive concentrated demand for lightweight, non-comedogenic variants that layer under sunscreens without pilling.
- Serums:Concentrated active delivery systems—niacinamide, hyaluronic acid, vitamin C—command premium positioning and subscription loyalty. Urban millennials in Chiang Mai adopt these at triple the rate of mass-market alternatives, displacing basic creams through influencer-driven education on ingredient efficacy.
- Cleansers:pH-balanced surfactant systems serve the foundational step in multi-step routines, with foam and gel textures preferred for tropical conditions.
- Sunscreens:Photoprotection formulations with PA++++ ratings anchor professional women's daytime regimens, with reapplication frequency driving volume.
Moisturizers dominate installed base across all Thai demographics. Serums are where expansion concentrates most steeply among urban professionals.
End User:
Cost tier stratification separates mass-market teens from premium professional segments, with male grooming emerging as a whitespace between established female and teen positioning.
- Females:The core revenue pool spans mass to luxury tiers, with Bangkok working women driving photoprotection and anti-aging actives. This segment commands the highest per-capita spend and subscription conversion rates.
- Professionals:Time-constrained urban workers prioritize efficacy-verified, multi-functional products that compress routines. This cohort shows strongest adoption of AI skin diagnostics and personalized regimen services.
- Males:Emerging demand concentrates in cleansers and moisturizers, with stigma reduction around male grooming expanding addressable market in Bangkok and Phuket.
- Teens:Price-sensitive entry point for basic cleansers and oil-control formulations, with social media discovery driving brand switching.
Females anchor current revenue concentration. Professionals represent the steepest expansion trajectory for premium actives and subscription models.
Distribution Channel:
Volume gravity shifts from legacy pharmacy and supermarket dominance toward digital-native discovery, with specialty stores retaining authority for premium positioning.
- Online:Direct-to-consumer platforms and marketplace aggregators capture first-party data on Bangkok beauty shoppers. Subscription models and influencer referral loops reduce customer acquisition costs while extending lifetime value.
- Pharmacies:Dermatology-conscious buyers sustain trust in pharmacy partnerships for sensitive-skin and medicated formulations, particularly outside Bangkok's digital core.
- Supermarkets:Mass-market moisturizers and cleansers move through high-frequency grocery trips, with limited shelf space constraining SKU depth.
- Specialty Stores:Experiential retail environments enable texture sampling and regimen consultation, supporting premium serum conversion.
Pharmacies dominate trust-based purchase occasions. Online channels concentrate expansion investment from domestic and imported brands alike.
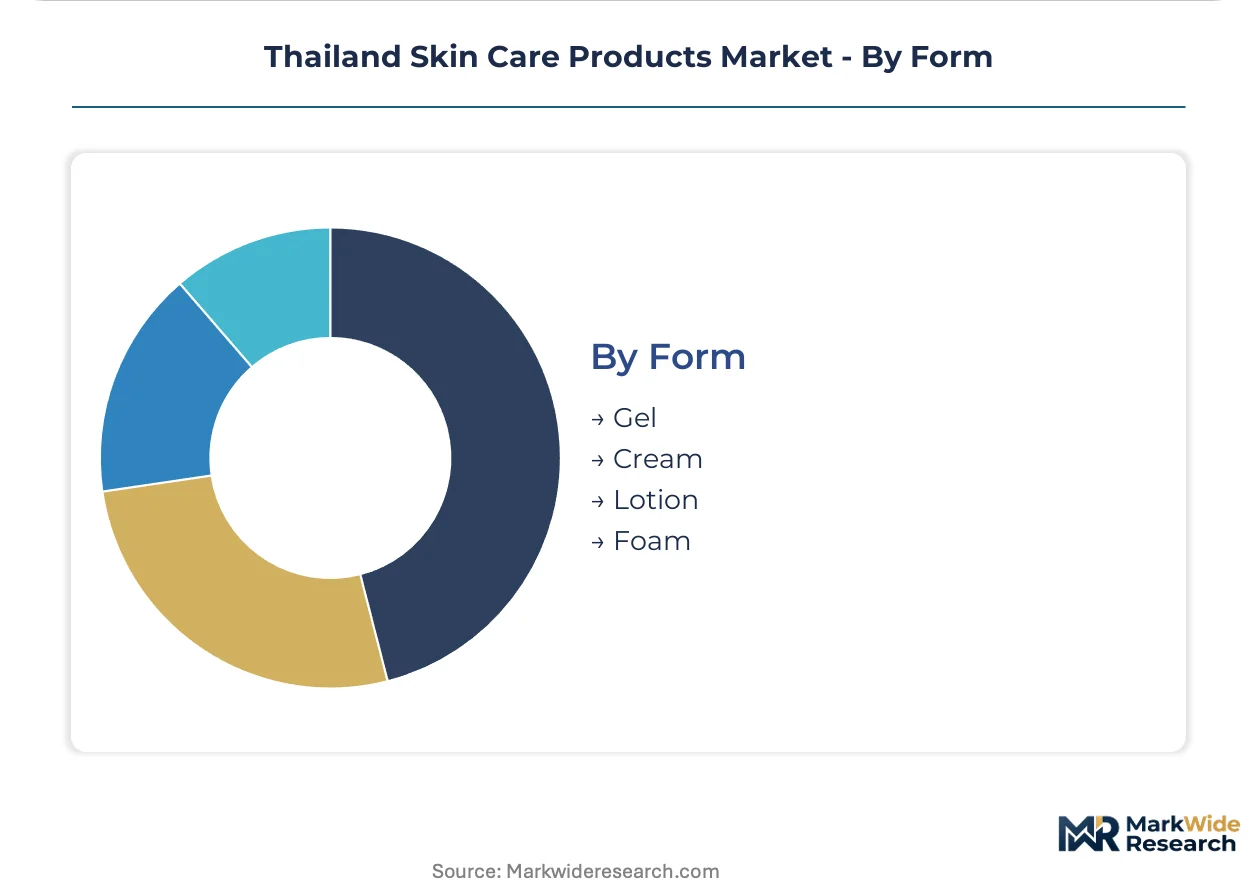
Form:
Application context—morning versus evening, standalone versus layered—determines texture preference, with tropical climate adaptation favoring specific vehicle types.
- Gel:Water-based, fast-absorbing vehicles dominate daytime moisturizers and post-cleanser hydration steps. Bangkok consumers reject occlusive residues in humidity.
- Cream:Emulsion systems serve nighttime repair and dry-skin segments, with richer textures accepted for evening regimens.
- Lotion:Intermediate viscosity spans body and face applications, with pump dispensers preferred for volume usage.
- Foam:Aerosol and pump-dispensed cleansers deliver sensorial satisfaction and perceived deep cleaning, particularly among male and teen adopters.
Gel formulations dominate daytime installed base. Cream textures are where nighttime and anti-aging expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Laem Chabang Deep Sea Port anchors Thailand's skin care supply chain, processing raw material imports from South Korea and Japan while exporting finished formulations across ASEAN trade corridors.
Bangkok Metropolitan Region
Bangkok's professional working women drive concentrated demand for photoprotection serums and AI-enabled skin diagnostics. Thailand's FDA cosmetic registration protocols under the Ministry of Public Health enforce ingredient disclosure standards that elevate compliance costs for imported brands. The Sathorn-Silom central business district hosts the densest cluster of specialty retail and dermatology clinic partnerships.
Chiang Mai
Chiang Mai's urban millennials adopt premium concentrated actives at triple the rate of provincial mass-market alternatives. The Thailand Board of Investment extends tax privileges for biotechnology R&D facilities targeting domestic active ingredient production. Nimmanhaemin Road anchors the city's emerging experiential retail corridor for sensorial texture sampling.
Phuket
Phuket's tourism-dependent economy sustains demand for travel-sized sunscreens and resort-channel distribution. The ASEAN Cosmetics Directive enables compliant Thai manufacturers to distribute into Indonesian and Vietnamese markets without reformulation. Patong and Laguna resort clusters concentrate duty-free and hospitality procurement relationships.
Eastern Economic Corridor
Rayong and Chonburi provinces host underutilized manufacturing capacity for tropical-stability formulation science. Thailand's FDA safety assessment protocols compress product development timelines while elevating standards for biotech-derived ingredients. The Map Ta Phut industrial zone attracts foreign investment in cosmetic chemist training programs.
Northeast Region
Khon Kaen and Udon Thani exhibit underpenetrated professional skincare demand relative to Bangkok saturation. Local herbal formulations using turmeric and tamarind extracts compete with synthetic actives on price resonance. Traditional pharmacy channels resist inventory digitization, creating data blind spots in consumer preference tracking.
Thailand Skin Care Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in active ingredient supply. Thailand's skin care market structures around three tiers: multinational conglomerates with direct-to-consumer infrastructure, regional pharmacy-anchored portfolios, and domestic challengers leveraging local FDA relationships. Two dominant competitive moves define current positioning: subscription commerce models capturing recurring revenue from millennial cohorts, and backward integration into biotech R&D facilities qualifying for Board of Investment incentives.
Among French-headquartered platform integrators, L'Oréal S.A. exemplifies the data-capture archetype through first-party consumer analytics on Bangkok beauty shoppers. Beiersdorf AG anchors the pharmacy-trust tier, while Kao Corporation occupies a position emphasizing sensorial texture specialization for tropical humidity conditions. These three represent distinct strategic postures: data-centric DTC, traditional channel loyalty, and climate-adaptive formulation science.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Beiersdorf AG |
| Kao Corporation |
| The Estée Lauder Companies Inc. |
| Shiseido Company Limited |
| Unilever PLC |
| Procter & Gamble |
| Mistine |
| Do Day Dream Plc. |
| Others |
Pricing and Supply Chain Analysis
The Strait of Malacca shipping corridor channels over seventy percent of Thailand's active ingredient imports from South Korea and Japan, with freight cost volatility compressing margins for premium serum formulators while enabling sharp price differentiation between mass-market moisturizers and concentrated actives. This logistics chokepoint concentrates supply risk in Bangkok's formulation hubs, forcing downstream pricing stratification that separates pharmacy-anchored trust premiums from subscription-driven digital discounts.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships, with three-tier pricing separating premium serums from standard moisturizers from economy cleansers. Price differentiation rests on brand heritage certification and vertical integration depth, with domestic manufacturers commanding loyalty premiums through established FDA testing relationships. Pricing pressure stems from yen and won currency volatility on imported niacinamide and hyaluronic acid, tightening margins most acutely for mid-tier entrants lacking backward integration. Professional working women in Bangkok show lowest price sensitivity for photoprotection actives, while rural teen segments drive volume through promotional elasticity.
Supply Chain Analysis
Contract-manufacturing concentration clusters in Rayong and Chonburi provinces, with Map Ta Phut industrial zone hosting tropical-stability formulation specialists and domestic R&D facilities qualifying for Board of Investment incentives. Raw material dependencies draw from South Korean biotech fermenters, Japanese specialty chemical houses, and local turmeric and tamarind extractors in Northeast provinces. Single-source vulnerability runs through the Malacca Strait for Northeast Asian actives, compounded by extended FDA safety assessment timelines. Distribution runs through pharmacy partnerships for trust-based purchases, direct-to-consumer platforms for millennial subscription conversion, and resort channels for Phuket tourism procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's skin care market reaches a platform-economics inflection where AI-enabled skin diagnostics and subscription commerce interoperability reshape how value captures from discovery through repurchase. Ecosystem integration between dermatology clinics, pharmacy chains, and direct-to-consumer platforms determines which portfolios secure sustained data access and regimen loyalty.
For Market Incumbents: Build data moat defenses through first-party analytics integration across Bangkok's dermatology clinic partnerships and pharmacy loyalty programs. Deepen backward integration into biotech R&D facilities under Board of Investment incentives to reduce yen and won exposure on imported actives. Consolidate position by acquiring domestic formulation houses with established FDA testing relationships, neutralizing emerging local challengers before they scale subscription infrastructure.
For New Entrants and Emerging Players: Mid-market professional women in Chiang Mai and Phuket represent the most penetrable entry point, with underpenetrated demand for AI-enabled regimen personalization relative to Bangkok saturation. Male grooming whitespace in cleansers and moisturizers offers stigma-reduction positioning with lower competitive density than female-core segments. Go-to-market through influencer referral loops on short-form video platforms compresses customer acquisition costs versus legacy broadcast-dependent incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates seeking to divest non-core tropical-climate portfolios lacking ASEAN Cosmetics Directive compliance infrastructure. Long-term viability favors domestic manufacturers with integrated FDA relationships and biotech R&D tax privileges over pure-import brands exposed to registration timeline compression. Watch for inflection in Thailand Board of Investment incentive expansion toward active ingredient production, signaling policy-driven supply chain relocalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biotech R&D | Board of Investment tax privileges reduce imported active dependency from South Korea and Japan. |
| AI Skin Diagnostic Platform Launch | Bangkok dermatology clinics deploy camera-based analysis to compress trial-and-error purchase cycles. |
| Subscription Commerce Infrastructure | Recurring delivery models capture lifetime value from millennial consumers through influencer referral loops. |
| ASEAN Cosmetics Directive Compliance | Harmonized labeling enables cross-border distribution into Vietnam and Indonesia without reformulation costs. |
| Regional Distribution Partnership | Chiang Mai and Phuket whitespace offers pharmacy and experiential retail expansion beyond Bangkok saturation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA cosmetic registration filings, ASEAN Cosmetics Directive harmonization protocols, and Thailand Board of Investment incentive disclosures. Primary interviews engaged brand managers at multinational conglomerates, category buyers at pharmacy chains, supply planners at contract manufacturers, and regulatory affairs leads navigating Ministry of Public Health protocols. Secondary validation drew from customs import records for active ingredients, Nielsen retail audit data, and SEC filings of listed parent companies. Bottom-up SKU-level demand modeling triangulates against top-down category spend estimates across the analysis window.
Forecast inputs incorporate product type velocity, end-user segment expansion rates, and channel shift dynamics between pharmacy, online, and specialty retail. Segmentation dimensions span formulation complexity, climate adaptation requirements, and regional regulatory cluster alignment. CAGRs derive from installed base turnover analysis and trial conversion investment curves, with specific weighting for biotech ingredient penetration and subscription commerce adoption. Tropical-stability science capability scarcity and FDA timeline compression feature as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in baht volatility, Malacca Strait shipping disruptions, or South Korean and Japanese supplier pricing would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline stability and millennial digital adoption sustaining current velocity. Quarterly review of FDA registration backlog indicators, Board of Investment incentive utilization rates, and influencer platform engagement metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
Indonesia Skin Care Products Market
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
Nail Polish Market
Cosmetics & Skincare
Makeup Remover Pen Market
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
North America Bath Soap Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Foundation Cream Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Pillow Spray Market