
 Global Elastomers Market | 2026-2036
Global Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elastomers Market Analysis
The EU Green Deal is rebalancing procurement priorities across European automotive supply chains, compelling compounders to reformulate with lower-carbon feedstocks. BASF SE leverages its integrated Verbund structure to secure bio-based butadiene pathways. Dow anchors North American TPU capacity through its Midland manufacturing complex. Lanxess AG specializes in high-performance EPDM grades for electric vehicle cooling systems.
Elastomers are polymeric materials exhibiting elastic recovery after deformation, with glass transition temperatures typically below room temperature and cross-link densities ranging from 10⁻⁴ to 10⁻⁷ mol/cm³. Manufacturers produce these compounds through emulsion polymerization, solution polymerization, or thermoplastic processing to deliver sealing, damping, and flexural functions across industrial and consumer applications. SBR and BR maintain mature volume positions in tire manufacturing where cost efficiency dominates procurement criteria. TPU captures accelerated growth in medical device tubing and wearable electronics where optical clarity and biocompatibility command premium positioning. EPDM sheet and extrusion forms serve infrastructure waterproofing segments with extended replacement cycles that stabilize margin pools.
REACH in Europe, EPA emissions standards in the United States, and China's MEE environmental compliance protocols are elevating testing burdens and reformulation costs for cross-border suppliers. The FDA enforces biocompatibility thresholds for medical-grade elastomers that constrain raw material sourcing flexibility. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance-driven product obsolescence and redirect R&D investment toward certified sustainable feedstocks.
Market Dynamics
Automotive electrification is compressing traditional rubber demand while simultaneously opening high-value niches for thermal management-grade elastomers, forcing compounders to rebalance capacity between commodity tire polymers and engineered specialty grades.
Growth Catalysts
- EU Green Deal:The EU Green Deal mandates lifecycle emissions reductions across automotive supply chains, compelling OEMs to source lower-carbon EPDM and TPU compounds for under-hood components.
- Electric vehicle cooling systems:Battery thermal management architectures require high-performance elastomer seals and hoses that withstand glycol-based coolants across wider temperature ranges than internal combustion applications.
- China and India:Manufacturing hub concentration in China and India generates sustained demand for conveyor belts, vibration dampeners, and industrial hoses as capital goods production scales.
Market Restraints
- Butadiene price volatility:Synthetic rubber producers face margin compression from naphtha-derived butadiene feedstock swings tied to crude oil benchmarks and refinery operating rates.
- Supply concentration in Northeast Asia:Styrene-butadiene rubber capacity clusters in China, South Korea, and Japan create geographic risk exposure for European and North American tire manufacturers.
- Natural rubber substitution ceiling:Technical limitations in tire sidewall applications prevent full displacement of Hevea brasiliensis-sourced natural rubber despite synthetic alternatives.
Strategic Opportunities
- Medical device tubing:Thermoplastic polyurethane optical clarity and biocompatibility properties unlock premium positioning in catheter and wearable sensor applications.
- Germany automotive engineering:German OEM supplier networks seek certified sustainable feedstocks to meet Scope 3 emissions targets under CSRD reporting requirements.
- 3D printing convergence:Photopolymerizable elastomer resins combined with multi-material extrusion enable patient-specific prosthetics and rapid tooling for low-volume automotive parts.
Industry Challenges
- REACH compliance timelines:European compounders face extended certification cycles for novel bio-based monomers under ECHA substance evaluation protocols.
- Specialized polymer engineering talent:Formulation chemists with expertise in dynamic vulcanization and reactor-grade TPU synthesis command scarcity premiums across the hiring market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elastomers Market |
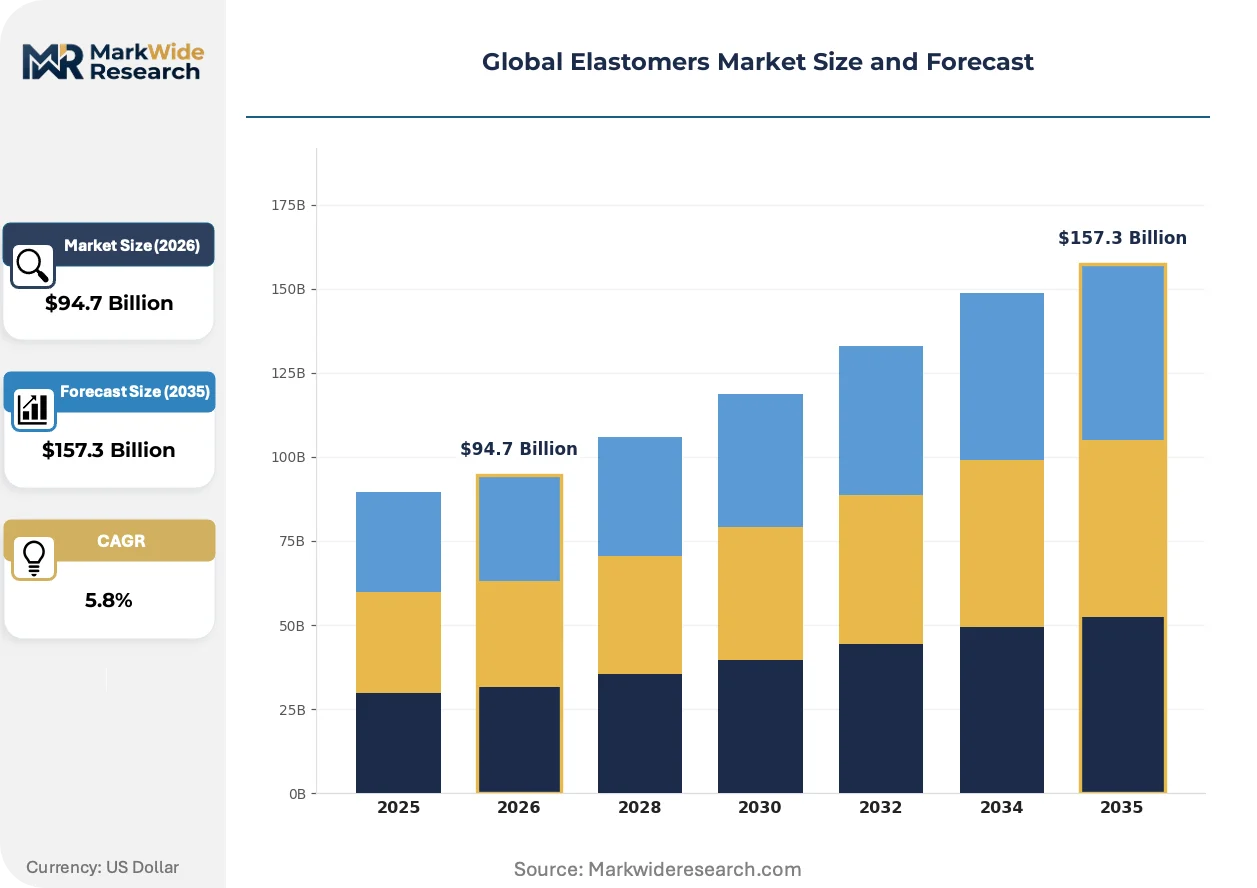
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $157.3 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBR, BR, TPU, EPDM Application: Automotive, Footwear, Medical, Consumer Goods End User: Manufacturers, Retailers, Wholesalers, Distributors Form: Sheets, Films, Foams, Extrusions |
| Companies Covered | BASF SE, Dow, DuPont de Nemours, Inc., ExxonMobil, Lanxess AG, Covestro AG, Huntsman Corporation, Arlanxeo, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elastomers Market Emerging Trajectories
Bio-based feedstock integration and advanced reactor technologies are reconfiguring production economics, while regulatory pressure on embodied carbon accelerates substitution toward circular material streams.
Thermoplastic vulcanizates are overtaking conventional EPDM in automotive weathersealing applications. These materials combine rubber-like elasticity with thermoplastic processability, enabling recycling and colorability. European and North American OEMs specify TPV grades for exterior trim at accelerating rates. The technology is overtaking compression-molded rubber in cost-sensitive sealing applications where weight reduction and manufacturing velocity outweigh legacy performance benchmarks.
REACH authorization requirements for polycyclic aromatic hydrocarbons in extender oils are tightening compound formulation standards. The regulation forces tire manufacturers to source alternative plasticizers and process oils. European production lines face the most acute compliance burden, with compounders accelerating migration to naphthenic and bio-based oil substitutes ahead of sunset date enforcement.
Automotive OEMs now specify full material disclosure and recycled content certificates upstream through tier-three suppliers. This behavioral shift fragments procurement authority from centralized purchasing to engineering-led sustainability teams. German and Swedish vehicle manufacturers enforce the strictest verification protocols, displacing spot-market raw material sourcing with multi-year offtake agreements tied to certified circular feedstock pools.
Global Elastomers Market Segmentation
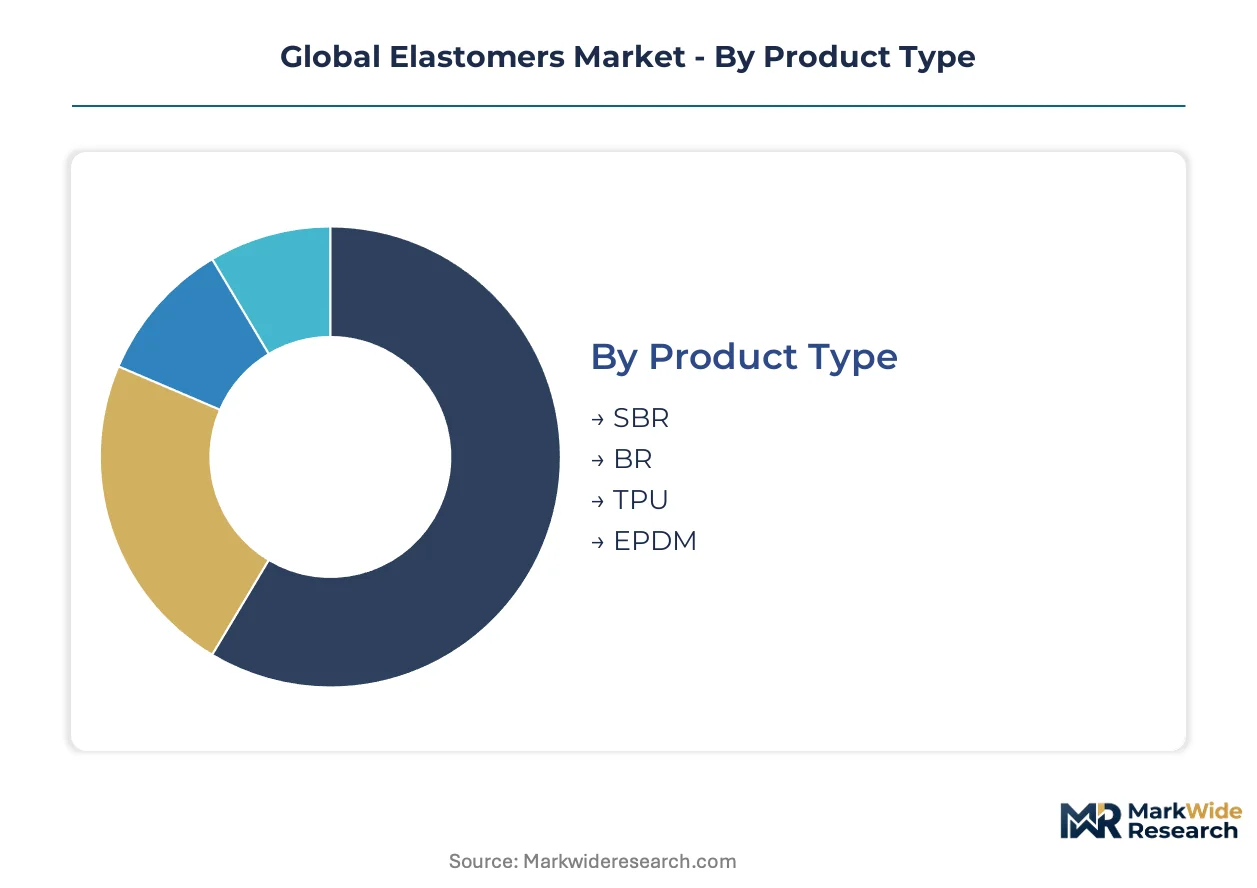
Product differentiation across the elastomers market determines pricing power and margin retention. Compounders align formulation investments with end-use performance thresholds and regulatory compliance burdens.
Product Type:
Replacement cycles vary dramatically across elastomer chemistries, with tire-grade commodities turning over faster than engineered specialties.
- SBR:Styrene-butadiene rubber dominates tire tread formulations through abrasion resistance and wet-grip balance. Chinese and Indian tire manufacturers absorb the majority of global SBR volume as vehicle production scales in these markets.
- TPU:Thermoplastic polyurethane delivers optical clarity and Shore hardness tunability from 70A to 75D. Medical device manufacturers in Germany and the United States specify TPU for catheter tubing where biocompatibility certification under FDA and MDR protocols commands premium positioning.
- BR:Polybutadiene rubber enhances tire sidewall resilience and low-temperature flexibility.
- EPDM:Ethylene-propylene-diene monomer compounds withstand ozone degradation and glycol-based coolants in automotive cooling systems.
Volume placements concentrate in SBR; the faster expansion belongs to TPU.
Application:
Cost tier stratification separates commodity automotive seals from certified medical devices and premium consumer goods.
- Automotive:Under-hood components demand thermal stability across -40°C to 150°C operating ranges. Battery electric vehicle architectures in Germany and China require EPDM and TPU seals for thermal management systems that handle wider temperature swings than internal combustion equivalents.
- Medical:Catheters, wound dressings, and wearable sensors require ISO 10993 biocompatibility validation. US and European device manufacturers source medical-grade TPU through qualified supplier programs with multi-year material disclosure obligations.
- Footwear:Midsole foams and outsoles utilize TPU and EVA blends for energy return and durability.
- Consumer Goods:Seals, grips, and flexible housings span price-sensitive mass-market applications.
Automotive commands the largest volume footprint; medical applications are climbing the fastest.
End User:
Procurement authority concentrates with direct manufacturers while distributors capture fragmented regional demand.
- Manufacturers:Tier-one automotive suppliers and medical device OEMs negotiate multi-year offtake agreements with certified feedstock documentation. German automotive suppliers enforce CSRD-aligned Scope 3 reporting requirements that cascade to compounder selection criteria.
- Distributors:Regional stockists serve molders and fabricators with shorter lead times and technical support. Indian and Southeast Asian industrial distributors bridge supply gaps for small-to-mid-scale processors lacking direct polymer sourcing relationships.
- Retailers:Direct-to-consumer channels remain limited for unprocessed elastomer compounds.
- Wholesalers:Bulk intermediaries handle commodity SBR and BR flows to tire manufacturers.
Manufacturers dominate premium-grade procurement; distributors gain share in emerging market penetration.
Form:
Processing method determines scrap rates, colorability, and recyclability in end-use conversion.
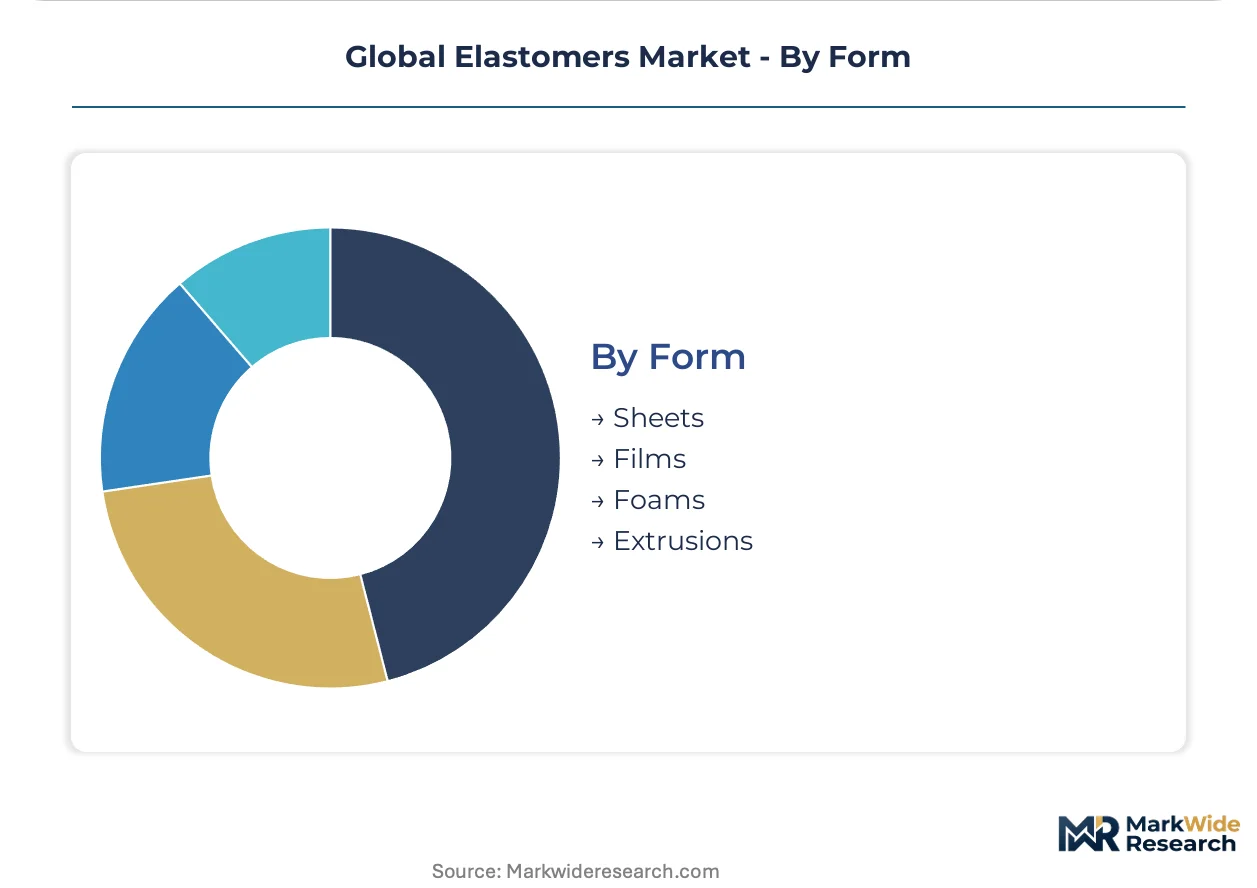
- Extrusions:Continuous profiles serve automotive weathersealing and industrial hose applications. European OEMs specify thermoplastic vulcanizate extrusions over compression-molded EPDM to enable in-process recycling and weight reduction targets.
- Sheets:Calendered goods supply roofing membranes and conveyor belting with extended replacement cycles. Chinese infrastructure investment sustains demand for EPDM sheet waterproofing in commercial construction.
- Foams:Expanded TPU and rubber grades deliver cushioning and acoustic dampening.
- Films:Thin-gauge TPU serves textile laminates and medical packaging with barrier properties.
Extrusions hold the broadest manufacturing footprint; sheet applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European elastomer compounding capacity, with production clusters extending into Belgium's Port of Antwerp chemical zone and Rotterdam's polymer logistics hub.
China
Shanghai and the Yangtze River Delta concentrate SBR and BR capacity serving domestic tire manufacturers. MEE environmental compliance protocols force facility upgrades at state-owned petrochemical complexes. Qingdao's rubber research institutes collaborate with compounders on high-performance EPDM grades for export markets.
Germany
Leverkusen and Ludwigshafen host integrated Verbund operations producing specialty TPU and EPDM compounds. EU Green Deal Scope 3 reporting requirements cascade through automotive supplier networks. Stuttgart's OEM engineering centers specify certified sustainable feedstocks for under-hood sealing applications.
United States
Houston's petrochemical corridor supplies butadiene feedstock to Gulf Coast synthetic rubber plants. EPA emissions standards elevate monitoring costs for styrene-butadiene production lines. Detroit's tier-one automotive suppliers source thermal management-grade elastomers for electric vehicle battery cooling architectures.
India
Gujarat's Dahej and Hazira industrial zones attract EPDM and TPU investments serving domestic automotive growth. BIS quality certification requirements constrain import flows from non-aligned jurisdictions. Pune's conveyor belt manufacturers sustain demand for abrasion-resistant rubber compounds as capital goods production scales.
Japan
Kawasaki and Yokkaichi chemical complexes produce high-purity BR grades for premium tire exports. METI carbon neutrality roadmaps pressure producers toward bio-based feedstock pilots. Nagoya's automotive supplier ecosystem specifies medical-grade TPU for wearable sensor applications in aging-care devices.
Global Elastomers Market Vendor Landscape
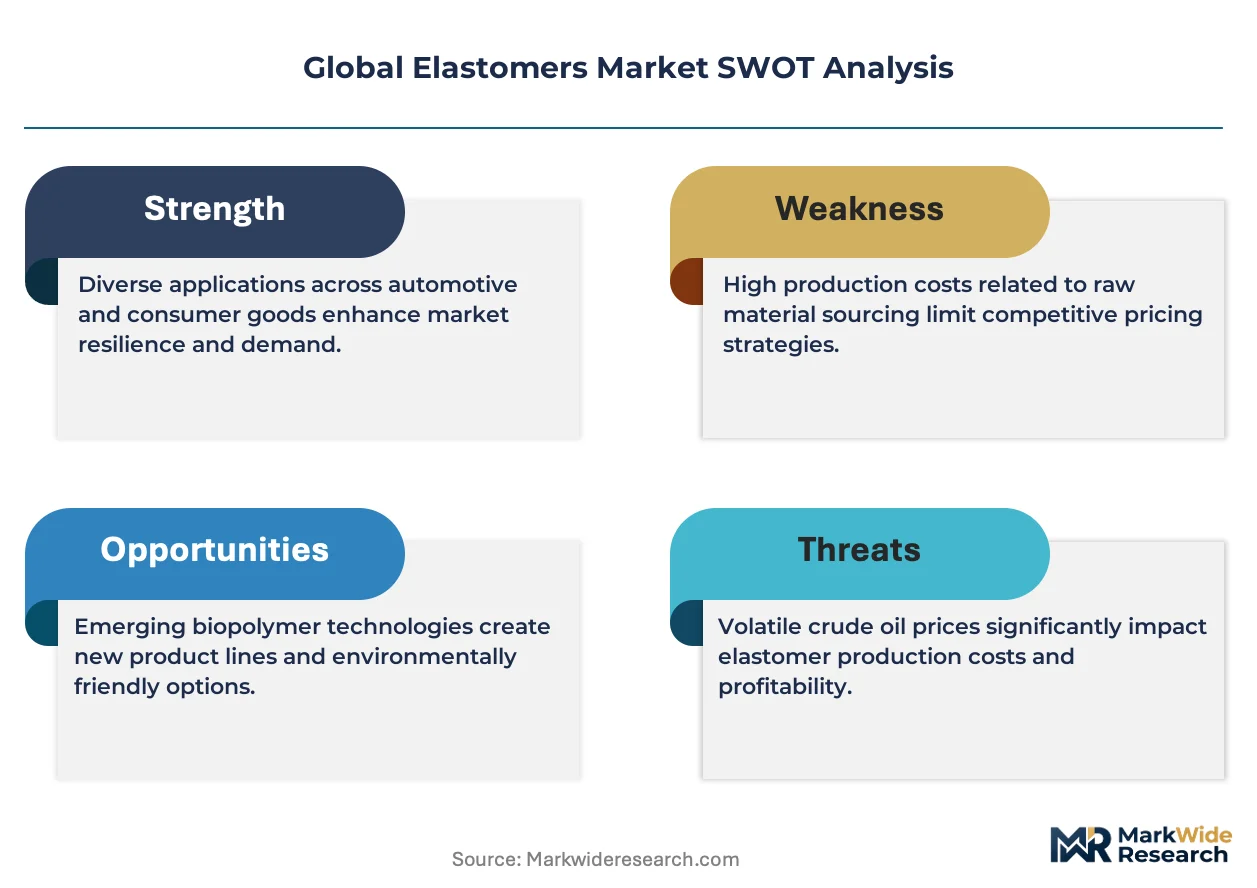
The competitive structure tilts toward integrated chemical conglomerates with captive feedstock positions. BASF SE and Dow exemplify this archetype, leveraging backward integration into butadiene and polyol supply chains. Three archetypes dominate: petrochemical majors with Verbund economics, specialized polymer compounders serving automotive certification programs, and regional tire-grade producers competing on volume scale. Capacity expansion and portfolio diversification toward medical-grade specialties represent the dominant competitive vectors.
Among European-headquartered producers, BASF SE, Lanxess AG, and Covestro AG occupy positions across the specialty elastomer spectrum. BASF SE exemplifies the integrated petrochemical archetype through its Ludwigshafen manufacturing complex. Lanxess AG represents the automotive-focused compounder segment with dedicated EPDM capacity for thermal management applications. Covestro AG anchors the high-performance TPU tier serving medical device and industrial coating end-uses.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| DuPont de Nemours, Inc. |
| ExxonMobil |
| Lanxess AG |
| Covestro AG |
| Huntsman Corporation |
| Arlanxeo |
| Asahi Kasei Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed petrochemical conglomerates in China and the Middle East anchor global elastomer capacity, deploying state-financed expansion programs that compress margins for privately held European compounders. Their below-cost export pricing during oversupply cycles forces specialty producers toward certified sustainable grades where buyer lock-in sustains premium realization.
Pricing Analysis
Outcome-based pricing tied to thermal management system uptime anchors premium tiers in electric vehicle cooling applications. Three-tier pricing structure across medical-grade, automotive-certified, and industrial-standard levels separates TPU catheter compounds commanding biocompatibility premiums from commodity SBR tire formulations. Pricing pressure stems from naphtha-derived butadiene feedstock volatility linked to refinery operating rates. Tire manufacturers exhibit acute price sensitivity, while medical device OEMs absorb premium positioning for FDA-validated material streams.
Supply Chain Analysis
Scrap TPU regrind flows and EPDM weathersealing refurbishment programs are gaining traction as German OEMs mandate recycled content verification through tier-three suppliers. Manufacturing gravity centers on China, South Korea, and Japan for SBR and BR tire polymers, with Germany and the United States anchoring specialty TPU and EPDM compounding. Feedstock chains draw from crude oil derivatives, bio-based butadiene pilots, and naphthenic process oils. Single-source vulnerability concentrates in Northeast Asian butadiene extraction capacity. Distribution runs through qualified supplier programs for medical grades and regional stockists for industrial compounds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty elastomer supply is tightening around certified sustainable feedstock pools, with European bio-based butadiene capacity constraints propping pricing for compliant grades. This supply-constrained structure favors incumbents with validated circular material streams.
For Market Incumbents: Acquire bio-based feedstock certification assets and reactor-grade TPU synthesis capabilities to defend against emerging biopolymer compounders. Backward integration into pyrolysis-derived butadiene streams secures margin protection from petrochemical volatility. Lanxess AG's dedicated EPDM thermal management lines demonstrate how automotive certification depth creates switching-cost moats. For New Entrants and Emerging Players: EU Green Deal Scope 3 reporting requirements in Germany open a window for regional bio-based compounders with verified carbon accounting. Medical device tubing in the United States offers the most penetrable white space, with qualified supplier program entry less capital-intensive than automotive tier-one certification. Lead with optical clarity TPU grades for wearable sensor applications where incumbent response lags. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale German compounders with CSRD-aligned feedstock documentation but strained working capital from REACH compliance costs. Five-to-ten-year viability hinges on automotive electrification sustaining thermal management elastomer premiums. Monitor MEE enforcement actions in China for signals of supply rationalization that would lift global SBR pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | BASF SE's Verbund structure secures lower-carbon butadiene pathways ahead of EU Green Deal enforcement. |
| Medical-Grade TPU Capacity Expansion | Covestro AG anchors high-purity optical clarity production for FDA-cleared catheter applications. |
| Long-Term Automotive Supply Agreement | Dow's Midland complex locks in thermal management elastomer offtake with Detroit tier-one suppliers. |
| Green Manufacturing Transition | Arlanxeo deploys bio-based EPDM grades to meet German OEM Scope 3 emissions targets. |
| Joint Venture in Emerging Production Hub | Asahi Kasei Corporation partners in Gujarat's Dahej zone to capture Indian automotive growth. |
Methodological Framework
Multi-period observation of butadiene feedstock spreads, REACH authorization timelines, and automotive platform electrification roadmaps anchored the trend analysis, supplemented by interviews with compounder plant managers, Tier 1 automotive procurement leads, medical device regulatory affairs directors, and distribution channel partners across Europe, North America, and Asia. Secondary validation drew from ECHA substance evaluation databases, SEC 10-K petrochemical segment disclosures, customs trade flow records, and IHS Markit vehicle production data. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Segment-weighting across product type, application, end-user category, and regional production hub shaped the analytical framework across the analysis window. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories. Model inputs incorporated electric vehicle thermal management content per vehicle, medical device tubing penetration curves, and infrastructure waterproofing replacement cycle patterns.
The model assumes a particular technology adoption path for thermoplastic vulcanizates displacing compression-molded EPDM; alternative pathways for hydrogenated nitrile rubber would alter the outlook for high-temperature sealing applications. Practitioners should monitor MEE carbon intensity enforcement in China, FDA biocompatibility guidance revisions, and German CSRD reporting granularity for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Roller Cleaner Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Silicone Rubber Market
Rubber
Natural Rubber Market
Rubber
Hospital Rubber Sheet Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Rubber Bulbs Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Synthetic Rubber Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Europe Rubber Hose Market
Rubber
Rubber Rollers Market
Rubber
Polybutadiene Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Abrasion-Resistant Rubber Pipe Market