
 Global Fidget Toys Market | 2026-2036
Global Fidget Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fidget Toys Market Foresight
Adult professionals and therapeutic users is reorganizing demand away from impulse-driven children's purchases toward sustained wellness-oriented consumption. Spin Master Ltd. leverages its established retail partnerships and entertainment licensing infrastructure to maintain shelf presence across mass-market channels. ZURU Inc. competes through aggressive speed-to-market and automated manufacturing scale that compresses production cycles for trend-responsive items. Tangle Creations specializes in continuous-loop geometric designs that occupy the sensory therapy niche with products developed in consultation with occupational practitioners.
Fidget toys encompass handheld manipulative objects engineered with weighted bearings, elastic resistance elements, or textured surfaces designed to channel repetitive motion and tactile stimulation for cognitive regulation. Most commercial variants incorporate ABS plastic housings with steel or ceramic ball bearings achieving 2-5 minute spin durations, while therapeutic-grade models utilize food-safe silicone meeting ISO 10993 biocompatibility standards for oral motor applications. The product type dimension shows spinners and cubes commanding mature volume positions, whereas poppers and rollers capture faster incremental growth through school and clinical procurement channels. Material segmentation reveals silicone ascending as the premium substrate due to durability and washability advantages, even as plastic retains cost-driven dominance in disposable and promotional segments.
ISO 8124 toy safety standards, EU REACH chemical restrictions, and U.S. Consumer Product Safety Commission small-parts regulations collectively govern material composition, age-grading disclosures, and choke-hazard labeling across export markets. FDA oversight applies to devices marketed with explicit therapeutic claims, creating a compliance bifurcation between general wellness positioning and regulated medical device classification. Stakeholders must monitor evolving classification precedents where sensory tools blur into assistive technology, as reimbursement eligibility and channel access hinge on regulatory positioning decisions.
Market Dynamics
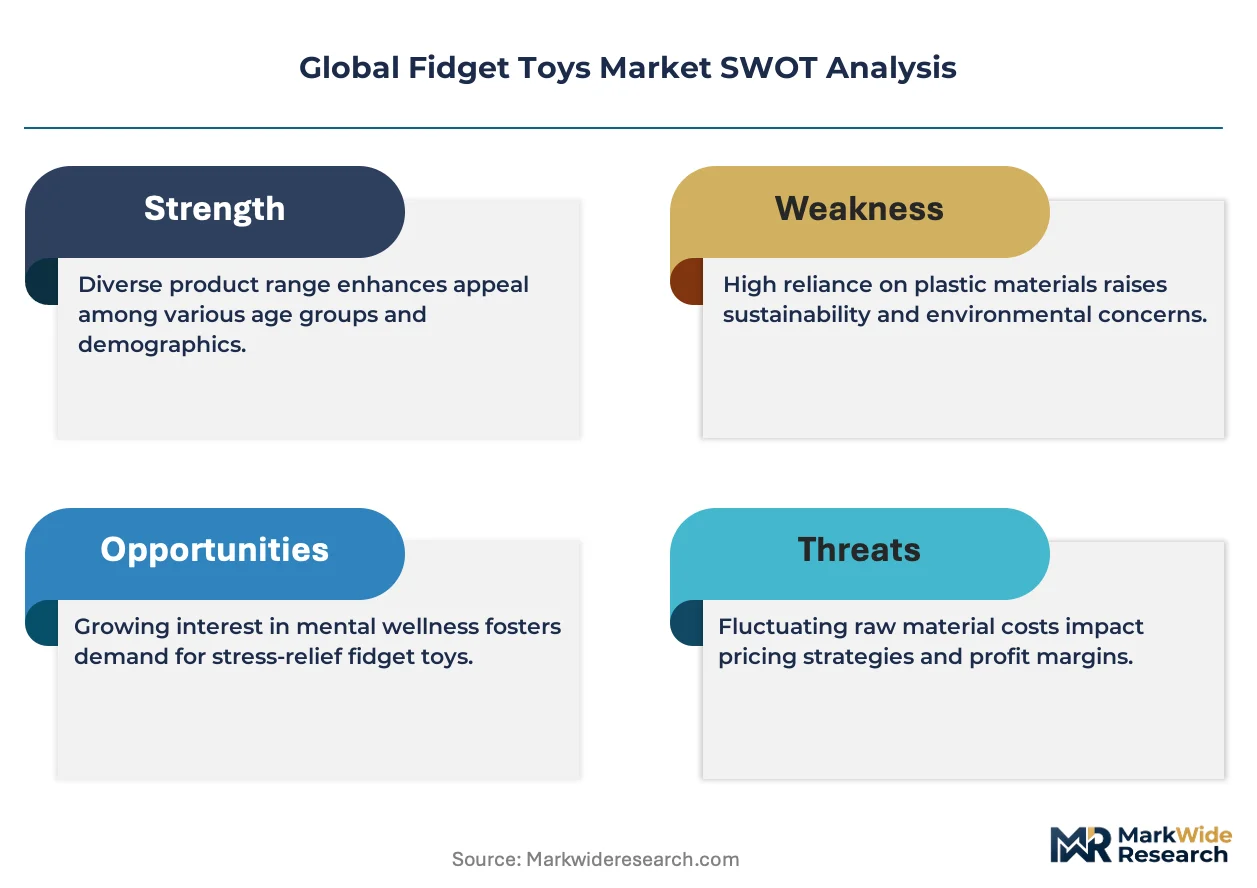
REACH compliance in the European Union is decomposing material supply chains, forcing manufacturers toward medical-grade silicone substitution and bifurcating product portfolios between regulated therapeutic claims and general wellness positioning.
Growth Catalysts
- Occupational therapy integration:Clinical procurement channels in the United States now route fidget tools through licensed practitioner networks, creating institutional demand stability absent from impulse retail.
- Corporate wellness mandates:HR departments at Fortune 500 firms are adding sensory regulation devices to standardized desk ergonomics programs, normalizing adult professional usage.
- ISO 10993 biocompatibility certification:Food-safe silicone formulations meeting this standard unlock oral motor therapy applications previously restricted to medical device classifications.
Market Restraints
- Petrochemical feedstock volatility:ABS plastic resin prices fluctuate with crude oil indices, compressing margins on mass-market spinner and cube variants.
- Single-supplier bearing concentration:Ceramic ball bearing production concentrates in East Asian precision manufacturing clusters, creating geographic supply vulnerability.
- FDA classification friction:Devices with explicit therapeutic claims face 510(k) clearance timelines that extend commercialization by 18-24 months versus general wellness positioning.
Strategic Opportunities
- Underpenetrated German clinical procurement:Occupational therapy reimbursement codes in Germany remain unsettled, creating first-mover advantage for compliant product entrants.
- Direct-to-consumer subscription models:E-commerce platforms bypass retail slotting fees and capture recurring revenue through sensory tool curation services.
- EU Green Deal material incentives:Bio-based silicone research grants accelerate development of petroleum-free substrates qualifying for circular economy procurement preferences.
Industry Challenges
- ISO 8124 testing backlog:Third-party laboratory capacity constraints delay toy safety certification by 8-12 weeks, compressing seasonal product launch windows.
- Design patent thickets:Continuous-loop geometric configurations face overlapping intellectual property claims from established sensory therapy specialists.
- Cross-border labeling harmonization:Divergent small-parts warnings between U.S. Consumer Product Safety Commission and EU member state requirements force SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fidget Toys Market |
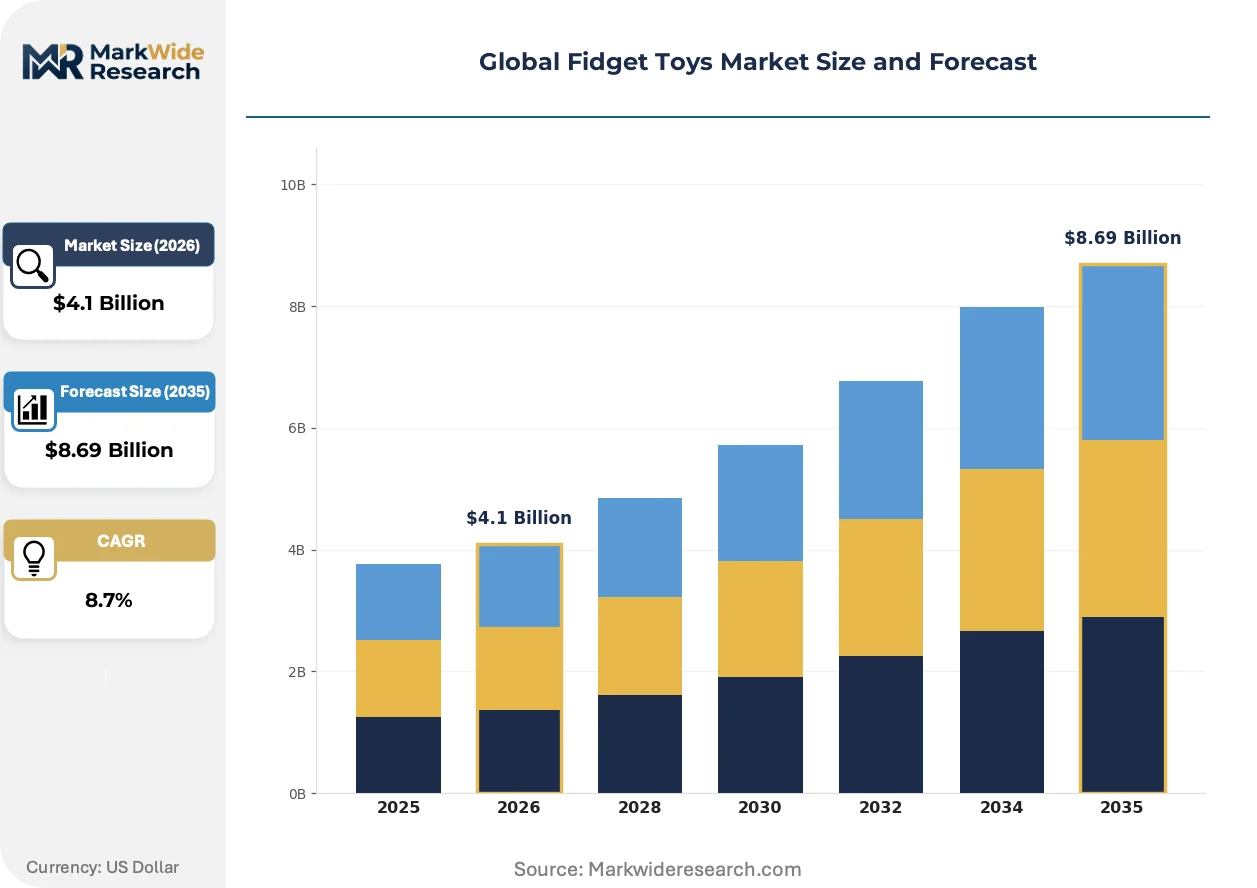
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinner, Cube, Ball, Roller, Popper, Ring Material: Plastic, Metal, Silicone, Wood, Rubber, Foam Application: Stress Relief, Focus Improvement, Sensory Therapy, Entertainment, Anxiety Reduction, Motor Skills Development End User: Children, Teenagers, Adults, Educators, Therapists, Collectors |
| Companies Covered | Spin Master Ltd., ZURU Inc., Fidgetland, Tangle Creations, Hasbro Inc., Tom's Fidgets, CAVN, DINGJIN, ThinkFun Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fidget Toys Market Shifts & Advancements
Material science advances and regulatory classification debates are fragmenting product architectures, separating disposable trend-responsive items from durable clinical-grade equipment with divergent technical specifications and channel strategies.
Magnetic haptic feedback systems are decomposing the traditional bearing-centric design paradigm. These systems utilize rare-earth magnet arrays to create adjustable resistance profiles without mechanical wear points. Occupational therapy clinics in Australia and Canada are piloting programmable resistance devices for personalized sensory protocols. The technology is decomposing price-performance tradeoffs that previously locked clinical procurement into premium mechanical bearings.
ECHA substance of very high concern listings are accelerating silicone purity documentation requirements. Manufacturers must now maintain full supply chain chemical disclosure records extending to raw material catalyst residues. Pediatric oral motor applications face the strictest scrutiny, with German and French market surveillance authorities conducting random migration testing at port of entry.
Licensed practitioner endorsement is displacing social media virality as the primary demand generation mechanism. School district procurement offices now require American Occupational Therapy Association product validation before bulk purchase authorization. This behavioral pivot concentrates volume with established clinical supply distributors rather than direct-to-consumer platforms, compressing margin structures but extending contract durations.
Global Fidget Toys Market Segmentation
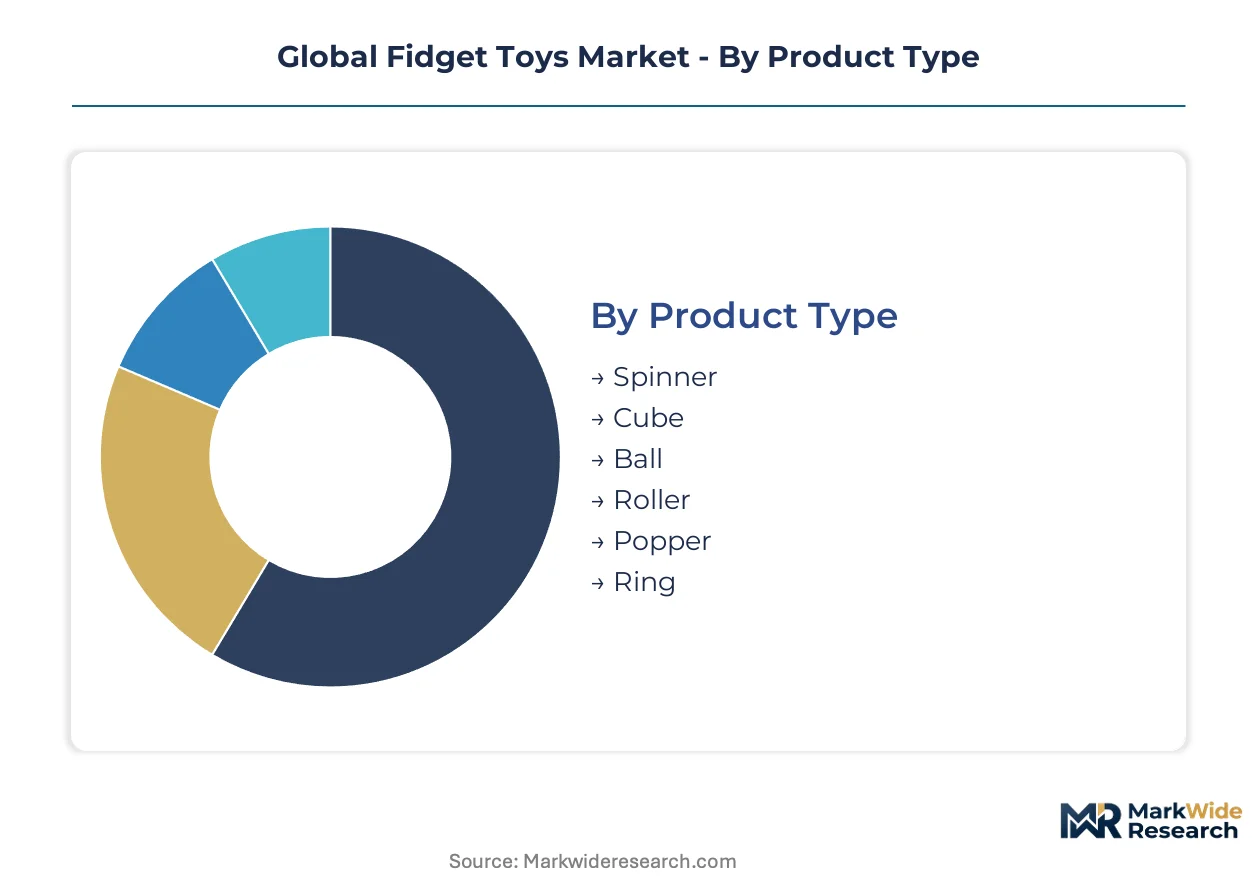
Segmentation in the fidget toys market separates impulse-driven retail commodities from durable clinical equipment with divergent certification requirements and margin structures. Channel strategy fundamentally differs across these divides, with mass-market spinners flowing through big-box retail while sensory therapy tools route through licensed practitioner networks.
Product Type:
Channel mix varies sharply by product architecture, with bearing-centric designs dominating brick-and-mortar shelf space while continuous-loop geometries concentrate in clinical procurement catalogs.
- Spinner:ABS plastic housings with steel or ceramic ball bearings achieve 2-5 minute rotation durations. Mass-market retail in the United States captures volume through big-box seasonal programs, though margin compression from petrochemical feedstock volatility constrains profitability.
- Cube:Multi-axis mechanical switches and joysticks provide discrete tactile feedback without rotational motion. Corporate wellness procurement channels in Germany and Canada route these through office supply distributors for desk ergonomics programs.
- Ball:Spherical grip strengtheners with elastic resistance elements target motor skills development. Pediatric occupational therapy clinics in Australia favor these for oral motor applications requiring ISO 10993 biocompatibility.
- Roller:Cylindrical textured surfaces with internal bearings enable one-handed manipulation. School district bulk purchasing in the United States drives institutional adoption through American Occupational Therapy Association validation requirements.
- Popper:Silicone bubble arrays with reversible suction action provide auditory and tactile feedback. Direct-to-consumer e-commerce platforms capture this segment through subscription curation services bypassing retail slotting fees.
- Ring:Wearable continuous-loop designs permit discreet sensory regulation during professional settings. Fashion-accessory positioning in Japanese and South Korean markets differentiates these from clinical-grade alternatives.
Spinners dominate installed base through early viral adoption. Rollers and poppers are where expansion concentrates as school procurement and subscription models displace impulse retail.
Material:
Cost tier stratification separates disposable promotional items from durable clinical equipment, with substrate selection determining washability, biocompatibility certification, and circular economy procurement eligibility.
- Plastic:ABS and polypropylene housings retain cost-driven dominance in mass-market spinners and cubes. REACH compliance in the European Union is forcing substitution toward medical-grade alternatives for pediatric applications.
- Metal:Aluminum and stainless steel frames provide heft for adult professional usage. Corporate wellness programs in the United States favor these for desk ergonomics durability requirements.
- Silicone:Food-safe formulations meeting ISO 10993 standards unlock oral motor therapy applications previously restricted to medical device classifications. EU Green Deal research grants accelerate bio-based silicone development for circular economy preferences.
- Wood:Natural substrates appeal to sustainability-positioned segments in German and Austrian markets. Limited washability constrains clinical adoption despite environmental credentials.
- Rubber:Elastic resistance elements in grip strengtheners and stress balls. Price volatility links to synthetic rubber feedstock indices tied to crude oil markets.
- Foam:Lightweight compression toys for anxiety reduction in educational settings. Disposable positioning limits margin recovery despite high volume throughput.
Plastic commands volume share through cost accessibility. Silicone is climbing the fastest as regulatory compliance and clinical procurement reshape material specifications.
Application:
Customer type determines channel routing, with wellness-positioned applications flowing through direct-to-consumer platforms while therapeutic claims require practitioner endorsement and distributor relationships.
- Stress Relief:General wellness positioning avoids FDA 510(k) clearance timelines. Adult professionals in United States corporate programs drive sustained demand absent from children's impulse purchases.
- Focus Improvement:Cognitive regulation claims in educational settings require American Occupational Therapy Association validation. School district procurement offices mandate this endorsement before bulk authorization.
- Sensory Therapy:Explicit therapeutic claims face FDA classification friction extending commercialization by 18-24 months. Licensed practitioner networks in Canada and Australia concentrate volume with established clinical supply distributors.
- Entertainment:Collectible and licensed character positioning leverages entertainment industry partnerships. Social media virality remains primary demand generation for this segment.
- Anxiety Reduction:Wellness-adjacent positioning permits broader channel access than regulated therapeutic claims. Subscription curation services capture recurring revenue through personalized sensory tool matching.
- Motor Skills Development:Pediatric applications face strictest ECHA substance scrutiny with German and French port-of-entry testing. ISO 8124 toy safety certification creates third-party laboratory capacity bottlenecks.
Stress relief anchors volume through corporate wellness normalization. Sensory therapy is gaining share fastest as institutional procurement displaces retail volatility.
End User:
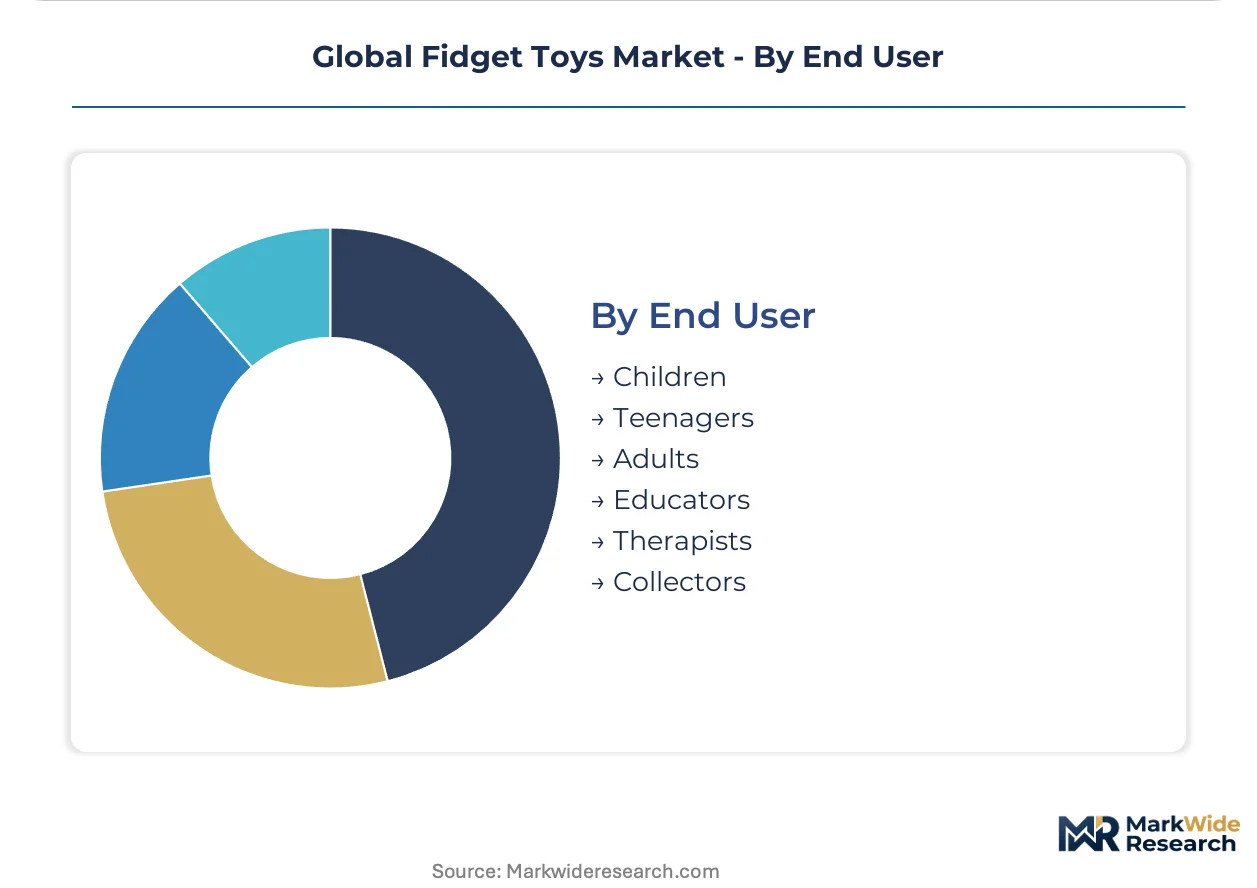
Volume concentration versus margin recovery splits across age demographics and professional roles, with adult professional adoption expanding average revenue per user while pediatric segments drive unit throughput.
- Children:Impulse-driven purchases through mass retail channels with high seasonality. Small-parts regulations from U.S. Consumer Product Safety Commission and EU member states force SKU proliferation for cross-border compliance.
- Teenagers:Social media trend responsiveness compresses product lifecycles. Speed-to-market manufacturing in East Asian clusters captures ephemeral demand before design saturation.
- Adults:Corporate wellness program integration normalizes professional usage. Fortune 500 HR departments add sensory regulation devices to standardized desk ergonomics programs.
- Educators:School district procurement requires clinical validation and bulk pricing structures. Contract durations extend volume stability despite compressed margins.
- Therapists:Licensed practitioner endorsement displaces viral marketing as primary demand mechanism. Reimbursement eligibility hinges on regulatory positioning between wellness and medical device classification.
- Collectors:Limited editions and licensed character variants command premium positioning. Entertainment industry partnerships extend product lifecycle through nostalgia and scarcity marketing.
Children retain unit volume leadership through retail accessibility. Adults and therapists are where margin expansion concentrates as institutional procurement stabilizes demand patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision bearing manufacturing clusters in East Asia supply the mechanical core of spinner and roller variants, while clinical-grade silicone formulation concentrates in German and North American chemical corridors. Demand-side expansion is fragmenting across institutional procurement channels that prioritize regulatory compliance over viral retail velocity.
United States
Corporate wellness mandates at Fortune 500 firms and school district occupational therapy integration drive institutional procurement. FDA 510(k) clearance timelines create compliance friction for therapeutic claims. Los Angeles and New York City logistics hubs route direct-to-consumer subscription volumes bypassing traditional retail slotting.
Germany
Occupational therapy reimbursement codes remain unsettled, creating first-mover positioning for compliant entrants. ECHA substance of very high concern listings accelerate silicone purity documentation requirements. Bavarian chemical corridors host medical-grade silicone formulation facilities serving pediatric oral motor applications.
China
East Asian precision manufacturing clusters concentrate ceramic ball bearing production for spinner variants. SAMR toy safety enforcement and GB standards compliance shape export-oriented production. Shenzhen and Dongguan electronics corridors automate speed-to-market manufacturing for trend-responsive items.
Australia
Occupational therapy clinics pilot programmable magnetic haptic feedback devices for personalized sensory protocols. TGA oversight applies to devices with explicit therapeutic positioning. Melbourne and Sydney clinical supply distributors concentrate volume with licensed practitioner networks.
Canada
Corporate wellness procurement channels route cube variants through office supply distributors for desk ergonomics programs. Health Canada PMRA regulations govern therapeutic marketing claims. Ontario and British Columbia school districts require clinical validation before bulk purchasing authorization.
Global Fidget Toys Market Competitive Landscape
Concentration sits with diversified toy conglomerates and specialized sensory therapy developers rather than pure-play fabricators. The vendor base spans entertainment licensing infrastructure, automated manufacturing scale, and clinical practitioner consultation networks. Three archetypes dominate: mass-market retail suppliers, clinical-grade specialists, and trend-responsive speed-to-market operators. Competitive moves center on regulatory positioning bifurcation and direct-to-consumer channel bypass of retail slotting fees.
Within the diversified conglomerate tier, Spin Master Ltd. and Hasbro Inc. occupy positions anchored by established retail partnerships and entertainment licensing infrastructure. ZURU Inc. exemplifies the speed-to-market archetype through automated manufacturing scale. Tangle Creations sits within the clinical specialist tier, representing continuous-loop geometric design expertise developed through occupational therapy practitioner consultation.
| Leading Market Players |
|---|
| Spin Master Ltd. |
| ZURU Inc. |
| Fidgetland |
| Tangle Creations |
| Hasbro Inc. |
| Tom's Fidgets |
| CAVN |
| DINGJIN |
| ThinkFun Inc. |
| Others |
Supply & Pricing Matrix
Automated manufacturing scale in Shenzhen and Dongguan compresses production cycles for trend-responsive items, concentrating cost advantages with speed-to-market operators while establishing price floors that mechanical-bearing specialists struggle to undercut. This scale asymmetry feeds into procurement channel bifurcation, where institutional buyers negotiate volume contracts against spot-market premiums in direct-to-consumer subscription tiers.
Pricing Analysis
Volume-discount tiering structures separate school district bulk procurement from individual subscription purchases, with clinical-grade silicone formulations commanding premium positioning against ABS plastic mass-market variants. Price differentiation rests on ISO 10993 biocompatibility certification and REACH compliance documentation, with German and French port-of-entry testing adding verification costs to pediatric oral motor applications. Cost compression in plastic spinner segments intensifies from petrochemical feedstock volatility, while corporate wellness programs show least price sensitivity for desk ergonomics durability requirements.
Supply Chain Analysis
China anchors precision manufacturing for ceramic ball bearings and automated assembly systems, while Germany and the United States concentrate medical-grade silicone formulation for clinical-grade outputs. Raw material dependencies span ABS plastic resin, rare-earth magnet arrays, and food-safe silicone catalysts. Single-supplier bearing concentration in East Asian clusters creates geographic supply vulnerability. Distribution runs through licensed practitioner networks for therapeutic claims and direct-to-consumer platforms for wellness-positioned items.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins compress as subscription curation services and practitioner endorsement programs expand recurring-revenue layers faster than unit sales, transforming competitive advantage toward service-attach depth.
For Market Incumbents: Shield market position through backward integration into medical-grade silicone formulation and exclusive distribution agreements with American Occupational Therapy Association validators. Certification investment in ISO 10993 and REACH documentation creates switching costs against speed-to-market challengers. Channel control through clinical supply distributors extends contract durations despite margin compression. For New Entrants and Emerging Players: Subscription-layer personalization gaps in sensory tool curation services offer white-space entry points, with German occupational therapy reimbursement code uncertainty representing the most penetrable geography. Direct-to-consumer platforms bypass retail slotting fees and capture recurring revenue through algorithmic matching protocols. Practitioner co-development partnerships accelerate clinical validation timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinical-grade specialists with regulatory documentation infrastructure over trend-responsive assemblers. Long-term viability hinges on reimbursement eligibility expansion across pediatric and adult therapeutic applications. Magnetic haptic feedback patent filings signal inflection toward programmable resistance platforms.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Certification Investment | Unlocks oral motor therapy applications previously restricted to medical device classifications. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees and captures recurring revenue through personalized curation algorithms. |
| Clinical Practitioner Partnership | American Occupational Therapy Association validation displaces viral marketing as primary demand mechanism. |
| EU Green Deal Material Transition | Bio-based silicone research grants accelerate petroleum-free substrate development for circular economy procurement. |
| Magnetic Haptic Feedback Patent | Programmable resistance devices decompose price-performance tradeoffs locking clinical procurement into mechanical bearings. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, ECHA substance registrations, and school district procurement databases, with bottom-up manufacturer interviews and top-down trade flow analysis triangulating volume estimates. Stakeholder consultations spanned occupational therapy practitioners, clinical supply distributors, corporate wellness program managers, and automated manufacturing operators. Primary insights were validated against U.S. Consumer Product Safety Commission recall data, EU market surveillance authority inspection reports, and direct-to-consumer platform transaction records.
Segmentation dimensions modeled include product architecture, material substrate, application positioning, and end-user demographic across the projection horizon. CAGRs were derived from installed base growth rates and replacement cycle analysis, with pricing trajectories informed by petrochemical feedstock indices and regulatory compliance cost structures. Forecast inputs incorporated reimbursement code adoption patterns in Germany and practitioner endorsement velocity in North American school districts.
Forecasts assume regulatory continuity in FDA classification precedents and ECHA substance listings; material policy shifts would require re-modeling of commercialization timelines and channel access assumptions. Recalibration cycles align with material shifts in reimbursement eligibility determinations and magnetic haptic feedback technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Bubble Tubes Market
Toys and Games
Coaster Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
US BDSM Sex Toys Market
Toys and Games
Cat Toys Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Toy Collectibles Market
Toys and Games
Inflatable Toys Market
Toys and Games
Global Educational Toy Market
Toys and Games
Wooden Toys Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Kids Toys Market
Toys and Games
Orbital Action Jigsaw Market
Toys and Games
Plush Toy Market
Toys and Games
Ride-Ons Market