
 Glow Sticks Market | 2026-2036
Glow Sticks Market Size, Share, and Industry Trends Forecast 2026-2036
Glow Sticks Market Outlook
Bulk-packaging configurations for event planners is realigning procurement patterns across the glow sticks industry. Cyalume Technologies Inc. dominates military and emergency signaling channels with hardened product specifications. Lumica Corporation anchors festival supply chains across East Asia through specialized multi-color formats. Sinoglow Industrial Co. Limited competes on manufacturing scale, leveraging integrated polyethylene molding operations to control unit economics.
Glow sticks are sealed plastic tubes containing isolated oxalate ester and hydrogen peroxide solutions that chemiluminesce when mixed, typically emitting visible light for 4–12 hours through a non-toxic reaction catalyzed by a glass ampoule fracture. Standard glow sticks command the largest volume share in emergency preparedness kits, while UV glow sticks capture premium positioning in nightlife and entertainment venues where fluorescence under blacklight creates differentiated visual effects. Event supply shops and specialty stores remain the highest-margin distribution channel due to impulse purchasing dynamics at point-of-sale locations.
REACH and RoHS frameworks in Europe restrict phthalate content and mandate chemical disclosure, compelling reformulation of legacy dye carriers. The US Consumer Product Safety Commission enforces child-safety labeling and small-part standards that shape packaging design and retail access. Stakeholders must monitor evolving chemical substance restrictions across multiple jurisdictions to sustain market access and avoid reformulation costs.
Market Dynamics
Bulk-packaging configurations for event planners are realigning procurement patterns across the glow sticks industry, compressing order cycles and reshaping distributor relationships. REACH chemical compliance requirements in Europe are simultaneously elevating production standards and fragmenting supplier qualification.
Growth Catalysts
- Festival procurement in Germany:Outdoor events and music festivals across Bavaria and North Rhine-Westphalia are consolidating supplier relationships through multi-year framework agreements.
- REACH reformulation mandates:ECHA disclosure requirements for phthalate-free dye carriers are accelerating transitions to bio-based ester formulations in continental manufacturing.
- Multi-color chemiluminescence formats:Specialized wavelength-tuned products for blacklight venues are penetrating nightlife supply chains in Tokyo and Seoul.
Market Restraints
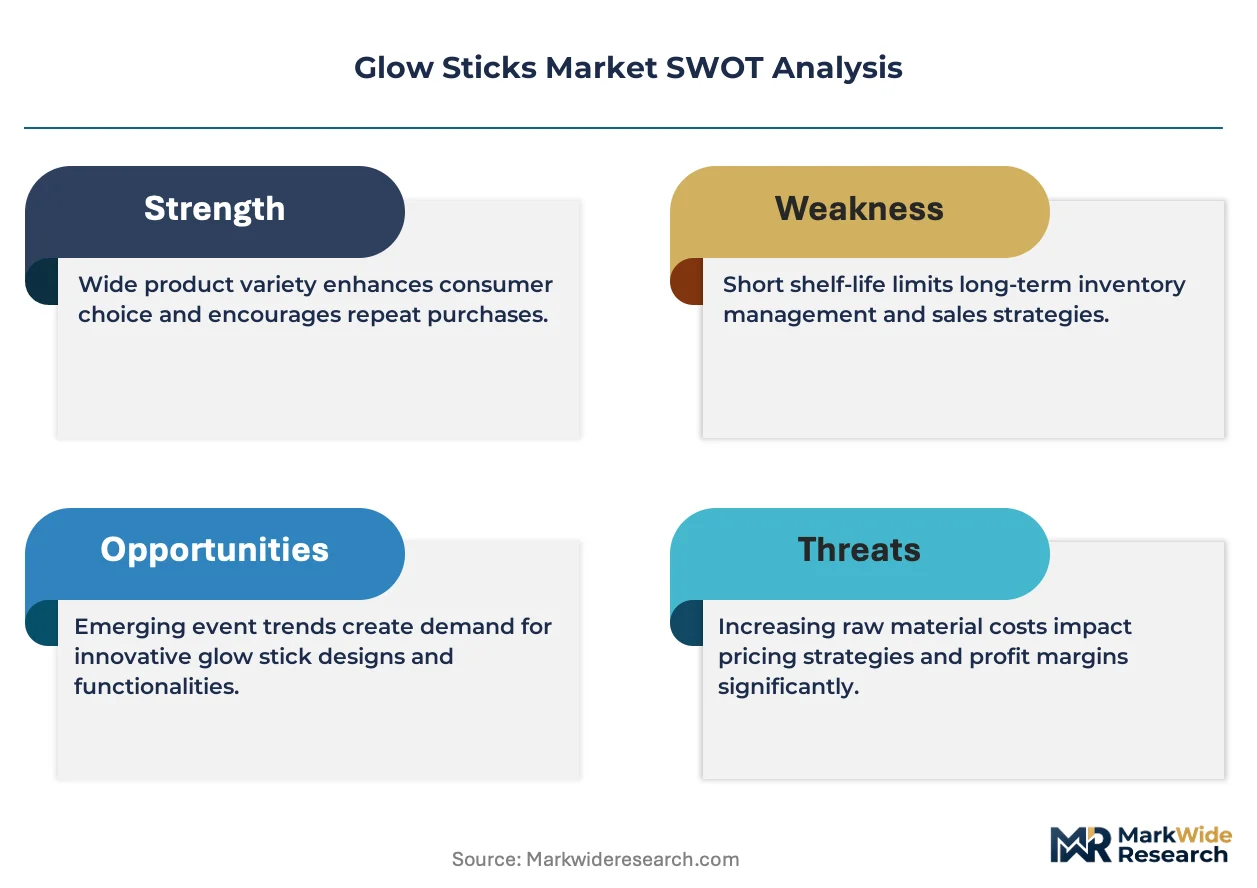
- Polyethylene feedstock volatility:Crude-linked resin costs create margin pressure for integrated molders dependent on spot-market ethylene.
- Single-source glass ampoule supply:Borosilicate fracture-vial production concentrates in China's Yangtze River Delta, exposing finished-goods assemblers to geographic concentration risk.
- LED substitution in emergency signaling:Solid-state alternatives with rechargeable powertrains are displacing chemical luminescence in military and first-responder kits.
Strategic Opportunities
- Reusable glow stick formats in France:Battery-powered LED-encapsulated designs are capturing premium positioning in Parisian event-decoration channels.
- Biodegradable shell polymers:PLA and PHA-based tubing formulations are converging with compostable-packaging mandates in municipal procurement codes.
- Direct-to-venue distribution platforms:Specialized e-procurement portals are disintermediating traditional wholesale distributors for mid-size festival operators.
Industry Challenges
- Chemiluminescence formulation chemistry expertise:PhD-level photochemistry talent scarcity constrains R&D throughput for next-generation dye-ester pairings.
- REACH SVHC notification timelines:Substance-of-very-high-concern dossier preparation extends product-launch cycles by 18-24 months for reformulated chemistries.
- Legacy injection-molding asset retooling:Captive polyethylene molding lines require substantial capital redeployment to process bio-based alternative resins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glow Sticks Market |
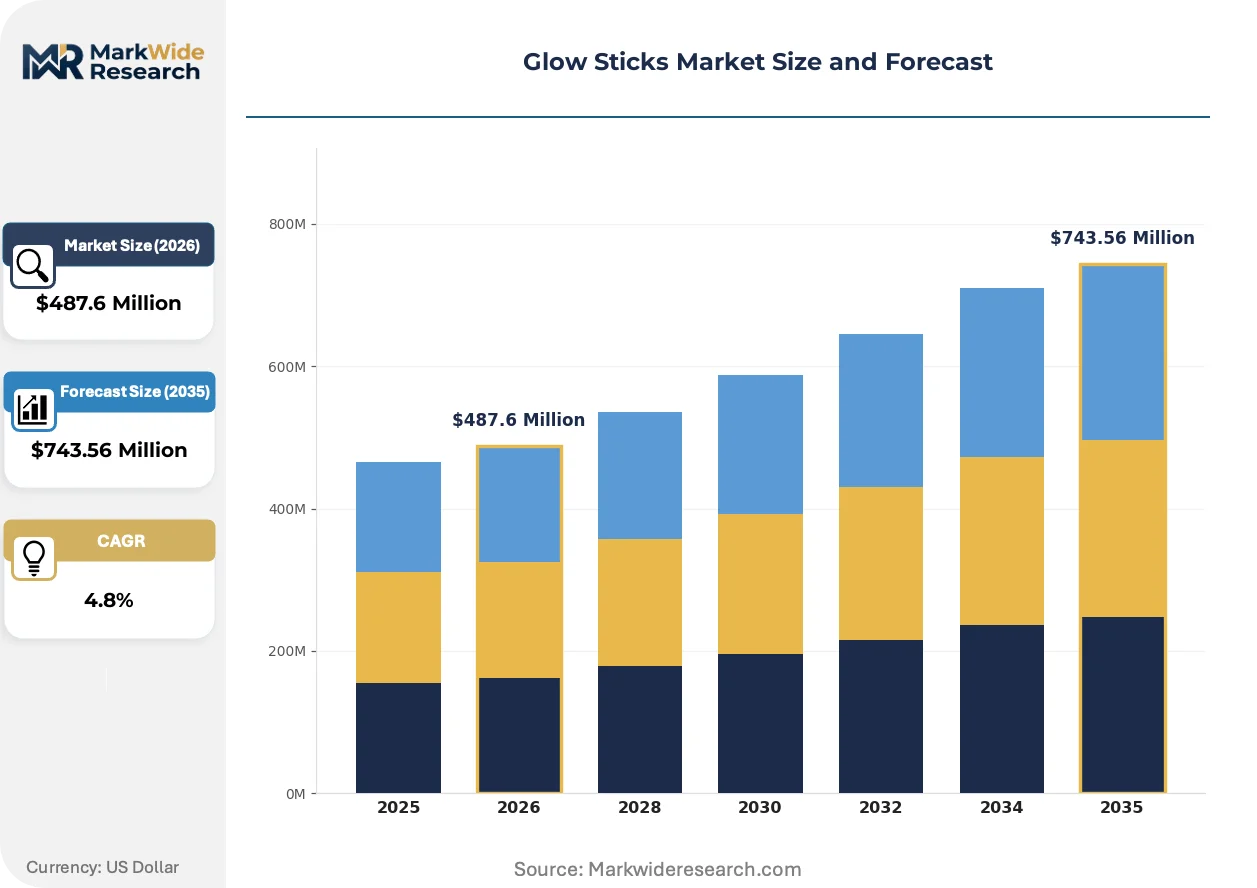
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Glow Sticks, Multi-Color Glow Sticks, UV Glow Sticks, Glow Necklaces Application: Event Decoration, Emergency Signaling, Recreational Use, Safety Equipment Material: Plastic, Polyethylene, Waterproof Coating, Non-Toxic Chemicals Distribution Channel: Online Retail, Wholesale, Specialty Stores, Event Supply Shops |
| Companies Covered | Cyalume Technologies Inc., Northern Products Inc., Lumica Corporation, Omniglow LLC, Sinoglow Industrial Co. Limited, Nite Ize, Inc., The Coleman Company, Inc., Brite Strike Technologies Inc., Nanjing Bessen Glow Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glow Sticks Market Strategic Shifts
Active reformulation of chemiluminescent dye systems is compressing product-development cycles while regulatory disclosure mandates are reshaping competitive qualification. These forces are converging to favor integrated manufacturers with captive polymer processing and in-house photochemistry capabilities.
Biodegradable polymer shells are unifying environmental compliance with performance durability in next-generation glow stick formats. Festival operators in Copenhagen and Amsterdam are specifying compostable-shell products in 60% of new procurement tenders. This material transition is unifying supply chain sustainability credentials with venue waste-reduction targets, compressing the addressable market for conventional polyethylene-based alternatives.
REACH Annex XIV authorization requirements are tightening control over diphenylanthracene and other legacy fluorophore precursors. ECHA's 2023-2024 substance evaluation wave is forcing reformulation of yellow-green emission standards that dominate emergency-preparedness kits. Military-specification producers are responding by accelerating qualification of alternative oxalate-ester activators with comparable quantum yield profiles.
Event planners are consolidating supplier relationships through annual-volume framework contracts rather than spot-market purchasing. Specialty retailers in London and Manchester are losing share to direct-procurement platforms that aggregate demand across multi-venue festival circuits. This channel rotation is most pronounced in the United Kingdom, where outdoor event licensing reforms have concentrated ownership of major festival sites.
Glow Sticks Market Segmentation
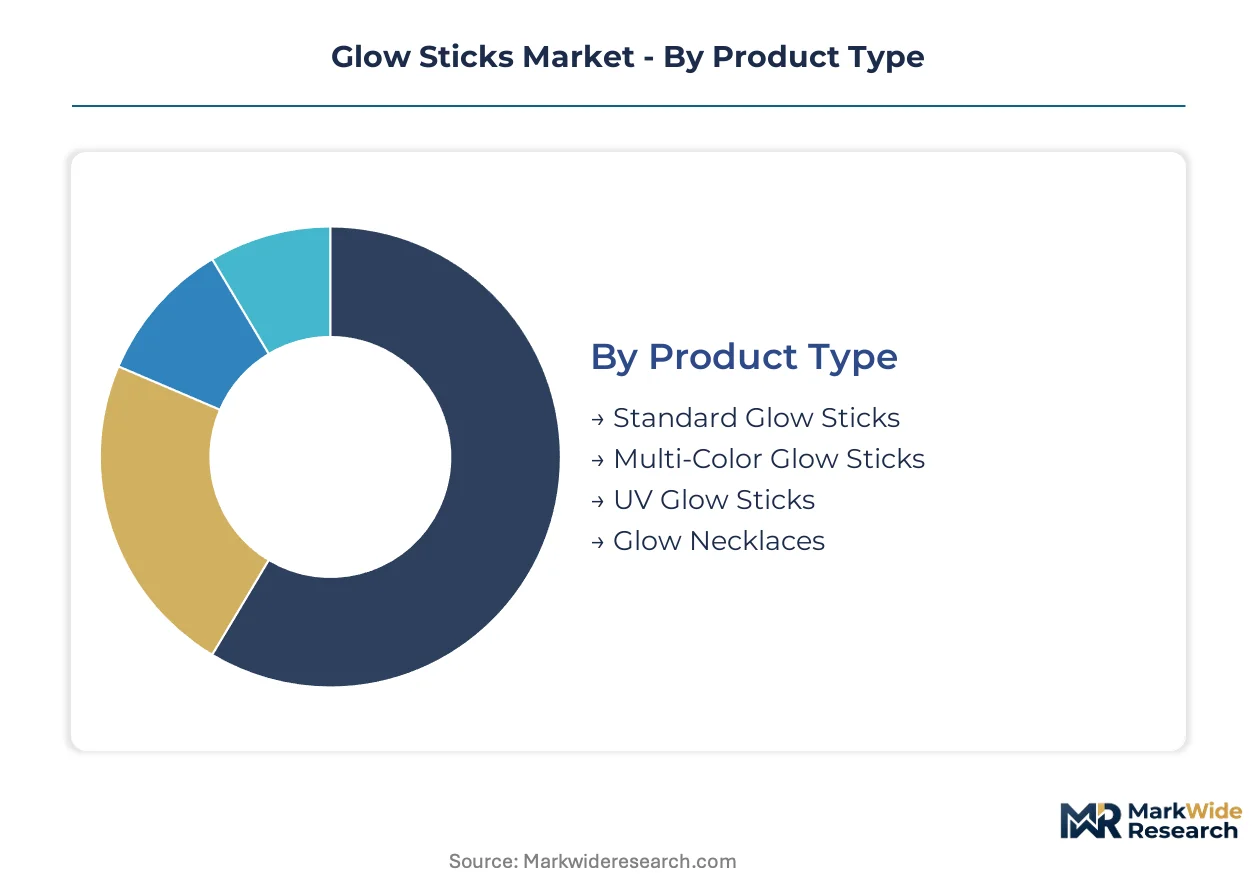
Glow stick manufacturers configure production lines around distinct chemiluminescence formats and shell specifications. Segmentation reveals where capital equipment concentrates and which formulations command reformulation investment under tightening chemical disclosure rules.
Product Type:
Capital intensity peaks with specialized wavelength-tuned chemistries requiring dedicated mixing vessels and clean-room filling environments.
- Standard Glow Sticks:Single-dye oxalate-ester formulations in fixed 6-inch polyethylene tubing dominate emergency-preparedness procurement. Germany's civil defense stockpiling programs absorb substantial volumes through multi-year framework agreements with hardened shelf-life specifications.
- Multi-Color Glow Sticks:Segmented ampoule architectures isolate incompatible dye-ester pairings within one shell, enabling sequential color transitions. Festival operators in Bavaria and North Rhine-Westphalia specify these for stage perimeter marking and crowd flow management.
- UV Glow Sticks:Diphenylanthracene-derived fluorophores tuned for blacklight excitation penetrate Tokyo and Seoul nightlife supply chains.
- Glow Necklaces:Flexible polyethylene tube extrusions with connector clasps target impulse purchases at point-of-sale locations.
Standard Glow Sticks absorb the bulk of installed capacity; Multi-Color Glow Sticks are expanding most quickly.
Application:
End-use differentiation separates high-volume commodity contracts from premium-margin specialty orders with exacting performance specifications.
- Event Decoration:Bulk procurement of multi-color and necklace formats by festival operators drives the largest absolute volume. Parisian event-decoration channels are pivoting toward reusable LED-encapsulated alternatives for premium positioning.
- Emergency Signaling:Military and first-responder specifications demand 12-hour minimum luminosity, cold-weather activation, and waterproof integrity. Cyalume Technologies anchors this segment with hardened product lines meeting NATO stock numbering requirements.
- Recreational Use:Camping and outdoor leisure applications favor compact packaging and retail-ready displays.
- Safety Equipment:Marine and industrial applications require Coast Guard and OSHA-compliant visibility standards.
Event Decoration commands the widest production footprint; Emergency Signaling maintains the steepest specification barriers.
Material:
Feedstock selection determines regulatory compliance pathways and end-of-life disposal economics.
- Plastic:Legacy petroleum-based resins face mounting substitution pressure from compostable alternatives in municipal procurement codes.
- Polyethylene:High-density blow-molding grades from spot-market ethylene supply the dominant shell material across all product formats. Integrated molders with captive resin processing control unit economics most effectively.
- Waterproof Coating:Acrylic and polyurethane barrier layers extend shelf life in humid climates.
- Non-Toxic Chemicals:REACH-compliant phthalate-free dye carriers and bio-based ester formulations are displacing legacy chemistries.
Polyethylene retains dominant share; Non-Toxic Chemicals is gaining share fastest amid ECHA reformulation mandates.
Distribution Channel:
Channel selection shapes margin capture and customer relationship durability.
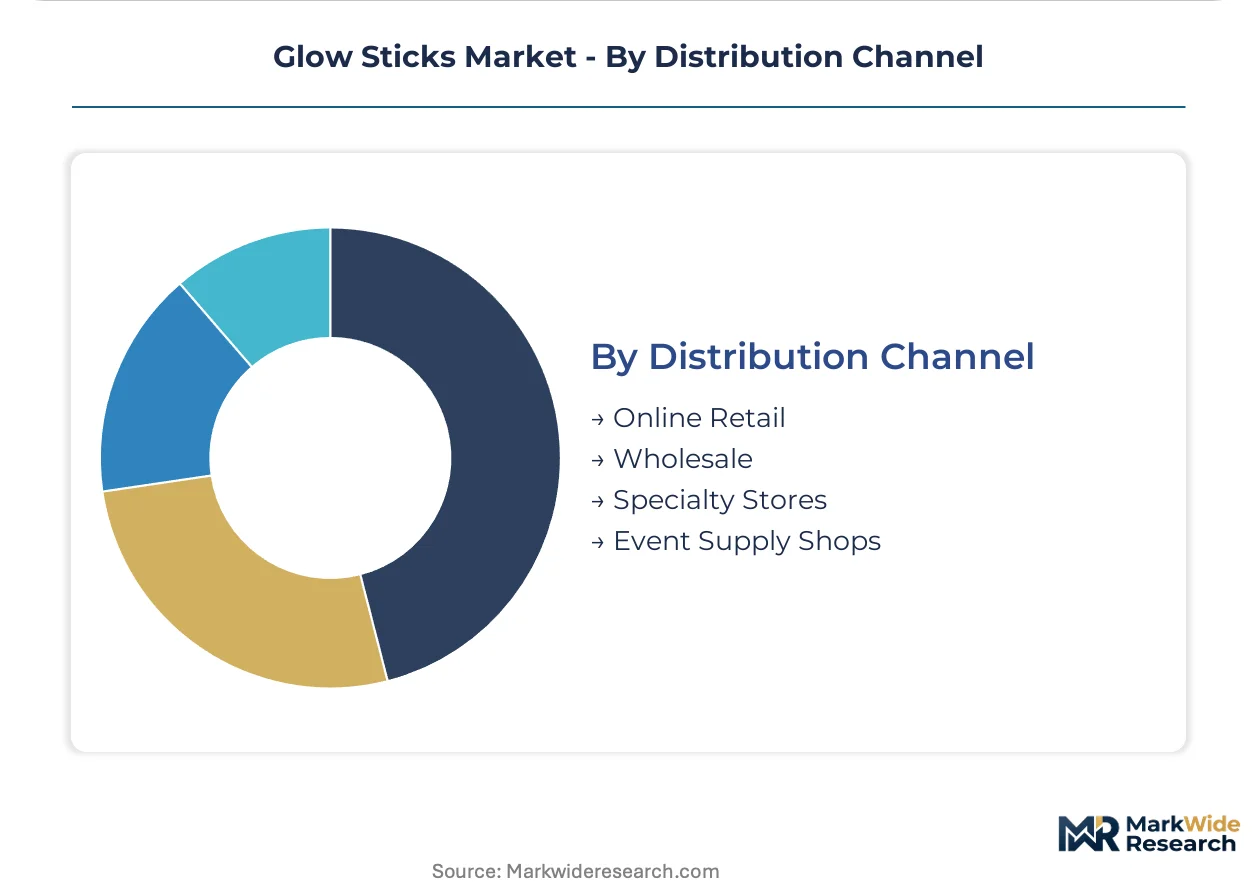
- Online Retail:Amazon and Alibaba platforms aggregate fragmented consumer demand with compressed delivery timelines.
- Wholesale:Distributor networks serving event planners and institutional buyers face disintermediation from direct-procurement portals.
- Specialty Stores:Party supply and camping retailers in London and Manchester command impulse-purchase premiums at point-of-sale.
- Event Supply Shops:Direct venue relationships with festival operators in Copenhagen and Amsterdam specify compostable-shell products in the majority of new tenders.
Wholesale retains the deepest volume relationships; Event Supply Shops are climbing the fastest on sustainability-linked procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates molded polyethylene shell production along the Yangtze River Delta, while Germany, the United States, Japan, and the United Kingdom absorb the bulk of finished-product procurement for festival and emergency applications.
Germany
Outdoor music festivals in Bavaria and North Rhine-Westphalia drive bulk procurement of multi-color chemiluminescence formats. ECHA REACH Annex XIV authorization requirements for diphenylanthracene precursors force reformulation of legacy yellow-green emergency standards. Manufacturing clusters in Hesse specialize in NATO-specification military signaling products with hardened cold-weather activation protocols.
United States
Civil defense stockpiling programs and recreational camping demand sustain high-volume consumption of standard 6-inch formats. The Consumer Product Safety Commission enforces child-safety labeling and small-part standards that shape retail packaging configurations. Production assets concentrate in the Midwest industrial corridor, with blow-molding operations tied to regional ethylene supply networks.
China
Integrated molders with captive polyethylene processing dominate export manufacturing, leveraging Yangtze River Delta chemical feedstock access. The national standardization administration mandates GB-compliant chemical disclosure for dye-ester formulations in domestic distribution. Borosilicate glass ampoule fabrication clusters in Jiangsu Province supply fracture-vial components to finished-goods assemblers across East Asia.
Japan
Specialized wavelength-tuned UV formats penetrate Tokyo and Osaka nightlife supply chains where blacklight fluorescence commands premium positioning. METI industrial standards govern chemiluminescence shelf-life labeling and performance certification for consumer products. Kansai-region distributors anchor festival supply relationships across East Asian entertainment venues.
United Kingdom
Outdoor event licensing reforms have concentrated ownership of major festival sites, consolidating procurement through direct-venue platforms. Specialty retailers in London and Manchester face margin compression from disintermediating e-procurement portals. Scottish and Welsh event operators increasingly specify compostable-shell alternatives in sustainability-linked tenders.
Glow Sticks Market Competitive Environment
The competitive structure tilts toward integrated manufacturers with captive polymer processing capabilities. Mid-scale specialists compete on formulation chemistry expertise, while volume-oriented fabricators compete on unit economics through backward integration into polyethylene molding. Two strategic archetypes dominate: military-specification producers with hardened product lines, and festival-supply specialists with multi-color format portfolios. Capacity expansion in biodegradable shell polymers and strategic partnerships for direct-venue distribution represent the dominant competitive moves.
Among North American producers, Cyalume Technologies Inc. and Northern Products Inc. occupy positions within the military-emergency signaling tier. Lumica Corporation exemplifies the festival-specialist archetype through its East Asian supply chain anchoring. Sinoglow Industrial Co. Limited represents scale-driven manufacturing integration with captive molding operations. Omniglow LLC and Nite Ize, Inc. sit within the consumer-recreational positioning vector.
| Leading Market Players |
|---|
| Cyalume Technologies Inc. |
| Northern Products Inc. |
| Lumica Corporation |
| Omniglow LLC |
| Sinoglow Industrial Co. Limited |
| Nite Ize, Inc. |
| The Coleman Company, Inc. |
| Brite Strike Technologies Inc. |
| Nanjing Bessen Glow Technology |
| Others |
Value Chain & Pricing Dynamics
Military-specification versus festival-commodity divergence manifests in both pricing stratification and supply chain configuration across the glow sticks market. NATO-compliant hardened products command premium positioning through specialized cold-weather activation chemistry and multi-year framework contracting, while bulk multi-color formats for event decoration compete on polyethylene unit economics and spot-market resin access.
Pricing Analysis
Margin tightening in standard glow stick tiers reflects polyethylene feedstock volatility tied to crude-linked ethylene spot markets. Three-tier pricing structure across military-specification, commercial-premium, and economy-event levels separates products by certification grade and shelf-life performance. Pricing pressure intensifies in recreational segments as LED substitutes penetrate emergency-preparedness kits. Event planners exhibit highest price sensitivity through consolidated annual-volume tenders, while military procurement maintains lowest sensitivity due to performance-specification rigidity.
Supply Chain Analysis
Dual-sourcing requirements for borosilicate glass ampoules are forcing finished-goods assemblers to qualify secondary fracture-vial suppliers beyond China's Yangtze River Delta concentration. Supply concentrates in China for polyethylene shell molding, Germany for REACH-compliant formulation finishing, and the United States for civil defense stockpiling distribution. Raw material dependencies span petroleum-based resin feedstocks, diphenylanthracene fluorophores, and hydrogen peroxide activators. Single-source geographic concentration for glass ampoules creates vulnerability to regional disruption. Distribution runs through direct-venue e-procurement portals disintermediating traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glow sticks market is becoming a vertical-integration race where backward control over polyethylene molding and captive photochemistry R&D separates profitable survivors from margin-compressed assemblers.
For Market Incumbents: Anticipate LED substitution in emergency signaling by accelerating qualification of bio-based ester formulations ahead of REACH SVHC notification timelines. Consolidate supplier relationships through multi-year framework agreements with Bavarian and North Rhine-Westphalian festival operators. Defensive capacity addition in biodegradable PLA shell polymers aligns with Copenhagen and Amsterdam compostable procurement mandates. For New Entrants and Emerging Players: Direct-venue distribution partnerships offer the most penetrable channel for bypassing entrenched wholesale relationships. White-space targets include reusable LED-encapsulated formats in Parisian premium event-decoration channels and compostable-shell specifications in Scottish and Welsh sustainability-linked tenders. A go-to-market angle anchored to REACH-compliant phthalate-free dye carriers addresses regulatory-driven reformulation demand. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking festival-supply channel access. Long-term viability favors manufacturers with captive polymer processing and in-house photochemistry capabilities over pure-play assemblers. The signal to watch is ECHA substance evaluation waves affecting diphenylanthracene authorization status.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethylene Molding | Captive resin processing insulates margin from ethylene spot volatility. |
| REACH-Compliant Formulation Reformulation | Phthalate-free dye carriers sustain market access under ECHA disclosure mandates. |
| Biodegradable Shell Polymer Transition | PLA and PHA formulations align with Copenhagen municipal compostable procurement codes. |
| Direct-to-Venue Distribution Platform | E-procurement portals disintermediate wholesale networks serving mid-size festival operators. |
| Multi-Year Framework Contracting | Annual-volume agreements with Bavarian festival sites lock in demand visibility. |
Study Parameters
Multi-period observation of REACH regulatory filing timelines, polyethylene resin spot pricing, and festival procurement tender volumes anchored the trend analysis, supplemented by interviews with plant managers at integrated molding operations, procurement leads at German event-planning agencies, distribution channel partners in London and Manchester, and technical R&D directors specializing in oxalate-ester photochemistry. Secondary validation drew from ECHA substance evaluation dossiers, customs and trade data for chemiluminescence product categories, SEC filings of disclosed market participants, and civil defense stockpiling program disclosures. Bottom-up volume builds across product formats triangulated against top-down market sizing.
Input-output matrices modeled demand drivers against production capacity constraints across the projection horizon. Segmentation dimensions included product type, application end-use, shell material composition, and distribution channel structure. CAGRs were derived from slope analysis of historical volume trajectories adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated ECHA SVHC notification timelines and polyethylene feedstock price elasticity assumptions.
Caveats apply where REACH Annex XIV authorization delays or LED substitution acceleration in military procurement could materially shift the outlook. Forecasts reflect documented assumptions regarding reformulation cost pass-through and festival operator demand consolidation. A model refresh is warranted upon material change in ECHA substance evaluation outcomes or borosilicate ampoule supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Toy Collectibles Market
Toys and Games
Ferret Toys Market
Toys and Games
Snooker Tables Market
Toys and Games
Bounce House Market
Toys and Games
China Toys Market
Toys and Games
Baby Toys Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Global Toys Market
Toys and Games
Bath Toy Market
Toys and Games
Global Blind Boxes Market
Toys and Games
Global Stem Toys Market
Toys and Games
Dartboard Market
Toys and Games
Remote Control Toys Market
Toys and Games
Fabric Toys Market
Toys and Games
Board Games and Puzzles Market