
 Coaster Market | 2026-2036
Coaster Market Size, Share, and Industry Trends Forecast 2026-2036
Coaster Market Outlook
Corporate hospitality procurement is collapsing as the dominant buyer archetype while individual consumers and specialty café operators gain ground. Rocky Mountain Construction leverages its themed design capabilities to anchor premium custom coaster contracts with entertainment venues. Mack Rides competes through geographic dominance across European amusement parks, where branded merchandise including coasters generates ancillary revenue streams. Intamin specializes in high-durability silicone formulations that sustain repeat orders from high-traffic foodservice operations.
A coaster is a flat, typically absorbent or non-slip surface placed beneath beverage vessels to protect underlying furniture from moisture damage, heat transfer, or abrasion; modern iterations employ silicone composites rated for thermal resistance exceeding 200°C or ceramic substrates with glazed finishes for stain prevention. The primary commercial purpose spans hospitality table protection, brand display, and souvenir merchandising across restaurants, hotels, and entertainment venues. Wooden and cork materials occupy mature, cost-sensitive volume tiers where margin compression is persistent, while silicone and ceramic segments capture premium positioning through durability claims and design customization. Themed and customized designs are accelerating fastest as venue operators seek differentiated guest experiences, whereas round and square shapes dominate standard foodservice procurement with limited differentiation.
The US Food and Drug Administration regulates indirect food contact materials including silicone coasters through food additive regulations, while the EU REACH framework restricts phthalate content in polymer-based products entering European hospitality supply chains. Germany's Federal Institute for Risk Assessment enforces additional migration testing for ceramic glazes, shaping supplier compliance investments. China's GB standards for silicone products and Japan's Ministry of Economy, Trade and Industry labeling requirements create fragmented certification demands. Stakeholders must monitor evolving chemical restriction schedules and regional labeling mandates to preempt supply chain disruptions.
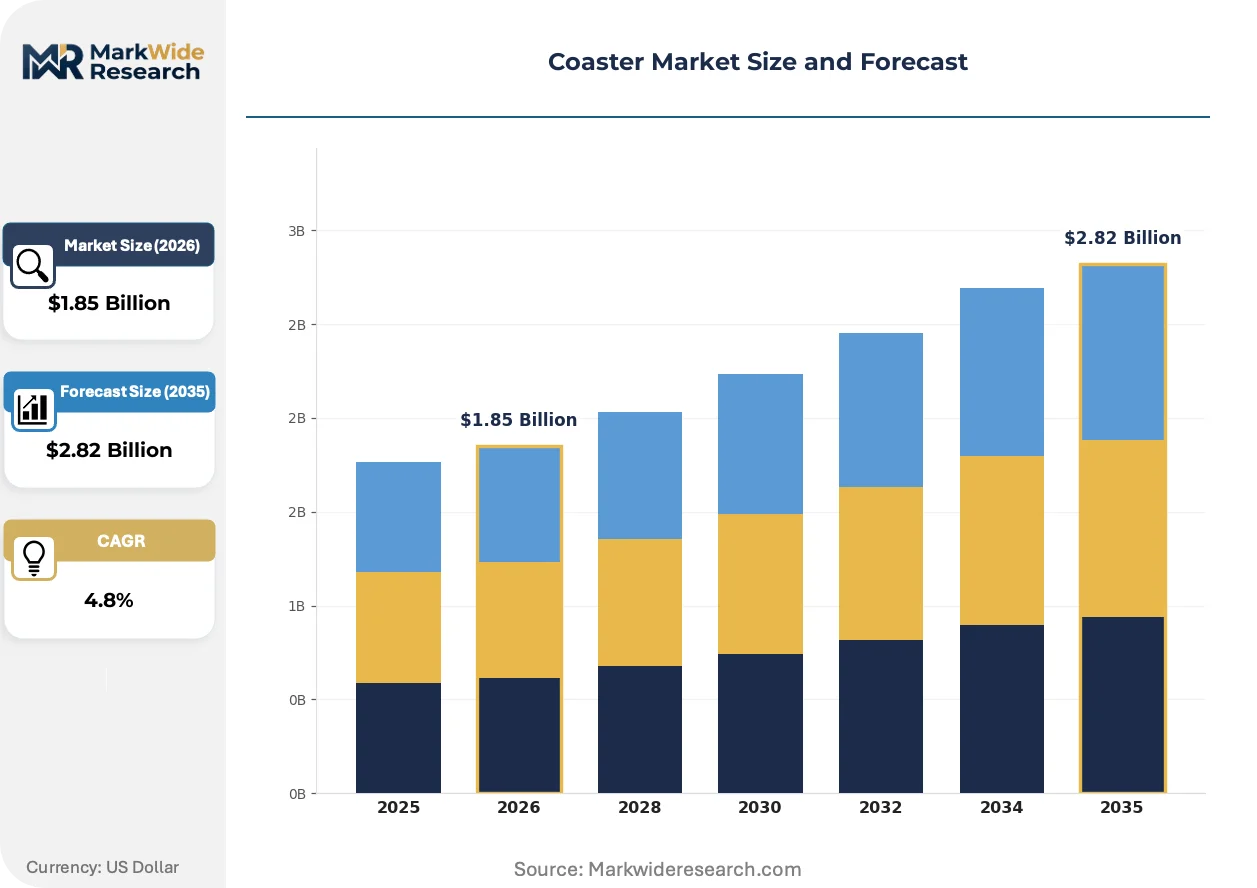
Market Dynamics
Hospitality procurement teams are consolidating supplier relationships while simultaneously fragmenting order specifications, creating tension between volume leverage and customization demands that reshapes coaster manufacturing economics.
Growth Catalysts
- Themed Entertainment Expansion:Amusement parks and immersive venues in Germany, Japan, and the United Arab Emirates are commissioning proprietary coaster designs as integral merchandise revenue streams. Custom fabrication capabilities attract multi-year supply contracts.
- REACH Chemical Restrictions:The EU framework's phthalate limitations accelerate silicone formulation adoption across European foodservice supply chains. Compliance investments by suppliers create competitive moats against cork and polymer alternatives.
- Thermal Resistance Standards:Silicone composites rated above 200°C penetrate high-temperature beverage service applications previously served by ceramic. Material science advances expand addressable use cases.
Market Restraints
- Raw Material Concentration:Silicone precursor supply concentrates among specialized chemical manufacturers in China and Germany. Input cost volatility constrains margin predictability for downstream fabricators.
- Ceramic Glaze Migration Testing:Germany's Federal Institute for Risk Assessment enforces extended certification timelines for ceramic coaster imports. Compliance delays extend new product introduction cycles.
- Digital Substitution Threat:Electronic table protection systems and integrated heating elements in furniture reduce coaster necessity in premium hospitality installations.
Strategic Opportunities
- Underpenetrated Middle Eastern Markets:Saudi Arabia's entertainment infrastructure investments and MOHAP regulatory alignment create entry pathways for compliant suppliers. Tourism-driven venue construction accelerates procurement volumes.
- Biodegradable Composite Convergence:Agricultural waste fiber integration with silicone binders addresses sustainability mandates without sacrificing durability. Early formulation patents establish positioning ahead of standardization.
- Direct-to-Venue Digital Channels:Procurement platforms connecting coaster fabricators directly with independent café operators bypass traditional hospitality distributors. Margin capture improves for specialized producers.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Simultaneous FDA food contact compliance, REACH substance restrictions, and Japan METI labeling requirements fragment quality assurance resources. Smaller fabricators face disproportionate overhead burdens.
- Design-to-Production Lead Time Compression:Themed venue operators demand four-week turnaround on custom coaster prototypes. Traditional six-week ceramic firing cycles and three-week silicone mold fabrication create fulfillment gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coaster Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Cork, Silicone, Ceramic Design: Classic, Modern, Themed, Customized Shape: Round, Square, Hexagonal, Novelty Sales Channel: Online, Retail, Wholesale, Specialty Stores |
| Companies Covered | Bolliger & Mabillard, Intamin, Rocky Mountain Construction, Mack Rides, Gerstlauer, The Gravity Group, Vekoma Rides Manufacturing, Great Coasters International, Fabbri Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coaster Market Strategic Shifts
Material substitution and regulatory harmonization pressures are converging to reshape coaster manufacturing processes, with sustainability claims and thermal performance emerging as primary competitive differentiators across hospitality procurement.
Silicone composite formulations are supplanting traditional cork substrates in moisture-critical foodservice applications. High-traffic hotel chains and airport lounges are adopting these materials for extended replacement cycles. The shift compresses revenue for cork processors while enabling premium pricing tiers for compliant silicone suppliers.
REACH substance restriction schedules are tightening migration limits for polymer-based coasters entering European supply chains. Manufacturers are reformulating phthalate-free compounds ahead of enforcement deadlines. German hospitality distributors are prioritizing pre-certified suppliers to preempt customs delays.
Specialty café operators are consolidating purchases through cooperative procurement platforms rather than fragmented individual orders. Independent roasteries and micro-cafés in Japan and the United Arab Emirates are pooling volumes to access custom design minimums previously reserved for chain accounts. This aggregation disrupts traditional distributor relationships while creating direct manufacturer engagement opportunities.
Coaster Market Segmentation
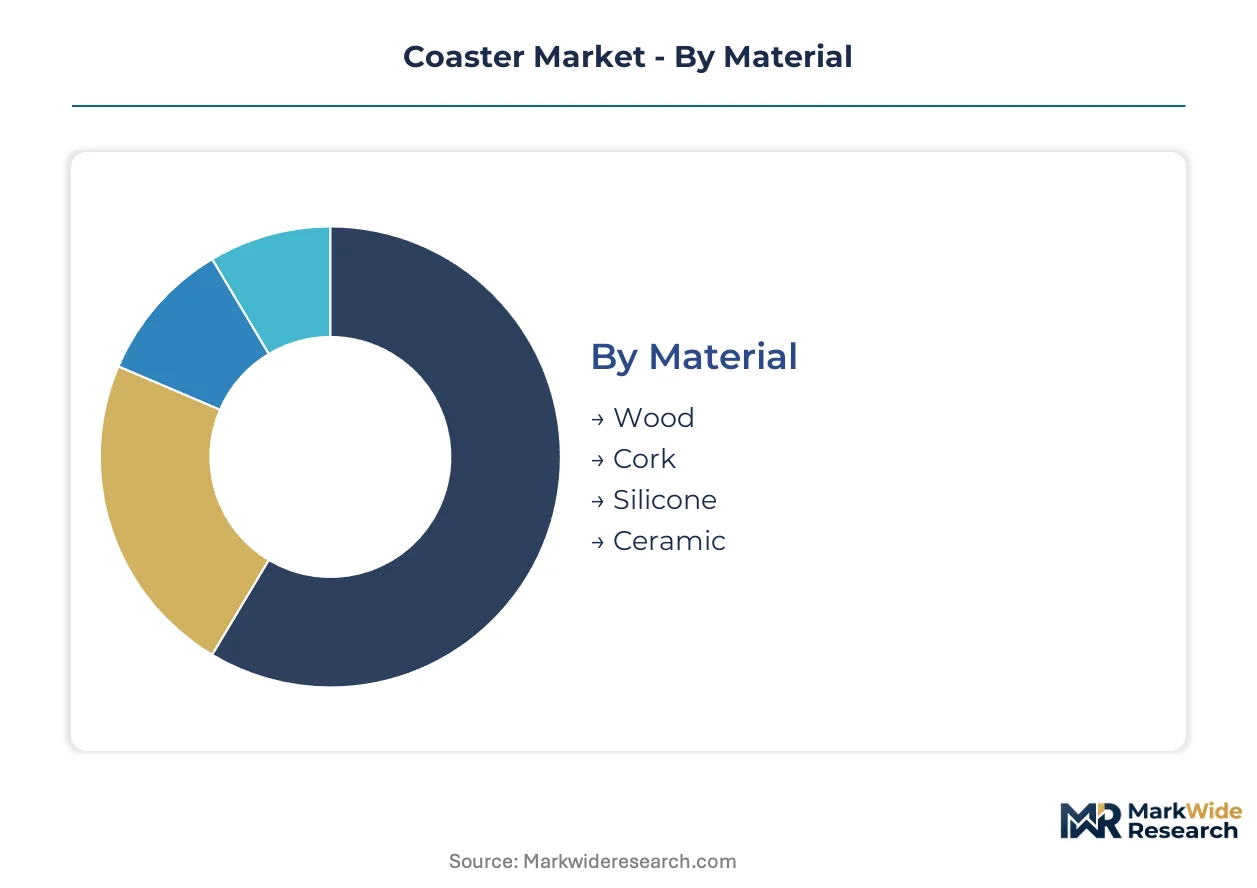
Coaster procurement patterns diverge sharply across material grades and venue types, with premium silicone and ceramic formulations commanding margin premiums while cork and wood compete on volume. Design complexity and sales channel selection determine whether fabricators capture direct relationships with hospitality operators or cede margin to distributor intermediaries.
Material:
Silicone and ceramic formulations concentrate margin pools through durability claims and regulatory compliance premiums, while cork and wood segments compete on procurement efficiency for high-volume foodservice accounts.
- Silicone:Thermal resistance exceeding 200°C enables deployment in airport lounges and hotel breakfast service where heat transfer protection is critical. REACH-compliant phthalate-free formulations from German chemical suppliers attract multi-year contracts from European hospitality chains seeking preemptive compliance.
- Ceramic:Glazed substrates with stain-resistant finishes penetrate premium restaurant and themed entertainment venues in Japan and the United Arab Emirates. Germany's Federal Institute for Risk Assessment enforces extended migration testing timelines that favor established suppliers with pre-certified product lines.
- Wood:Cost-sensitive procurement tiers in mature hospitality markets where replacement cycles are short and brand differentiation is minimal.
- Cork:Traditional absorbent substrates facing displacement by silicone in moisture-critical applications; retains foothold in eco-positioned café concepts.
Silicone holds installed capacity. Ceramic is rotating up the share rankings.
Design:
Procurement volume clusters around standard formats, yet margin extraction concentrates in bespoke fabrication capabilities that venue operators leverage for merchandise revenue and guest experience differentiation.
- Themed:Proprietary designs commissioned by amusement parks and immersive entertainment venues in Germany and the United Arab Emirates generate ancillary merchandise revenue streams. Rocky Mountain Construction anchors multi-year supply contracts through integrated design-to-production capabilities.
- Customized:Specialty café operators in Japan pool cooperative procurement volumes to access minimum order thresholds previously reserved for chain accounts. Direct-to-venue digital platforms bypass traditional distributor relationships.
- Modern:Minimalist aesthetics align with contemporary hospitality interiors in urban hotel renovations.
- Classic:Traditional patterns serving established restaurant chains with conservative brand standards.
Themed designs extract premium pricing. Customized is climbing the fastest.
Shape:
Manufacturing economics favor standardized geometries with minimal tooling investment, though novelty configurations create differentiation for souvenir merchandising and specialty retail.
- Round:Dominates foodservice procurement with universal vessel compatibility and efficient material utilization during fabrication. German hotel chains specify round silicone coasters for standardized table protection across property portfolios.
- Square:Parallel standard tier with margin compression from commoditized supply; preferred by institutional catering operations for stacking efficiency.
- Hexagonal:Geometric differentiation for design-forward hospitality concepts seeking visual distinction without custom tooling premiums.
- Novelty:Irregular shapes and die-cut profiles for souvenir retail and promotional applications.
Round holds installed capacity. Novelty is gaining share fastest.
Sales Channel:
Channel selection determines margin capture versus volume scale, with direct manufacturer relationships expanding at distributor expense as procurement platforms aggregate fragmented buyer demand.
- Wholesale:Traditional hospitality distributors in Germany and the United Arab Emirates consolidate procurement for hotel chains and restaurant groups. REACH pre-certification requirements create supplier stickiness and reduce switching elasticity.
- Online:Direct-to-venue platforms connect fabricators with independent café operators in Japan, disrupting established distributor relationships. Cooperative procurement aggregation enables custom design access for micro-roasteries.
- Retail:Consumer-facing sales through home goods and specialty gift channels.
- Specialty Stores:Curated hospitality supply showrooms serving design-conscious venue operators.
Wholesale holds installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German coaster fabricators export REACH-compliant silicone formulations to hospitality buyers across the Netherlands and Belgium, anchoring a westward trade corridor that channels premium-grade production into Benelux foodservice procurement networks.
Germany
Hospitality procurement teams at Frankfurt airport lounges and Munich hotel chains specify phthalate-free silicone coasters for thermal resistance above 200°C. The Federal Institute for Risk Assessment enforces extended migration testing timelines for ceramic glazes, favoring established suppliers with pre-certified product lines. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate mold-fabrication capacity for custom themed designs.
Japan
Specialty café operators in Tokyo and Osaka pool cooperative procurement volumes to access minimum order thresholds for customized ceramic coasters. METI labeling requirements for silicone products create compliance entry barriers for unverified imports. The Kansai region anchors production of glazed ceramic substrates with stain-resistant finishes for premium restaurant applications.
United Arab Emirates
Dubai and Abu Dhabi entertainment venues commission proprietary themed coaster designs as merchandise revenue streams alongside hospitality table protection procurement. MOHAP regulatory alignment with Gulf standardization initiatives streamlines import certification for silicone formulations. Sharjah-based distributors consolidate supply relationships for hotel chains across the northern emirates.
United States
Airport lounge operators in Atlanta and Dallas-Fort Worth specify silicone composites for high-traffic beverage service applications. FDA food additive regulations for indirect food contact materials shape supplier qualification requirements. Rocky Mountain Construction leverages themed design capabilities to anchor custom coaster contracts with entertainment venues in Colorado and California.
China
Silicone precursor manufacturers in Jiangsu and Zhejiang provinces supply downstream fabricators with raw material for export-grade coaster production. GB standards for silicone products create domestic certification requirements distinct from REACH and FDA frameworks. The Yangtze River Delta concentrates mold-making capacity for both standard and novelty shape configurations.
Coaster Market Competitive Environment
Player mix skews toward specialized ride-system manufacturers with ancillary merchandise fabrication capabilities, creating a tiered structure where themed entertainment expertise commands premium positioning. Three archetypes dominate: integrated entertainment venue suppliers, regional hospitality distributors with REACH pre-certification, and silicone formulation specialists with thermal resistance claims. Competitive moves concentrate on design-to-production lead time compression and direct-to-venue digital channel expansion.
Within the themed entertainment supplier tier, Rocky Mountain Construction and Intamin exemplify archetypes leveraging proprietary design capabilities to anchor multi-year coaster contracts. Mack Rides occupies a position among European fabricators with geographic concentration across German amusement parks. These three represent the competitive core where integrated merchandise revenue strategies intersect with hospitality procurement requirements.
| Leading Market Players |
|---|
| Bolliger & Mabillard |
| Intamin |
| Rocky Mountain Construction |
| Mack Rides |
| Gerstlauer |
| The Gravity Group |
| Vekoma Rides Manufacturing |
| Great Coasters International |
| Fabbri Group |
| Others |
Value Chain & Pricing Dynamics
Six-week ceramic firing cycles and three-week silicone mold fabrication windows compress supplier pricing power against buyers demanding four-week prototype turnaround. This lead-time tension concentrates margin capture with German and Chinese fabricators holding pre-certified inventory positions, while forcing secondary suppliers into spot-market raw material exposure.
Pricing Analysis
Current-generation silicone formulations command premium positioning against prior-generation cork substrates and next-generation biodegradable composites still in patent filing. Three-tier pricing structure across REACH-certified premium, standard foodservice, and economy cork tiers reflects certification grade and thermal performance differentiation. Cost compression in the cork tier intensifies because silicone displacement erodes volume scale. Chain hospitality procurement teams exhibit lowest price sensitivity; independent café operators pooled through cooperative platforms show highest.
Supply Chain Analysis
Inventory positions at German distributors and Sharjah-based consolidators reveal extended safety-stock holdings triggered by ceramic glaze migration testing delays. Raw material supply concentrates in China for silicone precursors, Germany for phthalate-free polymer formulations, and the Kansai region for glazed ceramic substrates. Downstream distribution runs through hospitality procurement platforms in the United Arab Emirates and cooperative aggregator networks in Japan. Single-source vulnerability concentrates in Jiangsu and Zhejiang silicone precursor manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as themed entertainment venue construction accelerates procurement volumes across Germany, Japan, and the United Arab Emirates.
For Market Incumbents: Fortify REACH pre-certification moats through accelerated phthalate-free formulation patents ahead of restriction tightening. Deepen backward integration into silicone precursor supply through captive arrangements with Jiangsu chemical manufacturers, neutralizing raw material volatility that threatens margin stability in high-volume foodservice contracts. For New Entrants and Emerging Players: Anchor in Saudi Arabia's entertainment infrastructure buildout where MOHAP regulatory alignment creates compliance pathways for new suppliers. Target direct-to-venue digital channels serving Tokyo and Osaka specialty café cooperatives, bypassing entrenched distributor relationships through design-to-production lead time compression below six weeks. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because themed entertainment supplier capabilities fragment across ride-system manufacturers with ancillary merchandise fabrication. Monitor ceramic glaze certification timeline compression at Germany's Federal Institute for Risk Assessment as inflection signal for import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Certification Investment | Preemptive compliance at Germany's Federal Institute creates customs clearance advantages for European hospitality distributors. |
| Direct-to-Venue Platform Launch | Bypassing Sharjah-based consolidators captures margin from Tokyo café cooperative procurement aggregation. |
| Biodegradable Composite Patent Filing | Agricultural waste fiber integration with silicone binders addresses sustainability mandates without sacrificing thermal resistance. |
| Themed Design Capability Acquisition | Integrated design-to-production compression below four weeks anchors multi-year entertainment venue contracts. |
| Silicone Precursor Supply Agreement | Long-term offtake with Jiangsu manufacturers mitigates raw material concentration risk in downstream fabrication. |
Study Parameters
The analysis maps silicone composite, ceramic, wood, and cork material sub-sectors, each validated through hospitality procurement directors, themed entertainment merchandise managers, foodservice distributor category buyers, and ceramic glaze compliance specialists. Primary fieldwork combined with secondary validation from FDA food additive regulations, EU REACH substance restriction schedules, Japan METI labeling requirements, and customs trade flow data. Bottom-up volume triangulation against top-down hospitality expenditure benchmarks anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated material grade, design complexity tier, venue type, and regional regulatory cluster dimensions. CAGRs derived from trend extrapolation of procurement volume patterns, thermal resistance standard adoption curves, and themed entertainment venue construction pipelines.
Material uncertainties — raw material cost volatility, ceramic certification timeline extensions, digital table protection substitution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement schedules and tourism infrastructure investment continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Model Train Market
Toys and Games
Orbital Action Jigsaw Market
Toys and Games
Toy Cars Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Plush Toy Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Claw Machine Market
Toys and Games
Global Stem Toys Market
Toys and Games
Construction Toys Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Toy Kitchens and Play Food Market
Toys and Games
Wooden Toys Market
Toys and Games
Snooker Tables Market
Toys and Games
Glow Sticks Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Smart Toys Market