
 Playing Cards and Board Games Market | 2026-2036
Playing Cards and Board Games Market Size, Share, and Industry Trends Forecast 2026-2036
Playing Cards and Board Games Market Outlook
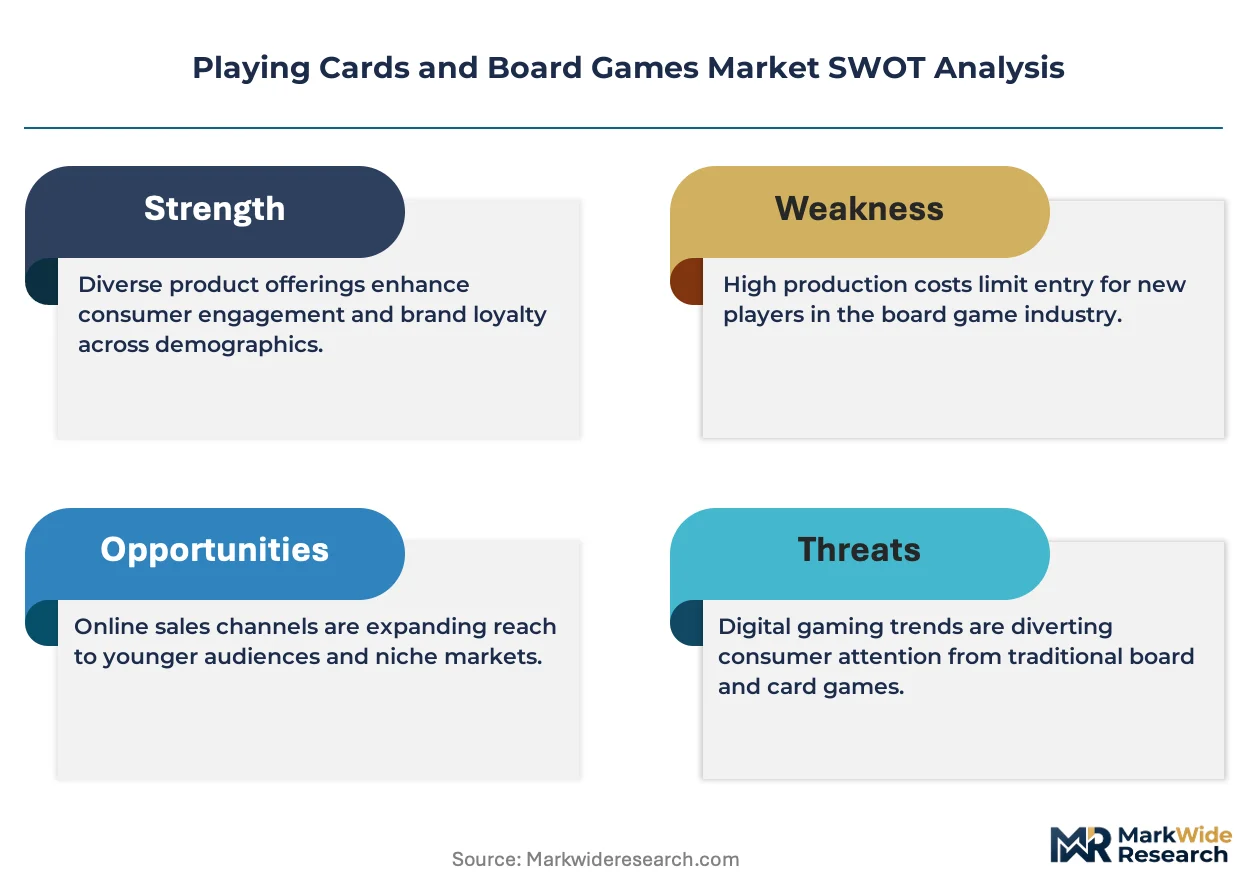
Millennial and Gen Z hobbyists are rotating demand away from mass-market family formats toward narrative-heavy tabletop and collectible card experiences. Hasbro Inc. leverages its legacy IP portfolio to sustain shelf presence across retail chains. Asmodee Group dominates hobbyist channels through specialized distribution and designer-title exclusivity. Ravensburger AG anchors European quality positioning with premium manufacturing standards.
Playing cards and board games comprise printed or manufactured game systems using paperstock, cardstock, wood, or molded plastics, governed by functional parameters including shuffle endurance, piece count tolerance, and rule-set complexity for competitive or recreational play. Family Board Games retains volume leadership through gift-cycle purchasing and holiday retail density, while Collectible Card Games captures margin concentration through booster-pack replenishment and organized play infrastructure. Tabletop Games is expanding fastest among adult hobbyists seeking social, screen-detached entertainment formats.
The US Consumer Product Safety Commission enforces small-parts and material-safety standards for children's game components, while the EU REACH regulation restricts hazardous substances in printed inks and coatings. The EU Packaging and Packaging Waste Directive shapes sustainable material transitions across European supply chains. Stakeholders must monitor evolving extended-producer-responsibility frameworks and decide whether to front-load biodegradable material investments or absorb compliance costs through supplier renegotiation.
Market Dynamics
REACH compliance is displacing petroleum-based inks across European manufacturing, forcing reformulation of card finishes and coating chemistries while elevating compliance costs for exporters serving EU hobbyist channels.
Growth Catalysts
- Organized Play Infrastructure:Tournament circuits and sanctioned event programs anchor recurring booster-pack purchases for collectible card formats, creating predictable replenishment cycles in hobby retail.
- REACH Material Standards:The EU regulation's tightening restrictions on hazardous substances in printed components accelerate adoption of water-based coatings and biodegradable cardstocks among quality-focused manufacturers.
- Screen-Detached Social Formats:Adult hobbyists seeking analog entertainment alternatives rotate discretionary spending toward narrative tabletop experiences with extended session duration and replayability.
Market Restraints
- Pulp and Paperstock Volatility:Fluctuating input costs for coated cardstock and specialty papers compress margin structures for mass-market family game producers without pricing power.
- China-Centric Component Sourcing:Concentration of molded plastic miniatures and custom dice manufacturing in Guangdong and Zhejiang provinces exposes supply chains to shipping disruptions and tariff friction.
- Digital Substitution Pressure:Mobile adaptations and digital collectible card platforms capture casual player time, particularly among younger demographics with lower analog game attachment.
Strategic Opportunities
- Biodegradable Material Mandates:Extended producer responsibility frameworks under the EU Packaging and Packaging Waste Directive create first-mover advantages for suppliers front-loading compostable component investments.
- Latin American Hobbyist Penetration:Brazil and Mexico exhibit underdeveloped organized play infrastructure relative to per-capita entertainment spending, presenting whitespace for distributor partnerships and localization.
- Direct-to-Consumer Kickstarter Channels:Crowdfunding platforms enable designer-title exclusivity and pre-funded production runs, bypassing traditional retail slotting fees and inventory risk for boutique publishers.
Industry Challenges
- Graphic Design and Rules-Engineering Talent Scarcity:The specialized skill set combining narrative systems design with production-ready mechanical balancing faces constrained supply relative to title volume growth.
- Multi-Jurisdiction Certification Timelines:Simultaneous compliance with US Consumer Product Safety Commission small-parts standards and EU REACH substance restrictions extends product launch windows and testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Playing Cards and Board Games Market |
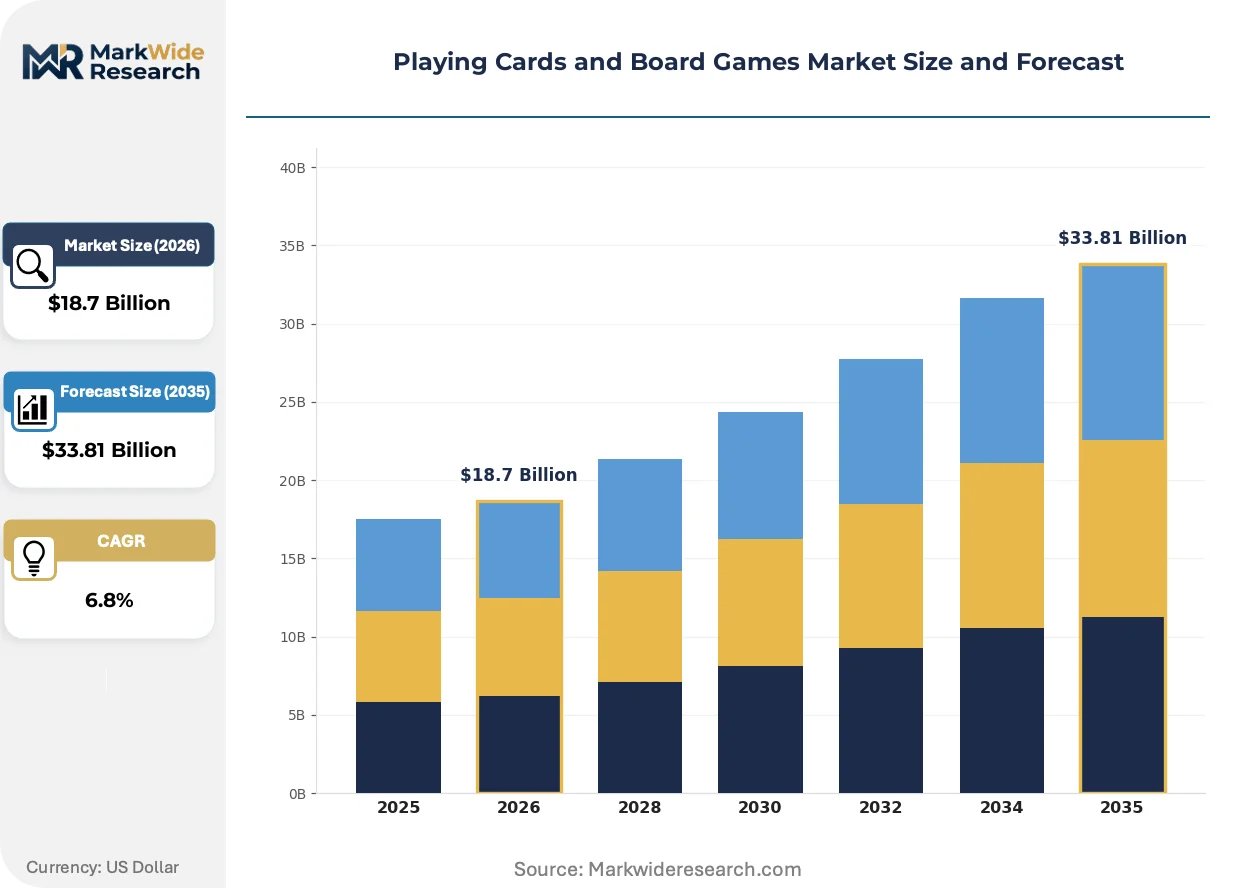
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Card Games, Tabletop Games, Collectible Card Games, Family Board Games Target Audience: Children, Families, Casual Gamers, Hobbyists Distribution Channel: Online Retailers, Specialty Stores, Retail Chains, Events Game Complexity: Beginner, Intermediate, Advanced, Expert |
| Companies Covered | Hasbro Inc., Mattel Inc., Asmodee Group, Ravensburger AG, Games Workshop Limited, Cartamundi Group, Spin Master Corp., University Games Corporation, Buffalo Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Playing Cards and Board Games Market Strategic Shifts
Digital hybridization and material sustainability are converging to redefine product architecture across tabletop and card game formats, with compliance pressures and hobbyist preferences jointly steering investment priorities.
Embedded NFC chips and companion app integration are displacing pure analog rulebooks and scorekeeping methods in mid-weight strategy titles. Publishers targeting millennial hobbyists deploy these technologies to enable dynamic scenario updates and community content sharing. The displacement of static printed components compresses traditional expansion pack business models while opening recurring digital revenue streams.
REACH Annex XVII restrictions on phthalates and heavy metals in printed coatings are compelling ink reformulation across European supply chains. Manufacturers serving German and French hobby markets accelerate migration to UV-cured, solvent-free finishes. Premium card game producers absorb higher unit costs to maintain CE marking access, while budget family formats face margin compression or market exit.
Hobbyist buyers are consolidating purchases through specialized direct channels and subscription box services, bypassing mass retail's seasonal gift-cycle dependency. Specialist distributors in the United States and Germany capture growing share of adult collector spending through exclusive preview allocations and loyalty programs. This channel rotation concentrates volume with fewer fulfillment partners, elevating negotiating leverage for slotting terms and inventory commitments.
Playing Cards and Board Games Market Segmentation
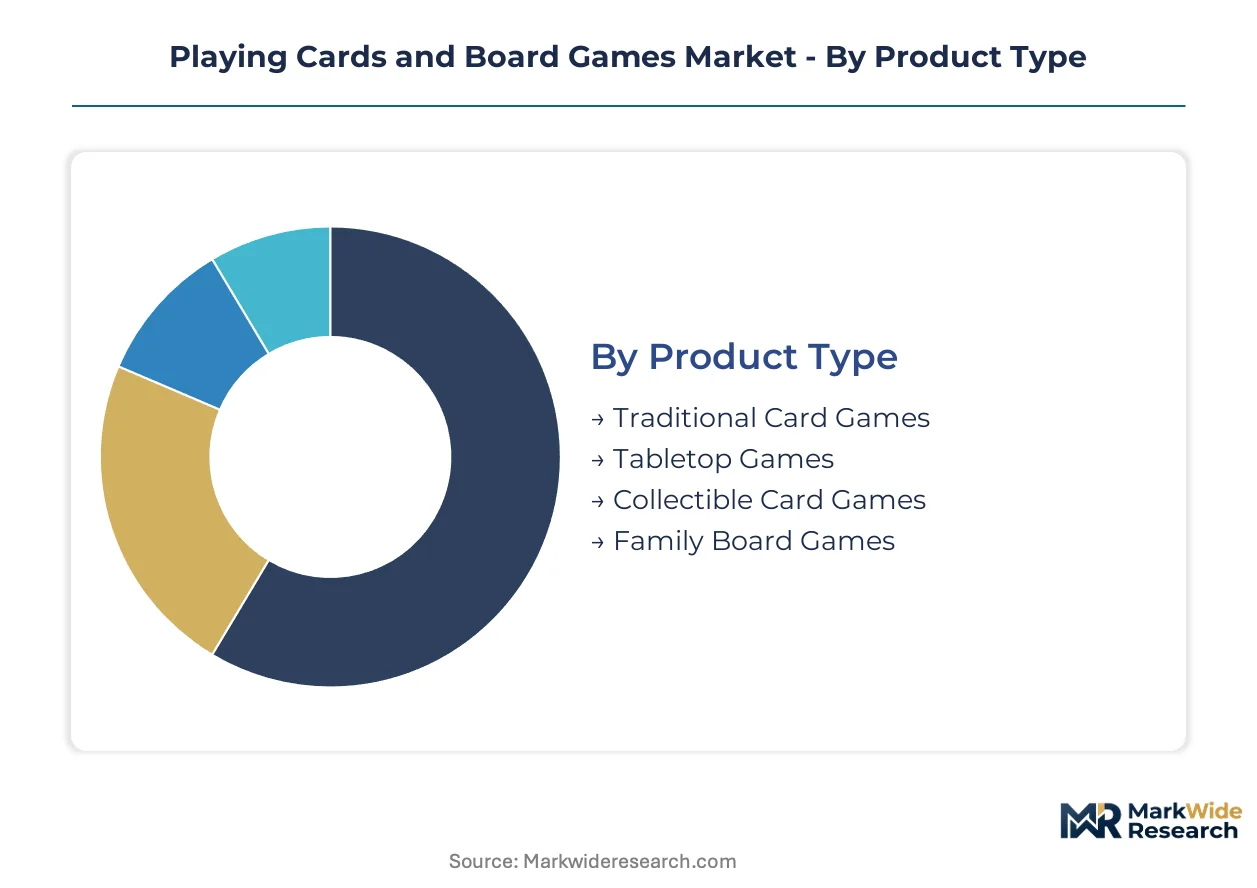
Segmentation in playing cards and board games reveals divergent margin structures across product architectures and audience psychographics. Manufacturers allocate R&D and tooling investments differently depending on whether a segment rewards volume throughput or premium pricing power.
Product Type:
Margin pools concentrate in segments with recurring purchase patterns and component upgrade cycles rather than one-time durable purchases.
- Collectible Card Games:These systems utilize randomized booster-pack distribution with tournament-legal card pools requiring regular set rotation. Demand clusters in organized play venues across Germany and the United States where sanctioned events mandate current-format compliance. The replenishment model generates predictable revenue streams independent of holiday gift cycles.
- Tabletop Games:Narrative-heavy systems employing modular boards, plastic miniatures, and branching scenario books command premium shelf positioning. Adult hobbyists in urban clusters rotate spending toward these screen-detached social formats with extended session duration. Component density and art production values justify price points that mass-market family formats cannot support.
- Traditional Card Games:Standard 52-card decks and regional variants serve price-sensitive casual purchasers through impulse retail placement.
- Family Board Games:Mass-market titles with simplified rule sets and durable plastic components dominate holiday gift purchasing cycles.
Family Board Games holds installed capacity across injection-molding facilities optimized for high-volume runs. Tabletop Games is rotating up the share rankings among adult demographic cohorts.
Target Audience:
Audience segmentation tracks discretionary spending elasticity and channel access patterns that determine go-to-market economics.
- Hobbyists:Dedicated collectors and competitive players maintain subscription relationships with specialty distributors and back crowdfunding campaigns for designer exclusives. This segment tolerates premium pricing for limited-edition components and imported European titles.
- Casual Gamers:Social players seeking accessible entry points drive volume for party-game formats and legacy-title reissues. Demand concentrates in online marketplaces and big-box retail where discovery depends on algorithmic recommendation and seasonal promotion.
- Families:Multi-generational households prioritize durability, safety certification, and rule simplicity for intergenerational play.
- Children:Age-appropriate titles with educational positioning and licensed character IP dominate this price-sensitive category.
Hobbyists anchor per-capita spending intensity. Casual Gamers is climbing the fastest in absolute participant counts.
Distribution Channel:
Channel selection determines inventory risk allocation and margin retention across the value chain.
- Specialty Stores:Hobby-focused retailers in Germany and the United States provide demo tables, organized play hosting, and staff curation that justifies premium pricing. These outlets capture recurring purchases from collector segments through loyalty programs and preview allocations.
- Online Retailers:E-commerce platforms aggregate long-tail inventory and enable direct publisher relationships that bypass wholesale markups. Fulfillment infrastructure investments by major platforms compress delivery timelines for impulse purchases.
- Retail Chains:Mass-market shelf placement depends on slotting fee negotiations and seasonal promotional calendars.
- Events:Convention and tournament direct sales generate burst revenue with minimal inventory carry.
Retail Chains hold installed capacity across seasonal gift-cycle logistics. Specialty Stores is gaining share fastest through hobbyist consolidation.
Game Complexity:
Complexity tiers align production specifications with audience skill acquisition curves and component tolerance requirements.
- Advanced:Multi-hour strategy systems with intricate rule interactions and high piece-count tolerance target experienced hobbyists. German manufacturers anchor quality positioning for this segment through precision-molded components and UV-cured finishes compliant with REACH standards.
- Expert:Tournament-grade titles with living rule documents and balance-patch protocols serve organized competitive communities. These systems require ongoing design support and community management infrastructure.
- Beginner:Entry-level titles with streamlined rule sets and minimal component count reduce purchase hesitation.
- Intermediate:Moderate complexity systems bridge casual and dedicated player bases.
Beginner holds installed capacity across mass-market production lines. Advanced is rotating up the share rankings through adult hobbyist expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for specialty cardstock and precision-molded game components, while the Los Angeles-Long Beach port complex handles trans-Pacific container flows for North American hobby retail channels.
United States
Organized play circuits and convention infrastructure drive collector-grade card game demand across metropolitan hobby clusters. The Consumer Product Safety Commission enforces small-parts standards for children's game components. Seattle and Austin anchor designer-title publishing ecosystems where crowdfunding campaigns pre-fund boutique production runs.
Germany
Adult hobbyists sustain premium tabletop purchasing through specialized retailer networks and designer-title import channels. ECHA REACH Annex XVII restrictions on phthalates and heavy metals compel UV-cured coating reformulations. Nuremberg and Munich concentrate precision manufacturing for card finishes and wooden game components compliant with EU material standards.
China
Guangdong and Zhejiang provinces host molded plastic miniature and custom dice fabrication for global board game publishers. SAMR product safety standards and GB toy safety certifications govern export-oriented production. Shenzhen's electronics integration capabilities support NFC-embedded hybrid game systems for digitally-augmented tabletop formats.
United Kingdom
Specialist hobby retailers in London and Manchester curate narrative-heavy imports for adult collector segments. The UKCA marking regime post-Brexit creates parallel certification requirements alongside retained EU REACH substance restrictions. Birmingham maintains legacy printing infrastructure for card stock finishing and specialty packaging.
Japan
Card game tournament culture and character-licensed collectible formats sustain domestic manufacturing for premium card finishes. METI product safety standards and JIS toy specifications govern material compliance. Tokyo and Osaka anchor design studios producing narrative tabletop titles for export to Asian hobby markets.
Playing Cards and Board Games Market Competitive Environment
Listed leaders compete with private specialists across distribution channel access and designer-title exclusivity arrangements. The vendor base clusters around three tiers: mass-market toy conglomerates with retail shelf dominance, European quality manufacturers with REACH-compliant production infrastructure, and boutique publishers leveraging direct-to-consumer crowdfunding platforms. Strategic moves concentrate on specialty retailer partnerships and biodegradable material transitions ahead of extended producer responsibility mandates.
Within the private specialist tier, Asmodee Group and Ravensburger AG exemplify European quality positioning through REACH-compliant manufacturing infrastructure and designer-title exclusivity. Hasbro Inc. represents the listed conglomerate archetype with legacy IP portfolios sustaining mass-market retail presence. These three anchors illustrate divergent competitive vectors: specialty channel depth, regulatory compliance leadership, and scaled retail distribution.
| Leading Market Players |
|---|
| Hasbro Inc. |
| Mattel Inc. |
| Asmodee Group |
| Ravensburger AG |
| Games Workshop Limited |
| Cartamundi Group |
| Spin Master Corp. |
| University Games Corporation |
| Buffalo Games |
| Others |
Value Chain & Pricing Dynamics
EU REACH Annex XVII substance restrictions gate both supplier qualification and price differentiation simultaneously, as manufacturers absorbing UV-cured coating reformulation costs capture premium positioning in German and French hobby channels while budget formats face margin compression or market exit.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on component density and certification grade. Hobbyist-grade titles with CE marking and REACH-compliant finishes command 40-60% price premiums over mass-market family formats. Cost compression in economy tiers is intensifying because pulp and paperstock volatility erodes producer margins without pricing power. Casual gamers purchasing through retail chains exhibit highest price sensitivity, while organized play participants in specialty channels tolerate premium pricing for tournament-legal card pools.
Supply Chain Analysis
Strategic stockpiling of coated cardstock and specialty papers dominates inventory strategy among European manufacturers confronting REACH reformulation timelines, while Asian producers maintain just-in-time molded plastic miniature flows. Component sourcing concentrates in China, Germany, and the United States, with Guangdong and Zhejiang provinces anchoring custom dice and miniature fabrication. Raw material dependencies center on petroleum-based ink chemistries, coated paperstock, and injection-molding resins. Single-source vulnerability runs through China-centric plastic component supply. Distribution feeds from Nuremberg and Hamburg through specialty retail networks in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The constrained supply of graphic designers capable of balancing narrative systems with production-ready mechanical engineering creates a persistent capability gap that shapes competitive outcomes across title volume growth.
For Market Incumbents: Shield market position by deepening exclusive designer-title partnerships that lock scarce creative talent away from crowdfunding competitors. Absorb REACH compliance costs through backward integration into UV-cured finishing capacity in Nuremberg rather than supplier renegotiation. Channel control through specialty retailer loyalty programs provides defensive moats against direct-to-consumer Kickstarter entrants. For New Entrants and Emerging Players: Organized play infrastructure services represent a service-layer gap where incumbents under-serve Latin American markets relative to per-capita entertainment spending. Brazil and Mexico present whitespace for distributor partnerships and localized tournament circuits. Direct-to-consumer crowdfunding campaigns enable pre-funded production runs that bypass traditional retail slotting fees and inventory risk. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable material transition programs as extended producer responsibility mandates approach. Long-term viability over a 5-10 year window favors targets with front-loaded compostable component investments and REACH-compliant European manufacturing footprints. The signal to watch is EU Packaging and Packaging Waste Directive enforcement timelines crossing implementation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Designer-Title Exclusivity Agreements | Locks scarce narrative-systems talent away from crowdfunding competitors in Seattle and Austin. |
| REACH-Compliant Finishing Capacity Expansion | Secures CE marking access for premium card game exports to German hobby channels. |
| Latin American Distributor Partnerships | Captures underdeveloped organized play infrastructure in Brazil and Mexico relative to spending levels. |
| Biodegradable Component Investment | Front-loads compostable cardstock transitions ahead of EU extended producer responsibility mandates. |
| Direct-to-Consumer Platform Launch | Bypasses mass retail slotting fees through Kickstarter pre-funding for boutique publisher titles. |
Study Parameters
Initial hypotheses were tested against primary input from game design studio heads, specialty retail buyers, organized play tournament organizers, and REACH compliance consultants, then refined through secondary validation against customs records, SEC 10-K filings of listed toy conglomerates, EU ECHA substance restriction databases, and crowdfunding platform disclosure data. Bottom-up title volume estimates were triangulated with top-down entertainment spending allocation models.
Variance-decomposition across product type, target audience psychographics, distribution channel economics, and game complexity tiers structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assumptions applied to baseline volume estimates. Industry-specific forecast inputs included organized play participation rates, REACH compliance cost absorption curves, and pulp futures price volatility indices.
Material uncertainties — regulatory enforcement acceleration, shipping disruption recurrence, and digital substitution threshold crossings — sit outside the modeled envelope. Forecasts reflect assumptions about sustained hobbyist discretionary spending and stable EU-China trade flows. Revision becomes warranted when biodegradable material cost parity crosses threshold viability against petroleum-based alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Eco-Friendly Toys Market
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Glow Sticks Market
Toys and Games
Kids Recreational Services Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Ferret Toys Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Sustainable Toys Market
Toys and Games
Animation Toys Market
Toys and Games
Toy Kitchens and Play Food Market
Toys and Games
Australia Toys and Games Market
Toys and Games
Bubble Blower Market
Toys and Games
United States Toys Market