
 Global Beauty and Personal Care Products Market | 2026-2036
Global Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beauty and Personal Care Products Market Analysis
ISO 16128 certification for natural and organic cosmetic ingredients is unwinding competitive barriers across the supply base. L'Oréal leverages its integrated R&D network to meet these botanical standards at scale. Estée Lauder anchors its premium positioning through controlled specialty retail channels. Shiseido competes by dominating skin-science formulations in Asian markets.
Beauty and personal care products encompass topical formulations for skin, hair, and personal hygiene, manufactured through emulsification, fermentation, or extraction processes with specified pH ranges and preservative systems; they serve consumer grooming, aesthetic enhancement, and dermatological maintenance needs. Skincare leads value generation as consumers prioritize barrier-repair and anti-aging actives. Haircare remains the most mature segment with consolidation around salon-professional and medicated sub-lines. Online Retail captures the fastest-growing distribution channel as direct-to-consumer platforms reshape margin pools away from traditional department stores.
FDA cosmetic regulations in the United States, EU REACH and MDR frameworks in Europe, and China's NMPA and GB standards collectively govern ingredient safety, labeling accuracy, and market access across major economies. These regulatory architectures force reformulation cycles and elevate compliance costs for cross-border entrants. Stakeholders must monitor divergence between EU hazard-based restrictions and US risk-assessment approaches when building regional product portfolios.
Market Dynamics
ISO 16128 certification is compressing ingredient sourcing advantages as botanical standards become table stakes, forcing reformulation investments across mid-tier suppliers while premium incumbents absorb compliance costs through captive R&D networks.
Growth Catalysts
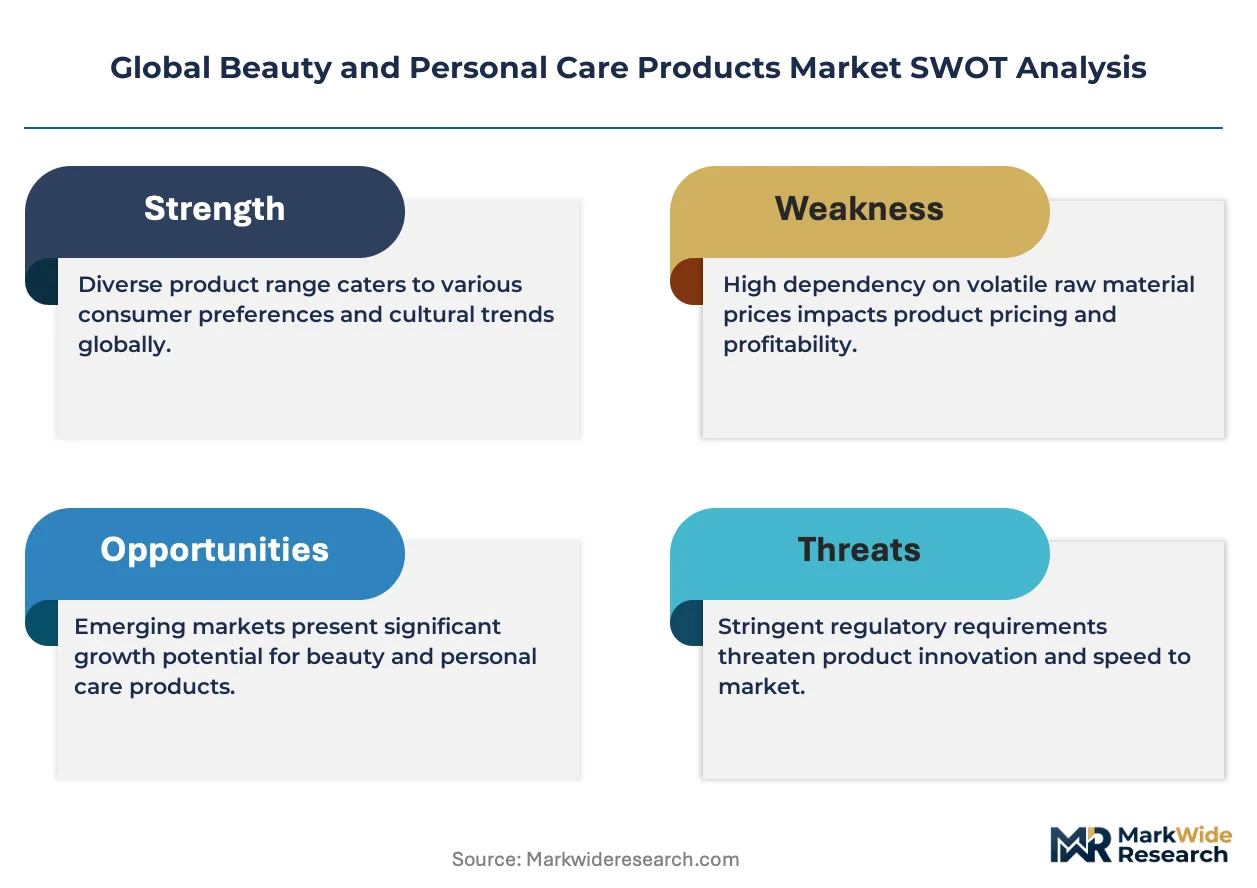
- Male Grooming Normalization:Social stigma erosion in South Korea and Brazil expands addressable population beyond traditional female-skewed targeting, opening dedicated shelf space and specialized retail formats.
- REACH Chemical Disclosure:EU ingredient transparency mandates accelerate clean-label competition, rewarding early movers with preemptive supply chain documentation.
- Biotech Fermentation:Engineered yeast platforms produce rare actives at scale, collapsing extraction-dependent supply constraints for peptides and ceramides.
Market Restraints
- Palm Oil Volatility:Southeast Asian feedstock price swings destabilize surfactant cost structures, squeezing mass-market margin pools dependent on stable input baselines.
- Preservative System Limitation:Clean-label phenoxyethanol avoidance narrows effective antimicrobial options, shortening product shelf life and complicating distribution logistics.
- China NMPA Registration Friction:Extended safety dossier timelines delay market entry for novel actives, favoring incumbents with established ingredient master files.
Strategic Opportunities
- India Tier-II Penetration:Underdeveloped organized retail in Lucknow and Jaipur creates first-mover advantage for direct-to-consumer platforms bypassing fragmented traditional trade.
- Microbiome Personalization:Skin flora sequencing convergence with AI formulation matching enables subscription models with retention economics superior to transactional retail.
- EU Green Deal Incentives:Carbon-border adjustment mechanisms reward localized European manufacturing with compliance cost advantages over import-dependent competitors.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in emulsion stability and active compatibility commands premium compensation, constraining mid-cap R&D scaling.
- ISO 16128 Certification Timeline:Third-party verification backlogs extend product launch windows, compressing revenue realization against fixed development costs.
- Legacy ERP Integration:Batch record digitization for FDA cosmetic facility registration encounters friction with paper-based quality systems at contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beauty and Personal Care Products Market |
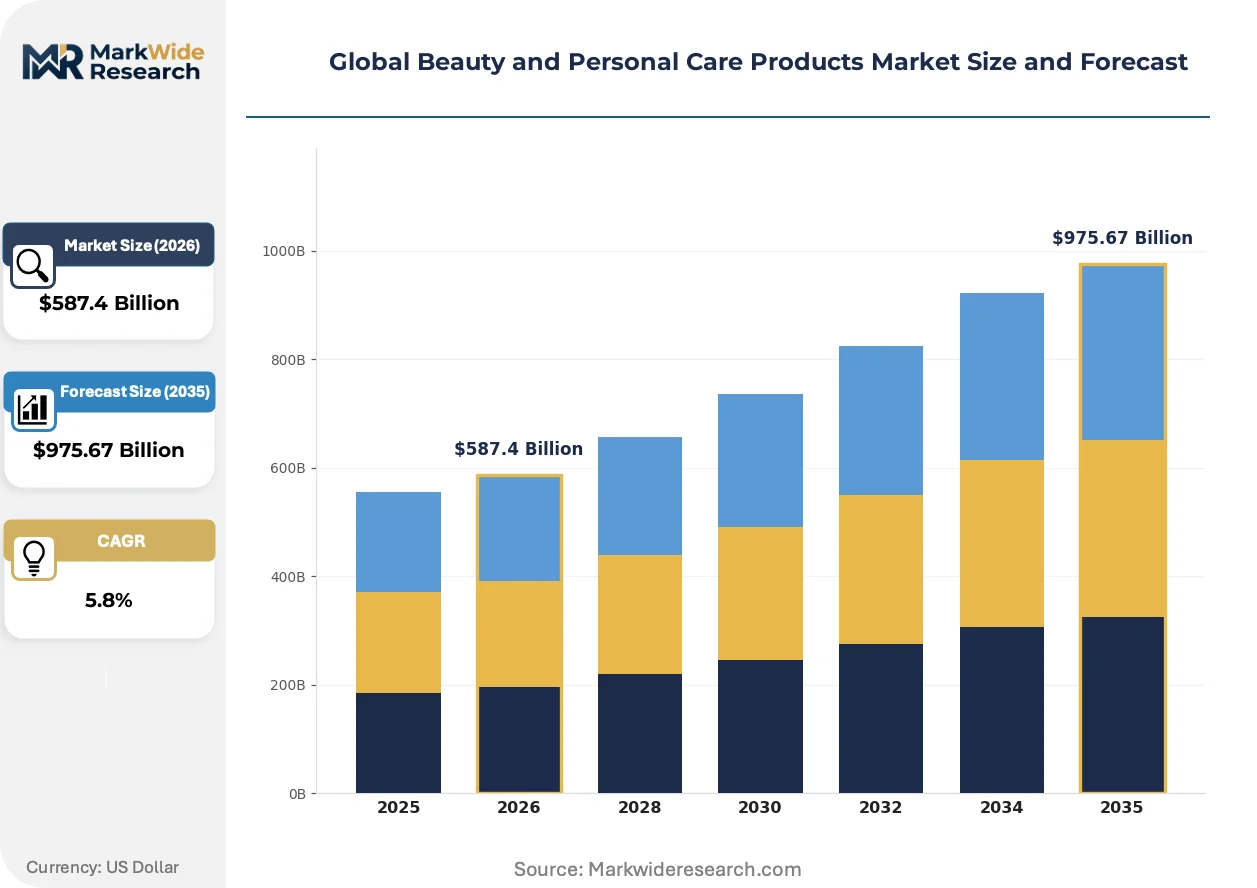
| Market Size in 2026 | $587.4 Billion |
| Market Size in 2035 | $975.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Distribution Channel: Online Retail, Department Stores, Specialty Stores, Supermarkets Customer Type: Mass Market, Premium, Luxury, Professional End User: Women, Men, Unisex, Teens |
| Companies Covered | Procter & Gamble, Chanel, L'Oréal, Shiseido, Beiersdorf, Unilever, LVMH, Coty, Estée Lauder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beauty and Personal Care Products Market Emerging Trajectories
Biotechnology is collapsing traditional extraction economics while regulatory fragmentation forces parallel compliance architectures and digital channels rewrite margin capture mechanics.
Precision fermentation for rare botanicals is supplanting agricultural cultivation and solvent extraction. Premium skincare brands in Japan and France adopt recombinant collagen and squalane at accelerating pace. This biotechnology shift compresses seasonality risk and enables consistent active concentrations previously unattainable through crop-dependent sourcing.
REACH MDR convergence in Europe tightens ingredient safety substantiation requirements beyond cosmetic scope into quasi-medical claims. Manufacturers must now maintain clinical dossiers for barrier-repair and anti-aging positioning. The premium segment bears disproportionate compliance burden as claim intensity correlates directly with documentation depth.
Livestream commerce platforms in China now capture majority share of new customer acquisition for domestic challenger brands. Beauty advisors convert through real-time demonstration rather than static shelf presentation. This channel rotation concentrates marketing spend with platform algorithms rather than traditional media buyers, reshaping vendor economics.
Global Beauty and Personal Care Products Market Segmentation
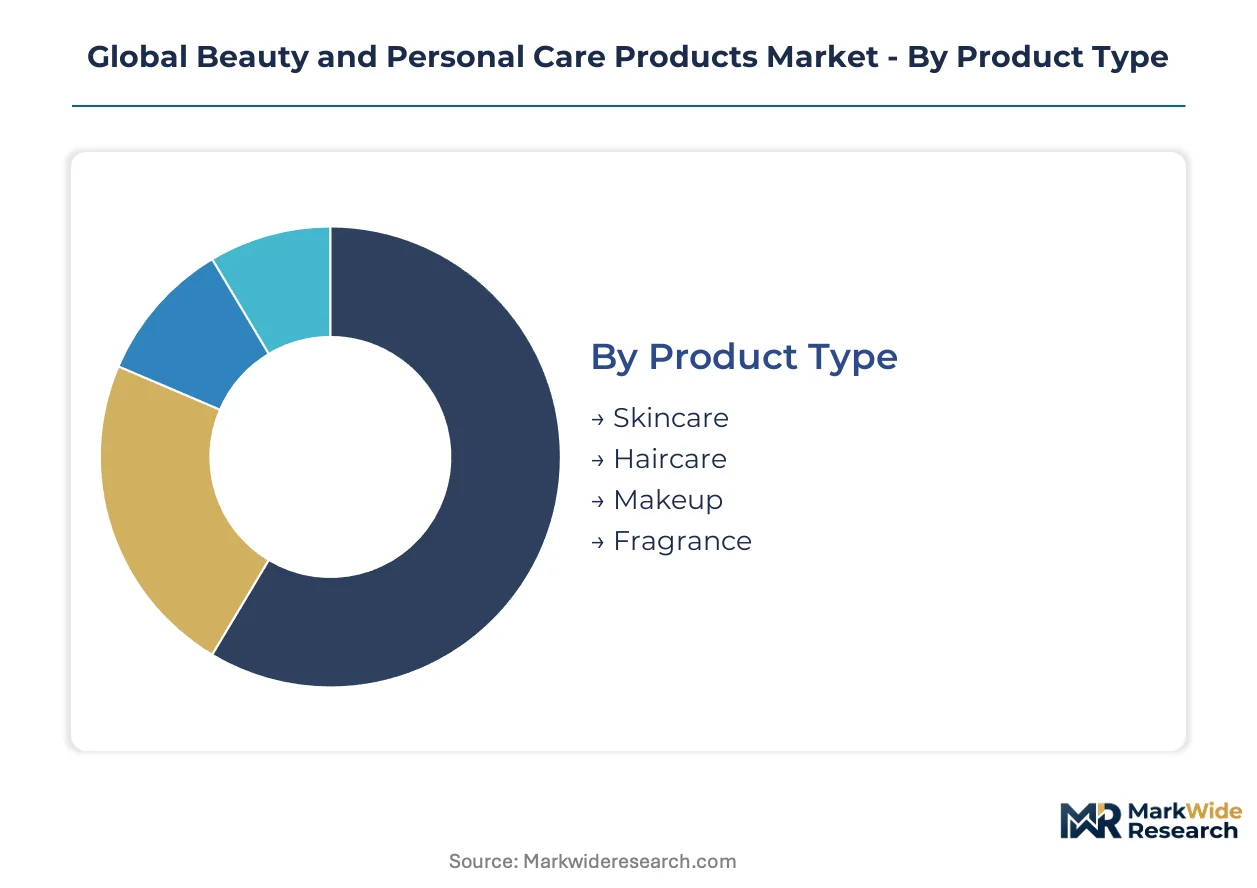
Channel fragmentation across direct-to-consumer platforms and specialty retail creates divergent margin structures that reward precise segment targeting. Formulation complexity and certification requirements vary sharply across product tiers, forcing suppliers to anchor capabilities in specific customer strata rather than spanning all four quadrants.
Product Type:
Channel-mix dynamics concentrate high-margin skincare through specialty stores and medical aesthetics clinics, while haircare and fragrance flow predominantly through mass retail and duty-free corridors.
- Skincare:Barrier-repair serums and ceramide-rich moisturizers command formulation premiums. Demand clusters in South Korea and France where consumers prioritize dermatological efficacy over cosmetic coverage, driven by aging demographics and pollution-defense positioning.
- Haircare:Salon-professional lines and scalp-treatment sub-segments anchor this mature category. Expansion concentrates in Brazil and India where humidity-driven frizz management and hard-water mineral buildup create specialized regional requirements.
- Makeup:Hybrid skincare-makeup formulations with SPF and active ingredients blur traditional boundaries.
- Fragrance:Niche perfumery and personalized scent subscriptions gain traction against mass-market celebrity launches.
Skincare dominates installed base. Haircare is where expansion concentrates.
Distribution Channel:
Margin compression varies by channel tier, with online retail capturing customer acquisition economics previously absorbed by department store concessions.
- Online Retail:Direct-to-consumer platforms and livestream commerce collapse traditional wholesale markups. Demand concentrates in China where platform algorithms reshape vendor economics away from static shelf presentation toward real-time conversion metrics.
- Department Stores:Prestige counters and beauty advisor staffing sustain premium positioning through tactile trial. Traffic erosion in the United States and Japan forces footprint consolidation, with surviving locations converting to experience-centric service models.
- Specialty Stores:Sephora and Ulta Beauty anchor this channel with curated discovery environments.
- Supermarkets:Mass-market essentials and private-label alternatives drive volume throughput.
Department stores retain the highest customer lifetime value per square meter. Online retail is climbing the fastest.
Customer Type:
Certification intensity scales with price tier, as ISO 16128 botanical standards and clinical substantiation requirements concentrate in premium and luxury segments.
- Mass Market:Price-competitive formulations with simplified preservative systems target volume turnover. Demand concentrates in India's Tier-II cities where organized retail penetration remains underdeveloped and direct-to-consumer platforms bypass fragmented traditional trade.
- Premium:Science-backed positioning with dermatologist co-development and controlled specialty retail distribution. Expansion concentrates in Germany and the United Kingdom where consumers trade up from mass-market basics toward proven efficacy claims.
- Luxury:Artisan craftsmanship and limited-edition releases sustain scarcity premiums.
- Professional:Salon-exclusive and medical-aesthetic channels require practitioner certification.
Mass market holds the largest unit volume. Premium is where margin expansion concentrates.
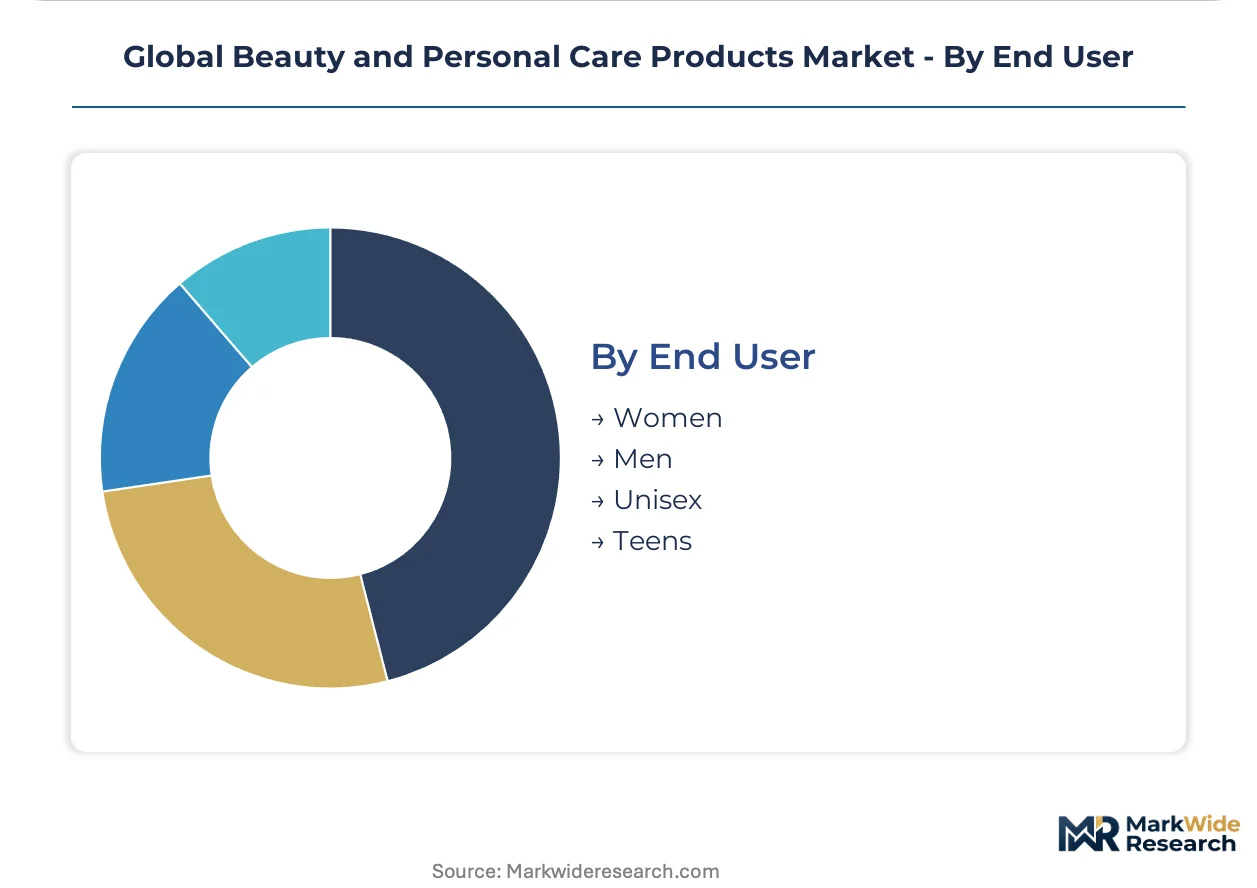
End User:
Gendered targeting erodes as unisex formulations and male-specific lines capture shelf space previously reserved for female-skewed SKUs.
- Women:Traditional core demographic with established purchasing patterns across all product categories. Demand concentrates in anti-aging and pigmentation-correction segments where clinical substantiation commands price premiums.
- Men:Beard care, scalp health, and simplified multi-step routines normalize male grooming. Expansion concentrates in South Korea and Brazil where social stigma erosion opens dedicated retail formats and specialized marketing channels.
- Unisex:Gender-neutral packaging and universal skin-concern positioning reduce SKU proliferation costs.
- Teens:Acne management and social-media-influenced trial drive entry-point consumption.
Women retain the largest absolute spending base. Men represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH chemical disclosure mandates and China's NMPA registration reforms are redirecting investment toward compliant manufacturing clusters. Domestic brand strength in livestream commerce channels is reshaping competitive entry patterns across Asia-Pacific. Regional differentiation now hinges on regulatory convergence speed rather than pure demand scale.
United States
FDA cosmetic facility registration rules and MoCRA implementation are elevating documentation burdens for contract manufacturers. Clean-label preservative reformulation concentrates in New Jersey and California R&D corridors. Direct-to-consumer platforms headquartered in San Francisco and New York capture customer acquisition economics previously absorbed by department store concessions.
China
Domestic challenger brands leverage livestream commerce algorithms on Douyin and Xiaohongshu to capture younger consumers. NMPA extended safety dossier timelines delay market entry for novel actives, favoring incumbents with established ingredient master files. Manufacturing clusters in Shanghai and Guangzhou anchor production for both domestic consumption and regional export.
Germany
EU Green Deal carbon-border adjustment mechanisms reward localized European manufacturing with compliance cost advantages. REACH MDR convergence tightens ingredient safety substantiation requirements beyond cosmetic scope into quasi-medical claims. The Rhine-Ruhr industrial corridor hosts precision fermentation facilities producing recombinant collagen and squalane at scale.
South Korea
Social stigma erosion around male grooming expands addressable population beyond traditional female-skewed targeting. MFDS cosmetic regulations align with international standards while maintaining distinct documentation requirements for functional claims. Seoul anchors skin-science formulation clusters where dermatological efficacy commands price premiums over cosmetic coverage.
Brazil
Humidity-driven frizz management and hard-water mineral buildup create specialized regional requirements for haircare formulations. ANVISA registration pathways for cosmetics maintain distinct timelines from pharmaceutical approvals, creating parallel compliance architectures. São Paulo and Rio de Janeiro concentrate both manufacturing capacity and specialized retail formats for dedicated male grooming lines.
Global Beauty and Personal Care Products Market Vendor Landscape
Listed leaders compete with private specialists across channel access and R&D amortization dimensions. The vendor base stratifies into three tiers: integrated conglomerates with captive ingredient networks, mid-cap specialists anchored in single categories, and private-label manufacturers serving retail-owned brands. Strategic moves concentrate on biotech fermentation partnerships and direct-to-consumer platform acquisitions.
Within the integrated conglomerate tier, L'Oréal and Estée Lauder occupy positions defined by R&D network scale and controlled specialty retail distribution. Shiseido anchors the Asia-centric skin-science archetype through dermatological formulation credibility. These three exemplify how premium positioning requires parallel investment in clinical substantiation and channel control rather than volume-driven mass-market penetration.
| Leading Market Players |
|---|
| Procter & Gamble |
| Chanel |
| L'Oréal |
| Shiseido |
| Beiersdorf |
| Unilever |
| LVMH |
| Coty |
| Estée Lauder |
| Others |
Supply Flow & Price Mechanics
Ninety-day ingredient certification timelines compress working capital cycles while amplifying pricing power for suppliers with pre-validated ISO 16128 dossiers. This lead-time structure concentrates margin capture among integrated conglomerates that internalize botanical verification, leaving mid-tier formulators exposed to spot-market volatility in palm-derived surfactants and fermented actives.
Pricing Analysis
Certification level creates the primary spread between premium and mass-market tiers, with ISO 16128-compliant botanical ingredients commanding substantial markups over conventional synthetics. Three-tier pricing structure across premium, standard, and economy levels reflects divergent substantiation burdens, as clinical dossier requirements for barrier-repair claims inflate development amortization. Pricing pressure stems from clean-label preservative reformulation costs, which squeeze mass-market margins most acutely. Mass-market buyers exhibit highest price sensitivity, while luxury consumers absorb certification premiums without volume elasticity.
Supply Chain Analysis
Inventory cycles stretch to 120 days for REACH-compliant documentation, forcing working capital commitments that favor scaled incumbents over emerging challengers. Manufacturing concentrates in China, Germany, and South Korea, where precision fermentation facilities and skin-science formulation clusters anchor regional supply. Raw material dependencies center on Southeast Asian palm oil derivatives, recombinant collagen from engineered yeast platforms, and ceramide precursors. Single-source vulnerability pervades rare active extraction, as agricultural cultivation yields prove inconsistent against biotech alternatives. Distribution runs through direct-to-consumer platforms and specialty retail, with livestream commerce capturing fastest-growing downstream share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based personalization services attach recurring revenue layers that outpace transactional product growth, as microbiome-matched formulation models capture superior retention economics. This service-attach dynamic restructures vendor economics away from one-time purchase margins toward lifetime value optimization.
For Market Incumbents: Compound channel control through captive specialty retail partnerships and direct-to-consumer platform acquisitions that isolate margin pools from wholesale compression. Biotech fermentation partnerships with engineered yeast platforms secure supply of rare actives against agricultural volatility. Preemptive REACH MDR dossier investment builds regulatory moats that delay challenger entry timelines.
For New Entrants and Emerging Players: Post-purchase skin-health monitoring represents an underserved service layer where incumbents under-serve retention opportunities. India's Tier-II cities offer penetrable white space, as fragmented traditional trade yields to direct-to-consumer platform bypass. Livestream commerce algorithms provide go-to-market angle for algorithm-native brands unburdened by legacy media-buying structures.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation infrastructure, favoring asset-light formulation specialists over captive manufacturing plays. Acquisition targets should display microbiome personalization capabilities or established ingredient master files with China's NMPA. Watch for carbon-border adjustment mechanism implementation as inflection signal rewarding localized European manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Fermentation Partnership | Engineered yeast platforms collapse extraction economics for rare ceramides and peptides. |
| Direct-to-Consumer Platform Acquisition | Livestream commerce algorithms capture customer acquisition economics from department stores. |
| ISO 16128 Certification Investment | Pre-validated botanical dossiers compress competitor launch windows by ninety days. |
| Microbiome Personalization Development | Skin flora sequencing enables subscription models with superior retention economics. |
| Localized European Manufacturing Expansion | EU Green Deal carbon-border adjustments reward regional production with compliance advantages. |
Methodological Framework
A spread of perspectives from brand managers, category buyers at specialty retailers, formulation chemists, and supply chain directors converged on the working assumptions driving this analysis. Primary fieldwork with these stakeholders combined with secondary validation from NMPA registration databases, REACH substance dossiers, customs trade records, and platform commerce metrics. Bottom-up SKU-level modeling triangulated against top-down macroeconomic demand projections.
Segmentation dimensions modeled include product type, distribution channel, customer tier, and end-user demographic across the analysis window. CAGRs derived from trend extrapolation anchored in historical volume trajectories and regulatory inflection points. Forecast inputs incorporated livestream commerce penetration curves and biotech fermentation capacity buildouts.
Forecasts assume regulatory continuity in EU REACH, US FDA MoCRA, and China NMPA regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Scalp Massager Market
Beauty & Personal Care
United Kingdom Cosmetics Products Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
Australia Skin Care Products Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Beard Grooming Products Market