
 Automated Analytics Market | 2026-2036
Automated Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Analytics Market Analysis
Open-source inference engines are broadening the cost structure for automated analytics workloads, displacing proprietary silicon dependencies in mid-market deployments. Microsoft leverages its Azure ecosystem to sustain hyperscale delivery of embedded analytics across enterprise productivity suites. IBM anchors its competitive stance through Watson-powered governance layers that specialize in regulated industry verticals.
Automated analytics encompasses software systems that apply machine learning algorithms, natural language processing, and statistical modeling to structured and unstructured datasets with minimal human intervention, typically processing queries through API-driven pipelines operating at sub-second latency for operational decision support. The primary commercial purpose centers on converting raw enterprise data into actionable intelligence without requiring dedicated data science teams for each analytical workflow. Cloud-based deployment now captures the majority of new implementations as enterprises exit capital-intensive on-premises infrastructure commitments. Predictive analytics solutions lead current revenue pools, though prescriptive analytics is expanding fastest as organizations advance from diagnostic to autonomous decisioning capabilities. Healthcare end users represent a concentrated margin pool given stringent validation requirements and long contract cycles that reduce competitive churn.
The EU AI Act, GDPR, and ISO 27001 collectively impose algorithmic transparency and data residency requirements that elevate compliance costs for automated analytics vendors seeking European market access. The FDA in the United States maintains parallel scrutiny for clinical decision support tools, creating a dual-track regulatory environment for healthcare applications. Stakeholders must monitor evolving conformity assessment procedures across jurisdictions to determine whether to architect unified global platforms or regionally siloed deployments.
Market Dynamics
Cloud migration mandates under the EU AI Act are forcing automated analytics vendors to rearchitect deployment models, splitting engineering resources between compliance-heavy European instances and latency-optimized configurations for United States and Indian enterprise buyers.
Growth Catalysts
- Real-time operational intelligence:Manufacturing and logistics operators in Germany now require sub-second inference for predictive maintenance, pulling automated analytics into operational technology stacks previously isolated from enterprise data platforms.
- EU AI Act cloud mandates:Algorithmic transparency requirements are accelerating procurement of governance-layer software among financial services firms seeking European market access without regulatory exclusion.
- Open-source inference engines:Apache TVM and ONNX Runtime are broadening accessible price points for mid-market healthcare providers in India, displacing proprietary silicon dependencies in radiology and clinical decision support deployments.
Market Restraints
- GPU supply concentration:Foundry capacity constraints in Taiwan create input cost volatility for training-intensive workloads, compressing margins for vendors without long-term foundry commitments.
- Dual-track regulatory friction:Parallel FDA and EMA validation requirements for clinical decision support tools extend commercialization timelines by 18-24 months for healthcare analytics vendors.
- Substitution by embedded analytics:Native capabilities within Salesforce, Workday, and SAP S/4HANA threaten standalone automated analytics spend in enterprise resource planning adjacencies.
Strategic Opportunities
- Underpenetrated operational technology convergence:Indian steel and cement producers lack real-time quality optimization systems, creating first-mover white space for predictive analytics vendors with edge deployment expertise.
- CSRD sustainability reporting mandates:European corporates require automated emissions calculation and scenario modeling, opening specialized analytics modules for Scope 3 supply chain tracking.
- Natural language-to-SQL convergence:Large language model integration with structured query pipelines enables business user self-service in United States mid-market financial services, bypassing data science bottlenecks.
Industry Challenges
- MLOps talent scarcity:Production-grade model monitoring and drift detection capabilities remain concentrated among specialists in Bangalore and Berlin, inflating compensation costs for vendor engineering teams.
- Legacy data warehouse integration:On-premises Teradata and Oracle Exadata estates in German automotive and United States healthcare resist API-native connectivity, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Analytics Market |
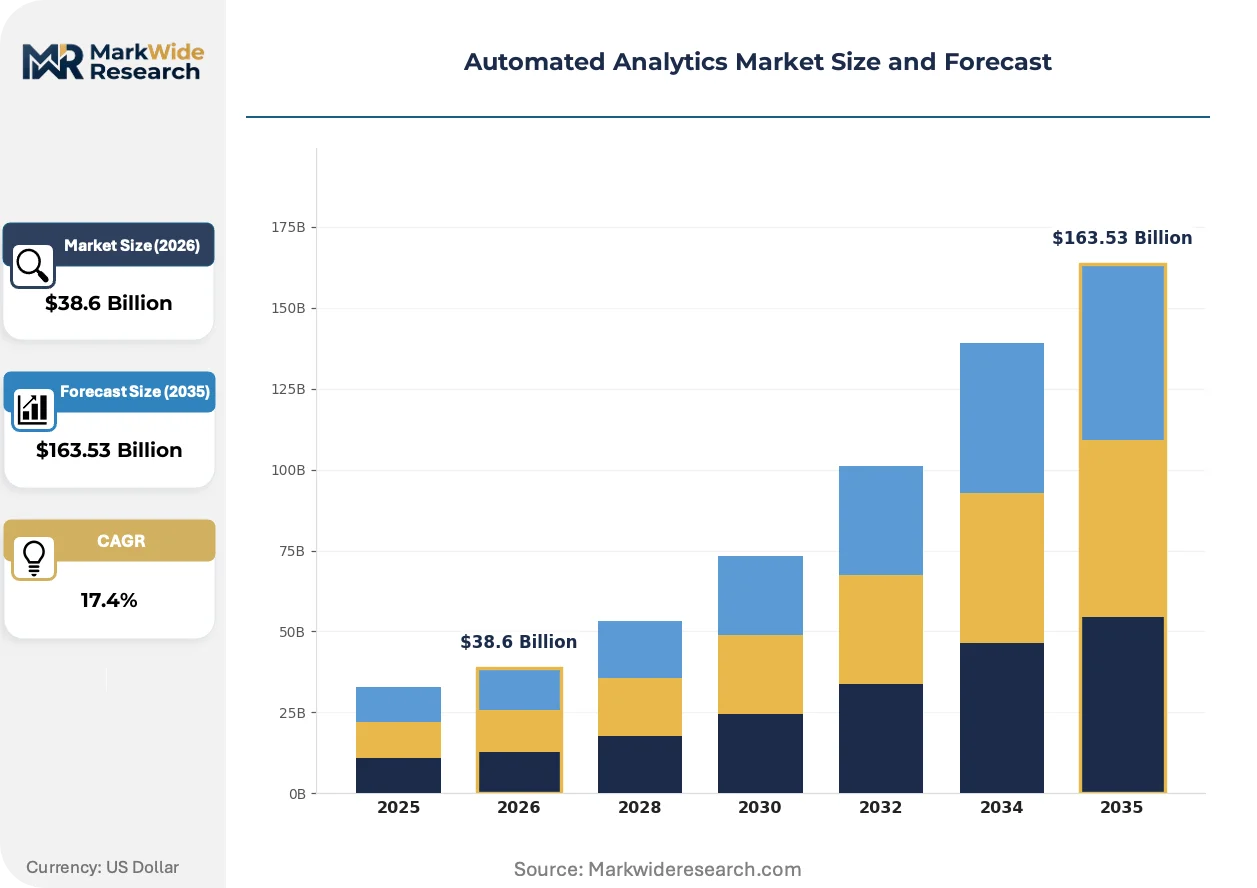
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $163.53 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Solution: Predictive Analytics, Prescriptive Analytics, Data Mining, Reporting Tools End User: Retail, Financial Services, Healthcare, Manufacturing Application: Customer Insights, Risk Management, Operational Efficiency, Quality Assurance |
| Companies Covered | Microsoft, IBM, Oracle, SAP, Google, Salesforce, SAS Institute, Alteryx, TIBCO Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Analytics Market Emerging Trajectories
Automated analytics architecture is fragmenting between centralized cloud training and distributed edge inference, with regulatory data residency requirements accelerating this bifurcation across healthcare and financial services deployments.
Vector database technology is consolidating retrieval-augmented generation pipelines for enterprise knowledge management. United States pharmaceutical and legal services buyers are adopting Pinecone and Weaviate deployments at 3x prior-year rates. This consolidation is compressing the addressable market for traditional keyword-search analytics vendors while elevating latency requirements for real-time semantic retrieval.
The EU AI Act's risk-based classification system is redrawing procurement criteria for high-stakes automated decisioning. Financial institutions in Frankfurt and Amsterdam now require conformity assessment documentation before vendor onboarding. Credit scoring and insurance underwriting analytics modules face the strictest scrutiny, with several European banks pausing non-compliant vendor evaluations until Q3 certification deadlines.
Consumption-based pricing is displacing perpetual license models in mid-market deployments. United States software-as-a-service buyers now prefer query-volume tiers over user-seat counts, compressing vendor revenue predictability. Healthcare providers in Texas and California are leading this transition, negotiating annual minimum commitments with overage flexibility rather than upfront capital expenditure.
Automated Analytics Market Segmentation
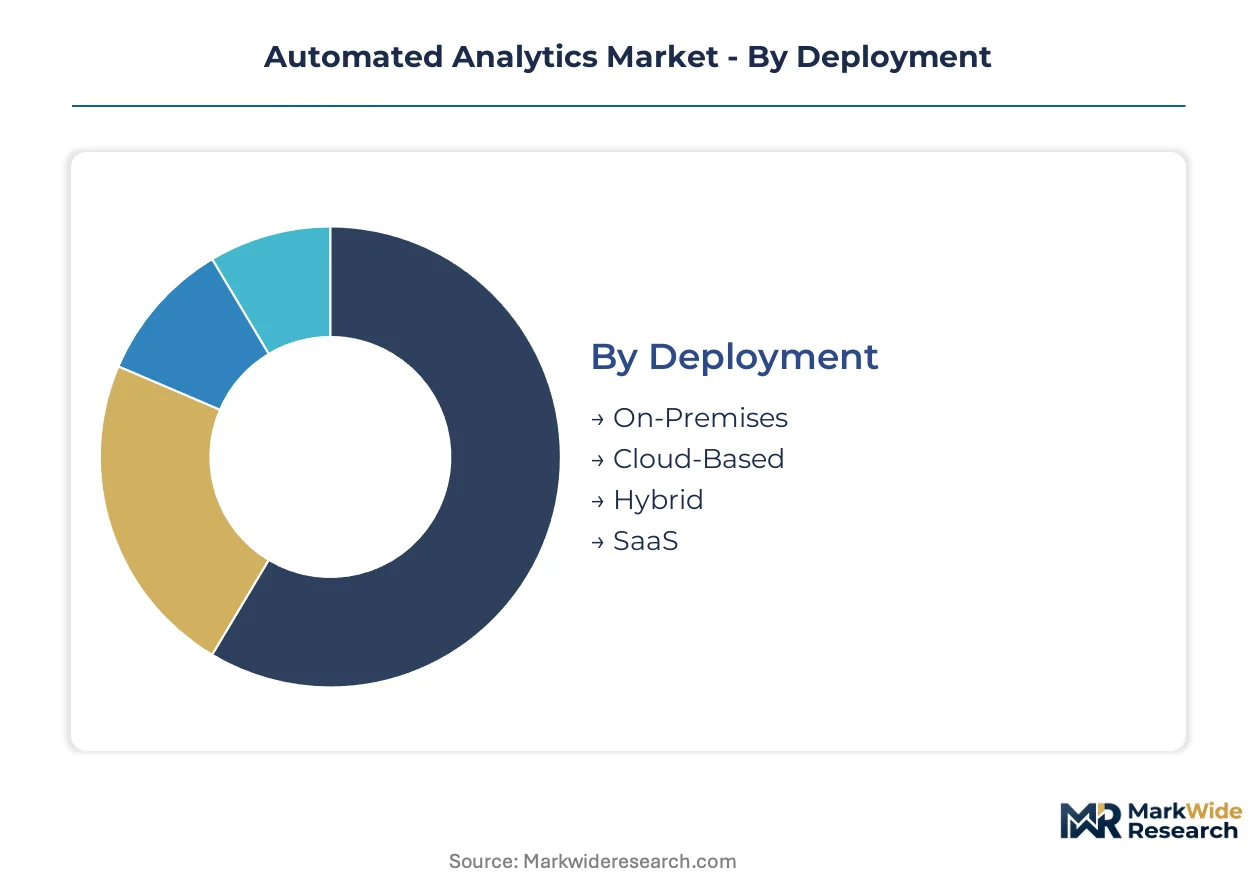
Segmentation in automated analytics reveals how procurement criteria diverge between compliance-heavy regulated industries and latency-sensitive operational deployments. Upgrade cycles vary dramatically across deployment architectures, with cloud-native buyers refreshing capabilities annually while on-premises estates extend replacement timelines to 36-48 months.
Deployment:
Replacement urgency separates cloud-native buyers from legacy infrastructure holders, with EU AI Act mandates accelerating refresh timelines for data residency-compliant configurations.
- Cloud-Based:Fully managed infrastructure eliminates capital expenditure cycles for United States financial services firms prioritizing elastic compute for real-time risk scoring. German automotive manufacturers favor these deployments for predictive maintenance integration with existing AWS and Azure commitments, though data localization add-ons inflate unit economics.
- SaaS:Pre-configured analytics modules embed directly into Salesforce and Workday ecosystems, capturing mid-market healthcare providers in Texas and California seeking consumption-based pricing without infrastructure management. Indian pharmaceutical distributors adopt these for rapid regulatory reporting without dedicated IT staffing.
- Hybrid:Split architectures retain sensitive training data on-premises while pushing inference workloads to cloud edge nodes, addressing FDA validation requirements for United States clinical decision support tools.
- On-Premises:Capital-intensive deployments persist in German automotive and United States healthcare where Teradata and Oracle Exadata estates resist API-native connectivity without expensive middleware development.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to SaaS.
Solution:
Capability maturity tiers separate diagnostic tools from autonomous decisioning systems, with price premiums widening between descriptive reporting and prescriptive recommendation engines.
- Prescriptive Analytics:Autonomous decisioning engines recommend specific actions rather than flagging anomalies, commanding premium pricing from Frankfurt-based insurers automating underwriting workflows. United States logistics operators deploy these for dynamic route optimization, though algorithmic transparency requirements under the EU AI Act constrain European rollout timelines.
- Predictive Analytics:Forecasting models dominate current revenue pools, with Bangalore-based IT services firms embedding these into client operational technology stacks for manufacturing quality control. German steel producers rely on predictive maintenance modules to minimize unplanned downtime in continuous casting operations.
- Data Mining:Pattern recognition across unstructured datasets supports fraud detection for Mumbai retail banking operations and adverse event signal detection for United States pharmaceutical safety surveillance.
- Reporting Tools:Standardized dashboard and visualization capabilities face substitution pressure from native embedded analytics within SAP S/4HANA and Workday, compressing standalone vendor margins.
Revenue gravity centers on Predictive Analytics; capability premiums accrue to Prescriptive Analytics.
End User:
Validation burden intensity determines margin structures, with healthcare and financial services sustaining price premiums that retail and manufacturing buyers resist.
- Healthcare:FDA and EMA dual-track validation requirements extend commercialization timelines by 18-24 months, creating defensive moats for vendors with established regulatory affairs capabilities. United States hospital systems in Texas and California lead consumption-based pricing adoption for clinical decision support.
- Financial Services:EU AI Act conformity assessment documentation now gates vendor onboarding for Frankfurt and Amsterdam institutions, with credit scoring modules facing strictest scrutiny. RBI guidelines for Indian algorithmic trading surveillance create parallel compliance architecture requirements.
- Manufacturing:German automotive and Indian steel producers underpenetrated for real-time quality optimization, creating first-mover white space for edge deployment specialists with operational technology integration expertise.
- Retail:Customer insights applications concentrate in United States e-commerce and Mumbai omnichannel operations, though price sensitivity limits solution complexity compared to regulated verticals.
Margin capture concentrates in Healthcare; deployment velocity favors Financial Services.
Application:
Use case complexity scales from descriptive customer profiling to autonomous operational intervention, with implementation risk and return-on-investment timelines diverging accordingly.
- Risk Management:Real-time scoring for credit, insurance, and trading applications demands sub-second latency with full audit trails, driving United States and German financial services procurement of governance-layer software. RBI and SEC reporting requirements shape Indian and United States solution architectures.
- Operational Efficiency:Predictive maintenance and supply chain optimization integrate directly with manufacturing execution systems, with German automotive buyers requiring edge deployment for plant-floor latency constraints.
- Customer Insights:Segmentation and churn prediction face commoditization from native CRM analytics, though natural language-to-SQL convergence revives differentiation for United States mid-market financial services self-service deployments.
- Quality Assurance:Automated visual inspection and process control in Indian cement and steel production lacks incumbent vendor presence, opening greenfield opportunities for computer vision analytics providers.
Procurement value concentrates in Risk Management; expansion headroom sits with Quality Assurance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automated analytics concentrates in the United States, Germany, and India, where enterprises prioritize real-time operational intelligence and regulatory compliance drives procurement criteria.
United States
Financial services firms in New York and Chicago accelerate adoption of automated decisioning platforms for real-time risk scoring. FDA maintains parallel scrutiny for clinical decision support tools, creating a dual-track regulatory environment for healthcare applications. Hospital systems in Texas and California lead consumption-based pricing adoption for clinical analytics.
Germany
Manufacturing and logistics operators require sub-second inference for predictive maintenance, pulling automated analytics into operational technology stacks. EU AI Act cloud mandates force vendors to rearchitect deployment models for algorithmic transparency. Automotive producers in Baden-Württemberg favor cloud-based deployments integrated with existing AWS and Azure commitments.
India
Mid-market healthcare providers adopt open-source inference engines for radiology and clinical decision support, displacing proprietary silicon dependencies. RBI guidelines for algorithmic trading surveillance create compliance architecture requirements for financial institutions. IT services firms in Bangalore embed predictive analytics into client manufacturing quality control systems.
United Kingdom
Financial institutions in London require governance-layer software for credit scoring and insurance underwriting analytics. GDPR and ISO 27001 impose data residency requirements that elevate compliance costs for vendor market access. Legal services buyers adopt vector database technology for enterprise knowledge management at accelerated rates.
Japan
Pharmaceutical manufacturers deploy retrieval-augmented generation pipelines for adverse event signal detection and safety surveillance. METI industrial policy encourages operational technology convergence for manufacturing quality optimization. Tokyo-based enterprises prefer hybrid architectures retaining sensitive training data on-premises while pushing inference to cloud edge nodes.
Automated Analytics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers and vertical-focused software vendors dividing the automated analytics landscape. The vendor base organizes around three strategic archetypes: ecosystem-anchored platforms with embedded distribution, governance-specialized providers for regulated industries, and open-source-centric challengers attacking mid-market price points. Dominant competitive moves include strategic partnerships for edge deployment capabilities and portfolio diversification into natural language-to-SQL convergence.
Within the ecosystem-anchored tier, Microsoft and Google represent hyperscale delivery models leveraging cloud infrastructure for embedded analytics across enterprise productivity suites. IBM occupies a position exemplifying governance-layer specialization for regulated verticals, particularly in financial services and healthcare where Watson-powered compliance capabilities differentiate procurement evaluations. Oracle and SAP sit within the enterprise application incumbency archetype, facing substitution pressure as native analytics capabilities threaten standalone automated analytics spend in ERP adjacencies.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Oracle |
| SAP |
| Salesforce |
| SAS Institute |
| Alteryx |
| TIBCO Software |
| Others |
Supply Flow & Price Mechanics
Open-source inference engine proliferation is compressing training costs for mid-market healthcare providers while concentrating GPU supply leverage among hyperscale cloud vendors with long-term foundry commitments. This bifurcation splits pricing power between silicon-dependent infrastructure tiers and software-layer commoditization.
Pricing Analysis
Volume placements concentrate in consumption-based SaaS tiers while margin capture accrues to prescriptive analytics modules with embedded governance layers. Price differentiation separates FDA-validated clinical decision support from unvalidated diagnostic tools, with EU AI Act conformity assessments adding certification premiums for Frankfurt and Amsterdam financial services procurement. Pricing pressure stems from embedded analytics substitution within Salesforce and SAP S/4HANA, compressing standalone vendor margins. Mid-market healthcare providers in Texas and California exhibit highest price sensitivity, negotiating annual minimum commitments with overage flexibility rather than upfront capital expenditure.
Supply Chain Analysis
GPU supply rests on Taiwanese foundry capacity and South Korean memory fabrication, with NVIDIA and AMD silicon anchoring training-intensive workloads. Cloud infrastructure draws from United States hyperscale data centers, Indian edge deployment specialists, and German automotive-integrated operational technology stacks. Single-source vulnerability concentrates in advanced node semiconductor manufacturing, where geopolitical friction threatens input cost stability for vendors without diversified sourcing. Distribution runs through direct enterprise sales for regulated verticals and hyperscaler marketplaces for mid-market self-service adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue captive control over inference-optimized silicon to escape foundry margin compression and secure supply certainty.
For Market Incumbents: Anchor competitive position through backward integration into edge deployment hardware and MLOps talent acquisition in Bangalore and Berlin. Defend against open-source inference engine substitution by embedding governance-layer software into existing cloud commitments. Prioritize certification investment for EU AI Act conformity assessment to maintain Frankfurt and Amsterdam financial services access. For New Entrants and Emerging Players: API-first distribution routes offer lowest customer acquisition friction for mid-market healthcare providers in India seeking radiology analytics without proprietary silicon dependencies. Target underpenetrated operational technology convergence in Indian steel and cement production, where real-time quality optimization lacks incumbent presence. Pursue natural language-to-SQL convergence as primary go-to-market angle for United States mid-market financial services self-service deployments. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of vertical-specialist governance vendors with established FDA and EMA regulatory affairs capabilities. Long-term viability favors platforms with unified compliance architecture spanning dual-track validation requirements. Monitor RBI algorithmic trading surveillance implementation and CSRD sustainability reporting mandate enforcement as inflection indicators for compliance-layer software demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding analytics within Microsoft Azure and Google Cloud productivity suites captures enterprise distribution. |
| Regulatory Certification Investment | EU AI Act conformity assessment documentation gates vendor onboarding for Frankfurt financial institutions. |
| Edge Deployment Partnership | Operational technology integration expertise opens German automotive predictive maintenance contracts. |
| Natural Language-to-SQL Convergence | Large language model integration bypasses data science bottlenecks in United States mid-market financial services. |
| Acquisition of Governance Specialist | Watson-powered compliance capabilities differentiate procurement evaluations in healthcare and financial services. |
Methodological Framework
Multi-period observation of hyperscaler capex disclosures, FDA 510(k) submission volumes, and EU AI Act implementation timelines anchored the trend analysis, supplemented by interviews with CTOs at United States hospital systems, regulatory affairs leads at Frankfurt-based insurers, and platform engineers at Bangalore IT services firms. Secondary validation drew from SEC filings, EMA submission databases, and cloud infrastructure spending reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrix modeling connected deployment architecture choices to solution capability premiums across cloud-native, SaaS, hybrid, and on-premises configurations. Segmentation dimensions included end-user vertical, application complexity tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating MLOps talent availability and legacy data warehouse integration friction. Forecast inputs incorporated GPU supply concentration indices and EU AI Act risk-classification implementation schedules.
The model holds under stable foundry capacity allocation and progressive EU AI Act enforcement; deviation in Taiwan semiconductor export restrictions or accelerated FDA clinical decision support reclassification would shift deployment architecture preferences. Forecasts reflect documented assumptions regarding open-source inference engine maturation and hyperscaler pricing discipline. A small set of named triggers—RBI algorithmic trading surveillance finalization, CSRD Scope 3 reporting technical standards, and FDA software-as-medical-device guidance—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
South Korea Contact Center Analytics Market
Analytics
Europe Crowd Analytics Market
Analytics
US Predictive Analytics Market
Analytics
Data Mining Tools Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Network Traffic Analytics Market
Analytics
Face Analytics Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Israel Geospatial Analytics Market
Analytics
North America Mobile Analytics Market
Analytics
Data Discovery Market
Analytics
Business Value Dashboard Market
Analytics
Global Clickstream Analytics Market
Analytics
Spain Geospatial Analytics Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
UAE Geospatial Analytics Market