
 Australia Beauty and Personal Care Products Market | 2026-2036
Australia Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Beauty and Personal Care Products Market Analysis
Australian contract manufacturing capacity for beauty formulations is hardening as local producers expand clean-beauty batch capabilities to serve Asia-Pacific export demand. L'Oréal S.A. leverages its Melbourne-based R&D hub to test botanical actives suited to UV-stressed skin profiles. Unilever PLC sustains broad retail penetration through supermarket and pharmacy networks that dominate mass-market distribution. McPherson's Limited anchors its competitive stance in specialty retail and pharmacy channels with heritage brands tailored to Australian ingredient preferences.
Beauty and personal care products encompass topical formulations designed for skin integrity, hair maintenance, color enhancement, and olfactory expression, typically incorporating emulsifiers, preservatives, active ingredients, and fragrance compounds manufactured through cold-process or hot-process batch methods. The primary commercial purpose centers on consumer hygiene, aesthetic improvement, and dermatological protection across daily and professional use contexts. Skin care commands the largest margin pool as Australian consumers prioritize SPF-integrated and barrier-repair formulations suited to high-UV climates. Online retail represents the fastest-growing distribution channel, though pharmacies retain structural importance for clinical-grade and TGA-registered therapeutic claims.
TGA oversees therapeutic claims and ingredient safety for cosmeceutical products crossing into medical-adjacent positioning, while the ACCC enforces consumer protection against misleading sustainability and efficacy marketing. These frameworks elevate compliance costs for entrants but reinforce quality differentiation for established players with dedicated regulatory affairs functions. Stakeholders must monitor evolving mandatory ingredient transparency requirements and the potential extension of microplastic bans to rinse-off cosmetic formulations.
Market Dynamics
TGA ingredient disclosure mandates and ACCC greenwashing enforcement are compressing formulation timelines while forcing brands to rebuild supply chain traceability from raw material to shelf. This regulatory tightening favors domestic contract manufacturers with dedicated compliance functions.
Growth Catalysts
- UV-adapted skin science:Australian consumers prioritize SPF-integrated and barrier-repair formulations suited to high-UV climates, expanding the addressable market for clinical-grade skin care.
- Male grooming diversification:Australian men are expanding beyond basic hygiene into specialized skin care and grooming routines, creating new SKU opportunities across retail channels.
- Asia-Pacific export demand:Local contract manufacturers are scaling clean-beauty batch capabilities to serve regional export markets, hardening domestic production capacity.
Market Restraints
- Regulatory compliance costs:TGA therapeutic claims oversight and ACCC sustainability marketing enforcement elevate fixed costs for market entrants without dedicated regulatory affairs teams.
- Ingredient transparency mandates:Mandatory disclosure requirements force reformulation of legacy products, compressing margin structures for mid-tier brands.
- Microplastic regulatory uncertainty:Potential extension of bans to rinse-off cosmetic formulations creates formulation risk for exfoliant and cleansing product lines.
Strategic Opportunities
- Professional spa-grade channel expansion:Premium skin care and spa-grade products command disproportionate shelf space in Sydney and Melbourne, with room for geographic extension.
- Online retail infrastructure:E-commerce represents the fastest-growing distribution channel, enabling direct-to-consumer models that bypass pharmacy and supermarket gatekeepers.
- Botanical active R&D localization:Melbourne-based research hubs can test actives suited to UV-stressed skin profiles, creating IP differentiation for export markets.
Industry Challenges
- Clean-beauty talent scarcity:Formulation chemists with expertise in preservative-free and natural emulsification systems are concentrated among established domestic manufacturers.
- Supply chain reconfiguration:Rebuilding traceability systems to satisfy TGA disclosure mandates requires capital investment in batch documentation and supplier auditing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Beauty and Personal Care Products Market |
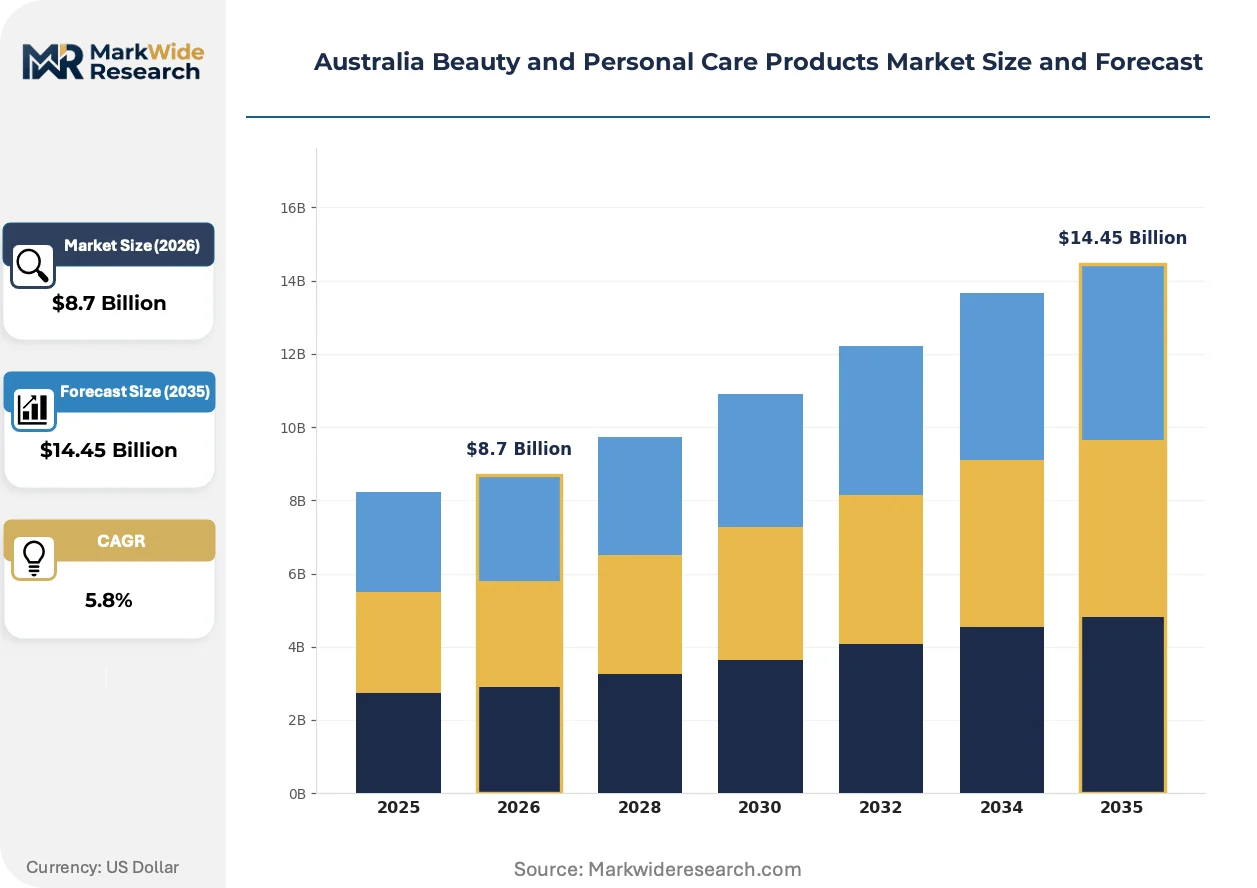
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Makeup, Fragrance End User: Women, Men, Teens, Seniors Application: Daily Use, Special Occasions, Professional Use, Spa Treatments Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | L'Oréal S.A., Unilever PLC, Procter & Gamble Company, Colgate-Palmolive Company, Estée Lauder Inc, Beiersdorf AG, Johnson & Johnson, Henkel AG & Co. KGaA, McPherson's Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Beauty and Personal Care Products Market Emerging Trajectories
Formulation automation and regulatory technology are compressing product development cycles while reshaping how Australian brands compete on transparency and efficacy claims. Three forces are actively restructuring competitive positioning.
AI-driven formulation screening is automating the identification of stable botanical active combinations for UV-stressed skin profiles. Mid-sized domestic manufacturers are adopting these platforms to compress R&D timelines from 18 months to under 8 months. This capability gap is separating technology-enabled contract manufacturers from legacy batch operators dependent on manual stability testing.
TGA's expanding oversight of therapeutic claims is forcing cosmeceutical brands to either register as medical devices or strip clinical language from packaging. The regulatory friction falls hardest on skin care lines positioned at the medical-adjacent boundary, with established players hiring dedicated regulatory affairs functions while smaller entrants retreat to purely cosmetic positioning.
Subscription-based replenishment models are displacing traditional pharmacy repurchase cycles for core skin care routines. Direct-to-consumer brands are capturing Melbourne and Sydney metro consumers through personalized regimen algorithms, while pharmacy chains respond with loyalty programs and in-clinic skin analysis services to defend foot traffic.
Australia Beauty and Personal Care Products Market Segmentation
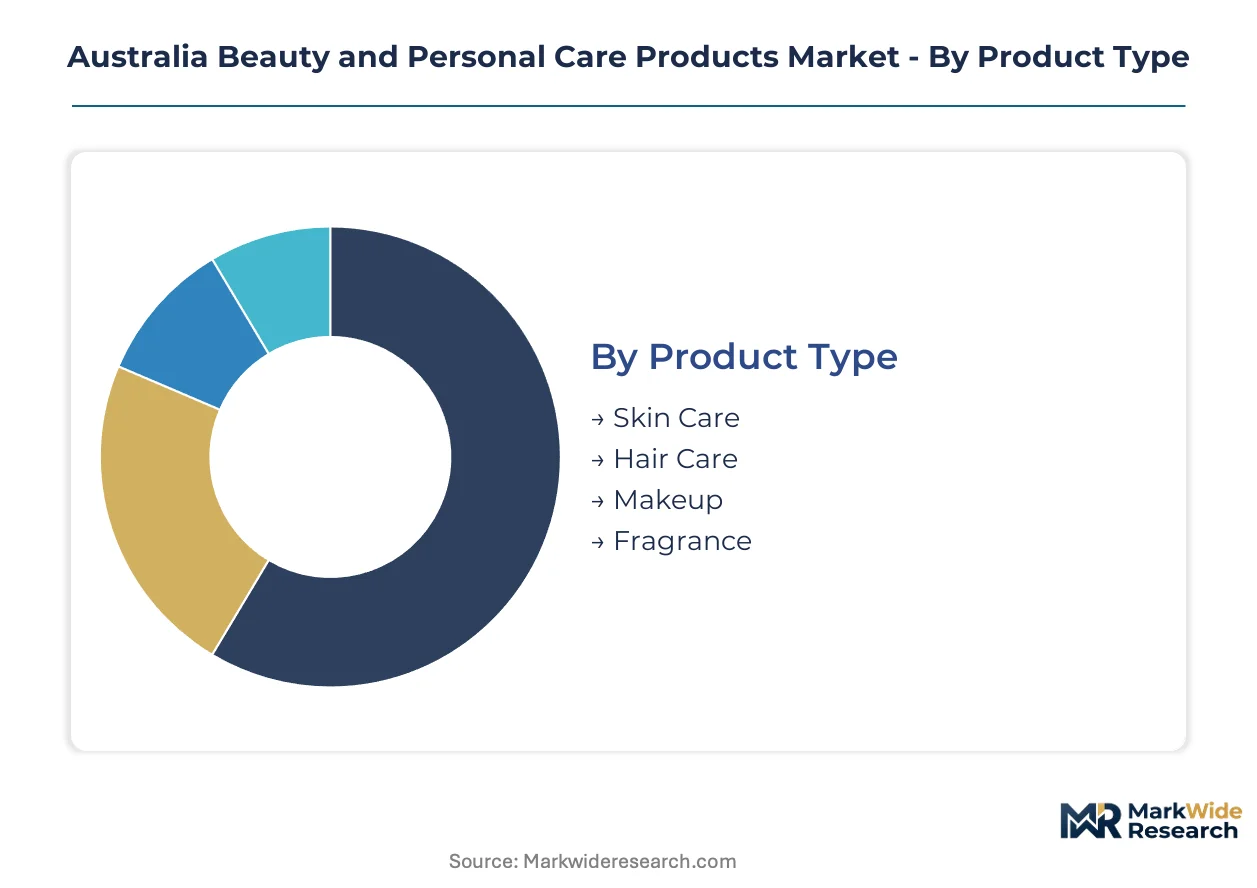
Segmentation in the Australian beauty and personal care market reveals how regulatory frameworks, distribution infrastructure, and UV-specific formulation demands create divergent margin profiles across product categories. Understanding these divisions exposes where TGA compliance costs concentrate and where direct-to-consumer models bypass traditional retail gatekeepers.
Product Type:
Certification burdens vary sharply across product type segments, with SPF-integrated skin care requiring TGA therapeutic claims registration while fragrance formulations face lighter cosmetic-only oversight.
- Skin Care:SPF-integrated and barrier-repair formulations dominate Australian portfolios, with Melbourne and Sydney consumers driving demand for clinical-grade products suited to high-UV climates. TGA registration requirements for sun protection claims elevate compliance costs but lock in pharmacy channel access and premium pricing power.
- Hair Care:Specialized treatments for UV-damaged hair are gaining shelf space in professional salon channels, though mass-market penetration relies heavily on supermarket and pharmacy distribution networks controlled by Unilever PLC and McPherson's Limited.
- Makeup:Long-wear and SPF-infused color cosmetics align with Australian climate conditions.
- Fragrance:Olfactory expression products command loyalty in specialty retail environments.
Skin Care sits at the top of the volume ranking, with SPF-integrated sub-segments climbing the fastest.
End User:
Cost tier stratification separates end user segments, with male grooming commanding premium pricing for specialized formulations while teen-oriented products compete on accessibility and social media discoverability.
- Women:The established core of Australian beauty expenditure, with demand concentrating in professional spa-grade skin care and multi-step regimens distributed through pharmacy and online channels. Sydney and Melbourne metro consumers drive premium tier adoption.
- Men:Australian men are diversifying beyond basic hygiene into specialized skin care and grooming routines, creating new SKU opportunities across retail channels. Male-targeted products command price premiums but require distinct marketing infrastructure.
- Teens:TikTok and Instagram discovery patterns dominate purchase initiation.
- Seniors:Barrier-repair and dermatological formulations align with skin aging concerns.
Women retain the largest share of absolute expenditure, with Men expanding most quickly as grooming routines deepen.
Application:
Application segments map directly to margin structure, with professional and spa treatments capturing value through service integration while daily use products compete on replenishment efficiency and subscription retention.
- Daily Use:Core skin care and hygiene routines dominate replenishment cycles, with subscription-based models displacing traditional pharmacy repurchase patterns in Melbourne and Sydney metro areas. Algorithms personalize regimens to lock in retention.
- Professional Use:Salon and clinic-grade formulations require TGA alignment for therapeutic claims, concentrating supply among domestic contract manufacturers with dedicated compliance functions. Professional channel relationships create switching costs.
- Special Occasions:Event-driven makeup and fragrance purchases concentrate in specialty retail.
- Spa Treatments:Premium skin care commands disproportionate shelf space in Sydney and Melbourne.
Daily Use leads by transaction frequency, with Professional Use gaining share fastest through clinic channel expansion.
Distribution Channel:
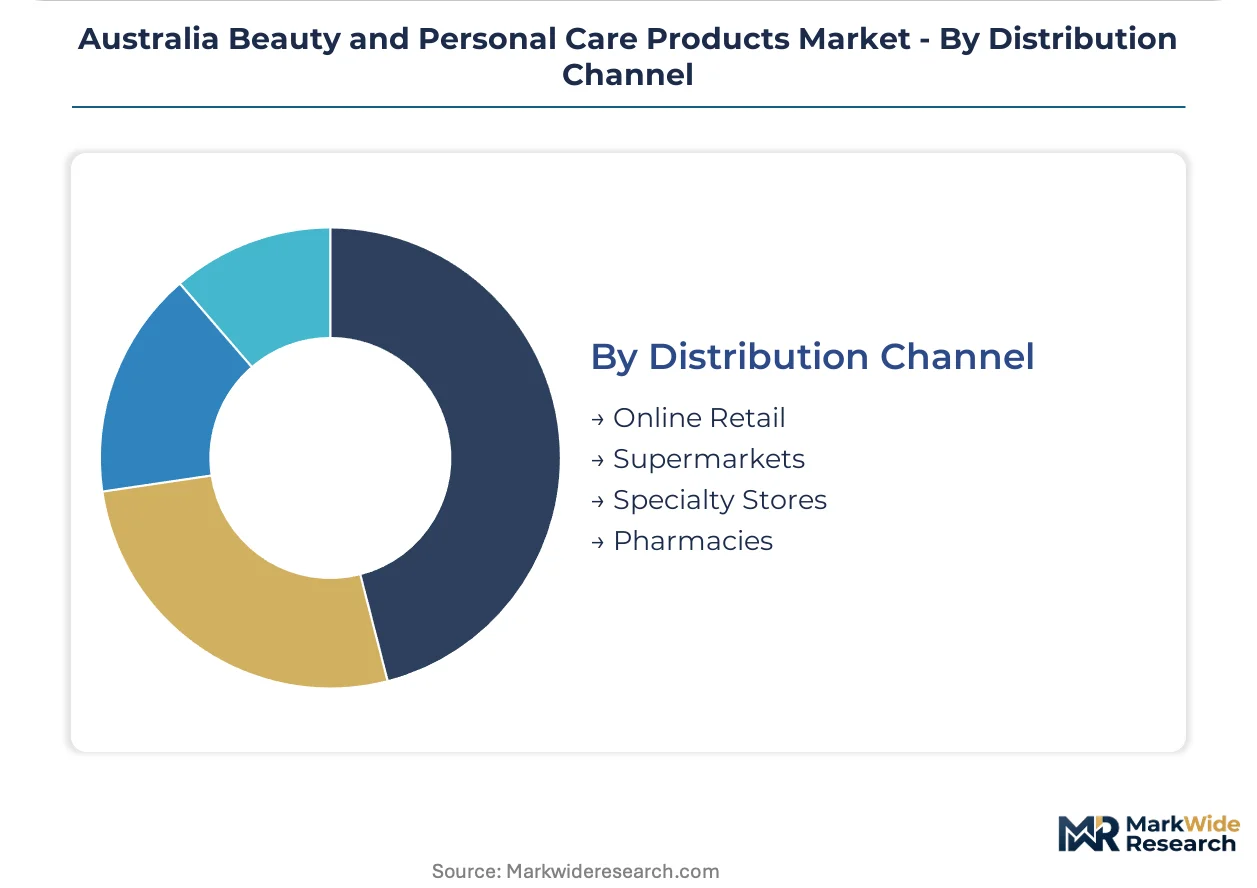
Supply concentration shapes competitive access, with pharmacy and supermarket networks dominated by established FMCG players while online retail enables direct-to-consumer insurgents to bypass traditional gatekeepers.
- Online Retail:The fastest-growing distribution channel enables personalized regimen algorithms and subscription replenishment models. Direct-to-consumer brands capture Melbourne and Sydney consumers while compressing customer acquisition costs through social proof and influencer integration.
- Pharmacies:Structural importance persists for clinical-grade and TGA-registered therapeutic claims, with pharmacy chains defending foot traffic through loyalty programs and in-clinic skin analysis services. Regulatory alignment creates barrier to entry.
- Supermarkets:Mass-market penetration relies on scale economics and shelf space negotiations.
- Specialty Stores:Premium positioning and experiential retail concentrate in urban centers.
Pharmacies anchor the volume ranking, with Online Retail climbing the fastest as subscription models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's beauty and personal care market diverges sharply from Asian export hubs, with domestic consumption concentrated in coastal metropolitan centers rather than manufacturing zones. New South Wales and Victoria generate disproportionate premium demand, while Queensland and Western Australia present distinct regulatory and climatic conditions.
New South Wales
Sydney's affluent eastern suburbs drive demand for professional spa-grade skin care and TGA-registered therapeutic formulations. The state's environmental protection authority enforces stringent chemical disclosure requirements for cosmetic manufacturers operating within its jurisdiction. North Sydney hosts several contract manufacturing facilities specializing in SPF-integrated batch production for Asia-Pacific export.
Victoria
Melbourne's inner-city consumers anchor subscription-based replenishment models for clinical-grade skin care regimens. The Victorian government supports advanced manufacturing grants for clean-beauty formulation facilities seeking to scale preservative-free emulsification capabilities. The city's southeastern industrial corridor concentrates domestic R&D hubs testing botanical actives for UV-stressed skin profiles.
Queensland
Brisbane and Gold Coast consumers prioritize barrier-repair formulations suited to tropical humidity and extreme ultraviolet exposure. Queensland's workplace health and safety regulator monitors cosmetic manufacturing facilities for compliance with chemical handling standards. The state's southeast corner attracts niche brands targeting outdoor-active demographics with sweat-resistant SPF products.
Western Australia
Perth's isolated market sustains premium pricing for imported specialty products with limited local manufacturing presence. The state's environmental protection legislation constrains water-intensive cosmetic production processes in drought-prone regions. Fremantle's port infrastructure supports direct-to-consumer import channels bypassing eastern distribution networks.
South Australia
Adelaide's manufacturing sector hosts mid-tier contract producers serving domestic pharmacy and supermarket supply chains. The South Australian government offers tax incentives for cosmetic exporters targeting Asian markets through Adelaide's air freight facilities. The city's northern suburbs concentrate batch production facilities specializing in hair care and basic hygiene formulations.
Australia Beauty and Personal Care Products Market Vendor Landscape
European multinationals anchor the premium therapeutic tier; Australian specialists hold pharmacy and specialty retail channels. Market structure consolidates around three strategic layers: global FMCG conglomerates with supermarket dominance, regional cosmeceutical players with TGA registration capabilities, and domestic contract manufacturers scaling clean-beauty exports. Competitive moves center on regulatory compliance infrastructure investment and direct-to-consumer channel bypass of traditional retail gatekeepers.
Within the multinational conglomerate tier, L'Oréal S.A., Unilever PLC, and McPherson's Limited exemplify divergent strategic positioning. L'Oréal S.A. occupies a research-intensive position leveraging Melbourne-based botanical active testing for Asia-Pacific product development. Unilever PLC represents mass-market scale economics through supermarket and pharmacy network penetration. McPherson's Limited anchors a heritage-focused specialty retail presence with formulations tailored to Australian ingredient preferences and regulatory frameworks.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever PLC |
| Procter & Gamble Company |
| Colgate-Palmolive Company |
| Estée Lauder Inc |
| Beiersdorf AG |
| Johnson & Johnson |
| Henkel AG & Co. KGaA |
| McPherson's Limited |
| Others |
Supply Flow & Price Mechanics
Botanical active ingredient price indices, particularly for Kakadu plum and tea tree oil extracts, cascade through Australian contract manufacturing tiers into three distinct pricing levels: premium TGA-registered therapeutic formulations, standard cosmetic-grade SKUs, and economy private-label alternatives. TGA disclosure mandates amplify documentation costs that concentrate in mid-tier brands lacking dedicated compliance infrastructure.
Pricing Analysis
Distributor margin layers separate pharmacy-controlled therapeutic claims from direct-to-consumer subscription models. Three-tier pricing structure across premium spa-grade, standard pharmacy, and economy supermarket levels reflects certification grade and channel access. Cost compression in mid-tier cosmetic positioning intensifies because TGA reformulation requirements drain R&D budgets. Price sensitivity concentrates among teen-oriented TikTok-discovered brands, while professional clinic channels demonstrate inelastic demand for TGA-registered barrier-repair formulations.
Supply Chain Analysis
Dual-sourcing requirements for preservative-free emulsification systems compel domestic manufacturers to qualify both Australian and New Zealand botanical suppliers. Raw material dependencies center on native Australian actives, imported fragrance compounds, and Asian-packaging substrates. Single-source vulnerability concentrates in Melbourne-based R&D hubs testing UV-stressed skin profiles. Distribution runs through pharmacy networks for therapeutic claims, with online retail bypassing traditional gatekeepers for subscription replenishment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TGA ingredient disclosure mandates function as a regulatory compounder, accelerating consolidation around domestic contract manufacturers with dedicated compliance functions. The ACCC's greenwashing enforcement timeline drives demand for verified supply chain traceability infrastructure.
For Market Incumbents: Anticipate margin compression from direct-to-consumer subscription algorithms by securing exclusive pharmacy clinic partnerships for skin analysis services. Prioritize backward integration into native Australian botanical cultivation to lock in Kakadu plum and finger lime extract supply. TGA registration capabilities remain the critical defensive moat against private-label encroachment.
For New Entrants and Emerging Players: Regional Queensland men represent an underserved buyer archetype with minimal specialized grooming penetration beyond basic hygiene. White-space targets include sweat-resistant SPF formulations for outdoor-active demographics and preservative-free emulsification systems for sensitive-skin segments. Go-to-market execution favors TikTok-native discovery patterns paired with subscription replenishment algorithms bypassing pharmacy gatekeepers.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic contract manufacturers scaling clean-beauty batch capabilities for Asia-Pacific export demand. Long-term viability over a multi-year horizon hinges on TGA compliance infrastructure and Melbourne-based R&D localization. Monitor ACCC enforcement intensity as the inflection indicator for marketing cost structures industry-wide.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Launch | Bypasses pharmacy and supermarket gatekeepers through subscription algorithms personalized to UV-stressed skin profiles. |
| Backward Integration into Botanical Supply | Secures native Australian active ingredients against Kakadu plum extract price volatility and TGA traceability mandates. |
| TGA Registration Investment | Locks in therapeutic claims positioning and pharmacy channel access for clinical-grade barrier-repair formulations. |
| Clean-Beauty Manufacturing Scale-Up | Expands preservative-free emulsification capacity to serve Asia-Pacific export demand from Melbourne production hubs. |
| Sustainability Repositioning | Preempts ACCC greenwashing enforcement through verified supply chain documentation and microplastic-free formulation transitions. |
Methodological Framework
Coverage spans New South Wales, Victoria, Queensland, and Western Australia, with primary inputs from each state informing segment-level demand calibration. The approach combines primary interviews with brand managers, category buyers at pharmacy chains, formulation chemists at contract manufacturers, and regulatory affairs specialists with secondary validation through TGA registration databases, ACCC enforcement records, Nielsen retail audit data, and customs import documentation. Bottom-up SKU-level modeling triangulates against top-down category expenditure estimates.
Granularity-level framing applies product type, end user, application, and distribution channel dimensions at the state level, with UV-adapted formulation intensity as an industry-specific overlay. CAGRs derive from regression analysis against dermatological consultation rates, male grooming SKU proliferation indices, and e-commerce penetration trajectories across the projection horizon. Forecast inputs incorporate TGA disclosure mandate implementation timelines and ACCC enforcement case volumes.
Underlying measurement precision varies by segment; TGA-registered therapeutic skin care carries tighter precision than fragrance and color cosmetics due to registration documentation density. Forecasts reflect documented assumptions regarding regulatory implementation pace and consumer subscription retention rates. Deviation in ACCC greenwashing penalty severity or microplastic ban extension timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Beard Oil Market
Beauty & Personal Care
Global Organic Personal Care and Cosmetic Products Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Middle East and Africa Beauty and Personal Care Products Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Switzerland Haircare Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Cosmetology Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Europe Sustainable Personal Care Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market