
 North America Jeans Market | 2026-2036
North America Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
North America Jeans Market Analytics
California's SB 657 supply-chain transparency mandate is restructuring how denim brands manage vendor relationships and consumer communication. Levi Strauss & Co. leverages its heritage archive and repair services to sustain premium positioning across direct-to-consumer channels. VF Corporation anchors volume through Kontoor Brands' Wrangler and Lee labels, which dominate mass-market shelf space in rural and suburban retail corridors. Gap Inc. competes on price-accessibility while extending its circular denim resale platform to capture younger demographics.
North America jeans comprise woven cotton denim garments, typically twill-constructed with warp-faced indigo dyeing and riveted stress points, designed for durable casual wear across consumer and work applications. Skinny and straight fits remain volume leaders in women's and men's categories respectively, though relaxed silhouettes are gaining floor space as comfort preferences shift. Online retail channels capture the fastest-growing transaction volume, while specialty stores retain margin concentration through curated premium and selvedge assortments that command higher price points.
The Federal Trade Commission enforces textile labeling standards that govern fiber content claims, while OSHA workplace safety rules affect domestic finishing and washing operations. EPA discharge regulations constrain wet-processing facilities, pushing brands toward laser-finishing and ozone-wash technologies. Stakeholders must monitor how state-level extended producer responsibility frameworks evolve, as California and New York legislative momentum could impose material recovery obligations that reshape cost structures and supplier selection criteria across the value chain.
Market Dynamics
California's SB 657 transparency mandate is forcing denim brands to restructure vendor relationships and disclose labor practices, while laser-finishing and ozone-wash technologies compress wet-processing footprints. These pressures are redrawing competitive advantage around traceability infrastructure and capital-light finishing capabilities.
Growth Catalysts
- Extended Producer Responsibility frameworks:California and New York legislative momentum toward material recovery obligations is creating first-mover advantages for brands with circular infrastructure. Brands investing in resale platforms and fiber-to-fiber recycling capture regulatory goodwill and younger demographics simultaneously.
- Teen and young adult demand concentration:United States and Canadian metropolitan areas show sustained appetite for premium selvedge and raw denim, with direct-to-consumer channels capturing transaction volume growth faster than wholesale.
- Laser-finishing technology:EPA discharge constraints on wet-processing facilities are accelerating adoption of waterless finishing methods that reduce chemical discharge and energy consumption while enabling customization at scale.
Market Restraints
- Cotton price volatility:Input cost swings from weather-driven supply shocks and speculative trading compress margin predictability for mid-tier labels dependent on commodity denim.
- Supply concentration in Asian finishing:Wet-processing capacity clusters in specific geographies create vulnerability to shipping disruptions, tariff fluctuations, and labor unrest that cascade through lead times.
- Technical limitations of mechanical stretch:Traditional rigid denim construction limits comfort performance against athleisure substitutes, constraining share in work-from-home and hybrid office environments.
Strategic Opportunities
- Underpenetrated Canadian premium segment:Toronto and Vancouver metropolitan areas show selvedge denim penetration gaps versus New York and Los Angeles, creating whitespace for heritage positioning and repair-service differentiation.
- Regulatory tailwind from FTC Green Guides:Updated textile marketing standards create enforcement leverage against greenwashing competitors, rewarding brands with verified lifecycle data and third-party certifications.
- AI-driven fit prediction:Machine learning convergence with 3D body scanning is reducing return rates in direct-to-consumer channels, enabling inventory efficiency gains that subsidize free shipping and extended sizing.
Industry Challenges
- Denim finishing technician shortage:Specialized skills in laser programming and ozone system calibration are scarce in domestic labor markets, constraining capacity expansion and technology diffusion.
- SB 657 compliance timeline compression:Vendor auditing and documentation requirements demand capital deployment in traceability software and third-party verification before penalty structures activate.
- Legacy ERP integration friction:Supply-chain transparency mandates require data interoperability between brand systems and tier-two supplier platforms, creating implementation bottlenecks and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Jeans Market |
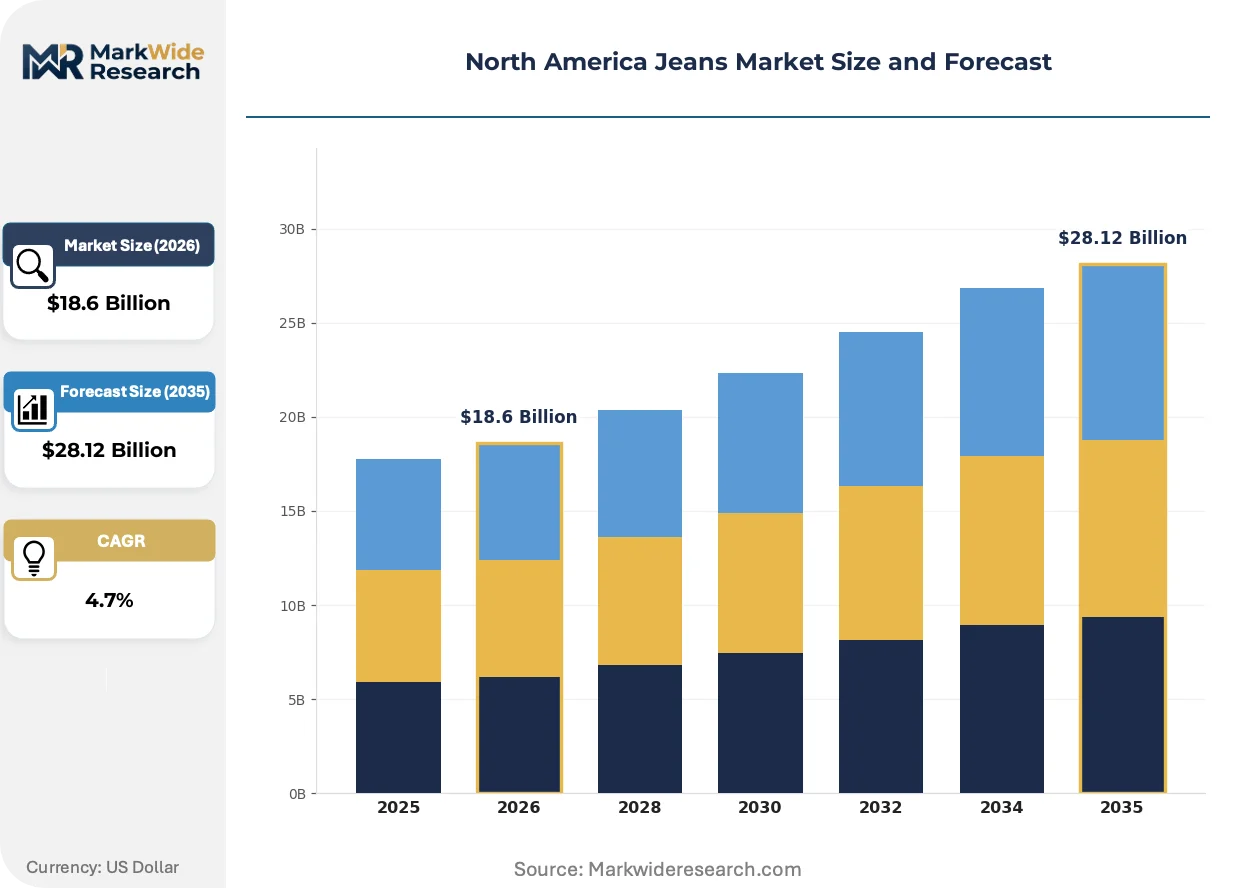
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $28.12 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bootcut, Skinny, Straight, Relaxed Consumer Demographics: Men, Women, Teens, Children Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale Price Range: Luxury, Mid-range, Budget, Discount |
| Companies Covered | Gap Inc., VF Corporation, Levi Strauss & Co., Ralph Lauren Corporation, Guess, Inc., Kontoor Brands Inc., American Eagle Outfitters Inc., H & M Hennes & Mauritz AB, PVH Corp., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Jeans Market Evolving Landscape
Laser-finishing, regulatory transparency mandates, and circular resale platforms are converging to redefine how denim is produced, marketed, and consumed across North American markets.
Ozone-wash technology is absorbing chemical-intensive stonewashing processes in domestic finishing facilities. Mass-market labels in the United States are adopting ozone systems at accelerating pace to preempt EPA enforcement actions and reduce water treatment costs. This absorption is compressing the competitive position of brands dependent on traditional wet-processing supply chains in Mexico and Central America.
The FTC's updated Green Guides are tightening enforcement against unsubstantiated sustainability claims in textile marketing. Denim brands must now maintain documented evidence for fiber source, labor conditions, and environmental impact assertions or face civil penalties. Premium and heritage segments are most affected, responding by investing in blockchain traceability and third-party certifications that exceed baseline compliance.
Resale platform integration is displacing traditional clearance channels for inventory management. Younger demographics in Canada and the United States are transacting through brand-owned secondary markets and peer-to-peer applications rather than discount retailers. This behavioral shift is most visible in metropolitan coastal markets where sustainability signaling carries higher social currency and authentication services reduce purchase risk.
North America Jeans Market Segmentation
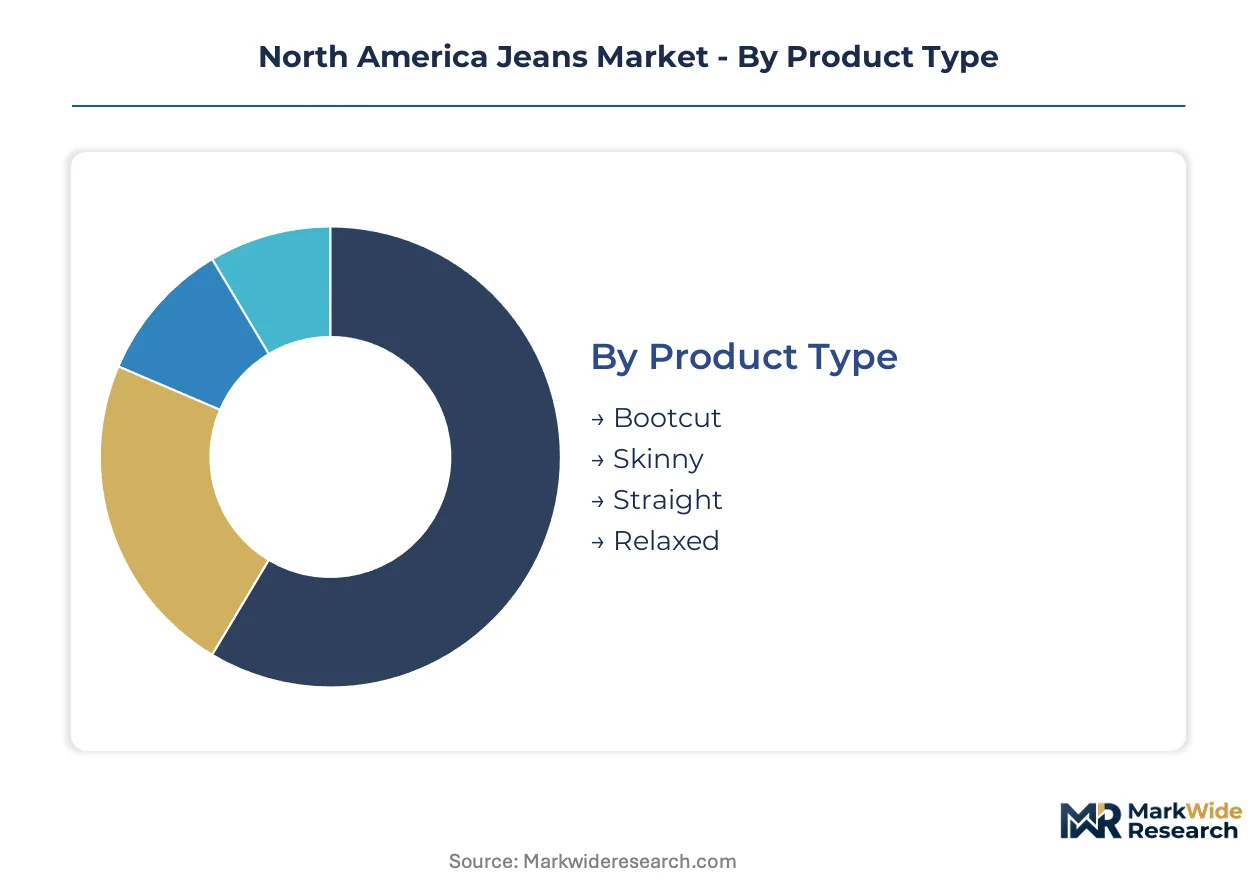
Jeans segmentation in North America reflects divergent purchase motivations across fit preferences, life-stage identity, channel convenience, and price-accessibility trade-offs. Understanding these partitions reveals where margin concentration and volume expansion diverge across the value chain.
Product Type:
Fit preference drives replacement frequency and price elasticity more than fabric innovation or wash treatment.
- Skinny:Tapered leg construction with reduced hem circumference dominates women's volume in United States metropolitan markets. Los Angeles and New York show sustained appetite despite comfort-driven shifts in adjacent categories, though inventory risk intensifies as relaxed alternatives gain floor space.
- Straight:Consistent leg width from thigh to ankle anchors men's core replenishment cycles across Canadian and United States mass retail. This silhouette shows lowest return rates in direct-to-consumer channels and supports standardized sizing that reduces fulfillment complexity.
- Bootcut:Flared hem accommodating western footwear retains regional concentration in Texas, Oklahoma, and Alberta agricultural corridors.
- Relaxed:Generous thigh and seat dimensions are capturing younger male demographics in Toronto and Vancouver as hybrid work norms relax dress codes.
Volume sits with Straight; growth tilts toward Relaxed.
Consumer Demographics:
Life-stage determines occasion breadth and brand loyalty intensity, with distinct replenishment rhythms across gender and age partitions.
- Women:Purchase frequency exceeds men's by substantial margin, driven by fit experimentation across seasonal collections. United States coastal metropolitan areas show highest per-capita expenditure on premium selvedge and raw denim variants.
- Teens:Social media discovery and resale platform engagement concentrate demand for limited drops and vintage authentication. This cohort shows steepest expansion trajectory in direct-to-consumer transaction share.
- Men:Longer replacement cycles and fit consistency preference support subscription and replenishment program adoption.
- Children:Growth-driven obsolescence creates predictable seasonal demand tied to back-to-school retail calendars.
Revenue concentrates with Women; engagement intensity peaks with Teens.
Distribution Channel:
Channel selection determines margin capture versus customer acquisition cost trade-offs, with divergent inventory risk profiles.
- Online Retail:Direct-to-consumer platforms capture transaction volume expansion fastest across United States and Canadian markets. AI-driven fit prediction and extended sizing are compressing return rate differentials versus physical trial.
- Specialty Stores:Curated selvedge and heritage assortments command price premiums through tactile fabric evaluation and repair service attachment. Toronto and Vancouver show penetration gaps versus Los Angeles and New York.
- Department Stores:Mid-range brand consolidation and private-label expansion are compressing dedicated denim floor space in suburban United States locations.
- Wholesale:Mass-market volume anchors through Kontoor Brands' Wrangler and Lee labels dominate rural retail corridors.
Margin concentrates with Specialty Stores; transaction velocity expands fastest through Online Retail.
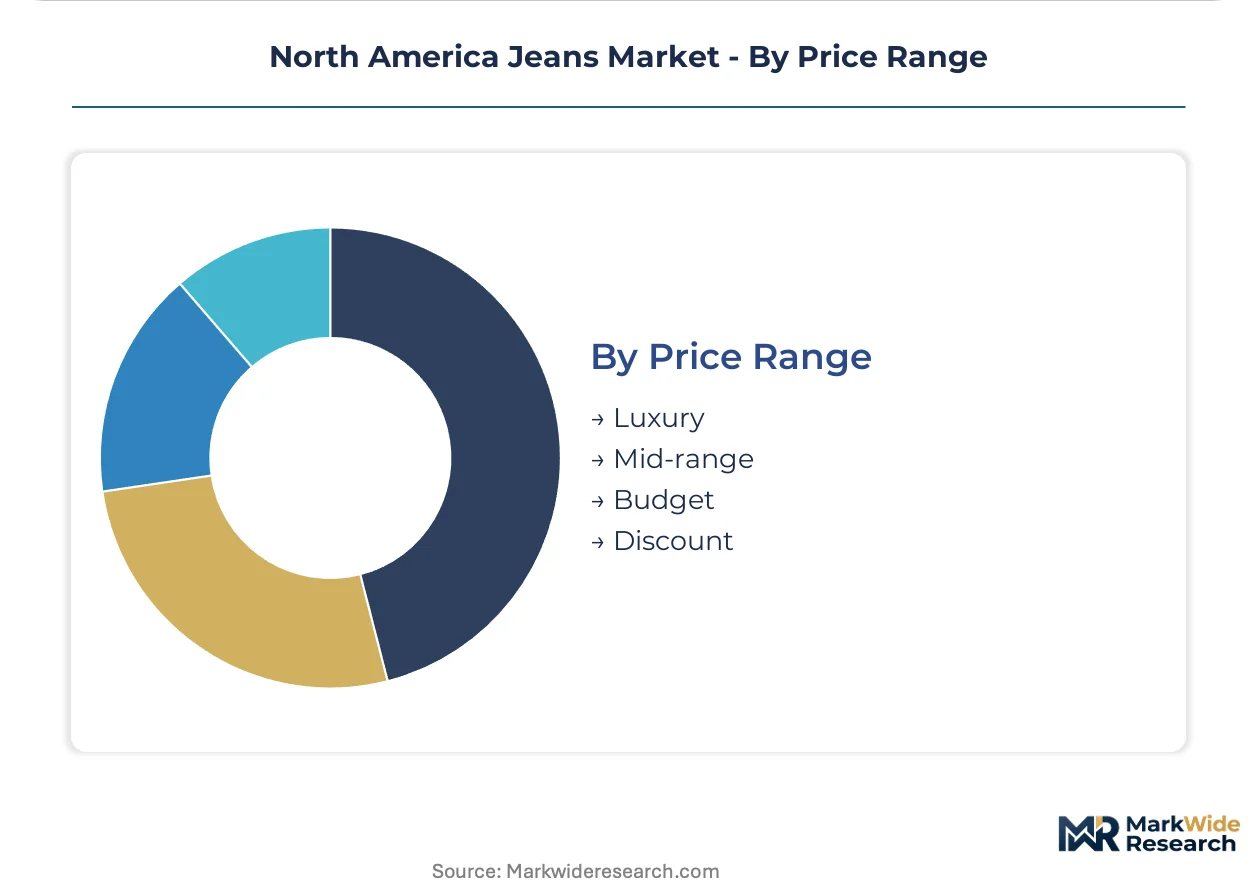
Price Range:
Price tier selection signals quality attribution and sustainability verification expectations that reshape supplier qualification criteria.
- Luxury:Japanese selvedge and Italian denim mills supply construction with documented provenance and repair service inclusion. FTC Green Guides enforcement is elevating documentation requirements for fiber source and labor condition claims.
- Mid-range:Heritage positioning with domestic finishing and transparent supply chains captures regulatory goodwill under California SB 657 mandates.
- Budget:Commodity denim with standardized fits dominates replenishment purchasing in suburban and rural United States markets.
- Discount:Overstock clearance and irregular goods face displacement from brand-owned resale platforms that preserve price integrity.
Profitability peaks with Luxury; volume anchors with Budget.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Mexico and Central America while consumption concentrates in metropolitan United States and Canadian markets. This geographic split creates trade-flow dependencies and regulatory compliance complexity across the value chain.
United States
Teen and young adult consumers in New York, Los Angeles, and Chicago sustain premium selvedge demand through direct-to-consumer channels. California's SB 657 transparency mandate forces brands to restructure vendor relationships and disclose labor practices. Los Angeles retains domestic finishing capacity for laser and ozone-wash technologies serving heritage labels.
Canada
Toronto and Vancouver metropolitan areas show selvedge denim penetration gaps versus United States coastal markets, creating whitespace for premium positioning. Health Canada textile labeling standards align with FTC requirements, reducing cross-border compliance friction. Montreal's apparel manufacturing base supplies private-label programs for mid-tier retailers.
Mexico
Wet-processing facilities in Puebla and Guanajuato serve as finishing hubs for United States-bound denim, though EPA discharge regulations constrain their expansion. Nearshoring incentives under USMCA rules of origin provisions attract cut-and-sew investment. Tlaxcala's industrial corridor concentrates denim washing and distressing operations.
North America Jeans Market Competitive Landscape
The competitive structure tilts toward heritage-led differentiation rather than scale-driven consolidation. Three tiers operate: mass-market volume players anchored through wholesale distribution, premium heritage labels commanding direct-to-consumer margins, and fast-fashion retailers competing on trend velocity. Dominant competitive moves include circular platform deployment for resale revenue capture and laser-finishing technology licensing to reduce water-treatment compliance costs.
Within the heritage-premium tier, Levi Strauss & Co. and Ralph Lauren Corporation exemplify archive-driven positioning and repair-service differentiation. VF Corporation, through its Kontoor Brands subsidiary, occupies the mass-market anchor position. Gap Inc. represents price-accessibility competition with circular platform extension. These three archetypes structure rivalry around brand equity depth versus operational scale versus channel flexibility.
| Leading Market Players |
|---|
| Gap Inc. |
| VF Corporation |
| Levi Strauss & Co. |
| Ralph Lauren Corporation |
| Guess, Inc. |
| Kontoor Brands Inc. |
| American Eagle Outfitters Inc. |
| H & M Hennes & Mauritz AB |
| PVH Corp. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap denim finishing specialists in Guanajuato and Puebla anchor wet-processing capacity, their capital constraints limiting expansion and sustaining pricing discipline for United States-bound heritage labels facing California SB 657 compliance costs.
Pricing Analysis
Margin tightening in mid-range tiers reflects cotton price volatility from weather-driven supply shocks and speculative trading. Three-tier pricing structure across premium, standard, and economy levels segments buyers by provenance documentation and repair service inclusion. Cost compression accelerates in budget tiers as brand-owned resale platforms displace discount channels. Mass-market suburban buyers show highest price sensitivity; luxury consumers purchasing Japanese selvedge demonstrate lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Los Angeles and Dallas orchestrate hub-and-spoke patterns for domestic finishing output. Cut-and-sew capacity concentrates in Mexico, Guatemala, and Nicaragua under USMCA rules of origin provisions. Raw cotton draws from Texas high plains, Arizona, and California's San Joaquin Valley. Single-source vulnerability in Asian laser-equipment componentry threatens technology diffusion timelines. Distribution runs through direct-to-consumer platforms capturing fastest transaction velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser-finishing technician scarcity constrains domestic capacity expansion, propping margin structures for brands with installed ozone-wash infrastructure.
For Market Incumbents: Deepen vertical integration into cotton sourcing and captive finishing capacity to defend against tariff exposure on Mexican wet-processing. Invest in blockchain traceability infrastructure ahead of California SB 657 penalty activation. Acquire specialist laser-programming talent pools before wage inflation accelerates. For New Entrants and Emerging Players: Capture underpenetrated Canadian premium segments in Toronto and Vancouver through heritage positioning and repair-service differentiation. Exploit selvedge denim penetration gaps versus United States coastal markets. Launch direct-to-consumer channels with AI-driven fit prediction to compress return rate differentials. For Investors and Strategic Acquirers: California SB 657 third-party verification contract awards are the leading indicator that traceability infrastructure valuations are resetting upward. Five-to-ten-year viability favors brands with circular platform revenue and fiber-to-fiber recycling partnerships. Target acquisition archetype: domestic finishing specialists with ozone-wash installations and EPA compliance records.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Finishing Technology Licensing | Reduces water-treatment compliance costs for domestic facilities facing EPA discharge constraints. |
| Circular Resale Platform Launch | Captures younger demographics while preserving price integrity against discount channel erosion. |
| Blockchain Traceability Implementation | Exceeds California SB 657 baseline compliance and defends against FTC Green Guides enforcement. |
| Canadian Market Expansion | Addresses selvedge penetration gaps in Toronto and Vancouver metropolitan corridors. |
| AI-Driven Fit Prediction Integration | Compresses return rates in direct-to-consumer channels and subsidizes extended sizing offers. |
Research Methodology
SEC 10-K filings, customs trade records, and EPA enforcement databases formed the secondary backbone, cross-referenced with primary interviews across brand sustainability officers, denim finishing plant managers, and specialty retail buyers. Bottom-up and top-down triangulation validated volume estimates against import manifests and production capacity surveys.
Bottom-up modeling aggregated segment-level demand across fit preference, price tier, and distribution channel, while top-down constraints checked aggregate against macroeconomic consumption indicators. CAGRs derived from historical trajectory analysis and technology diffusion curves for laser-finishing adoption. Segmentation dimensions included product type, consumer demographics, channel structure, and regional regulatory cluster.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cotton price volatility, tariff regime shifts, and EPA enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Global Apparel Market
Apparel & Footwear
Europe Denim Jeans Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Maternity Intimate Wear Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Women's Socks Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Golf Outfit Market