
 Asia-Pacific Sports Apparel Market | 2026-2036
Asia-Pacific Sports Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sports Apparel Market Analytics
Women's professional sports participation is repositioning product development priorities across the Asia-Pacific sports apparel landscape. Nike, Inc. leverages its innovation pipeline to dominate performance wear for female athletes in Japan and Australia. ANTA Sports Products Limited anchors its growth through deep distribution networks in China's inland provinces, while Li-Ning Company Limited differentiates via national team sponsorships that reinforce brand equity in basketball and badminton segments.
Asia-Pacific sports apparel encompasses engineered garments designed for athletic performance, moisture management, and biomechanical support through synthetic fiber blends, seamless knitting, and compression weaving technologies. These products serve competitive athletes, fitness practitioners, and lifestyle consumers seeking functional comfort during physical exertion. Activewear leads volume generation across the region as hybrid work-leisure wardrobes expand, while premium price tiers capture disproportionate margin pools in South Korea and Singapore where brand prestige drives purchasing decisions. The online retail distribution channel is accelerating fastest in India and Southeast Asia, though specialty stores sustain higher conversion rates for technical footwear fittings.
China's SAMR enforces GB textile standards that mandate chemical safety disclosures, while India's BIS certification requirements govern fiber content labeling for domestic sports apparel sales. Australia's ACCC monitors consumer protection claims around performance benefits, creating compliance complexity for brands operating across multiple regulatory jurisdictions. Stakeholders must monitor evolving sustainability mandates and digital commerce regulations as these frameworks increasingly determine market access and product positioning across the region.
Market Dynamics
China's GB textile standards and India's BIS certification requirements are forcing material sourcing restructuring across Asia-Pacific supply chains. Brands must redesign fiber procurement and chemical disclosure protocols to maintain market access in these high-volume jurisdictions.
Growth Catalysts
- Women's professional league expansion:Rising participation rates in cricket, football, and basketball across India and Australia are creating specialized performance wear demand that commands premium positioning.
- GB 18401-2010 textile safety standards:China's mandatory chemical safety disclosures are accelerating certified sustainable material adoption, rewarding early-compliant suppliers with preferential retail partnerships.
- Seamless knitting automation:Advanced circular knitting equipment is compressing production cycles for compression garments, enabling rapid style rotation in Japan's fitness apparel segment.
Market Restraints
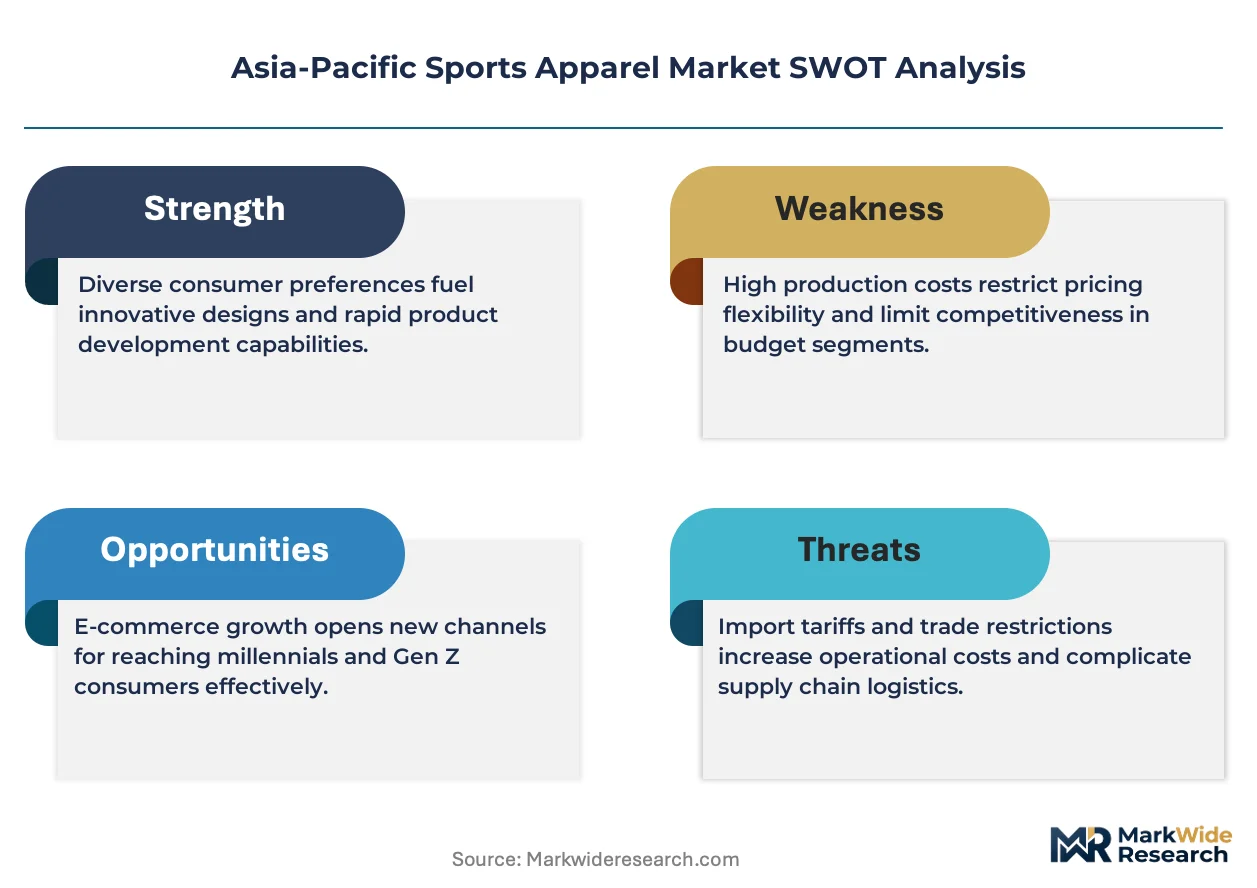
- Petrochemical feedstock volatility:Polyester and spandex input costs fluctuate with crude oil derivatives, squeezing margin predictability for synthetic fiber-dependent manufacturers.
- Concentrated dye chemical supply:Specialty performance dye production clusters in Zhejiang province, creating single-point vulnerability for moisture-wicking fabric coloration.
- Biomechanical measurement standardization gaps:Inconsistent sizing protocols across China, Japan, and India force redundant pattern development, inflating new product introduction costs.
Strategic Opportunities
- Vietnam and Indonesia manufacturing expansion:Rising labor costs in coastal China are redirecting cut-and-sew operations to these lower-cost ASEAN production bases with improving technical capability.
- Direct-to-consumer digital channels:Social commerce integration on platforms like Shopee and Flipkart is bypassing traditional wholesale margins in Southeast Asia and India.
- Dual carbon policy alignment:China's MEE carbon intensity targets are creating first-mover advantage for brands with verified recycled polyester supply chains and renewable energy manufacturing.
Industry Challenges
- Technical textile engineering talent scarcity:Advanced polymer science and compression weaving expertise concentrates in South Korea and Japan, constraining R&D scaling in emerging production bases.
- Multi-jurisdiction certification complexity:Simultaneous compliance with China's SAMR, India's BIS, and Australia's ACCC creates elongated product approval timelines and fragmented testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sports Apparel Market |
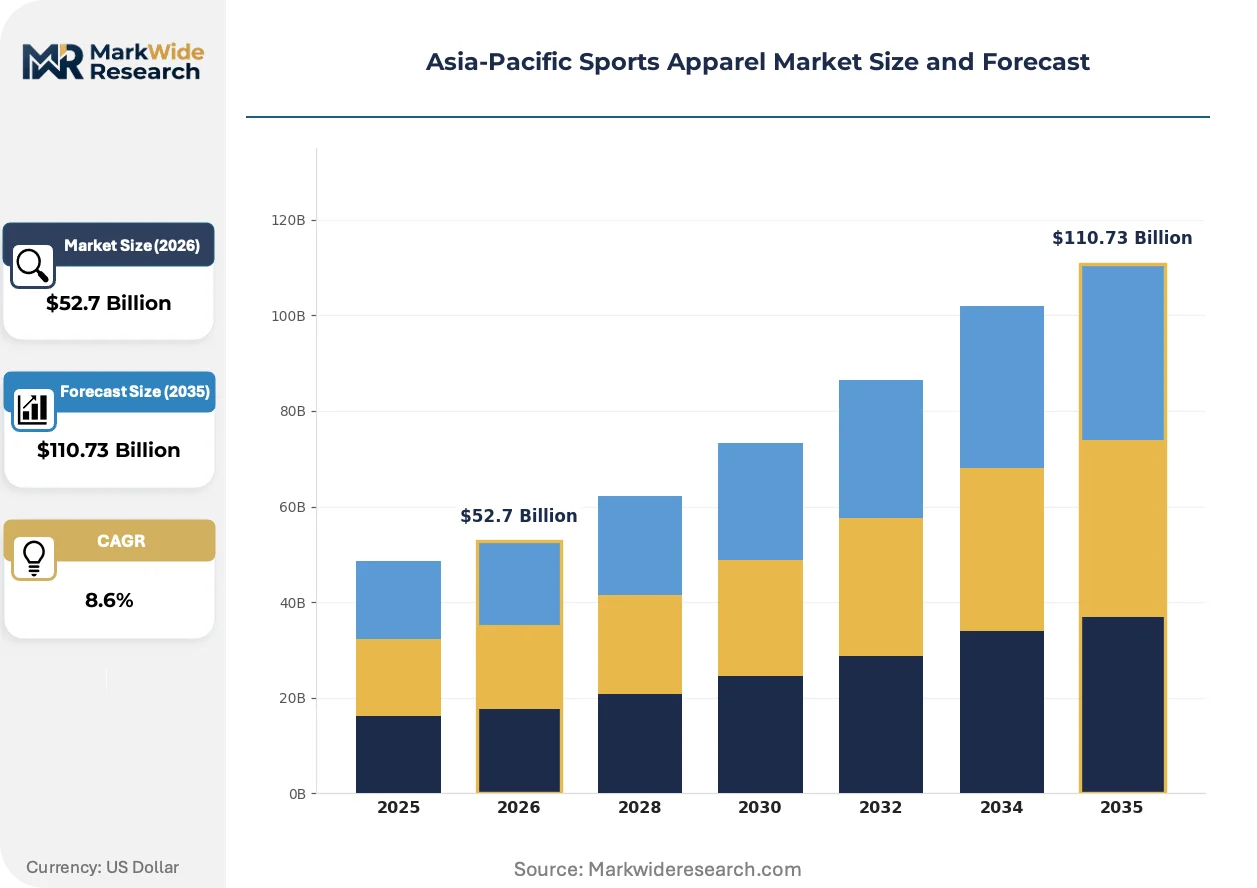
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Activewear, Outerwear, Accessories Customer Type: Fitness Enthusiasts, Casual Users, Professional Athletes, Teams Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Nike, Inc., Adidas AG, PUMA SE, Under Armour, Inc., ASICS Corporation, ANTA Sports Products Limited, Li-Ning Company Limited, FILA Holdings Corporation, Lululemon Athletica, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sports Apparel Market Evolving Landscape
Digital manufacturing and sustainability verification are compressing traditional production and procurement cycles across Asia-Pacific sports apparel. These shifts are redistributing competitive advantage toward vertically capable suppliers with transparent supply chain documentation.
Blockchain-enabled fiber traceability is decentralizing supply chain verification authority away from centralized brand audits. Tier-two and tier-three mills in Bangladesh and Vietnam are adopting distributed ledger systems to prove recycled content claims directly to retailers. This technology compression is reducing reliance on third-party certification bodies and accelerating supplier qualification timelines.
China's MEE is tightening wastewater discharge standards for textile dyeing operations, forcing coastal finishing facilities to install closed-loop water treatment systems. Zhejiang and Guangdong province manufacturers face capital intensity pressure that favors larger integrated producers over fragmented job-shop dyers. The regulatory squeeze is accelerating consolidation in fabric finishing capacity.
Fitness practitioners in South Korea and Singapore are compressing purchase cycles through subscription-based athletic wear rental services. These platforms displace traditional seasonal buying patterns with continuous rotation models that prioritize durability and style versatility over brand loyalty. The behavioral shift is most pronounced among urban professionals aged 25-34 in high-density metropolitan corridors.
Asia-Pacific Sports Apparel Market Segmentation
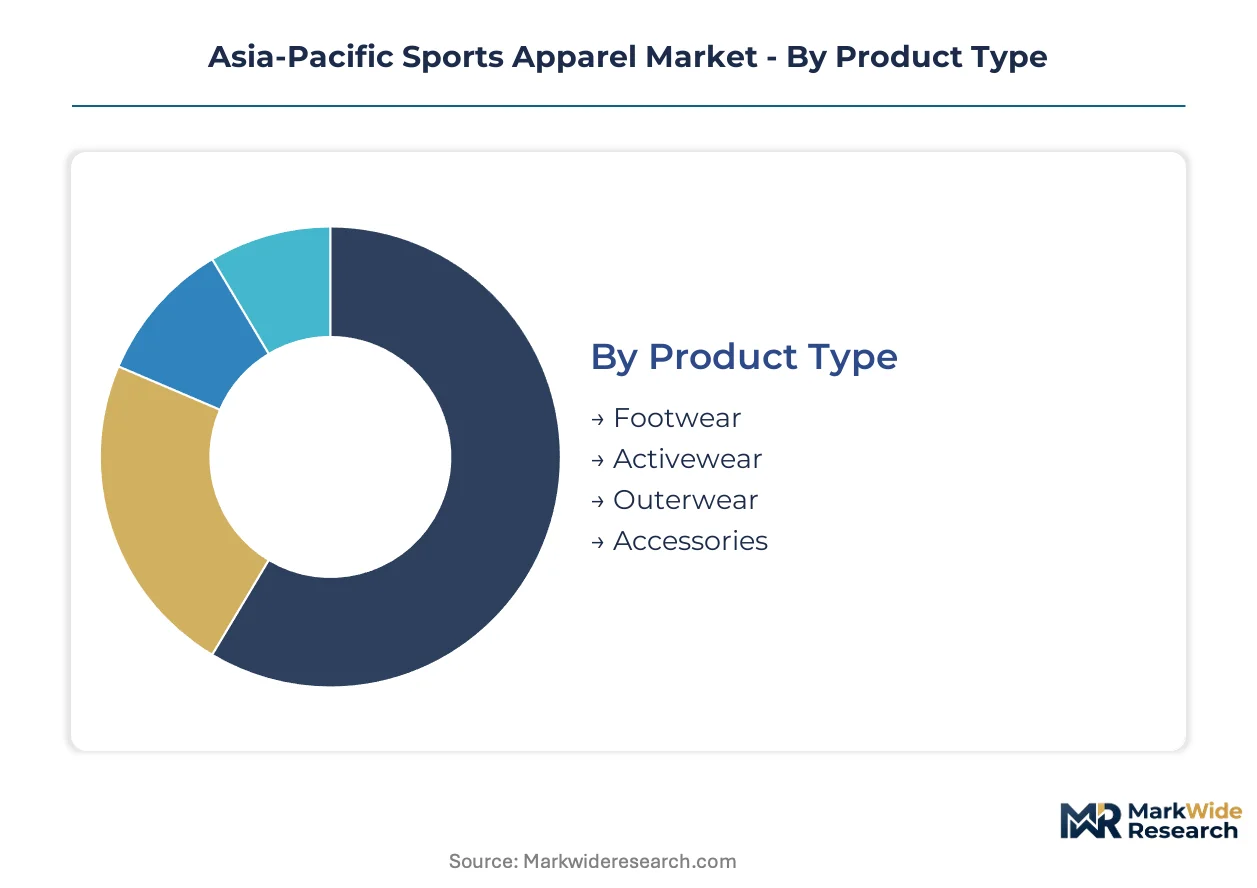
Segmentation in Asia-Pacific sports apparel reveals how technical specifications, purchasing behavior, and channel economics fragment addressable demand. Understanding these axes exposes where margin pools concentrate and which specifications command price premiums across diverse consumer bases.
Product Type:
Engineered performance characteristics and biomechanical design complexity define competitive differentiation across product categories.
- Footwear:Midsole foam compounds, carbon fiber plates, and last geometries optimize energy return and injury prevention. Demand clusters in Japan and Australia's organized running communities where technical fitting protocols drive specialty store traffic and repeat purchase loyalty.
- Activewear:Moisture-wicking polyester-spandex blends with seamless knitting construction dominate volume production. China's tier-one cities and India's metropolitan corridors absorb the highest throughput as hybrid work-leisure wardrobes expand among urban professionals.
- Outerwear:Waterproof-breathable membranes and thermal insulation layers serve climate-variable training conditions.
- Accessories:Compression sleeves, headbands, and equipment bags complete athletic kit configurations with lower engineering barriers.
Mature deployment sits with Activewear. Newer deployment is concentrated in technical Footwear with advanced midsole innovations.
Customer Type:
Purchasing sophistication and performance requirements stratify product positioning and channel economics.
- Professional Athletes:Custom-fitted garments with biometric sensor integration and federation-compliant specifications. Sponsorship contracts in China's basketball leagues and India's cricket franchises anchor volume commitments with embedded performance feedback systems.
- Fitness Enthusiasts:Regular training practitioners seeking durability-to-price optimization and style versatility. South Korea's subscription rental platforms and Singapore's boutique fitness studios concentrate this segment's purchasing power in metropolitan corridors.
- Casual Users:Lifestyle-driven purchasers prioritizing aesthetic and comfort over technical specifications.
- Teams:Bulk procurement through institutional contracts with uniform standardization requirements.
Volume leadership belongs to Fitness Enthusiasts. Steepest expansion trajectory is emerging in Professional Athletes as women's league infrastructure deepens across Australia and India.
Distribution Channel:
Channel selection determines margin capture, inventory risk allocation, and consumer data access.
- Online Retail:Platform-native brands and direct-to-consumer models leveraging social commerce integration. India's Flipkart and Southeast Asia's Shopee accelerate fastest as mobile payment penetration and logistics infrastructure mature in secondary cities.
- Specialty Stores:Staffed fitting expertise and technical product education sustain higher conversion rates for footwear and compression garments. Japan's running specialty chains and Australia's triathlon retailers anchor this channel's regional presence.
- Department Stores:Multi-brand aggregation with seasonal promotional calendars and foot traffic dependence.
- Wholesale:Third-party retail access with margin compression and inventory ownership transfer to distributors.
Established infrastructure concentrates in Specialty Stores. Digital channel investment is expanding most aggressively in Online Retail across India and Southeast Asian markets.
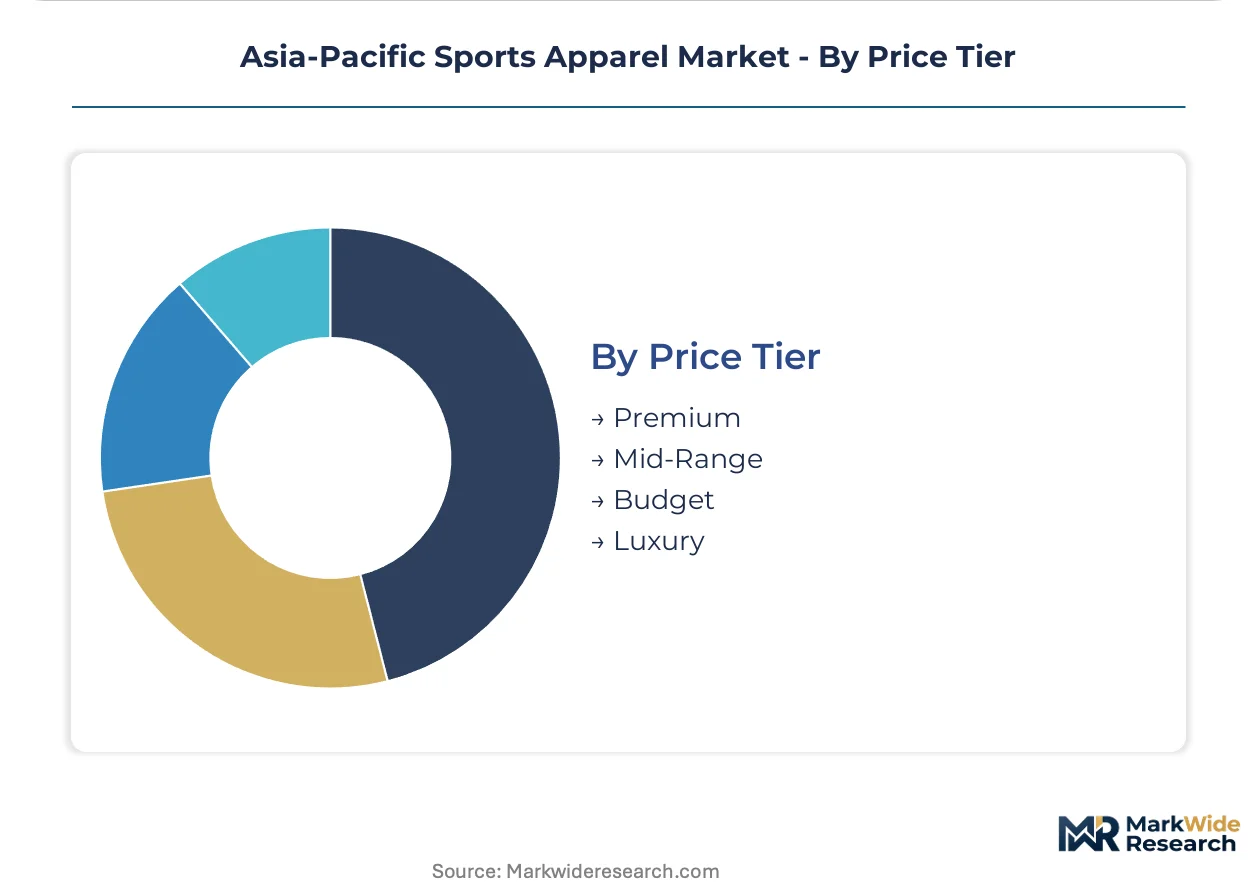
Price Tier:
Material certification, manufacturing origin, and brand equity stratify accessible price positioning.
- Premium:Recycled polyester supply chains, renewable energy manufacturing verification, and limited distribution control. South Korea and Singapore absorb disproportionate share where brand prestige and sustainability credentialing drive purchasing decisions.
- Mid-Range:Balanced performance specifications with mainstream retail availability and seasonal style rotation.
- Budget:Cost-optimized synthetic blends with minimal compliance overhead serving price-sensitive volume markets.
- Luxury:Designer collaborations, exotic material integration, and scarcity-based distribution in flagship metropolitan locations.
Margin concentration aligns with Premium tier deployment. Fastest volume accumulation is occurring in Mid-Range positioning as mass-market fitness participation broadens across China's inland provinces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and India's Special Economic Zones in Tamil Nadu and Gujarat are concentrating textile manufacturing investment through tax holidays and duty exemptions on imported production equipment. These zones anchor regional capacity expansion for performance wear destined for domestic consumption and re-export.
China
Tier-one cities Beijing, Shanghai, and Shenzhen absorb premium activewear volumes as hybrid work patterns normalize fitness-integrated lifestyles. SAMR enforces GB 18401-2010 textile safety standards that mandate chemical disclosure and restrict formaldehyde content in skin-contact garments. The Yangtze River Delta cluster around Suzhou and Hangzhou houses automated seamless knitting facilities serving both domestic brands and export orders.
India
Women's cricket league expansion and metropolitan marathon culture in Mumbai and Bengaluru are creating specialized performance wear demand. BIS certification requirements govern fiber content accuracy and care labeling for all domestic sports apparel sales. Tiruppur in Tamil Nadu and Ludhiana in Punjab concentrate knitwear and synthetic fabric finishing capacity for both branded and private-label production.
Japan
Organized running communities and corporate wellness programs sustain technical footwear and compression garment demand in Tokyo and Osaka metropolitan corridors. METI promotes JIS standards for functional textile performance claims, including moisture management and UV protection verification. The Chubu region around Nagoya hosts advanced polymer science research facilities supplying midsole foam compounds to regional footwear manufacturers.
South Korea
Subscription-based athletic wear rental platforms and boutique fitness studio culture concentrate purchasing power in Seoul's Gangnam and Jongno districts. MFDS regulates skin-contact textile biocompatibility for performance garments marketed with therapeutic claims. The Gyeonggi-do province surrounding Seoul houses domestic brand headquarters and limited cut-and-sew operations increasingly focused on design and marketing functions.
Australia
Triathlon participation growth and women's professional football league expansion drive technical outerwear and team kit procurement. ACCC monitors consumer protection compliance around performance benefit claims in marketing materials. Melbourne and Sydney anchor specialty retail chains with staffed fitting expertise for technical footwear and biomechanical support garments.
Asia-Pacific Sports Apparel Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium performance wear consolidating around innovation-intensive labels while mass-market activewear fragments across private-label and regional brand competition. Three archetypes dominate: multinational sportswear conglomerates with integrated R&D pipelines, domestic champions leveraging distribution depth in home markets, and platform-native direct-to-consumer entrants. Competitive moves concentrate on M&A to acquire technical textile capabilities and strategic partnerships with national sports federations for team sponsorship rights.
Within the multinational tier, Nike, Inc. and Adidas AG occupy positions defined by innovation pipeline scale and athlete endorsement portfolios spanning multiple Asia-Pacific markets. Among domestic champions, ANTA Sports Products Limited and Li-Ning Company Limited exemplify archetypes built on distribution network density and national team sponsorship equity in basketball and badminton segments. These company groupings anchor the competitive structure without exhausting the addressable player set.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| PUMA SE |
| Under Armour, Inc. |
| ASICS Corporation |
| ANTA Sports Products Limited |
| Li-Ning Company Limited |
| FILA Holdings Corporation |
| Lululemon Athletica, Inc. |
| Others |
Value Network & Pricing Analysis
Seamless knitting automation across the Yangtze River Delta is compressing production cycles while concentrating capital requirements among larger integrated mills, simultaneously lowering unit costs for compression garments and reducing supplier fragmentation. This technological shift rewards early adopters with pricing power in Japan's fitness segment while marginalizing smaller job-shop operators unable to fund equipment upgrades.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard production schedules in Australia's triathlon retail channels, while spot inventory from overproduction cycles trades at distressed levels through Southeast Asian digital platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and renewable energy manufacturing verification, with China's dual carbon policy compliance emerging as the primary price differentiation driver. Cost compression in mid-range activewear intensifies because polyester-spandex feedstock volatility squeezes margin predictability for synthetic fiber-dependent manufacturers. Casual users in India's secondary cities exhibit highest price sensitivity, while professional athletes and corporate wellness programs in Singapore absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang province's specialty performance dye production clusters, where concentrated chemical supply creates chokepoint exposure for moisture-wicking fabric coloration across the entire region. Manufacturing gravity draws from China's coastal provinces, Vietnam's northern industrial zones, and Bangladesh's export processing areas for cut-and-sew operations, while midsole foam compounds and seamless knitting equipment rest on South Korean and Japanese technical textile engineering. Tariff exposure threatens re-export economics as regional trade agreement utilization rates vary across ASEAN production bases. Distribution runs through direct-to-consumer digital channels accelerating fastest in India and Southeast Asia, though specialty stores sustain higher conversion rates for technical footwear fittings in Japan and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific sports apparel is consolidating around compliance-capable integrated producers as China's GB textile standards and India's BIS certification requirements force material sourcing restructuring that eliminates margin-thin operators unable to fund multi-jurisdiction testing expenditure.
For Market Incumbents: Anticipate regulatory squeeze by securing early-compliant supplier partnerships with preferential retail access under China's SAMR enforcement timeline, while deploying backward integration into recycled polyester supply chains to defend margin position against feedstock volatility. Prioritize R&D scaling in compression weaving and biometric sensor integration to maintain technical differentiation against platform-native entrants. For New Entrants and Emerging Players: Boutique fitness studio partnerships in Seoul and Singapore offer white-space access with lower brand loyalty barriers than established retail channels, while women's professional league infrastructure across Australia and India presents underexploited sponsorship entry points. Penetrate subscription-based rental platforms as the most accessible go-to-market angle, prioritizing durability and style versatility over premium brand equity. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational sportswear conglomerates seeking technical textile capabilities and national federation sponsorship rights. Long-term viability favors vertically integrated mid-cap specialists with verified sustainable supply chains and renewable energy manufacturing credentials across the projection horizon. Watch blockchain-enabled fiber traceability adoption rates as the signal indicating supplier qualification timeline compression and competitive moat formation.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Knitting Automation Deployment | Compresses production cycles for compression garments in Japan's fitness segment while raising capital barriers. |
| Recycled Polyester Supply Chain Verification | Aligns with China's MEE carbon intensity targets to secure preferential retail partnerships in tier-one cities. |
| Direct-to-Consumer Digital Channel Expansion | Bypasses wholesale margins through Shopee and Flipkart integration in Southeast Asia and India. |
| National Team Sponsorship Acquisition | Reinforces brand equity in basketball and badminton segments through Li-Ning's demonstrated model. |
| Blockchain-Enabled Fiber Traceability | Decentralizes verification authority from centralized brand audits to accelerate supplier qualification. |
Research Methodology
Document review covered customs and trade data, SEC filings from listed sportswear conglomerates, and GB standard enforcement notices from China's SAMR, complemented by interviews with brand sourcing directors, textile mill operations managers, and specialty retail buyers across Japan, Australia, and India. Primary fieldwork engaged compression weaving engineers in South Korea, sustainability certification specialists, and digital platform category managers at Flipkart and Shopee. Secondary validation drew from BIS fiber content regulations, Australia's ACCC consumer protection guidance, and METI functional textile performance standards. Bottom-up demand modeling triangulated against top-down market sizing across product type, customer segment, distribution channel, and price tier dimensions.
Cross-referencing historical shipment data against panel input from procurement leads at ANTA Sports and Li-Ning anchored volume projections across the analysis window. Segmentation modeling incorporated product type, customer sophistication tier, channel economics, and geographic price elasticity. CAGRs derived from weighted average of demand driver trajectories and supply-side capacity expansion schedules. Industry-specific forecast inputs included women's professional league formation timelines and seamless knitting equipment installation rates in Zhejiang and Guangdong provinces.
Caveats apply where petrochemical feedstock volatility, regulatory enforcement intensity shifts, or digital commerce platform policy changes could materially shift the outlook. Forecasts reflect assumptions around sustained fitness culture deepening and hybrid work-leisure wardrobe permanence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Swimwear and Beachwear Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Outdoor Sports Apparel Market
Apparel & Footwear
Europe Jeans Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Smart Wardrobe Market
Apparel & Footwear
Press-To-Close Zippers Market
Apparel & Footwear
Yoga Clothing Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Sequins Apparels Market
Apparel & Footwear
Women's Dresses and Skirts Market
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Europe Headwear Market