
 Maternity Intimate Wear Market | 2026-2036
Maternity Intimate Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Maternity Intimate Wear Market Outlook
Direct-to-consumer online channels is narrowing as Seraphine and PinkBlush Maternity redirect marketing spend from wholesale accounts to owned digital platforms. Boob Design leverages its Scandinavian manufacturing base to sustain organic cotton certifications across European markets. Motherhood Maternity anchors its position through extensive retail partnerships with pharmacy chains and hospital gift shops in North America.
Maternity intimate wear encompasses engineered undergarments designed to accommodate thoracic and abdominal dimensional changes during gestation and lactation, typically incorporating stretch recovery fibers with moisture-wicking properties for skin sensitivity management. Nursing bras command the largest revenue pool within product type segments due to repeat purchase cycles spanning prenatal through weaning periods, while bamboo-derived fabrics represent the fastest-expanding material category as thermal regulation and antimicrobial performance gain priority among postpartum mothers. Premium and luxury price tiers concentrate margin pools where technical construction and certified sustainable sourcing justify elevated price points.
Oeko-Tex Standard 100 and REACH compliance in Europe, alongside FDA textile labeling requirements in the United States, elevate barrier costs for new entrants while mandating chemical disclosure that reshapes supplier selection. China's GB standards for textile safety and the EU Green Deal's extended producer responsibility frameworks will tighten material traceability obligations across export-oriented supply chains. Stakeholders must monitor evolving chemical restriction lists and certification costs as determinants of competitive viability.
Market Dynamics
Direct-to-consumer channel migration is compressing wholesale margins while Oeko-Tex Standard 100 certification mandates in Europe and North America reshape supplier selection criteria across the maternity intimate wear value chain.
Growth Catalysts
- REACH and Oeko-Tex compliance frameworks:Chemical disclosure mandates in Europe elevate barrier costs for uncertified competitors, concentrating margin pools among pre-qualified suppliers with established testing protocols.
- Bamboo fiber thermal regulation:Postpartum mothers prioritize antimicrobial performance and moisture management, accelerating material substitution away from conventional cotton-polyester blends.
- Millennial first-time motherhood concentration:Digital-native cohorts in the United States and Germany drive repeat purchase cycles through subscription nursing bra programs and app-integrated sizing tools.
Market Restraints
- Organic cotton input cost volatility:Climate-induced yield fluctuations in India and Turkey compress gross margins for certified sustainable product lines.
- Chinese GB standard textile safety enforcement:Export-oriented manufacturers face dual compliance burdens when serving domestic and international markets simultaneously.
- Synthetic elastane substitution limitations:Spandex recovery properties remain unmatched by bio-based alternatives, constraining full material transitions in stretch-panel construction.
Strategic Opportunities
- Hospital and pharmacy retail channel penetration:Institutional procurement partnerships in Germany and the United States create captive audience access during prenatal care visits.
- EU Green Deal extended producer responsibility:Take-back program mandates reward brands with established circular infrastructure and textile recycling partnerships.
- AI-driven fit prediction convergence:Smartphone body-scanning integration with e-commerce platforms reduces return rates and sizing friction for remote purchasers.
Industry Challenges
- Oeko-Tex Standard 100 certification timeline compression:Testing laboratory backlogs extend product launch windows by four to six months for new entrants.
- Multi-tier supplier traceability integration:Tier-three spinning mill visibility gaps complicate organic fiber chain-of-custody documentation for audit readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternity Intimate Wear Market |
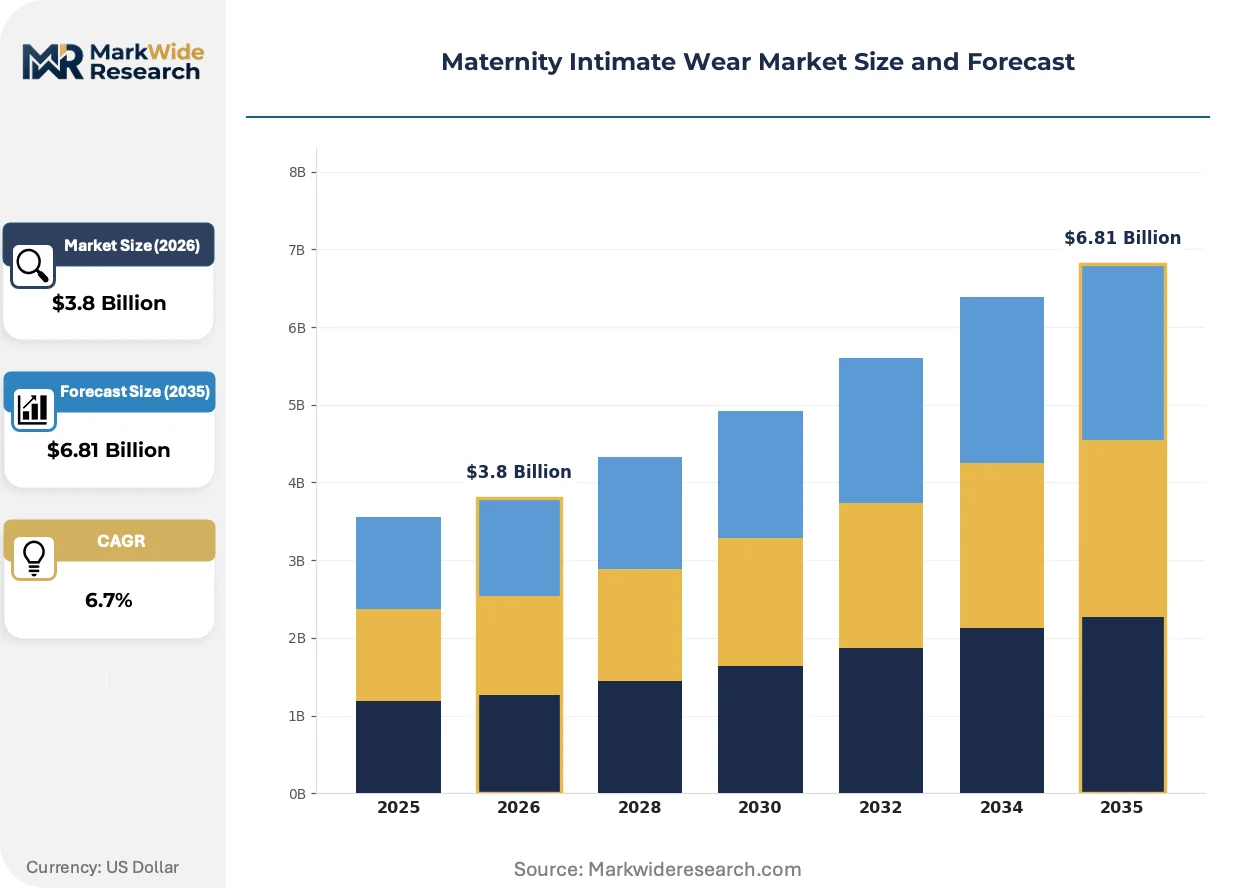
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nursing Bras, Maternity Briefs, Nursing Tanks, Belly Bands Material: Cotton, Spandex, Bamboo, Lace End User: Pregnant Women, Postpartum Mothers, Maternity Shops, Online Shoppers Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Ingrid & Isabel, Boob Design, Bodily, 23 Mai Paris, Mamalicious, PinkBlush Maternity, Seraphine, Tajinebanane, Motherhood Maternity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternity Intimate Wear Market Strategic Shifts
Material science advances and regulatory disclosure mandates are converging to redefine competitive differentiation in maternity intimate wear, with certification transparency and thermal performance emerging as primary purchase determinants.
Adaptive stretch-panel construction is migrating from fixed-compression designs to zone-engineered support systems that accommodate thoracic expansion through gestation. Premium-tier buyers in Germany and the United States adopt these garments earlier in pregnancy cycles. This migration from uniform elasticity to graduated compression is enabling brands to command price premiums through technical construction narratives.
REACH chemical restriction list expansions and the EU Green Deal's carbon border adjustment mechanisms are tightening material traceability obligations for European market access. Manufacturers must now document dye stuff and finishing chemical sources through tier-three suppliers. Nursing bra categories face the steepest compliance burden due to prolonged skin-contact duration and infant proximity concerns.
Subscription-based replenishment models are displacing episodic retail purchasing among repeat buyers with predictable sizing needs. Direct-to-consumer platforms capture postpartum mothers transitioning between maternity and nursing phases. This behavioral shift concentrates most visibly in the United States, where pharmacy chain partnerships and hospital discharge gift programs create hybrid physical-digital acquisition funnels.
Maternity Intimate Wear Market Segmentation
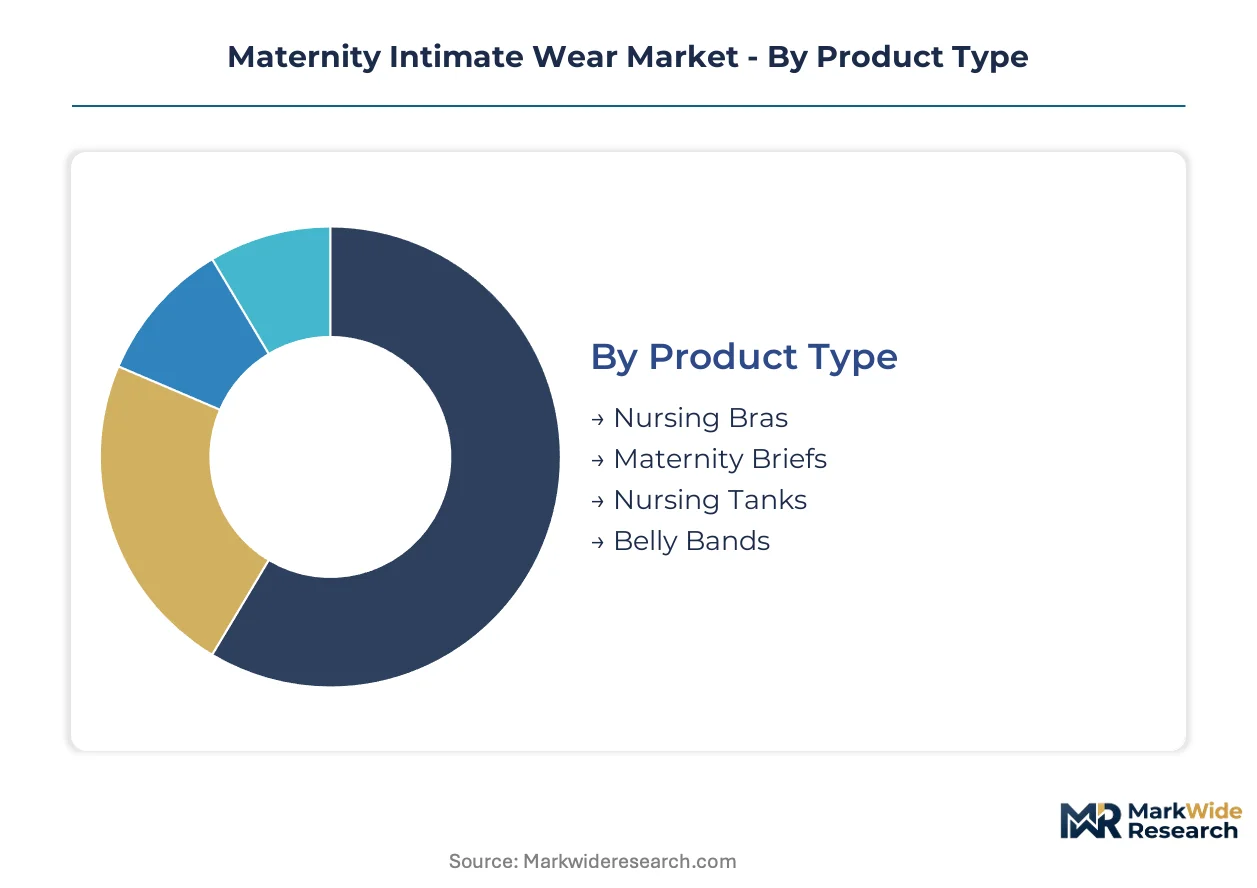
Maternity intimate wear segmentation reflects distinct physiological stages and purchasing contexts across gestation and lactation cycles. Product architecture, fiber composition, and channel preferences diverge sharply between first-time mothers and experienced buyers, creating parallel demand streams that manufacturers must address through specialized inventory and sizing systems.
Product Type:
Engineered support requirements vary dramatically across thoracic expansion, abdominal displacement, and nursing accessibility phases.
- Nursing Bras:Drop-cup mechanisms and stretch-panel construction accommodate ribcage expansion from first trimester through weaning. Repeat purchase cycles concentrate in the United States and Germany where subscription replenishment models have displaced episodic retail buying.
- Maternity Briefs:Low-rise and over-bump waistband configurations address comfort preferences shifting across pregnancy progression. Demand clusters in China where domestic e-commerce platforms enable rapid style turnover and size exchanges.
- Nursing Tanks:Integrated shelf bras with clip-down access layers provide discrete feeding functionality. Postpartum mothers in hospital discharge programs drive initial trial.
- Belly Bands:Elastic compression panels support abdominal weight distribution and lower back strain relief. Third-trimester mothers and postpartum recovery segments sustain volume.
Established volume favors nursing bras; emerging adoption favors belly bands as prenatal fitness culture expands.
Material:
Skin-contact duration and infant proximity elevate fiber safety certification requirements beyond conventional apparel standards.
- Cotton:Organic and conventional grades dominate base-layer construction for breathability and wash durability. Oeko-Tex Standard 100 certification requirements in Europe and North America constrain supplier pools to pre-qualified spinning mills.
- Bamboo:Viscose derived from bamboo pulp delivers thermal regulation and antimicrobial performance for postpartum moisture management. This material category is expanding most quickly as mothers prioritize infant-safe fiber proximity.
- Spandex:Recovery properties remain unmatched for stretch-panel construction despite bio-based substitution efforts. Elastane content typically ranges 8-15% in nursing bras.
- Lace:Decorative applications in premium tiers require dye stuff documentation under REACH chemical disclosure mandates.
Certified organic cotton anchors current volume; bamboo-derived alternatives command the steepest growth trajectory.
End User:
Purchasing authority and size predictability determine channel economics and return rate exposure.
- Pregnant Women:First-trimester entry purchases exhibit high size-exchange rates as body dimensions remain unstable. AI-driven fit prediction tools target this uncertainty.
- Postpartum Mothers:Predictable sizing needs enable subscription replenishment and bulk purchasing. Pharmacy chain partnerships in the United States capture this segment through hospital discharge gift programs.
- Maternity Shops:Wholesale accounts face margin compression as direct-to-consumer migration accelerates. Inventory risk concentrates with seasonal style obsolescence.
- Online Shoppers:Digital-native cohorts drive mobile-first purchasing with app-integrated sizing tools. Return logistics costs erode profitability without fit prediction technology.
Postpartum mothers concentrate margin stability; pregnant women represent the highest acquisition cost segment.
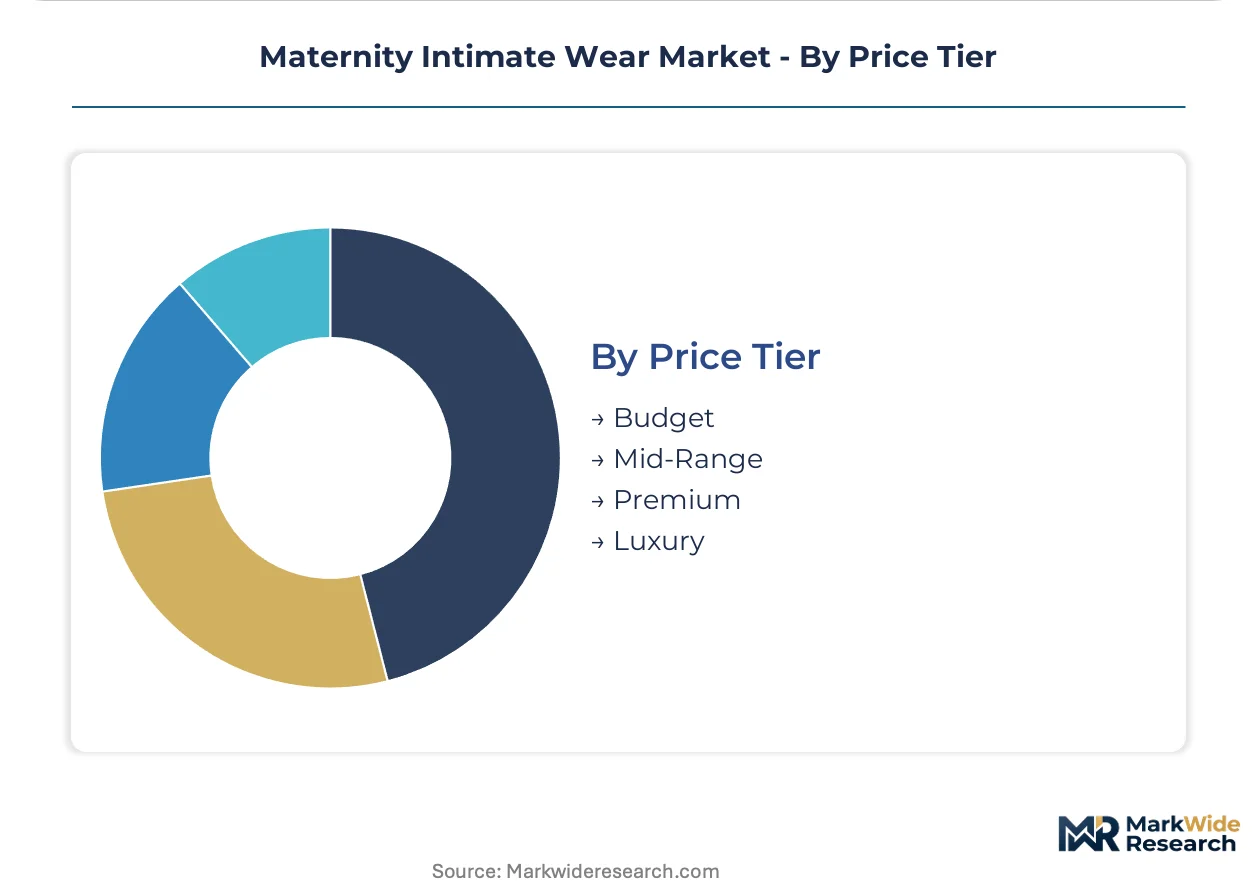
Price Tier:
Certification transparency and technical construction narratives justify tier separation.
- Budget:Basic cotton-spandex blends target price-sensitive first-time mothers with limited repeat purchase intent. Manufacturing concentrates in Bangladesh and Vietnam.
- Mid-Range:Balanced fiber quality with Oeko-Tex certification satisfies safety-conscious European buyers. This tier captures the largest addressable volume.
- Premium:Zone-engineered support systems and organic fiber sourcing command elevated price points. German and United States buyers adopt these garments earlier in pregnancy cycles.
- Luxury:Limited-run designs with full chain-of-custody documentation target gift purchasing and special occasion positioning. Margin pools concentrate here despite low unit volume.
Mid-range positioning captures volume concentration; premium tier expansion reflects certification premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA textile labeling requirements in the United States anchor the regulatory framework shaping maternity intimate wear market access, while REACH and Oeko-Tex Standard 100 mandates in Europe elevate compliance costs for cross-border suppliers.
United States
Millennial first-time mothers drive subscription nursing bra adoption through pharmacy chain partnerships and hospital discharge gift programs. FDA textile labeling enforcement mandates chemical disclosure for skin-contact garments. New York and Los Angeles concentrate direct-to-consumer brand headquarters where AI-driven fit prediction tools reduce return rates.
Germany
Postpartum mothers prioritize Oeko-Tex Standard 100 certified organic cotton for infant-safe fiber proximity. EU Green Deal extended producer responsibility frameworks mandate textile take-back program infrastructure. Bavaria hosts manufacturing clusters specializing in zone-engineered support systems for premium-tier nursing bras.
China
Domestic e-commerce platforms enable rapid maternity brief style turnover and size exchanges among price-sensitive first-time mothers. GB standards for textile safety enforcement create dual compliance burdens for export-oriented manufacturers. Guangdong Province concentrates bamboo fiber processing facilities serving antimicrobial fabric demand.
United Kingdom
Digital-native cohorts adopt app-integrated sizing tools for remote nursing bra purchasing with predictable postpartum sizing needs. REACH chemical restriction list expansions require tier-three dye stuff documentation. London anchors direct-to-consumer brand operations targeting hybrid physical-digital acquisition funnels.
France
Premium-tier buyers adopt adaptive stretch-panel construction earlier in pregnancy cycles with technical construction narratives justifying elevated price points. ECHA enforcement of SVHC candidate list substances tightens material traceability for lace decorative applications. Paris concentrates luxury limited-run design houses with full chain-of-custody documentation capabilities.
Maternity Intimate Wear Market Competitive Environment
Digital-native direct-to-consumer specialists and legacy retail-anchored incumbents split the maternity intimate wear market between channel strategies. Consolidation pressure concentrates among wholesale-dependent accounts facing margin compression. Three archetypes dominate: Scandinavian sustainability-certified manufacturers, North American pharmacy-channel anchors, and venture-backed fit-technology platforms. Geographic expansion through hospital procurement partnerships and backward integration into organic fiber sourcing represent the dominant competitive moves reshaping supplier relationships.
Within the sustainability-certified tier, Boob Design exemplifies Scandinavian manufacturing-base positioning for Oeko-Tex compliance across European markets. Seraphine and PinkBlush Maternity occupy the direct-to-consumer pivot archetype, redirecting marketing spend from wholesale accounts toward owned digital platforms. Motherhood Maternity anchors the retail-partnership archetype through extensive pharmacy chain and hospital gift shop penetration in North America. These three entities collectively represent the strategic positioning spectrum—certified sourcing, channel migration, and institutional access—that defines current competitive differentiation.
| Leading Market Players |
|---|
| Ingrid & Isabel |
| Boob Design |
| Bodily |
| 23 Mai Paris |
| Mamalicious |
| PinkBlush Maternity |
| Seraphine |
| Tajinebanane |
| Motherhood Maternity |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Bangladeshi cut-and-sew facilities compresses unit economics for basic cotton-spandex maternity briefs while elevating bargaining power for buyers of certified organic grades. This utilization asymmetry between commodity and premium tiers reshapes supplier selection criteria across the value chain.
Pricing Analysis
Geographic price spreads between United States direct-to-consumer premiums and Chinese e-commerce base tiers exceed threefold multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and fiber provenance. Price differentiation separates Oeko-Tex Standard 100 certified organic lines from uncertified conventional production. Cost compression in budget tiers intensifies because of Bangladeshi overcapacity and synthetic elastane price volatility. First-time pregnant women exhibit highest price sensitivity; postpartum subscription buyers demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for bamboo fiber sourcing and finished garment importation. Manufacturing concentrates in Bangladesh, Vietnam, and China for cut-and-sew assembly; organic cotton spinning anchors in India and Turkey. Raw material dependencies include GOTS-certified cotton, bamboo viscose pulp, and petroleum-derived spandex. Single-source vulnerability concentrates in Guangdong Province bamboo processing facilities. Distribution runs through direct-to-consumer platforms, pharmacy chain partnerships, and hospital gift shop procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from venture-backed fit-technology platforms deploying AI-driven sizing tools that erode brand loyalty among digital-native first-time mothers.
For Market Incumbents: Pre-empt platform-based entrants by acquiring smartphone body-scanning capabilities or licensing fit-prediction algorithms. Consolidate backward integration into organic cotton sourcing to secure GOTS-certified fiber allocations against climate-induced yield volatility. Certification investment in Oeko-Tex Standard 100 and EU Green Deal compliance infrastructure defends margin position against regulatory escalation.
For New Entrants and Emerging Players: Hospital discharge gift programs in the United States and Germany represent the most penetrable entry point for initial customer acquisition. Postpartum mothers with predictable sizing needs enable subscription replenishment models with superior unit economics. App-integrated sizing tools reduce return rate exposure and accelerate direct-to-consumer conversion.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with established postpartum customer cohorts. Long-term viability over the next decade hinges on circular infrastructure capabilities including textile take-back programs and recycling partnerships. Watch EU Green Deal extended producer responsibility enforcement timelines as inflection indicator for compliance cost restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Owned digital channels capture subscription nursing bra renewals with superior retention economics. |
| Organic Fiber Backward Integration | GOTS-certified cotton sourcing secures supply against climate volatility in India and Turkey. |
| AI-Driven Fit Prediction Integration | Smartphone body-scanning reduces return logistics costs and sizing friction for remote purchasers. |
| Hospital Procurement Partnership | Institutional access during prenatal visits creates captive audience acquisition at zero CAC. |
| Circular Infrastructure Buildout | Textile take-back programs satisfy EU Green Deal mandates and unlock sustainability premium pricing. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade records, Oeko-Tex certification databases, and hospital procurement contract filings. Primary interviews engaged brand managers at direct-to-consumer maternity wear companies, category buyers at pharmacy chains, supply planners at organic cotton spinning mills, and regulatory affairs leads at certification bodies. Secondary validation drew from FDA textile labeling guidance documents, REACH chemical restriction list updates, and EU Green Deal implementation timelines. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, end user, and price tier dimensions.
Forecast inputs include gestation-stage purchasing patterns, lactation duration statistics, e-commerce penetration curves, and certification adoption rates across the analysis window. Segmentation modeling spans product architecture, fiber composition, channel preference, and geographic regulatory cluster. CAGRs derive from trend extrapolation of historical volume trajectories adjusted for cohort-specific behavioral shifts. Industry-specific inputs incorporate nursing bra repeat purchase cycle frequency and bamboo fiber processing capacity expansion.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, cotton commodity prices, or cross-border tariff schedules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and digital channel migration velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Compression and Shapewear Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Chest Bags Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Streetwear Market