
 Asia-Pacific Cross-Border B2C E-Commerce Market | 2026-2036
Asia-Pacific Cross-Border B2C E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cross-Border B2C E-Commerce Market Insights
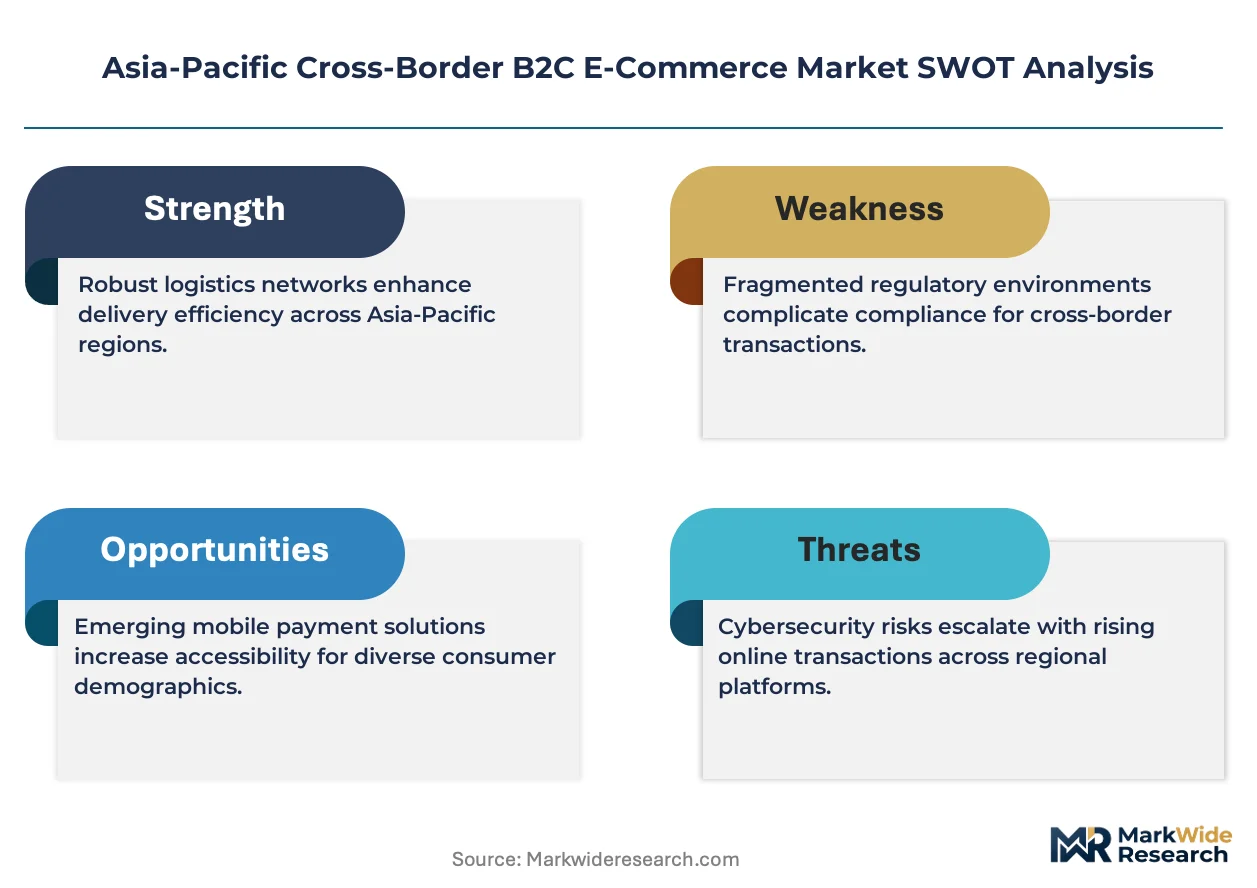
Asset-light marketplace financing is reshaping competitive entry in Asia-Pacific cross-border B2C e-commerce, allowing platforms to scale inventory without balance-sheet heaviness. Alibaba Group Holding Limited leverages its Cainiao logistics arm to sustain fulfillment density across ASEAN corridors. Shopee anchors seller liquidity through embedded working-capital products in Indonesia and Vietnam. JD.com differentiates via captive warehouse networks that control last-mile temperature integrity for beauty and electronics imports.
Asia-Pacific cross-border B2C e-commerce denotes consumer-facing retail transactions where buyers in one national jurisdiction purchase goods from sellers headquartered in another, with customs clearance, payment settlement, and logistics orchestrated through digital infrastructure. The model relies on harmonized HS code classification, real-time duty calculators, and multi-currency escrow to reduce friction at borders. Apparel and electronics dominate transaction volumes, though beauty products command higher per-unit margins due to regulatory complexity and brand premiums. Mobile apps capture the fastest-growing share of sales channels, displacing desktop marketplaces as smartphone penetration deepens in Philippines and Bangladesh.
China's SAMR enforces product-safety labeling and consumer-recourse rules for inbound parcels, while India's DGFT customs notifications reshape duty-free thresholds for cross-border shipments. Indonesia's BIS-equivalent standards body mandates pre-shipment inspection for electronics and cosmetics entering through bonded zones. Stakeholders must monitor how ASEAN's forthcoming digital economy framework agreement harmonizes data-localization rules against payment-integration requirements.
Market Dynamics
Mobile-first purchasing infrastructure is compressing checkout friction across Southeast Asia's archipelago corridors, while China's SAMR regulatory harmonization accelerates customs clearance velocity for inbound parcels.
Growth Catalysts
- ASEAN Digital Economy Framework Agreement:The forthcoming harmonization of data-localization rules against payment-integration requirements reduces cross-border compliance fragmentation for platforms operating across Indonesia, Vietnam, and Philippines corridors.
- Fashion-conscious millennials:This demographic segment in Southeast Asia drives adoption through smartphone-native purchasing behaviors, concentrating demand in apparel and beauty categories with higher per-unit margins.
- India's DGFT customs notifications:Reshaped duty-free thresholds for cross-border shipments lower landed costs for tier-two urban clusters, expanding addressable consumer bases beyond metro corridors.
Market Restraints
- Pre-shipment inspection mandates:Indonesia's BIS-equivalent standards body requires mandatory inspection for electronics and cosmetics entering bonded zones, adding 3-5 days to fulfillment timelines and increasing working capital lockup.
- Last-mile temperature integrity:Captive warehouse networks remain concentrated in China and Singapore, creating single-point vulnerability for beauty and electronics imports requiring climate-controlled handling.
- Multi-currency escrow complexity:Real-time settlement across Philippine peso, Indonesian rupiah, Indian rupee, and Vietnamese dong introduces FX volatility exposure that asset-light marketplaces must hedge or absorb.
Strategic Opportunities
- Bangladesh smartphone penetration:Underpenetrated mobile commerce infrastructure in Dhaka and Chittagong corridors offers first-mover positioning before platform saturation mimics Indonesia's trajectory.
- Embedded working-capital products:Seller liquidity tools pioneered in Indonesia and Vietnam can migrate to Indian tier-three clusters where traditional trade credit remains scarce.
- Real-time duty calculators:Convergence of HS code classification engines with AI-powered customs documentation is compressing clearance times at Mumbai and Jakarta ports.
Industry Challenges
- Harmonized HS code expertise:Talent scarcity in cross-border tariff engineering forces platforms to maintain redundant compliance teams across Singapore, Hong Kong, and Shanghai coordination hubs.
- Bonded zone integration:Legacy ERP systems at Indonesian and Indian customs facilities require expensive API reconfiguration to support real-time inventory visibility.
- Consumer-recourse rule variance:Divergent SAMR labeling requirements versus India's DGFT dispute resolution timelines create operational complexity for multi-destination sellers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cross-Border B2C E-Commerce Market |
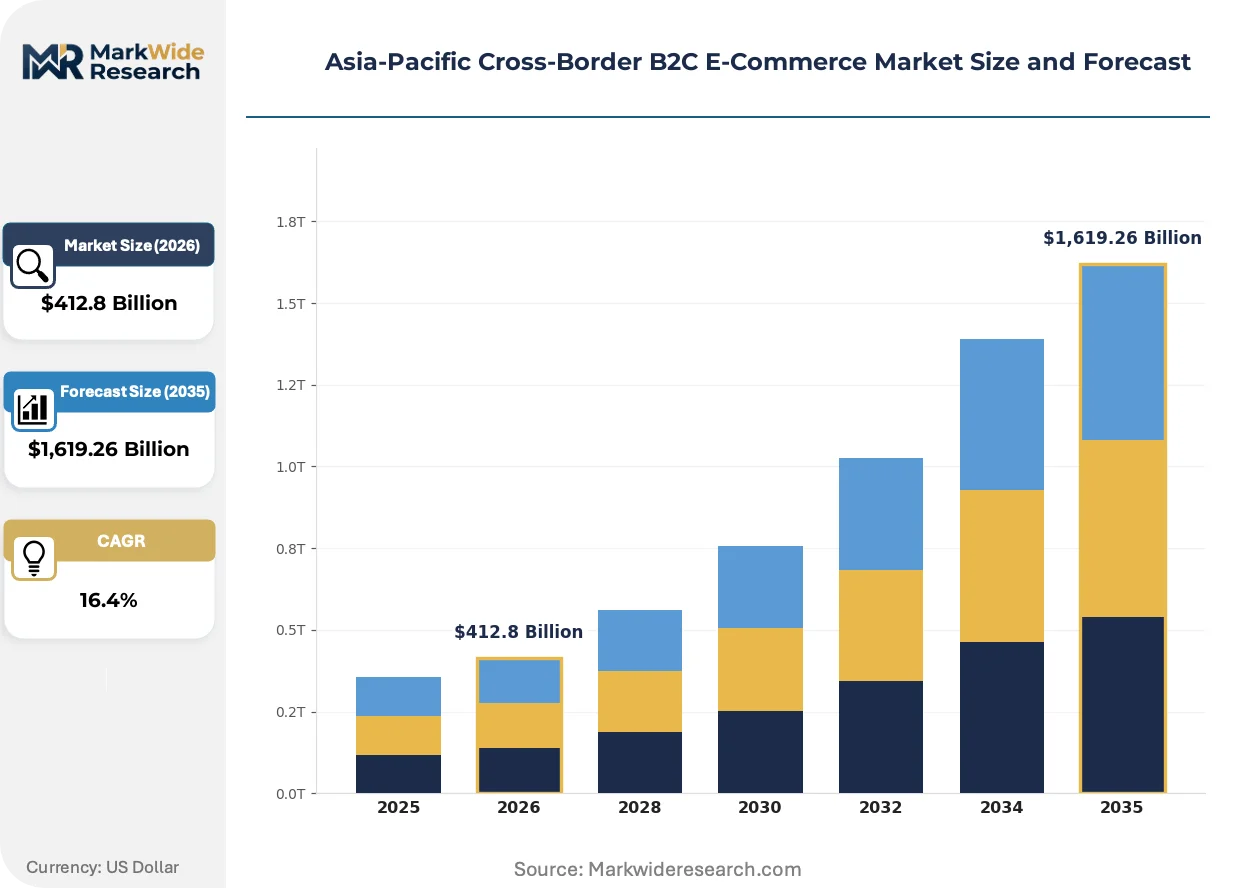
| Market Size in 2026 | $412.8 Billion |
| Market Size in 2035 | $1,619.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Beauty Products, Home Goods Sales Channel: Online Marketplaces, Company Websites, Social Media, Mobile Apps Customer Type: Millennials, Gen Z, Professionals, Families Payment Method: Credit Cards, Digital Wallets, Bank Transfers, Cash on Delivery |
| Companies Covered | Alibaba Group Holding Limited, JD.com, Shopee (Sea Ltd), Lazada Group, Rakuten, Tokopedia (GoTo), Pinduoduo, Shein, Qoo10 Pte Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cross-Border B2C E-Commerce Market Trends and Innovations
Platform infrastructure is migrating from desktop marketplaces toward smartphone-native super-apps, compressing the traditional e-commerce value chain while regulatory harmonization efforts reshape compliance architecture across the region.
Live-stream commerce technology is migrating from entertainment-adjacent novelty toward primary sales channel status. Beauty and electronics sellers in Vietnam and Thailand now allocate 40-60% of marketing spend to influencer-hosted sessions. This format is migrating from discretionary experimentation toward mandatory infrastructure, forcing legacy platforms to rebuild their seller dashboards around real-time inventory flash mechanics.
China's SAMR cross-border e-commerce regulatory framework streamlines customs clearance through standardized product-safety labeling and unified consumer-recourse rules. The industrial consequence is reduced documentation friction for inbound parcels under 5,000 yuan declared value. Beauty imports entering through Shanghai and Hangzhou bonded zones are responding by consolidating previously fragmented supplier bases to exploit clearance velocity advantages.
Social discovery is displacing search-led purchasing as the dominant path to transaction initiation. Young consumers in Philippines and Indonesia now encounter products through TikTok and Instagram algorithms before expressing explicit purchase intent. This behavioral shift is most visible in fast-fashion verticals where impulse conversion rates exceed traditional marketplace benchmarks by 2-3x, forcing platforms to reallocate advertising inventory toward content-native placement.
Asia-Pacific Cross-Border B2C E-Commerce Market Segmentation
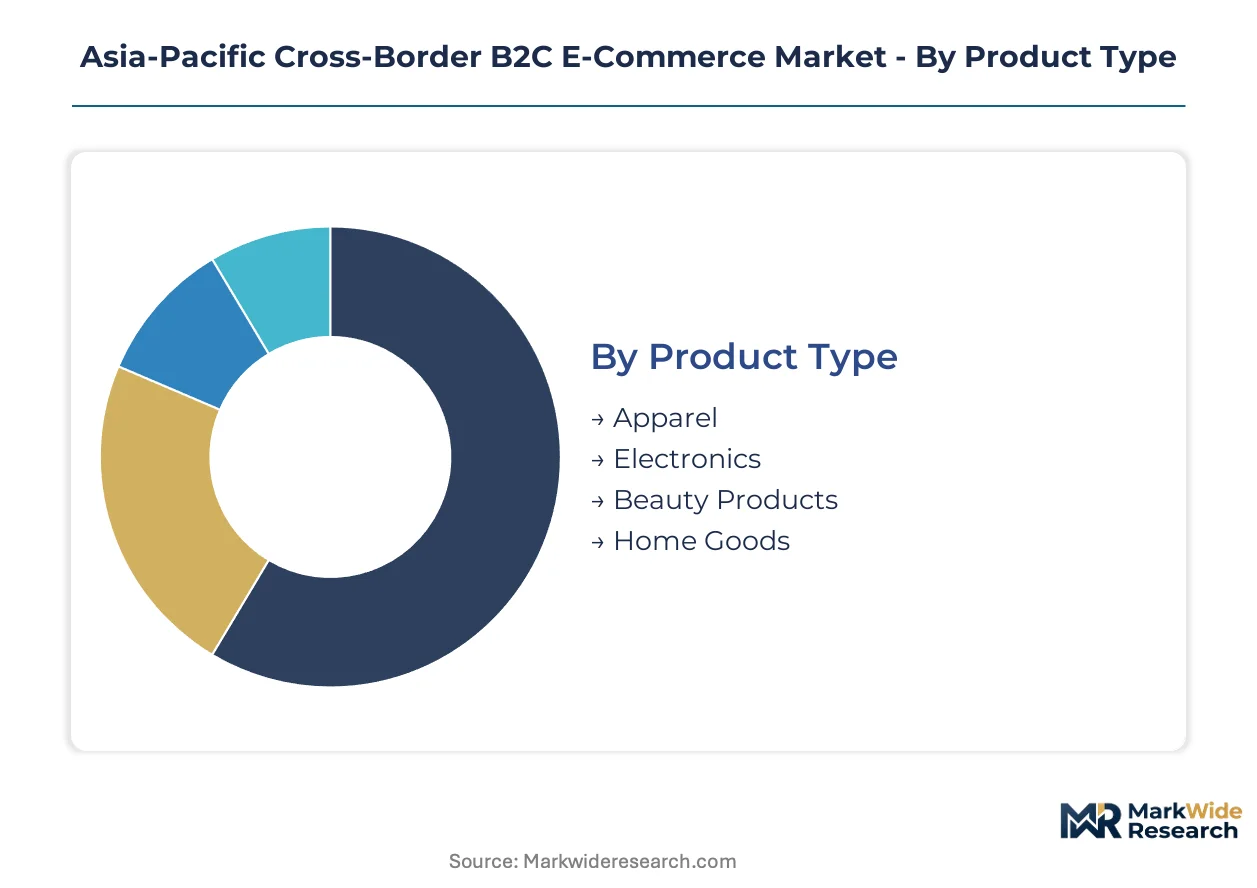
Segmentation in Asia-Pacific cross-border B2C e-commerce reveals how mobile infrastructure, regulatory thresholds, and demographic purchasing power concentrate demand across distinct product and channel configurations. Understanding these partitions illuminates where platform investment and compliance resources generate disproportionate returns.
Product Type:
Mature categories dominate transaction volume while emerging verticals capture margin expansion through regulatory complexity and brand premiums.
- Apparel:Fast-fashion SKUs with standardized HS classifications move through Shanghai and Jakarta bonded zones with minimal inspection friction. Demand clusters in Vietnam and Philippines corridors where social discovery algorithms drive impulse conversion rates above traditional marketplace benchmarks.
- Electronics:Smartphones and accessories require pre-shipment inspection under Indonesia's BIS-equivalent standards, adding fulfillment latency that favors sellers with captive warehouse networks in Singapore. India's tier-two urban clusters absorb the fastest volume growth as DGFT duty thresholds improve landed cost economics.
- Beauty Products:Temperature-controlled last-mile requirements concentrate margin capture among platforms with climate-integrity infrastructure.
- Home Goods:Bulky freight economics limit cross-border viability to higher-value decorative and smart-home categories.
Apparel handles the majority of throughput; beauty products are expanding most quickly on margin contribution.
Sales Channel:
Channel economics stratify by customer acquisition cost and inventory ownership intensity, with asset-light models gaining traction against balance-sheet-heavy alternatives.
- Mobile Apps:Super-app ecosystems in Indonesia and Philippines compress checkout friction through embedded payment and logistics orchestration. Smartphone-native millennials drive the steepest expansion trajectory as desktop displacement accelerates in Dhaka and Chittagong corridors.
- Social Media:Live-stream commerce in Vietnam and Thailand now commands 40-60% of seller marketing spend, forcing platform rebuilds around real-time inventory flash mechanics. TikTok and Instagram algorithms initiate transaction paths before explicit purchase intent forms.
- Online Marketplaces:Alibaba and Shopee infrastructure anchors cross-border fulfillment density across ASEAN corridors.
- Company Websites:Direct-to-consumer models concentrate among beauty brands seeking margin protection from marketplace commission structures.
Mobile apps capture the dominant share of new customer acquisition; social media is climbing the fastest on engagement-to-transaction conversion.
Customer Type:
Purchasing behavior diverges sharply by digital nativity and disposable income stability, shaping platform merchandising and payment integration priorities.
- Millennials:Fashion-conscious smartphone natives in Southeast Asia concentrate demand in apparel and beauty categories with higher per-unit margins. This cohort responds most aggressively to influencer-hosted live-stream sessions and algorithmic product discovery.
- Gen Z:Social-first purchasing patterns in Philippines and Indonesia prioritize content-native placement over search-led transaction initiation.
- Professionals:Electronics and premium beauty imports dominate purchasing baskets in Indian tier-two urban clusters.
- Families:Home goods and bulk consumables concentrate demand in markets with improving cross-border logistics reliability.
Millennials anchor current revenue concentration; Gen Z is gaining share fastest on platform-native engagement patterns.
Payment Method:
Settlement infrastructure maturity determines addressable customer bases, with FX volatility exposure creating operational complexity for multi-currency platforms.
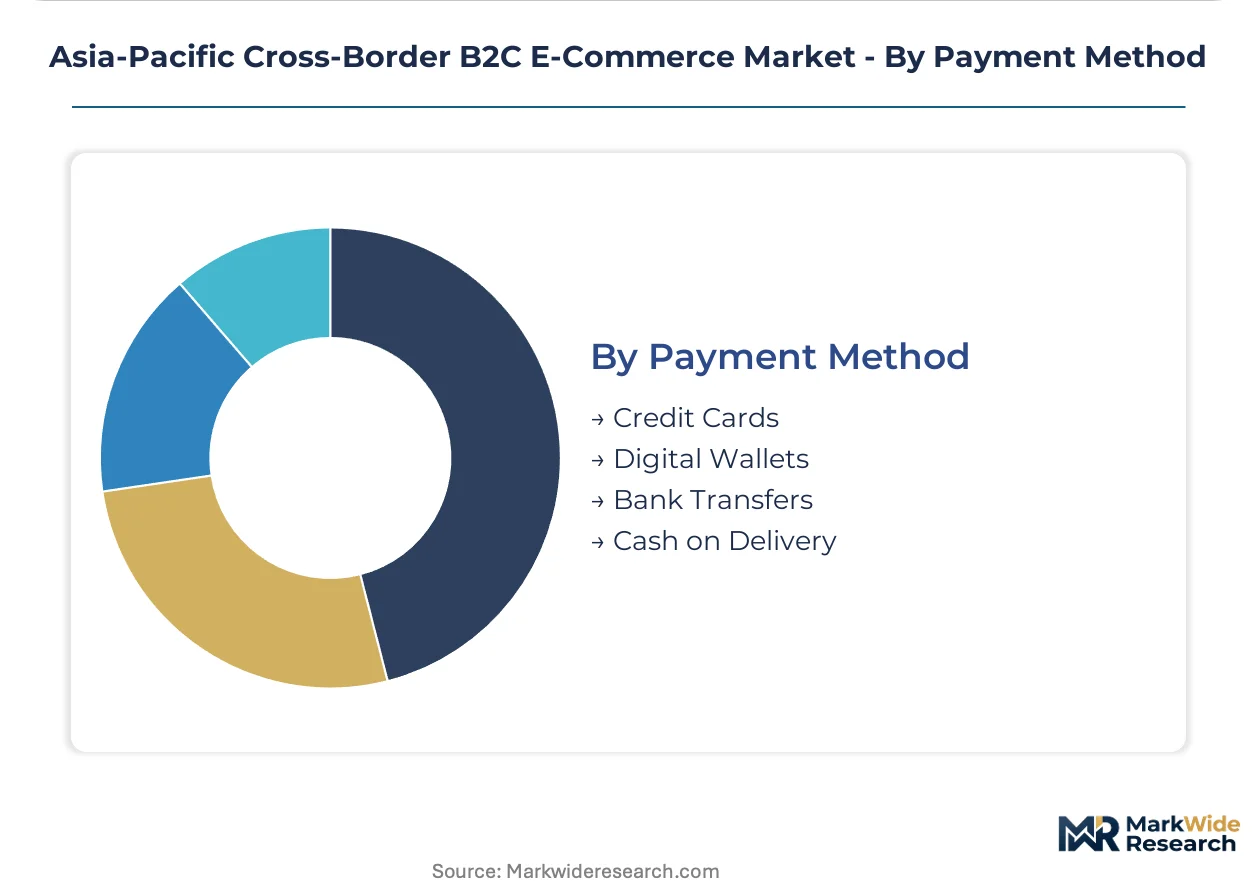
- Digital Wallets:Embedded escrow in Indonesian rupiah and Vietnamese dong reduces checkout abandonment but introduces hedging requirements for asset-light marketplaces. Smartphone penetration in Bangladesh creates first-mover positioning before platform saturation.
- Credit Cards:Concentrated among professionals in Indian tier-two clusters and mature ASEAN urban corridors with established banking infrastructure.
- Bank Transfers:Preferred for higher-value electronics transactions where real-time settlement reduces seller working capital lockup.
- Cash on Delivery:Persists in underpenetrated logistics corridors where trust deficits and financial inclusion gaps limit digital payment adoption.
Digital wallets process the majority of transaction volume; bank transfers are expanding most quickly on high-ticket electronics purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's cross-border e-commerce regulatory framework in China streamlines customs clearance and consumer protection, creating template effects for neighboring jurisdictions. India's DGFT duty-free threshold adjustments expand addressable consumer bases beyond metro corridors. Indonesia's BIS-equivalent standards body mandates pre-shipment inspection for electronics and cosmetics entering bonded zones.
China
Shanghai and Hangzhou bonded zones consolidate fragmented supplier bases for beauty imports under 5,000 yuan declared value thresholds. SAMR enforces standardized product-safety labeling and unified consumer-recourse rules. Yangtze River Delta logistics corridors exploit clearance velocity advantages to compress fulfillment timelines for ASEAN-bound parcels.
India
Tier-two urban clusters absorb the fastest volume growth in electronics as DGFT customs notifications reshape duty-free thresholds. Mumbai and Delhi-NCR corridors concentrate platform fulfillment density. Karnataka and Maharashtra sub-regions host expanding warehouse networks targeting professional-class demand for premium beauty imports.
Indonesia
Archipelago logistics corridors concentrate demand from fashion-conscious millennials purchasing through smartphone-native super-apps. Pre-shipment inspection mandates for electronics and cosmetics add 3-5 days to fulfillment timelines. Jakarta and Surabaya bonded zones require expensive API reconfiguration to support real-time inventory visibility.
Vietnam
Live-stream commerce commands 40-60% of seller marketing spend in beauty and electronics verticals. Ho Chi Minh City and Hanoi corridors anchor embedded working-capital products that sustain seller liquidity. Vietnamese dong settlement infrastructure reduces checkout abandonment but introduces FX hedging requirements for asset-light marketplaces.
Philippines
Social discovery algorithms on TikTok and Instagram displace search-led purchasing initiation for fast-fashion SKUs. Manila and Cebu logistics corridors face trust deficits that sustain cash-on-delivery persistence. Smartphone penetration deepens mobile app capture of sales channels before platform saturation mimics Indonesia's trajectory.
Asia-Pacific Cross-Border B2C E-Commerce Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fulfillment infrastructure and inventory ownership intensity. The vendor base stratifies between asset-light marketplace models and balance-sheet-heavy captive warehouse networks. Three archetypes dominate: logistics-integrated conglomerates, social-commerce platforms, and direct-to-consumer specialists. Competitive moves concentrate on geographic corridor expansion and embedded financial product rollout.
Within the logistics-integrated tier, Alibaba Group Holding Limited and JD.com exemplify divergent fulfillment strategies. Alibaba leverages its Cainiao logistics arm to sustain density across ASEAN corridors. JD.com anchors its positioning through captive warehouse networks controlling last-mile temperature integrity. Shopee occupies a distinct archetype as a social-commerce platform embedding working-capital products in Indonesia and Vietnam. These three players collectively represent the strategic spectrum from asset-light marketplace financing to balance-sheet-heavy infrastructure ownership.
| Leading Market Players |
|---|
| Alibaba Group Holding Limited |
| JD.com |
| Shopee (Sea Ltd) |
| Lazada Group |
| Rakuten |
| Tokopedia (GoTo) |
| Pinduoduo |
| Shein |
| Qoo10 Pte Ltd |
| Others |
Pricing and Supply Chain Analysis
Shanghai and Hangzhou bonded zones anchor clearance velocity advantages that compress fulfillment timelines for ASEAN-bound parcels, translating infrastructure density into pricing power for platforms controlling captive warehouse networks. SAMR's standardized labeling requirements under 5,000 yuan thresholds create tiered cost structures where compliant sellers extract margin premiums from fragmented competitors facing documentation friction.
Pricing Analysis
Certification level (SAMR-compliant labeling tiers) creates the primary spread between premium-positioned sellers and economy operators in cross-border fulfillment. Three-tier pricing structure across premium, standard, and economy levels stratifies by customs clearance speed and temperature-integrity guarantees. Cost compression in the economy tier is intensifying because pre-shipment inspection mandates in Indonesia extend working capital cycles. Small-scale marketplace sellers exhibit highest price sensitivity, while captive-network operators absorb margin pressure through vertical integration.
Supply Chain Analysis
Export-control restrictions on semiconductor components and advanced logistics software limit technology transfer into certain bonded zone configurations. Supply concentrates in China, Singapore, and Vietnam for last-mile fulfillment infrastructure. Raw material dependencies span temperature-controlled packaging, lithium-ion power cells for delivery fleets, and bonded-zone real estate. Single-source vulnerability runs through Singapore's climate-integrity warehouse concentration. Distribution runs through mobile super-apps and live-stream commerce platforms rather than traditional marketplace intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through SAMR compliance certification creates switching costs that lock in seller bases. Network effects in logistics density compound as fulfillment velocity advantages attract incremental merchant volume.
For Market Incumbents: Build switching-cost moats through embedded working-capital products that deepen seller dependency. Deepen vertical integration into temperature-controlled last-mile networks to defend against asset-light challengers. Anchor capacity expansion in Indian tier-two clusters before DGFT threshold adjustments attract competitor entry. Prioritize API reconfiguration investments at Jakarta and Surabaya bonded zones to sustain real-time inventory visibility advantages. For New Entrants and Emerging Players: Establish a beachhead in Bangladesh's Dhaka and Chittagong corridors before smartphone penetration saturation mimics Indonesia's trajectory. Target live-stream commerce infrastructure gaps in Philippines where social discovery algorithms displace search-led purchasing. Exploit talent scarcity in cross-border tariff engineering by recruiting redundant compliance teams from Singapore coordination hubs. Launch with influencer-hosted session formats that command 40-60% of seller marketing spend in Vietnam. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with captive warehouse networks over pure marketplace models. Long-term viability hinges on controlling climate-integrity infrastructure as beauty and electronics imports expand. Acquisition target archetype: vertically integrated specialists with ASEAN corridor density and SAMR certification capabilities. Watch embedded finance product penetration rates as the inflection indicator for platform stickiness.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Working-Capital Product Rollout | Seller liquidity tools pioneered in Indonesia migrate to Indian tier-three clusters where traditional trade credit remains scarce. |
| Climate-Integrity Warehouse Expansion | Captive networks controlling last-mile temperature integrity capture margin premiums in beauty and electronics verticals. |
| Live-Stream Commerce Infrastructure Buildout | Real-time inventory flash mechanics in Vietnam and Thailand force legacy platform rebuilds around influencer-hosted sessions. |
| Bonded Zone API Reconfiguration | Legacy ERP integration at Jakarta ports compresses clearance timelines for SAMR-compliant shipments under 5,000 yuan. |
| Cross-Border Tariff Engineering Talent Acquisition | Specialized HS code expertise reduces redundant compliance team maintenance across Singapore and Hong Kong hubs. |
Research Methodology
Operator-level perspectives from platform logistics directors, cross-border seller operations leads, bonded zone facility managers, and customs clearance specialists anchored the qualitative base. Primary interviews combined with secondary validation from SAMR regulatory filings, DGFT customs notifications, ASEAN trade statistics, and logistics operator disclosures. Bottom-up transaction volume estimates triangulated against top-down corridor capacity assessments.
Scenario-bracketing framed demand projections across the analysis window, modeling product type, sales channel, customer demographic, and payment method segmentation dimensions. CAGRs derived from corridor-level growth rate convergence with macroeconomic consumption indicators. Forecast inputs incorporated smartphone penetration trajectories in Bangladesh and live-stream commerce adoption curves in Vietnam.
Sensitivities concentrate around SAMR regulatory amendments, DGFT duty threshold revisions, and ASEAN digital economy framework implementation timelines. Forecasts reflect documented assumptions on bonded zone capacity expansion and embedded finance product penetration. Material shifts in pre-shipment inspection mandate scope or data-localization rule harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Social Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
United States E-Commerce Market
E-Commerce Solutions
E-Commerce Market