
 Direct-To-Consumer Test Market | 2026-2036
Direct-To-Consumer Test Market Size, Share, and Industry Trends Forecast 2026-2036
Direct-To-Consumer Test Market Outlook
A shift from clinic-dependent sampling to at-home collection and telehealth-integrated result delivery is restructuring procurement patterns across the diagnostic value chain. 23andMe leverages its proprietary genotyping platform to sustain direct consumer relationships beyond ancestry into pharmacogenomics. Everlywell anchors its position through partnerships with certified laboratories, while Quest Diagnostics competes by extending its clinical credibility into consumer-facing digital portals.
Direct-to-consumer tests encompass self-administered biological specimen collection kits analyzed in CLIA-certified laboratories, with results delivered through encrypted digital platforms to individuals without physician intermediation. These products employ dried blood spot cards, saliva collection vessels, or micro-sampling devices stabilized for ambient shipping, serving commercial purposes spanning disease screening, carrier status determination, and personalized wellness optimization. Genetic tests occupy the premium tier of product type segmentation due to higher processing complexity and interpretive value, while subscription services within the delivery model dimension capture recurring revenue streams that health risk assessments increasingly favor. Nutritional analysis products differentiate through algorithmic integration with wearable biometric data, creating stickier consumer relationships than one-time ancestry queries.
FDA premarket review pathways and CLIA laboratory certification requirements govern test accuracy claims and analytical validity in the United States, compressing market access timelines for novel biomarker introductions. HIPAA and state-level genetic privacy laws constrain data monetization architectures, compelling platform redesigns that localize storage and limit third-party sharing. Stakeholders must monitor evolving state laboratory licensing reciprocity agreements and federal preemption debates that could fragment compliance burdens or create unified national standards.
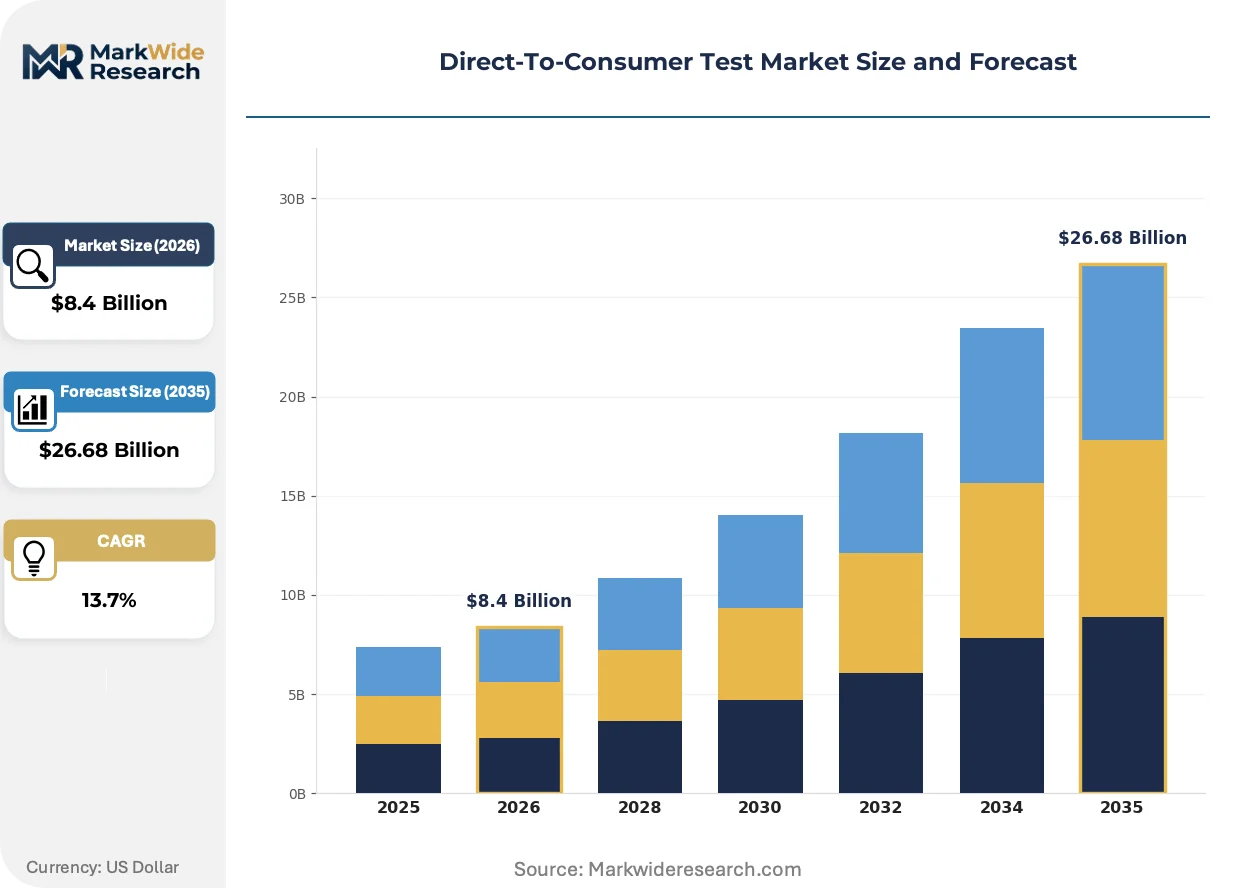
Market Dynamics
Telehealth integration and at-home specimen collection are compressing the diagnostic value chain, eliminating physician intermediation and shifting laboratory economics toward high-throughput CLIA-certified processing centers.
Growth Catalysts
- Employer wellness program expansion:Large corporations in the United States are bundling subscription-based health risk assessments into employee benefits, creating recurring revenue pools for platform providers.
- CLIA laboratory certification standardization:Federal quality requirements for analytical validity are building consumer trust in self-collected specimen results versus clinic-dependent alternatives.
- Pharmacogenomics clinical validation:Drug-gene interaction evidence is expanding reimbursable indications for genetic testing beyond ancestry into medication management.
Market Restraints
- HIPAA and state genetic privacy fragmentation:Inconsistent privacy laws across United States jurisdictions are constraining cross-border data architectures and platform standardization.
- FDA premarket review timelines:Novel biomarker validation requirements are extending commercialization cycles for laboratory-developed tests beyond typical venture capital horizons.
- Reagent supply concentration:Specialized stabilization chemistries for ambient shipping depend on limited North American and European chemical suppliers.
Strategic Opportunities
- Direct primary care model alignment:Membership-based primary care practices in the United States are integrating at-home testing into preventive care protocols, bypassing traditional insurance reimbursement.
- Wearable biometric convergence:Continuous glucose monitors and fitness trackers are creating data integration opportunities for nutritional analysis algorithms.
- Medicare Advantage supplemental benefits:CMS flexibility for supplemental health benefits is enabling plans to cover home-based screening for chronic disease monitoring.
Industry Challenges
- Genetic counselor workforce scarcity:Interpretation of complex pharmacogenomic results requires specialized clinical expertise that outpaces training program output.
- Interoperability with electronic health records:Proprietary platform formats are creating friction for result integration into hospital and health system workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct-To-Consumer Test Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Tests, Health Risk Assessments, Nutritional Analysis, Lifestyle Monitoring Consumer Type: Fitness Enthusiasts, Health-Conscious Individuals, Busy Professionals, Families Delivery Model: Online Sales, Subscription Services, Mobile App Integration, Retail Outlets End User: Consumers, Health Care Providers, Wellness Coaches, Nutritionists |
| Companies Covered | 23andMe, Inc., Ancestry, Everlywell, Inc., LetsGetChecked, Color Health, Inc., Helix, Inc., Labcorp, MyHeritage Ltd., Quest Diagnostics Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct-To-Consumer Test Market Strategic Shifts
Micro-sampling devices and dried blood spot technologies are collapsing the infrastructure requirements for diagnostic access, enabling specimen stability without cold chain logistics and expanding addressable populations beyond urban clinical corridors.
Capillary micro-sampling technology is consolidating the specimen collection step into finger-prick volumes that stabilize biomarkers for ambient transport. Health-conscious individuals in employer wellness programs are adopting these devices at accelerating rates. This consolidation is compressing the cost structure of longitudinal monitoring and displacing venipuncture-dependent panels for routine wellness tracking.
FDA premarket review pathway refinements for laboratory-developed tests are reshaping validation requirements for analytical and clinical claims. Manufacturers must now demonstrate analytical validity through prospective studies before marketing novel biomarkers. Genetic testing platforms face the steepest compliance burden, with pharmacogenomic indications requiring extensive drug-gene interaction evidence.
Subscription service models are displacing one-time transactional purchases across wellness and nutritional analysis segments. Direct primary care practices and employer benefits administrators are negotiating annual contracts for comprehensive screening panels. This shift concentrates procurement decisions among benefits managers rather than individual consumers, most visibly in United States metropolitan markets with mature direct primary care penetration.
Direct-To-Consumer Test Market Segmentation
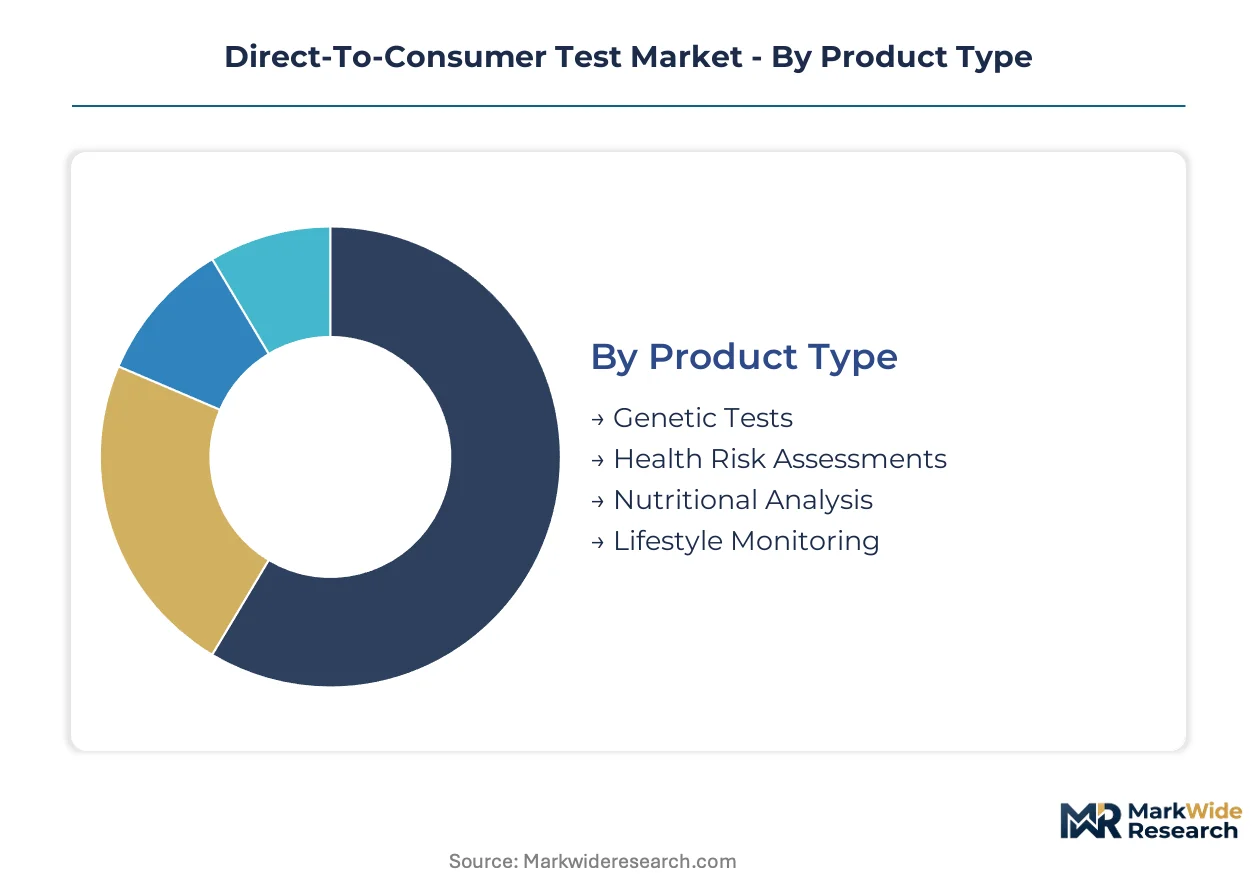
Segmentation in direct-to-consumer testing reveals divergent paths to market capture. Product complexity and recurring revenue potential separate premium genetic platforms from commoditized wellness trackers. Consumer motivation and procurement channel further stratify addressable populations and margin structures.
Product Type:
Price sensitivity and interpretive depth divide buyers across this dimension, with complexity premiums commanding subscription loyalty.
- Genetic Tests:These assays analyze DNA variants for ancestry, carrier status, and drug-gene interactions using microarray or sequencing platforms. Demand concentrates among health-conscious individuals in employer wellness programs, driven by pharmacogenomic reimbursement expansion and personalized medication management protocols.
- Health Risk Assessments:Multi-biomarker panels screen for diabetes, cardiovascular, and metabolic conditions through dried blood spot analysis. Procurement tilts toward direct primary care practices in United States metropolitan markets, where membership-based models bypass traditional insurance authorization.
- Nutritional Analysis:Metabolite profiling paired with algorithmic dietary recommendations.
- Lifestyle Monitoring:Cortisol, sleep hormone, and stress marker tracking for optimization protocols.
Volume sits with Health Risk Assessments; growth tilts toward Genetic Tests.
Consumer Type:
Engagement frequency and price elasticity distinguish these buyer personas, from sporadic purchasers to committed subscribers.
- Health-Conscious Individuals:Proactive wellness seekers pursuing longitudinal biomarker tracking and preventive screening. This cohort drives subscription service adoption across United States employer wellness programs, motivated by tax-advantaged health savings account eligibility for preventive testing.
- Fitness Enthusiasts:Performance-optimizing consumers integrating continuous glucose monitors and recovery biomarkers with training regimens. Concentrated in urban fitness ecosystems, they demand wearable biometric convergence and real-time dashboard integration.
- Busy Professionals:Time-constrained buyers prioritizing convenience and telehealth result delivery.
- Families:Multi-user purchasers seeking pediatric nutritional screening and inherited condition carrier testing.
Revenue concentrates with Health-Conscious Individuals; expansion accelerates fastest among Fitness Enthusiasts.
Delivery Model:
Channel economics and customer acquisition costs structure competitive positioning, from high-lifetime-value subscriptions to transactional retail.
- Subscription Services:Recurring panel delivery with longitudinal tracking and physician-integrated result interpretation. Direct primary care practices and benefits administrators in United States markets negotiate annual contracts, creating concentrated procurement decisions and predictable revenue streams.
- Online Sales:Direct-to-consumer e-commerce with kit fulfillment and encrypted portal delivery. Health-conscious individuals drive volume through employer wellness program portals, where single-click enrollment reduces friction.
- Mobile App Integration:Platform-native ordering with wearable data synchronization and push notification result delivery.
- Retail Outlets:Physical pharmacy and big-box placement for impulse and gift purchases.
Margins favor Subscription Services; customer acquisition efficiency peaks with Online Sales.
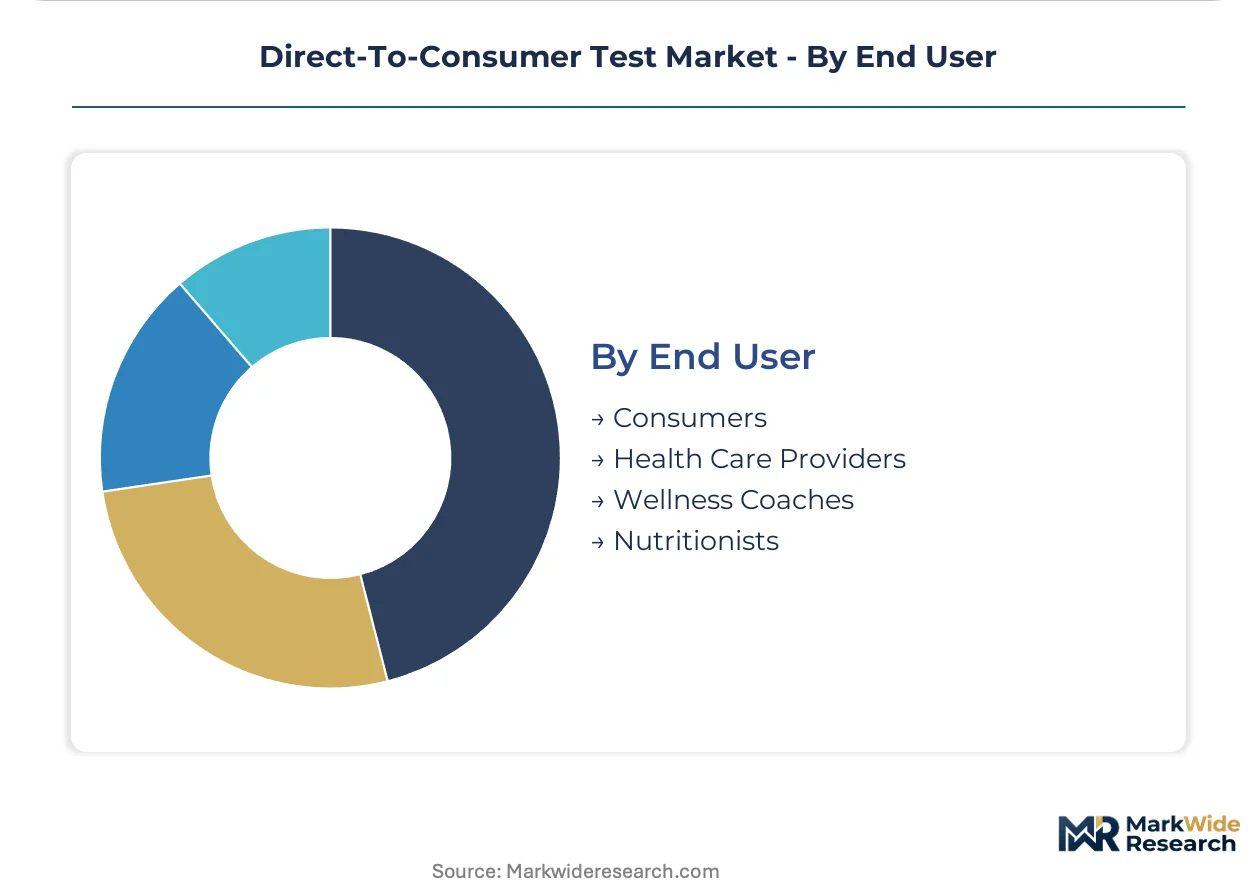
End User:
Decision authority and reimbursement pathway determine product design, from self-directed consumers to clinically integrated providers.
- Consumers:Self-purchasing individuals acting without physician intermediation. This population dominates nutritional analysis and lifestyle monitoring segments, attracted by HIPAA-compliant data architectures and telehealth-integrated result counseling.
- Health Care Providers:Physicians and nurse practitioners ordering panels for remote patient monitoring. United States direct primary care practices embed at-home testing into preventive protocols, requiring CLIA-certified laboratory partnerships and EHR interoperability.
- Wellness Coaches:Non-clinical practitioners integrating biomarker data into behavioral coaching protocols.
- Nutritionists:Registered dietitians prescribing metabolic panels for personalized dietary intervention.
Transaction volume flows through Consumers; clinical validation requirements intensify for Health Care Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley venture capital and Boston biotech corridors anchor the geographic concentration of direct-to-consumer test innovation. CLIA-certified laboratory networks cluster near major metropolitan demand pools. Regulatory fragmentation across national boundaries shapes market entry sequencing.
United States
FDA premarket review pathways and employer wellness program expansion drive commercial activity. HIPAA privacy requirements and state-level genetic privacy laws constrain data architecture design. The San Francisco Bay Area hosts 23andMe and Color Health, while Boston anchors Helix pharmacogenomics operations.
Germany
EMA medical device regulations and BfArM oversight of in-vitro diagnostics shape product registration timelines. GDPR data localization mandates compel server infrastructure investments. The Munich biotech corridor concentrates genetic testing platform development alongside Heidelberg laboratory automation specialists.
United Kingdom
NHS England primary care integration pilots and MHRA regulatory guidance accelerate clinical credibility building. Genetic counselor training programs at Manchester and Cambridge supply interpretive expertise. London fintech-biotech convergence supports subscription billing infrastructure for wellness platforms.
China
NMPA medical device classification rules and SAMR consumer protection enforcement govern market access. Dual carbon goals accelerate micro-sampling device adoption by eliminating cold chain emissions. Shenzhen hardware manufacturing clusters supply dried blood spot card production at scale.
Canada
Health Canada IVD licensing and provincial laboratory accreditation requirements structure market entry. Privacy Commissioner guidance on genetic data handling influences platform design. Toronto-Waterloo corridor health technology accelerators incubate at-home testing startups alongside established clinical laboratory networks.
Direct-To-Consumer Test Market Competitive Environment
Strategic partnerships dominate the current landscape as platform providers seek CLIA laboratory certification and telehealth integration capabilities. The vendor base stratifies across three tiers: ancestry-origin platforms pivoting toward health applications, clinical laboratory incumbents extending consumer-facing digital portals, and wellness-native subscription services. Archetypes include genetic data aggregators, laboratory infrastructure lessors, and algorithmic interpretation specialists. Portfolio diversification and geographic expansion represent the primary competitive vectors as players seek recurring revenue streams beyond one-time ancestry queries.
Within the genetic data aggregator tier, 23andMe, Inc. and Ancestry occupy positions exemplifying the pivot from ancestry toward pharmacogenomics and health risk applications. Everlywell, Inc. represents the wellness-native archetype through its certified laboratory partnership model. These three companies anchor the competitive structure without vertical integration into captive laboratory infrastructure, instead relying on distributed CLIA-certified processing networks that compress capital requirements while extending geographic reach.
| Leading Market Players |
|---|
| 23andMe, Inc. |
| Ancestry |
| Everlywell, Inc. |
| LetsGetChecked |
| Color Health, Inc. |
| Helix, Inc. |
| Labcorp |
| MyHeritage Ltd. |
| Quest Diagnostics Incorporated |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up laboratory networks anchor supply-side consolidation across the direct-to-consumer test market, compressing procurement costs while enabling subscription pricing discipline through captive CLIA-certified processing capacity. This ownership pattern feeds pricing power upstream to platform aggregators and downstream to employer wellness program administrators, who negotiate annual contracts based on guaranteed volume throughput rather than per-test spot pricing.
Pricing Analysis
Genetic counseling and telehealth result interpretation are unbundled from base kit pricing, creating service-tier differentiation that separates premium pharmacogenomic panels from commodity ancestry queries. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade—FDA-reviewed tests command 40-60% markups over laboratory-developed alternatives—and volume scale from employer benefits administrators. Cost compression in standard-tier health risk assessments is intensifying because direct primary care practices are consolidating procurement decisions. Health-conscious individuals in employer wellness programs show lowest price sensitivity; individual consumers purchasing one-time nutritional panels exhibit highest elasticity.
Supply Chain Analysis
Specialized stabilization chemistries for ambient shipping rest on concentrated North American and European specialty chemical producers, with dried blood spot card manufacturing clustered in United States and German industrial corridors. Micro-sampling device production draws from precision molding specialists in China and Switzerland, while CLIA-certified laboratory processing capacity concentrates in United States metropolitan markets. Single-source vulnerability in reagent supply creates exposure to regulatory restriction from FDA premarket review delays. Distribution runs through encrypted digital platforms with kit fulfillment via third-party logistics networks, bypassing traditional clinical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The direct-to-consumer test market is transitioning from one-time transactional ancestry queries to continuous biometric-integrated health monitoring, with pharmacogenomics and wearable data convergence displacing static genetic reports as the primary value proposition.
For Market Incumbents: To counter subscription churn from fitness-native entrants, 23andMe and Everlywell should deepen CLIA laboratory partnerships in United States direct primary care corridors while investing in FDA premarket review pathways for pharmacogenomic indications. Backward integration into proprietary stabilization chemistry reduces reagent supply risk. Channel control through employer wellness program portals locks in annual contract renewal rates. For New Entrants and Emerging Players: Enter via underpenetrated Medicare Advantage supplemental benefits channels, where CMS flexibility for home-based chronic disease monitoring creates reimbursable white space. Fitness enthusiasts in urban biometric-integrated ecosystems represent the most penetrable consumer segment. Go-to-market through wearable device OEM partnerships embeds testing into existing health optimization workflows. For Investors and Strategic Acquirers: FDA 510(k) clearance for pharmacogenomic drug-gene interaction panels is the leading indicator that clinical validation thresholds are crossing into reimbursable territory, signaling platform viability. Over a multi-year horizon, genetic data aggregators with HIPAA-compliant architectures and longitudinal consumer relationships present acquisition profiles distinct from commoditized wellness kit providers. Watch for state-level genetic privacy law preemption debates as the regulatory inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Partnership Expansion | Certified processing capacity in United States metropolitan markets compresses commercialization timelines for novel biomarkers. |
| Pharmacogenomic FDA Submission | Premarket review pathway completion unlocks employer wellness program reimbursement for medication management applications. |
| Wearable Biometric Platform Integration | Continuous glucose monitor and fitness tracker data feeds algorithmic nutritional analysis, creating stickier consumer relationships. |
| Direct Primary Care Channel Penetration | Membership-based practices in United States markets bypass traditional insurance authorization for preventive screening panels. |
| HIPAA-Compliant Data Architecture Investment | State-level genetic privacy law fragmentation compels localized storage and limits third-party sharing liability. |
Study Parameters
Independent corroboration across CLIA laboratory operations directors, employer benefits administrators, genetic counselors, and digital health platform executives underwrites the qualitative findings in this study. Primary interviews with these stakeholders were validated against FDA 510(k) filing databases, CMS Medicare Advantage supplemental benefits guidance, state genetic privacy statute compilations, and employer wellness program procurement records. Bottom-up test volume estimates from certified laboratory networks were triangulated against top-down consumer expenditure patterns from health savings account eligibility data.
Comparable-period anchoring to historical CLIA laboratory certification trends and employer wellness program adoption curves structured the forecast window across the analysis window. The analytical framework modeled product type segmentation—genetic tests, health risk assessments, nutritional analysis, lifestyle monitoring—alongside delivery model dimensions including subscription services, online sales, and mobile app integration. CAGRs were derived from longitudinal tracking of consumer uptake rates in employer wellness programs and direct primary care membership growth. Forecast inputs incorporated pharmacogenomic reimbursement expansion trajectories and micro-sampling device regulatory clearance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA premarket review pathway delays or state genetic privacy law fragmentation scenarios. Forecasts reflect assumptions regarding CLIA laboratory certification standardization and employer wellness program tax-advantaged eligibility continuity. Regulatory preemption debates, genetic counselor workforce scarcity, and wearable biometric data interoperability standards warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Argentina Alcohol E-Commerce Market
E-Commerce Solutions
Moldova E-Commerce Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
North America Automotive E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
UAE Ecommerce Market