
 B2B Travel Market | 2026-2036
B2B Travel Market Size, Share, and Industry Trends Forecast 2026-2036
B2B Travel Market Analysis
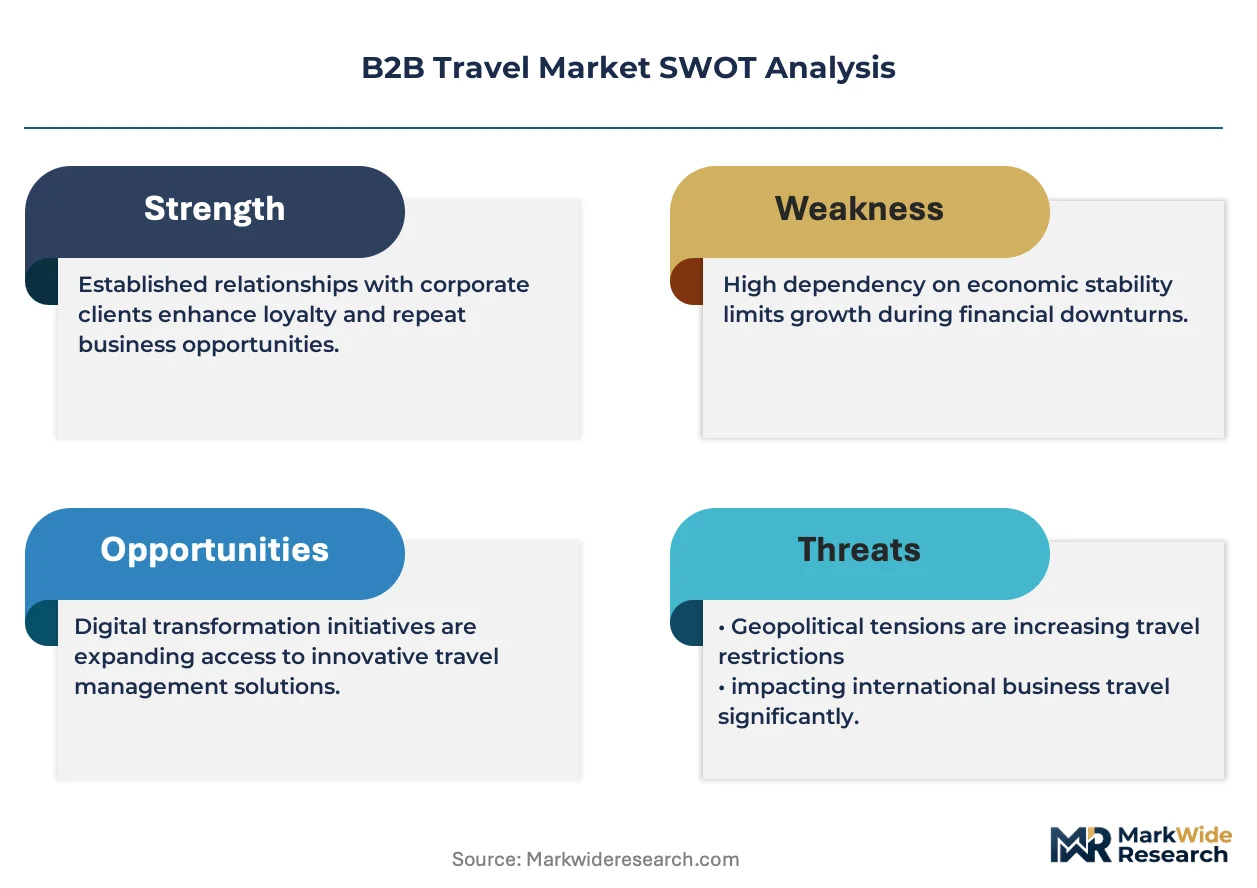
The EU Green Deal is pivoting corporate travel procurement toward emissions-accountable supplier selection. BCD Travel leverages its sustainability verification partnerships to anchor premium account retention. Amex GBT competes through centralized data infrastructure that captures scope-three travel emissions. Navan differentiates with real-time carbon offset integration at point of booking.
B2B travel encompasses the procurement, management, and optimization of business-related transportation, accommodation, and itinerary services purchased through contractual arrangements rather than consumer retail channels. The segment operates on negotiated rate structures, centralized billing protocols, and duty-of-care tracking systems designed to reduce enterprise travel expenditure while ensuring employee safety compliance. Corporate Travel dominates service type revenue due to recurring volume commitments from multinational accounts, while Online Booking Platforms capture the fastest expansion as self-service adoption displaces traditional agency intermediation. SMEs represent an underpenetrated customer type where automated expense-to-itinerary integration creates margin compression for legacy full-service models.
The EU Green Deal and REACH frameworks mandate emissions disclosure across supply chains, forcing travel management companies to certify hotel and aviation partners against verified carbon accounting standards. The US Securities and Exchange Commission's climate disclosure rules extend these requirements to American-domiciled corporations with European operations, creating cross-jurisdictional compliance complexity. China's MIIT dual carbon goals further shape multinational travel policy as Beijing-based headquarters impose domestic supplier preferences. Stakeholders must monitor regulatory fragmentation between voluntary carbon offset markets and mandatory disclosure regimes to avoid procurement lock-in with non-compliant vendors.
Market Dynamics
The EU Green Deal's scope-three emissions disclosure mandates are forcing procurement teams to requalify travel suppliers against verified carbon accounting standards, compressing legacy intermediaries that lack sustainability certification infrastructure.
Growth Catalysts
- CSRD Mandates:The EU's Corporate Sustainability Reporting Directive compels large enterprises to disclose business travel emissions, creating procurement pull for certified management platforms.
- API-First Integration:Real-time expense-to-itinerary synchronization is displacing manual reconciliation workflows in technology sector procurement teams.
- Mittelstand Consolidation:German mid-market firms are mandating centralized booking protocols, aggregating fragmented departmental spend into volume-committed contracts.
Market Restraints
- Aviation SAF Scarcity:Sustainable aviation fuel supply concentrates in Northwest European hubs, limiting emissions reduction claims for Asia-Pacific itineraries.
- Legacy GDS Lock-In:Global distribution system contracts impose multi-year switching costs that delay platform modernization for established corporate accounts.
- Carbon Offset Integrity Gaps:Voluntary offset markets lack standardization, exposing procurement teams to greenwashing liability under EU Green Deal enforcement.
Strategic Opportunities
- SME Automation White Space:Automated expense-to-itinerary integration remains underpenetrated among sub-500-employee firms in France and Italy.
- MIIT Dual Carbon Alignment:China's Ministry of Industry and Information Technology goals create demand for domestic supplier preference tools in Beijing-headquartered multinationals.
- Rail-Air Convergence:High-speed rail booking APIs integrating with aviation platforms capture regulatory tailwind from EU short-haul flight restrictions.
Industry Challenges
- Scope-Three Data Fragmentation:Procurement teams lack standardized methodologies to aggregate emissions across hotel, aviation, and ground transport suppliers.
- Legacy ERP Integration:SAP and Oracle travel modules require custom middleware development, extending implementation timelines for self-service platform adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B2B Travel Market |
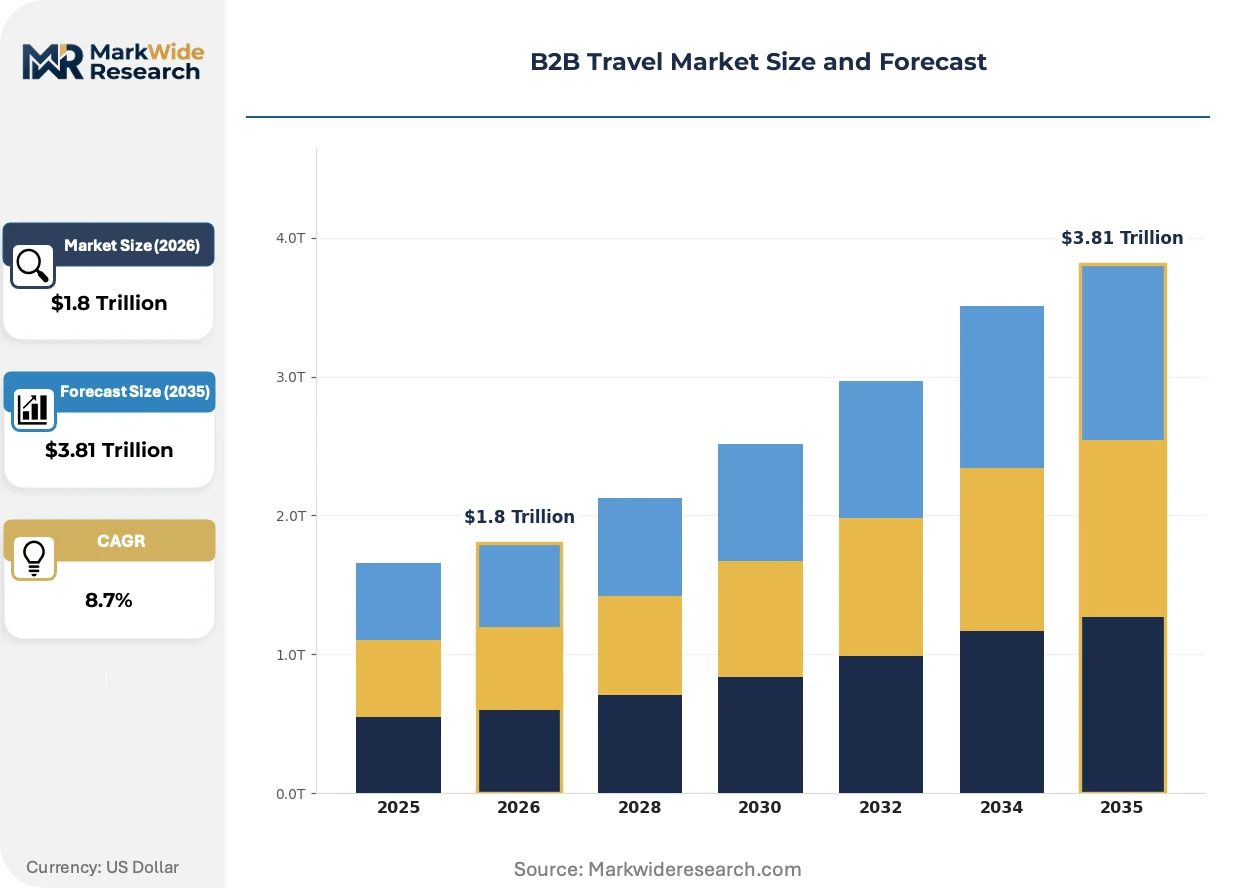
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $3.81 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Travel, Incentive Travel, Meeting Planning, Event Management Customer Type: SMEs, Large Enterprises, Government Agencies, Nonprofits Distribution Channel: Travel Agencies, Online Booking Platforms, Direct Sales, B2B Partnerships End User: Sales Teams, Executives, Project Managers, HR Professionals |
| Companies Covered | BCD Travel, SAP Concur, Navan, Brex, ITILITE, American Express Global Business Travel (Amex GBT), TravelPerk (Perk), Expedia Group, Routespring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B2B Travel Market Emerging Trajectories
Self-service booking platforms are compressing traditional agency intermediation through real-time policy enforcement and automated duty-of-care tracking. Three convergent forces are restructuring competitive positioning.
Embedded finance capabilities are unifying payment, reconciliation, and carbon accounting into single-workflow platforms. Technology sector procurement teams are adopting these tools fastest, displacing separate expense management and travel booking contracts. The structural consequence is margin compression for standalone corporate card providers and legacy TMCs lacking fintech infrastructure.
REACH and EU Green Deal frameworks mandate verified carbon accounting across supply chains. Industrial consequence: travel management companies must certify hotel and aviation partners against ISO 14064 standards or face procurement exclusion. German Mittelstand firms are responding fastest, embedding sustainability clauses into RFP scoring matrices.
Centralized booking mandates are displacing departmental self-procurement in European mid-market enterprises. Traditional agency relationships are being replaced by platform-based volume aggregation. This pattern concentrates most visibly in Germany, where works council agreements increasingly mandate pre-approved supplier lists with emissions disclosure requirements.
B2B Travel Market Segmentation
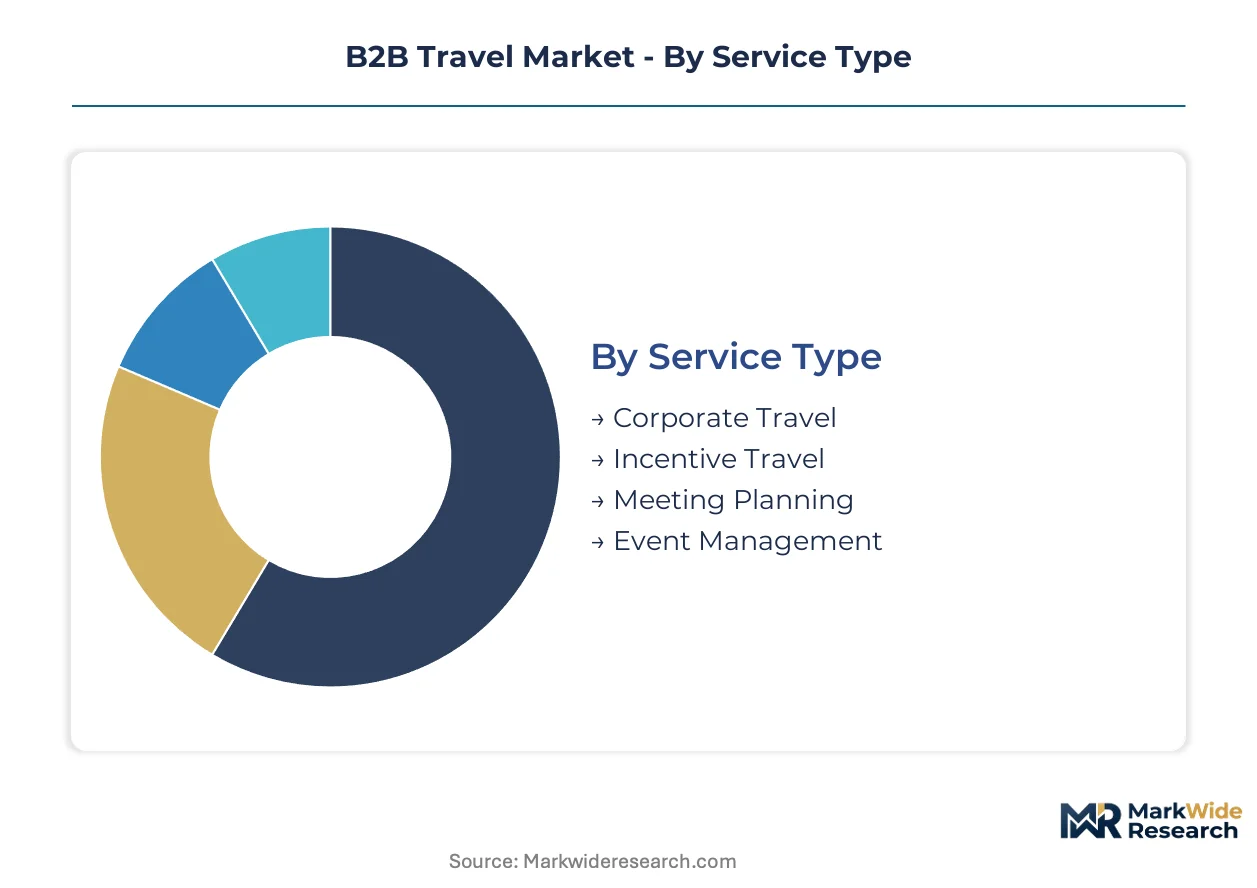
Procurement heterogeneity across the B2B Travel Market demands granular segmentation. Service configurations range from fully customized enterprise programs to standardized self-service platforms. Customer scale and regulatory exposure further stratify vendor selection criteria.
Service Type:
Customization intensity varies from negotiated multi-year corporate contracts to modular event components.
- Corporate Travel:Encompasses recurring transportation, accommodation, and itinerary management under centralized billing protocols. Volume concentrates among technology sector procurement teams seeking API-first expense integration. The segment anchors revenue through multinational account retention.
- Incentive Travel:Reward-based group programs combining destination experiences with performance recognition. Demand clusters in German Mittelstand firms consolidating departmental spend through works council-mandated supplier lists. REACH compliance requirements now embed sustainability scoring into RFP evaluation.
- Meeting Planning:Logistics coordination for internal gatherings and client presentations.
- Event Management:Large-scale conference and exhibition execution with vendor orchestration.
Most installed capacity flows through Corporate Travel. Expansion is steepest in Online Booking Platforms.
Customer Type:
Account scale determines service model economics and platform investment thresholds.
- Large Enterprises:Multinational accounts with centralized procurement functions and duty-of-care mandates. German industrial conglomerates and Beijing-headquartered multinationals drive demand for emissions-accountable supplier certification under CSRD and MIIT dual carbon frameworks.
- SMEs:Sub-500-employee firms with fragmented departmental booking patterns. Automated expense-to-itinerary integration remains underpenetrated in France and Italy, creating margin compression for legacy full-service intermediaries lacking self-service infrastructure.
- Government Agencies:Public sector accounts with compliance-heavy procurement protocols.
- Nonprofits:Budget-constrained organizations prioritizing cost transparency over service breadth.
Revenue concentration sits with Large Enterprises. SMEs are gaining share fastest through platform democratization.
Distribution Channel:
Channel selection reflects trade-offs between human advisory depth and workflow automation.
- Online Booking Platforms:Self-service interfaces with real-time policy enforcement and carbon offset integration at point of booking. Technology sector procurement teams adopt these tools fastest, displacing separate expense management contracts and compressing margins for standalone corporate card providers.
- Travel Agencies:Full-service intermediation with negotiated rate access and duty-of-care tracking. Legacy GDS lock-in imposes multi-year switching costs that delay platform modernization for established accounts.
- Direct Sales:Supplier-procured arrangements bypassing intermediary markups.
- B2B Partnerships:Embedded travel modules within enterprise software ecosystems.
Transaction volume concentrates in Online Booking Platforms. Travel Agencies retain highest value-per-booking.
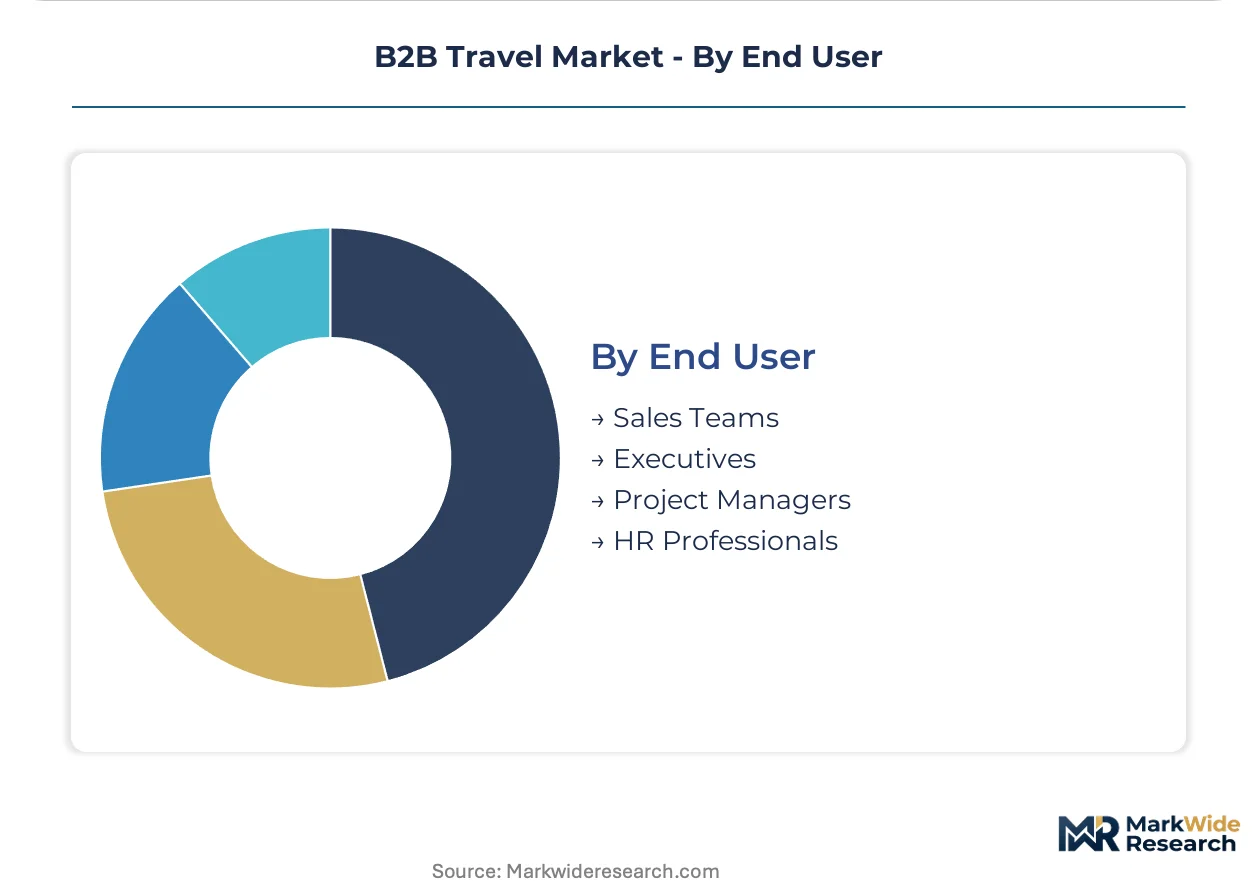
End User:
Functional role shapes itinerary complexity, policy latitude, and duty-of-care requirements.
- Executives:C-suite travelers requiring flexible cancellation terms and premium service tiers. German Mittelstand firms increasingly mandate pre-approved supplier lists with emissions disclosure for this cohort.
- Sales Teams:High-frequency road warriors with unpredictable routing needs. Real-time itinerary synchronization and automated expense reconciliation rank as priority platform capabilities.
- Project Managers:Extended-stay specialists with accommodation-heavy spend profiles.
- HR Professionals:Group travel organizers managing recruitment and training mobility.
Policy enforcement complexity peaks with Executives. Sales Teams generate highest booking frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology sector procurement talent clusters in Germany, the United States, and China anchor platform adoption patterns. Corporate travel management demand concentrates where emissions disclosure mandates intersect with centralized booking infrastructure.
United States
Technology sector procurement teams in Seattle and San Francisco drive API-first platform adoption. The SEC's climate disclosure rules extend EU-style emissions reporting requirements to American-domiciled corporations with European operations. Boston-based financial services firms are consolidating separate expense management and travel booking contracts into unified workflows.
Germany
Mittelstand firms in Bavaria and North Rhine-Westphalia mandate centralized booking protocols through works council agreements. The EU Green Deal's CSRD framework compels emissions-accountable supplier selection in RFP scoring matrices. Frankfurt's financial district anchors premium corporate travel volume committed to certified management platforms.
China
Beijing-headquartered multinationals impose domestic supplier preferences aligned with MIIT dual carbon goals. The Ministry of Industry and Information Technology's emissions targets shape procurement policy for state-affiliated enterprises. Shanghai's technology corridor concentrates demand for integrated expense-to-itinerary automation.
United Kingdom
London's professional services sector generates concentrated demand for duty-of-care tracking and flexible cancellation terms. The UK's adoption of CSRD-aligned disclosure standards forces requalification of hotel and aviation partners. Manchester and Birmingham mid-market firms are displacing departmental self-procurement with platform-based volume aggregation.
India
Technology sector procurement teams in Bangalore and Hyderabad adopt self-service platforms fastest among Asia-Pacific markets. The country's central bank guidelines on corporate travel expenditure create compliance pull for centralized billing protocols. Mumbai's financial services cluster drives premium account retention through negotiated rate structures.
B2B Travel Market Vendor Landscape
Capital-heavy legacy travel management companies compete with asset-light platform designers for procurement team relationships. The vendor base stratifies across three tiers: full-service intermediaries with GDS infrastructure, API-first self-service platforms, and embedded fintech hybrids. Strategic archetypes include sustainability-certified account anchors, real-time policy enforcers, and expense-to-itinerary integrators. Dominant competitive moves encompass strategic partnerships with carbon accounting providers and portfolio diversification into SME automation tools.
Within the sustainability-certified tier, BCD Travel and American Express Global Business Travel exemplify legacy intermediaries pivoting toward emissions verification partnerships. Navan occupies a position among asset-light platform designers integrating real-time carbon offset capabilities at point of booking. SAP Concur anchors the embedded finance archetype unifying payment, reconciliation, and travel workflow into single-platform infrastructure.
| Leading Market Players |
|---|
| BCD Travel |
| SAP Concur |
| Navan |
| Brex |
| ITILITE |
| American Express Global Business Travel (Amex GBT) |
| TravelPerk (Perk) |
| Expedia Group |
| Routespring |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up travel management specialists anchor supply consolidation across fragmented agency networks, compressing intermediary margins while enforcing volume-based pricing discipline on multinational accounts. This ownership pattern concentrates supplier negotiating leverage in Germany and the United States, where procurement teams extract preferential rate structures through committed spend thresholds.
Pricing Analysis
Bundled subscription platforms commanding per-seat SaaS fees separate from unbundled transactional agency commissions that capture percentage-based booking markups. Three-tier pricing structure across premium concierge, standard managed, and economy self-service levels reflects certification intensity and duty-of-care depth. Cost compression in the economy tier is intensifying because API-first entrants displace legacy GDS-dependent intermediaries with automated policy enforcement. SME procurement teams exhibit highest price sensitivity, while German Mittelstand firms prioritize emissions-accountable supplier certification over rate minimization.
Supply Chain Analysis
Direct-to-multinational channels handle hyperscale buyer demand through dedicated account teams and customized rate negotiations, while indirect agency networks serve fragmented SME demand. Distribution runs through Ireland and Netherlands for European corporate travel platform hosting, with customer service operations concentrated in India and the Philippines. Raw material dependencies include aviation seat inventory from IATA-member carriers, hotel block allocations from property management systems, and carbon offset credits from voluntary market registries. Single-source vulnerability in sustainable aviation fuel supply concentrates procurement risk for EU Green Deal-compliant itineraries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement teams requalify suppliers against verified carbon accounting standards, elevating certified platforms above rate-competitive alternatives. Demand is shifting toward premium specifications embedding real-time emissions disclosure and automated duty-of-care tracking.
For Market Incumbents: Anchor account retention through sustainability verification partnerships with ISO 14064-accredited carbon accounting providers. Deepen backward integration into expense-to-itinerary API infrastructure to defend against fintech platform displacement. Certification investment in REACH-compliant hotel and aviation partner networks represents the critical defensive lever against procurement exclusion under CSRD enforcement. For New Entrants and Emerging Players: Real-time carbon offset integration at point of booking offers a technology-first wedge into the underpenetrated French and Italian SME automation white space. Target sub-500-employee firms lacking centralized booking mandates with modular expense-to-itinerary tools that displace separate corporate card contracts. A channel partnership with ERP providers like SAP and Oracle accelerates enterprise penetration despite legacy module integration friction. For Investors and Strategic Acquirers: Embedded fintech platforms unifying payment, reconciliation, and travel workflow are the most active acquirer category in this space, consolidating standalone expense management and booking tools into single-infrastructure propositions. Acquisition target archetypes include API-first self-service platforms with proven MIIT dual carbon alignment for Beijing-headquartered multinational access. The signal to monitor is works council adoption of centralized booking mandates across German Mittelstand firms as inflection indicator for platform volume aggregation.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Certification | ISO 14064 verification anchors premium account retention under EU Green Deal procurement rules. |
| API-First Platform Integration | Real-time expense-to-itinerary synchronization displaces manual reconciliation in technology sector procurement. |
| Sustainability Partnership Expansion | Verified offset provider alliances protect against greenwashing liability under REACH enforcement. |
| SME Automation Tools | Self-service infrastructure captures fragmented departmental spend in France and Italy mid-market. |
| Rail-Air Convergence Development | High-speed rail booking APIs capture regulatory tailwind from EU short-haul flight restrictions. |
Methodological Framework
Direct dialogue with corporate procurement officers, travel management company account directors, sustainability certification auditors, and ERP integration specialists grounded the qualitative foundation of this study. Secondary validation drew from EU CSRD disclosure filings, SEC climate rule comment letters, MIIT dual carbon policy documents, and IATA airline industry data. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation outputs across service type, customer scale, distribution channel, and end-user functional role structured the analytical framework throughout the projection horizon. CAGRs derived from volume commitment trends in multinational accounts and platform adoption curves in SME automation white space. Forecast inputs incorporated aviation SAF supply constraints, works council mandate diffusion rates, and API integration timeline assumptions.
The model holds under sustained emissions disclosure regulatory expansion; deviation in carbon offset market standardization or legacy GDS contract renewal patterns would shift platform migration timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Surfing Tourism Market
Travel and Tourism
India Outbound Tourism Market
Travel and Tourism
Pet Travel Services Market
Travel and Tourism
Hong Kong Outbound Tourism Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
Tourism Market
Travel and Tourism
North America Travel Retail Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
Global Golf Travel Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
Asia-Pacific Travel Retail Market