
 Global Exhibition Organizing Market | 2026-2036
Global Exhibition Organizing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exhibition Organizing Market Foresight
Modular stand packages is restructuring buyer procurement across the exhibition organizing value chain. Informa leverages its portfolio breadth to anchor multi-industry show calendars across North America and Europe. Messe Frankfurt sustains dominance in capital-goods verticals through captive venue ownership and destination infrastructure control.
Exhibition organizing encompasses the end-to-end planning, coordination, and execution of temporary commercial gatherings, incorporating spatial design, attendee registration systems, vendor logistics, and on-site technical services with typical build cycles of 3-6 months for major shows. Trade shows within the Event Type category occupy the deepest margin pools due to multi-year exhibitor contracts and premium sponsorship tiers, while Conferences represent the fastest-expanding segment as knowledge-economy sectors prioritize delegate monetization over floor space. The Service Offering dimension concentrates value in Event Design and Logistics Coordination, where specialized labor scarcity protects pricing power against commoditized venue sourcing.
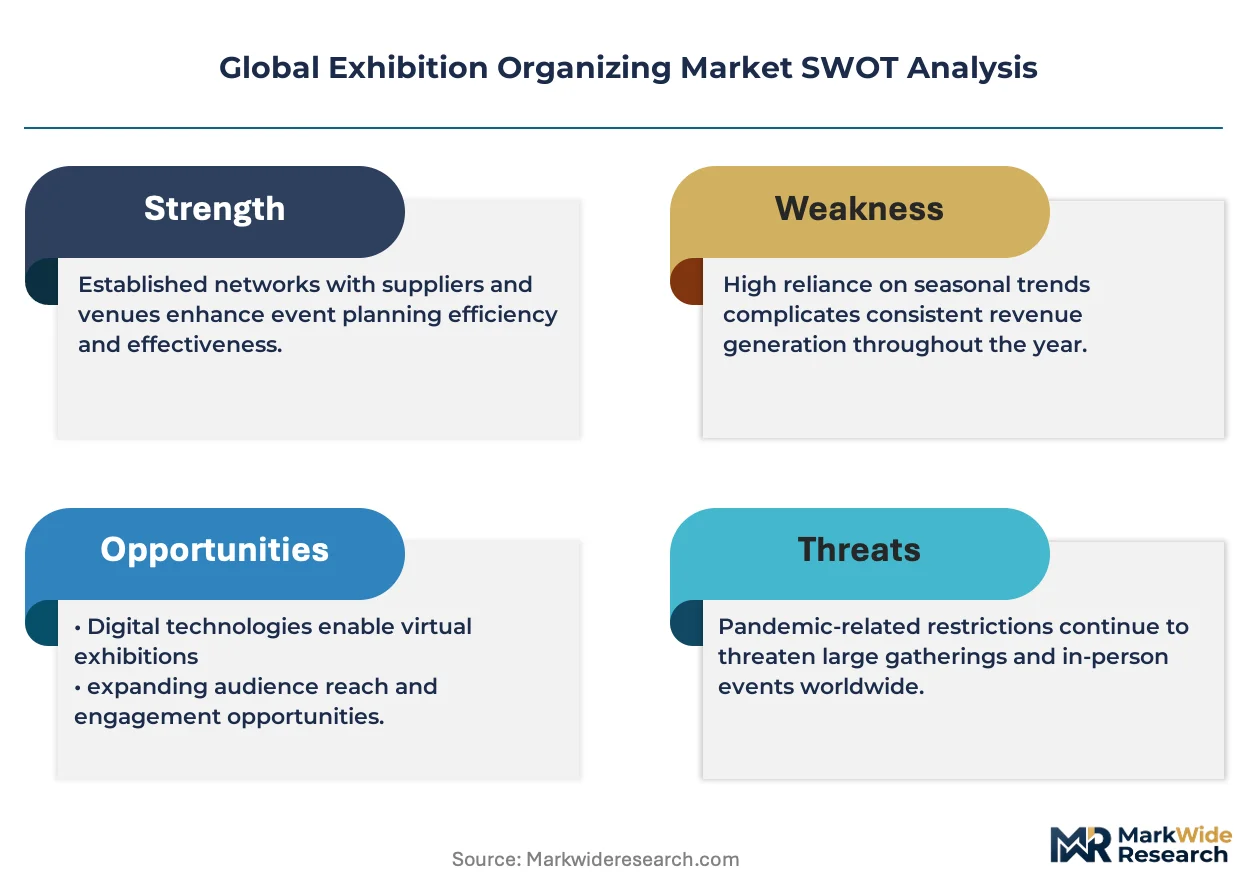
Germany's MEE enforces emissions thresholds for temporary structures, while the EU Green Deal mandates carbon disclosure for publicly supported events, pushing organizers toward renewable energy contracting and waste-reduction protocols. The UAE's MOHAP coordinates health-and-safety standards for international medical congresses, creating compliance gateways for pharmaceutical-focused operators. Stakeholders must weigh venue decarbonization investments against hybrid-format cost structures as regulatory baselines tighten across jurisdictions.
Market Dynamics
Hybrid event infrastructure is rewriting capital allocation across the exhibition organizing value chain, forcing organizers to maintain dual physical-digital capabilities while venue operators retrofit legacy halls with broadcast-grade connectivity.
Growth Catalysts
- Pharmaceutical congress expansion:Specialized medical gatherings in the UAE draw increasing sponsor investment as MOHAP streamlines international health-and-safety protocols for large-scale clinical gatherings.
- EU Green Deal carbon disclosure:Mandates for publicly supported events accelerate renewable energy contracting and waste-reduction investments among European venue operators.
- RFID and biometric credentialing:Contactless attendee tracking systems reduce on-site staffing requirements while generating granular behavioral data for exhibitor monetization.
Market Restraints
- Skilled labor scarcity in event design:Specialized spatial designers and logistics coordinators command premium rates, compressing margins for mid-tier organizers without captive talent pools.
- Aluminum and composite material volatility:Stand construction costs fluctuate with raw material indices, complicating fixed-price contracting for multi-year exhibitor agreements.
- Single-venue dependency in secondary cities:Concentrated supply of purpose-built exhibition space in Manchester, Birmingham, and Lyon limits competitive venue selection for regional show organizers.
Strategic Opportunities
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea developments create demand for inaugural trade events in construction, renewable energy, and hospitality verticals.
- India's PLI scheme spillover:Manufacturing incentives in electronics and pharmaceuticals generate exhibitor bases seeking domestic component sourcing platforms.
- AI-powered matchmaking convergence:Natural language processing and predictive analytics combine to automate buyer-seller scheduling, reducing manual pre-event coordination.
Industry Challenges
- Legacy CRM integration with hybrid platforms:Decades-old exhibitor databases resist seamless connection to virtual event APIs, requiring costly middleware development.
- Certification timelines for temporary structures:Germany's MEE emissions compliance and UAE civil defense approvals extend build cycles, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exhibition Organizing Market |
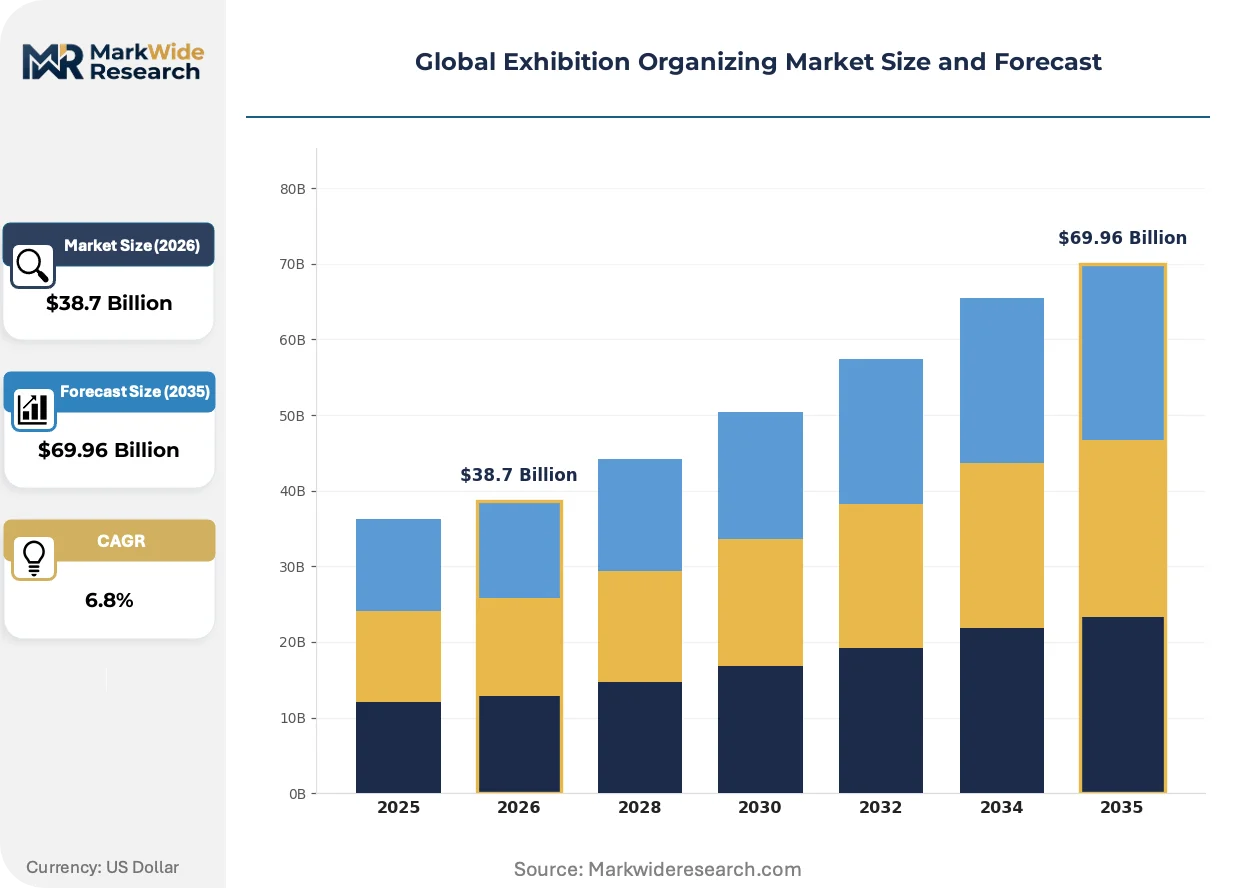
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Trade Shows, Conferences, Product Launches, Corporate Meetings, Roadshows Service Offering: Venue Selection, Event Design, Marketing & Promotions, Registration Management, Logistics Coordination Client Industry: Technology, Pharmaceuticals, Manufacturing, Consumer Goods, Finance Sales Channel: Direct Sales, Online Platforms, Agency Partnerships, Referral Networks |
| Companies Covered | Informa, RX, Messe Frankfurt, Clarion Events, Hyve, dmg events, NürnbergMesse, Easyfairs, CloserStill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exhibition Organizing Market Shifts & Advancements
Digital twin technology and generative design tools are compressing spatial planning cycles while sustainability mandates force material specification changes across temporary construction.
Spatial computing platforms are rewriting how pharmaceutical exhibitors prototype booth experiences before physical build. Medical congress organizers in Basel and Boston deploy virtual reality walkthroughs to secure sponsor commitments six months ahead of construction. This capability collapses the traditional design revision cycle from eight weeks to seventy-two hours.
REACH substance restrictions and the EU Green Deal's carbon disclosure rules are eliminating solvent-based adhesives and non-recyclable carpeting from European temporary structures. German venue operators now mandate renewable energy certificates for all contracted stand builders. Messe Frankfurt's captive energy infrastructure gives it compliance advantages over rental-hall competitors.
Subscription-based exhibitor relationships are displacing transactional per-show contracts in knowledge-economy verticals. Software and professional services firms in London and Singapore prefer annual participation packages with guaranteed floor positions across multiple industry calendars. This shift concentrates buyer power with portfolio-owning organizers and marginalizes single-event specialists.
Global Exhibition Organizing Market Segmentation
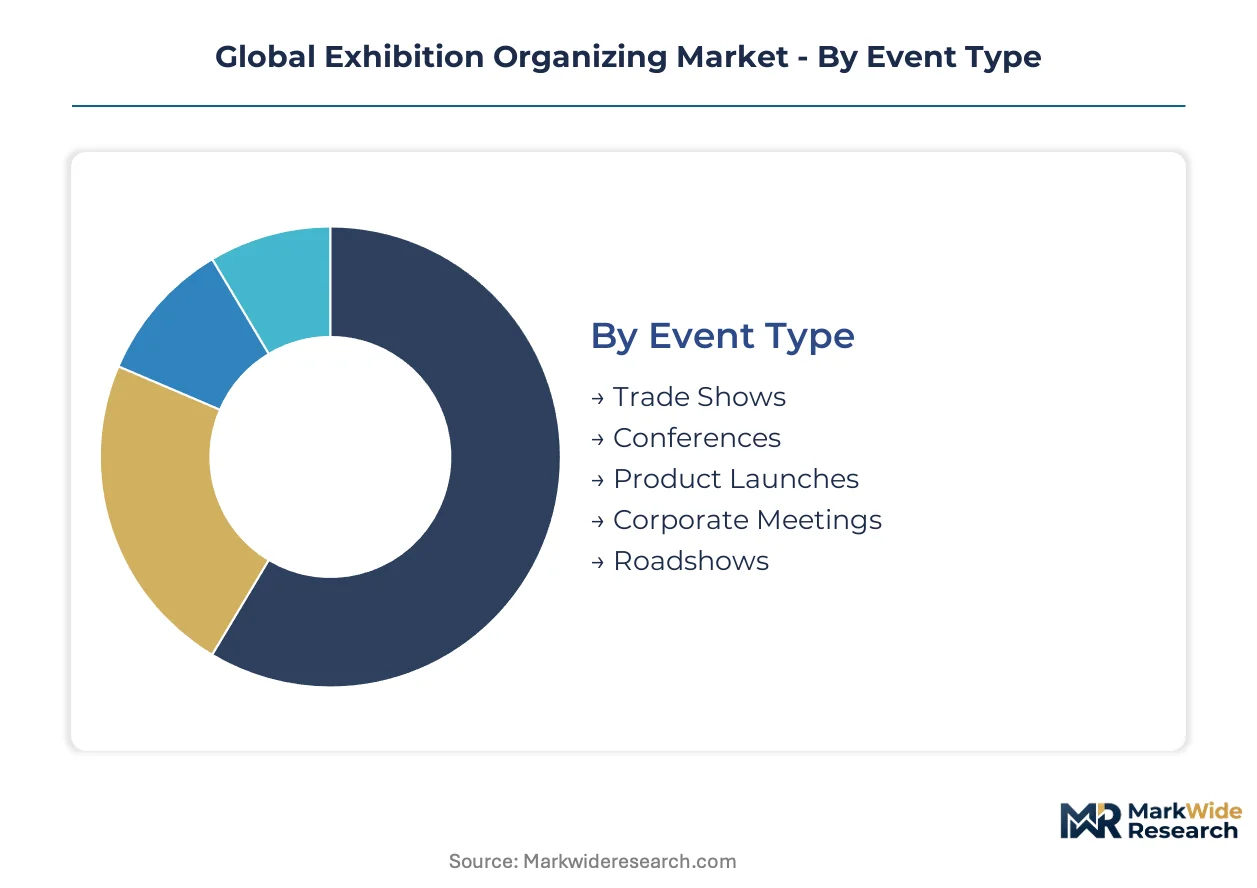
Segmentation in exhibition organizing reveals how procurement priorities diverge across buyer archetypes. Pharmaceutical sponsors prioritize compliance infrastructure while technology exhibitors demand hybrid broadcast capabilities. Understanding these fault lines exposes where margin pools concentrate and which service bundles command pricing power.
Event Type:
Buyers in this category separate by contract duration and sponsorship depth rather than attendance scale alone.
- Trade Shows:Multi-year exhibitor contracts with premium sponsorship tiers generate the deepest margin pools. Floor space monetization dominates revenue models in capital-goods verticals across Germany and the UAE.
- Conferences:Delegate monetization through registration fees and knowledge content is displacing floor space as the primary revenue driver. Knowledge-economy sectors in Basel and Boston prioritize this format for pharmaceutical and software verticals.
- Product Launches:Single-use experiential builds with compressed 4-8 week cycles. Technology firms in Singapore and London favor immersive reveals with broadcast distribution.
- Corporate Meetings:Recurring internal gatherings with standardized procurement. Financial services firms in New York and Frankfurt drive volume through annual calendar commitments.
- Roadshows:Mobile formats requiring modular infrastructure and rapid city-to-city redeployment. Consumer goods brands use these for market testing across secondary cities in India and Brazil.
Trade Shows lead volumes today; Conferences are gaining share fastest.
Service Offering:
Margin protection in this category tracks labor scarcity and technical specialization rather than asset ownership.
- Event Design:Spatial designers and experiential architects command premium rates due to specialized labor scarcity. Pharmaceutical exhibitors in Basel and Boston deploy virtual reality walkthroughs to secure sponsor commitments six months ahead of physical construction.
- Logistics Coordination:Vendor synchronization, customs brokerage, and on-site technical services with typical build cycles of 3-6 months for major shows. Complex temporary structures in Germany face MEE emissions compliance extensions that compress revenue recognition windows.
- Venue Selection:Sourced capacity with location analysis and contract negotiation. Dubai's mega-venue investments attract international show organizers seeking scale.
- Marketing & Promotions:Attendee acquisition and exhibitor lead generation through digital and traditional channels. Hybrid event platforms are rewriting capital allocation toward dual physical-digital capabilities.
- Registration Management:Credentialing systems and attendee database administration. RFID and biometric systems reduce on-site staffing while generating behavioral data for exhibitor monetization.
Event Design captures the highest margins today; Logistics Coordination is expanding most quickly as regulatory complexity deepens.
Client Industry:
Compliance requirements and procurement sophistication create tiered buyer power in this category.
- Pharmaceuticals:Specialized medical congresses with MOHAP health-and-safety protocols in the UAE and EMA-aligned standards in Europe. Sponsor investment concentrates here due to regulatory gateway requirements.
- Technology:Software and hardware firms demanding hybrid broadcast infrastructure and AI-powered matchmaking. Subscription-based annual participation packages are displacing transactional per-show contracts in London and Singapore.
- Manufacturing:Capital-goods exhibitors with multi-year show calendars anchored by portfolio-owning organizers. India's PLI scheme spillover in electronics and pharmaceuticals generates exhibitor bases seeking domestic component sourcing platforms.
- Consumer Goods:Brand activation and retail buyer engagement with rapid format testing. Roadshow mobility suits market penetration strategies in secondary cities.
- Finance:Regulatory-heavy gatherings with standardized procurement and recurring internal calendars. Professional services firms prefer guaranteed floor positions across multiple industry calendars.
Pharmaceuticals dominates sponsor spend today; Technology is climbing the fastest as hybrid infrastructure investments accelerate.
Sales Channel:
Channel selection in this category reflects buyer scale and relationship maturity rather than cost efficiency alone.
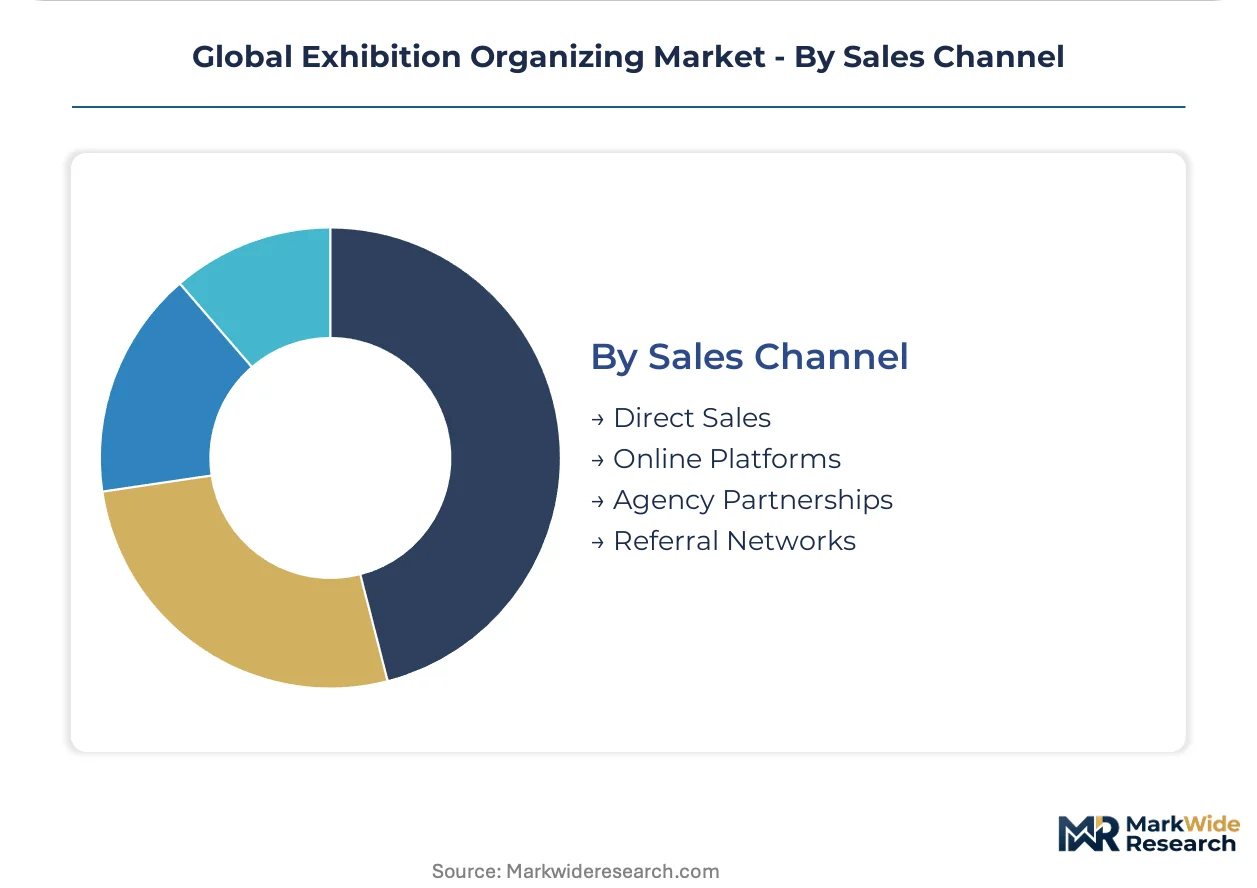
- Direct Sales:Enterprise relationships with multi-year calendar commitments and customized service bundling. Portfolio-owning organizers concentrate buyer power through captive account management teams.
- Agency Partnerships:Third-party representation for geographic expansion and vertical specialization. Regional show organizers in Manchester and Lyon leverage these to overcome single-venue dependency constraints.
- Online Platforms:Self-service booking for standardized packages and modular stand configurations. Mid-tier exhibitors without captive talent pools use these to compress procurement cycles.
- Referral Networks:Industry association and peer recommendation channels with trust-based conversion. Professional services verticals in knowledge-economy clusters favor these for calendar continuity.
Direct Sales leads contract value today; Online Platforms are gaining share fastest as modular procurement patterns spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern exhibition industry traces its commercial roots to Leipzig's medieval trade fairs and the industrial-era bourse halls of London and Chicago. These historical centers established the venue ownership models and multi-year exhibitor contracts that persist across today's organizing landscape.
Germany
Messe Frankfurt and NürnbergMesse anchor capital-goods show calendars through captive venue ownership across Hesse and Bavaria. The MEE enforces emissions thresholds for temporary structures, extending build cycles for large-scale industrial gatherings. Frankfurt's exhibition grounds leverage integrated renewable energy infrastructure to meet EU Green Deal disclosure requirements faster than rental-hall competitors.
United States
Informa anchors multi-industry portfolios across Las Vegas, Chicago, and Orlando convention corridors. OSHA workplace safety standards and state-level building codes create compliance layering for temporary structures. Chicago's McCormick Place and Las Vegas Sands Expo concentrate pharmaceutical and technology show volumes through integrated broadcast infrastructure.
United Arab Emirates
Dubai World Trade Centre and Expo City infrastructure attract international medical congresses and construction trade events. MOHAP coordinates health-and-safety standards for pharmaceutical gatherings, creating regulatory gateways that concentrate sponsor investment. The emirate's mega-venue investments position it as the primary Gulf hub for inaugural trade events tied to Saudi giga-projects.
United Kingdom
Hyve and Clarion Events operate across London Olympia, Birmingham NEC, and Manchester Central with hybrid-format capabilities. The UK's Building Regulations and HSE event safety guidance impose certification timelines for temporary structures. London's knowledge-economy clusters drive subscription-based annual participation packages in software and professional services verticals.
India
PLI scheme spillover in electronics and pharmaceuticals generates exhibitor bases seeking domestic component sourcing platforms. BIS standards for temporary electrical installations and state-level fire safety codes create compliance variation across Maharashtra and Gujarat. Mumbai and Bangalore convention centers capture manufacturing-focused show volumes as industrial policy reshapes supply chain geography.
Global Exhibition Organizing Market Competitive Landscape
The competitive structure tilts toward portfolio-owning conglomerates with captive venue assets. Market concentration splits between multi-vertical calendar operators and single-industry specialists, with mid-tier regional players facing margin compression from labor scarcity and material volatility. Three archetypes dominate: integrated venue-owners, hybrid-platform developers, and vertical-specific community builders. Consolidation through venue acquisition and technology licensing partnerships represent the primary competitive vectors reshaping participant economics.
Within the integrated venue-owner archetype, Messe Frankfurt exemplifies captive infrastructure control through its Frankfurt and Hamburg assets, while Informa occupies a position spanning North American and European calendar density. dmg events anchors Middle East and Africa expansion through Dubai-based operations. These three represent distinct geographic and vertical strategies without overlapping core markets.
| Leading Market Players |
|---|
| Informa |
| RX |
| Messe Frankfurt |
| Clarion Events |
| Hyve |
| dmg events |
| NürnbergMesse |
| Easyfairs |
| CloserStill |
| Others |
Supply & Pricing Matrix
Hybrid event infrastructure deployment is simultaneously inflating fixed cost bases and concentrating procurement power with venue-owning conglomerates capable of amortizing broadcast-grade connectivity investments across multi-year exhibitor contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with differentiation driven by sustainability certification grade and bundled hybrid broadcast capabilities. Cost compression in mid-tier packages is intensifying because aluminum and composite material volatility complicates fixed-price contracting. Pharmaceutical sponsors show lowest price sensitivity due to regulatory gateway requirements, while consumer goods exhibitors in secondary cities face acute budget constraints.
Supply Chain Analysis
Freight cost escalation for modular stand components is reshaping geographic sourcing patterns across the exhibition organizing value chain. Supply concentrates in Germany, China, and the UAE for specialized temporary structures and broadcast equipment. Raw material dependencies span aluminum extrusions, composite panels, and LED display arrays. Single-source vulnerability in certified sustainable materials creates structural risk. Distribution runs through captive venue operator networks and third-party logistics coordinators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward premium specifications as EU Green Deal carbon disclosure mandates eliminate non-compliant operators.
For Market Incumbents: Lock in multi-year exhibitor relationships through subscription-based annual participation packages before emerging hybrid-platform specialists capture pharmaceutical sponsor budgets. Prioritize captive renewable energy infrastructure investments to defend margin position against rental-hall competitors facing MEE compliance cost inflation. For New Entrants and Emerging Players: Capture inaugural trade event contracts tied to Saudi Arabia's NEOM and Red Sea giga-projects where incumbent venue operators lack established presence. India's PLI scheme spillover in electronics and pharmaceuticals offers the most penetrable exhibitor base for domestic component sourcing platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among regional show organizers in Manchester, Birmingham, and Lyon facing single-venue dependency constraints. Long-term viability hinges on portfolio consolidation into multi-vertical calendar operators. Watch AI-powered matchmaking adoption rates as the signal indicating which hybrid-platform investments will generate sustainable returns.| Strategic Initiative | Industry Significance |
|---|---|
| Venue Renewable Energy Infrastructure | Messe Frankfurt's captive energy assets accelerate EU Green Deal compliance faster than rental competitors. |
| Hybrid Broadcast Platform Integration | Dual physical-digital capabilities capture pharmaceutical sponsor investment at Basel and Boston congresses. |
| AI-Powered Matchmaking Deployment | Natural language processing automation reduces manual pre-event coordination costs for technology exhibitors. |
| Subscription-Based Exhibitor Contracts | Annual participation packages concentrate buyer power with portfolio-owning organizers in London and Singapore. |
| Saudi Giga-Project Event Anchoring | NEOM and Red Sea developments create demand for construction and renewable energy trade events. |
Research Methodology
Coverage spans North America, Europe, Middle East, and Asia-Pacific, with primary inputs from each region combining interviews with exhibition organizers, venue operators, pharmaceutical sponsor procurement leads, and stand construction specialists. Secondary validation draws from SEC filings of listed event companies, EU regulatory disclosure databases, UAE MOHAP congress registration records, and trade association membership data. Bottom-up exhibitor spend analysis and top-down industry revenue triangulation anchor the quantitative framework.
Granularity-level modeling spans Event Type, Service Offering, Client Industry, and Sales Channel dimensions across the analysis window. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporate pharmaceutical congress expansion trajectories, hybrid infrastructure deployment curves, and regulatory compliance timeline acceleration under EU Green Deal and Germany's MEE frameworks.
Raw material cost volatility, regulatory certification timeline extensions, and hybrid platform adoption rate divergence are the dominant revision risks to projection assumptions. Stakeholders should weight assumptions against their own operating context and captive infrastructure position.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Europe Discount Events and Experiences Market
Events and Conferences
UAE Event Management Market
Events and Conferences
Italy Event Services Market
Events and Conferences
Corporate Event Market
Events and Conferences
GCC Event Management Market
Events and Conferences
Saudi Arabia Event Services Market
Events and Conferences
Japan Wedding Services Market
Events and Conferences
Canada Wedding Services Market
Events and Conferences
Trade Show Services Market
Events and Conferences
MICE Market
Events and Conferences
Event Management Solutions Market
Events and Conferences
Corporate Event Planner Market
Events and Conferences
Mexico Event Services Market
Events and Conferences
India B2B Events Market
Events and Conferences
Spain Event Services Market
Events and Conferences
France Event Services Market