
 Europe Business Travel Market | 2026-2036
Europe Business Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Business Travel Market Intelligence
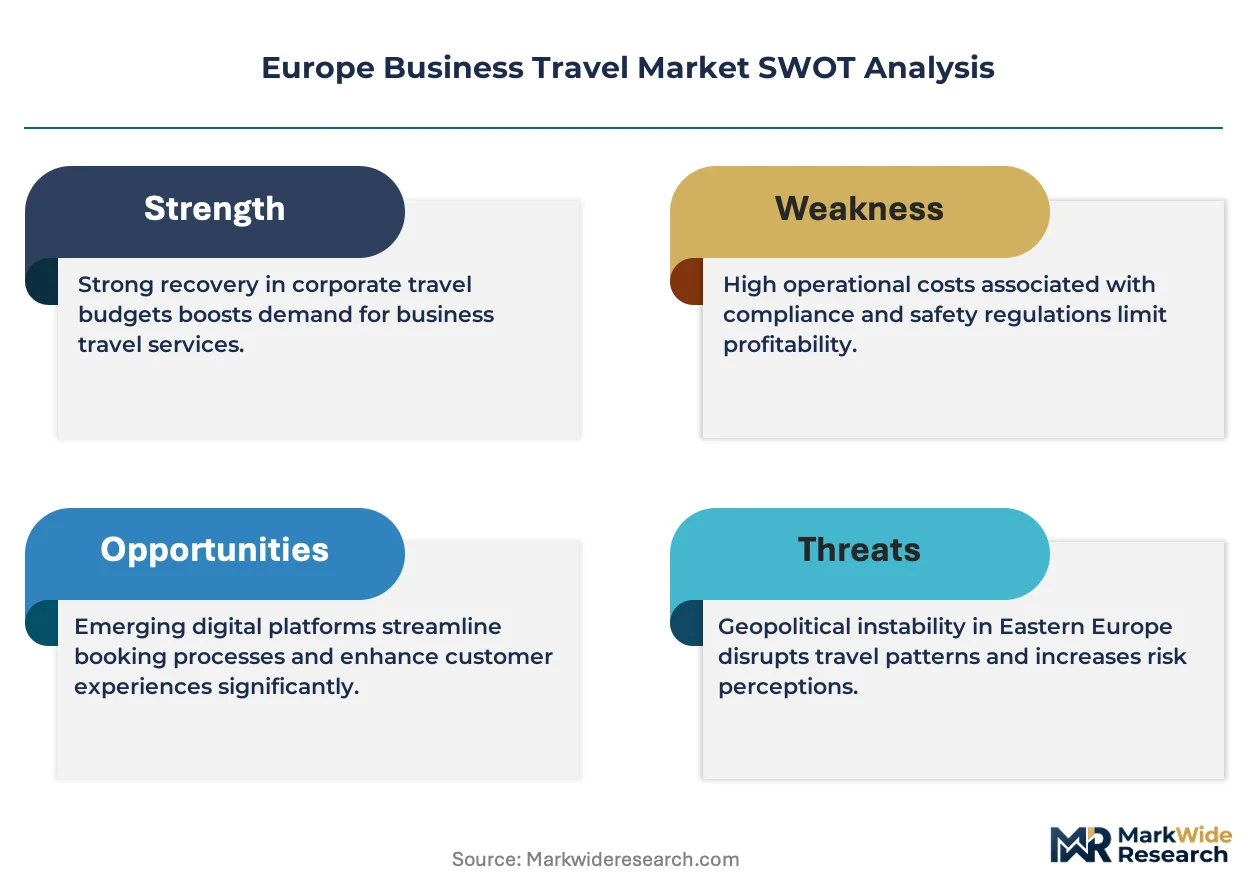
European airline capacity restoration is expanding seat availability on intra-European routes, directly supporting business travel volume recovery. CWT leverages its legacy corporate relationships to sustain large-account retention across the continent. BCD Travel anchors its competitive position through specialized life sciences and energy sector programs. TravelPerk differentiates via its SaaS-native platform architecture targeting mid-market European enterprises.
Europe business travel encompasses commercially motivated journeys undertaken by employees for employer-sponsored purposes, typically involving air or rail transportation, lodging procurement, and ground logistics coordination with average trip durations of two to four nights. The primary commercial purpose centers on relationship maintenance, contract negotiation, and knowledge transfer that cannot be replicated through virtual channels. Transportation and accommodation services command the dominant share of spend allocation, while travel management solutions capture disproportionate margin pools through technology-enabled policy enforcement and negotiated rate access. Corporate client type represents the most mature segment with established procurement frameworks, whereas SME adoption is accelerating fastest as cloud-based booking platforms reduce minimum contract thresholds.
EU Green Deal emission disclosure requirements and national carbon reporting frameworks are reshaping supplier evaluation criteria, with ESG compliance now gating preferred provider status across European procurement departments. REACH and GDPR indirectly influence travel data handling and supplier due diligence processes, while the EU AI Act will govern automated booking recommendation engines. Stakeholders must monitor regulatory trajectory on sustainable aviation fuel mandates and corporate travel emissions caps to align portfolio positioning with compliance timelines.
Market Dynamics
The EU Green Deal is compressing supplier evaluation timelines across European procurement departments, forcing travel management companies to requalify their entire accommodation and aviation portfolios against emission disclosure thresholds before contract renewal cycles complete.
Growth Catalysts
- CSRD Mandates:Corporate Sustainability Reporting Directive requirements are compelling listed enterprises to document Scope 3 travel emissions, creating captive demand for carbon-accounting booking platforms that automate data collection across German, French, and UK corporate headquarters.
- Hybrid Work Stabilization:Technology sector employers have normalized quarterly in-person gatherings, generating predictable quarterly booking patterns that reduce revenue volatility for managed travel programs serving mid-market SaaS enterprises.
- Sustainable Aviation Fuel Infrastructure:Amsterdam Schiphol and Frankfurt Airport anchor are expanding SAF blending capacity, enabling carriers to offer verified lower-carbon itineraries that satisfy procurement ESG gating criteria without route fragmentation.
Market Restraints
- Jet Fuel Price Volatility:Kerosene cost swings compress airline yield management flexibility, forcing corporate fare renegotiations mid-contract and eroding the price predictability that underpins managed travel program value propositions.
- Rail Infrastructure Bottlenecks:Cross-border high-speed capacity constraints between France, Belgium, and the Netherlands limit viable alternatives to short-haul aviation for time-sensitive business itineraries under four hours.
- GDPR Data Localization:Passenger name record processing restrictions fragment cloud-hosted booking platform architectures, requiring redundant EU data residency investments that inflate technology provider operational costs.
Strategic Opportunities
- Poland and Czech Republic Manufacturing Corridors:Automotive and electronics production expansion in Wrocław and Brno is generating underpenetrated SME travel demand for supplier audit and quality assurance site visits.
- EU AI Act Governance:Automated itinerary recommendation engines face new transparency requirements that favor established platforms with compliance documentation, creating barriers for unproven entrants.
- Rail-Air Intermodal Integration:Deutsche Bahn and Air France-KLM code-sharing agreements enable seamless carbon-efficient routing that captures sustainability-mandated corporate accounts abandoning pure aviation programs.
Industry Challenges
- Legacy GDS Migration Friction:Corporate travel departments face eighteen-month integration timelines when transitioning from Sabre or Amadeus to API-native booking platforms, delaying SaaS adoption despite functional superiority.
- Carbon Accounting Skill Scarcity:Procurement teams lack personnel trained in GHG Protocol Scope 3 calculation methodologies, forcing reliance on external consultants that elongate supplier requalification cycles.
- REACH Chemical Disclosure Complexity:Business travel amenity suppliers must document cleaning product compositions for hotel procurement departments, adding administrative burden to hospitality category management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Business Travel Market |
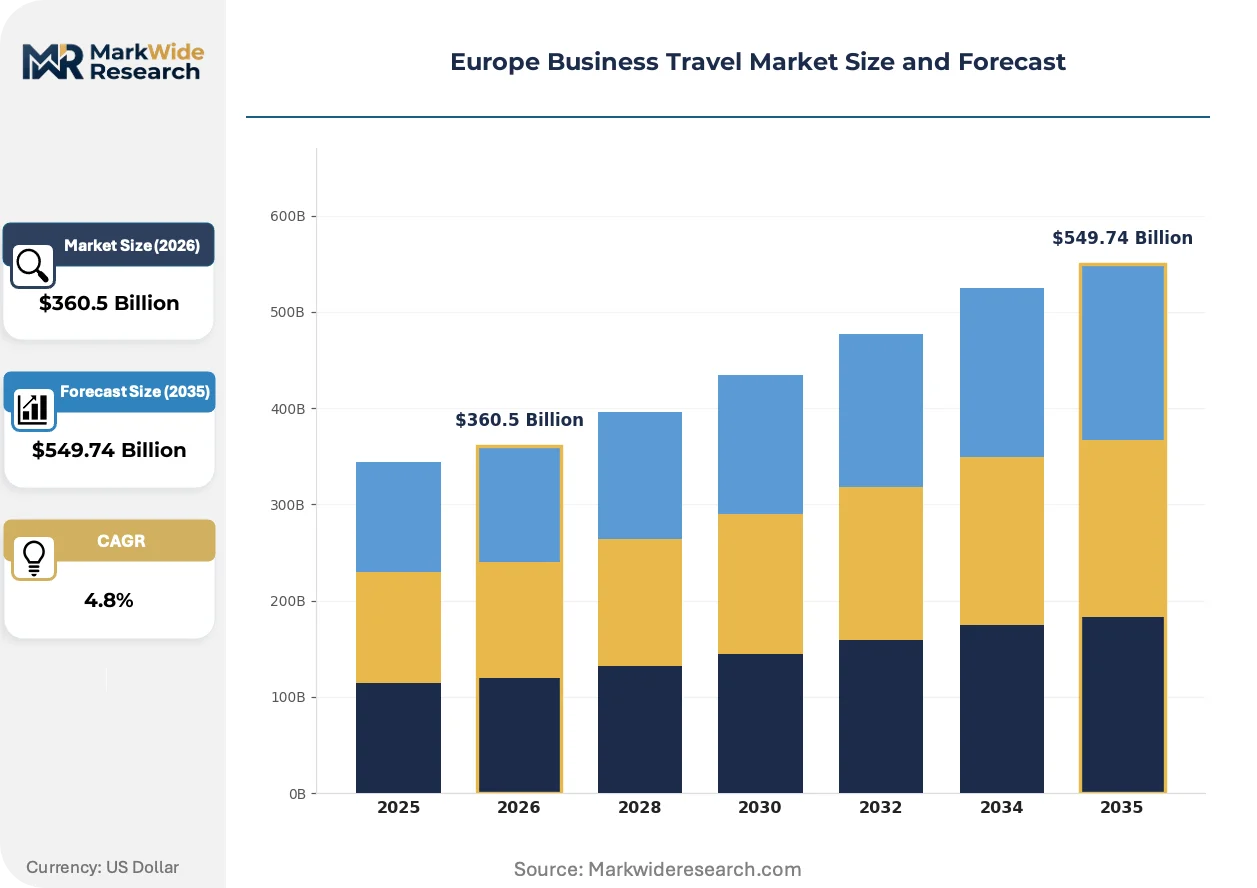
| Market Size in 2026 | $360.5 Billion |
| Market Size in 2035 | $549.74 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: Corporate, SMEs, Multinational Companies, Startups Service Type: Transportation, Accommodation, Travel Management, Events Booking Channel: Online, Travel Agencies, Direct, Corporate Bookings Travel Purpose: Meetings, Conferences, Incentives, Training |
| Companies Covered | CWT (Carlson Wagonlit Travel), Corporate Travel Management, American Express Global Business Travel, FCM Travel, TravelPerk, BCD Travel, Expedia Group, Navan Group, Booking Holdings (Egencia), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Business Travel Market Strategic Shifts & Innovations
Artificial intelligence and sustainability verification systems are rewriting the operational architecture of European corporate travel, collapsing traditional distinctions between booking execution, policy enforcement, and emission accountability into unified platform experiences.
Dynamic pricing algorithms are converging with real-time carbon intensity data to generate itinerary recommendations that simultaneously optimize fare cost and emission exposure. Mid-market enterprises in the Netherlands and Scandinavia are piloting these converged systems fastest, compressing the traditional separation between procurement cost centers and sustainability reporting functions into single-dashboard decision workflows.
REACH and the EU Green Deal are mandating supplier chemical and emission disclosure at the contract level, forcing hospitality chains to document linen laundering energy sources and cleaning product compositions. German automotive and chemical sector procurement departments are applying these disclosure requirements most stringently, rejecting hotel properties that cannot provide verified Scope 1 and Scope 2 data within thirty-day request windows.
Corporate travel buyers are consolidating spend onto fewer, larger managed travel programs with embedded sustainability reporting rather than fragmenting across multiple point solutions. This concentration favors platforms offering consolidated invoicing, policy enforcement, and automated EU Taxonomy alignment documentation, particularly among French and Italian manufacturing conglomerates with complex multi-jurisdictional travel footprints.
Europe Business Travel Market Segmentation
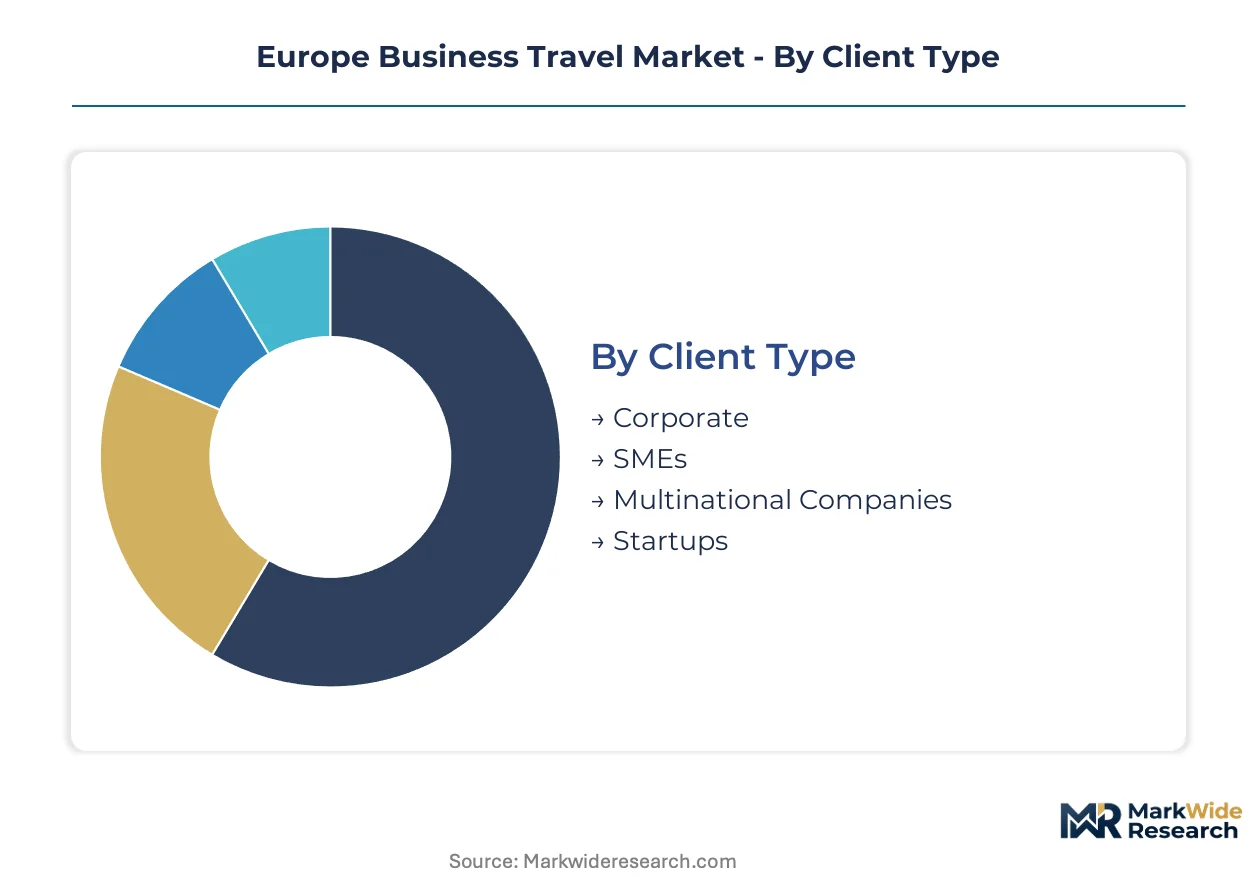
European business travel procurement operates across distinct organizational scales, service bundles, and booking modalities. Each segmentation axis reveals divergent margin structures and technology adoption curves that suppliers must navigate to capture account value.
Client Type:
Customization intensity rises with procurement sophistication and travel volume scale across this spectrum.
- Corporate:Mature enterprises with centralized procurement frameworks negotiate multi-year managed travel contracts. German automotive and French pharmaceutical headquarters dominate this segment, driving demand for integrated policy enforcement and automated carbon accounting dashboards under CSRD mandates.
- SMEs:Mid-market enterprises with 50-500 employees increasingly adopt cloud-native booking platforms that collapse minimum contract thresholds. SaaS sector employers in Amsterdam and Stockholm represent the fastest-climbing adoption curve as hybrid work models stabilize quarterly in-person gathering patterns.
- Multinational Companies:Complex multi-jurisdictional footprints require consolidated invoicing and EU Taxonomy alignment documentation. Procurement departments prioritize platforms with redundant EU data residency to satisfy GDPR passenger name record processing restrictions.
- Startups:Early-stage ventures rely on self-service booking tools with minimal policy guardrails. Travel spend concentrates on founder-led investor meetings and talent recruitment trips to London and Berlin venture hubs.
Most installed capacity flows through Corporate accounts. Expansion is steepest in SMEs.
Service Type:
Margin capture potential separates execution-heavy services from technology-enabled orchestration layers.
- Transportation:Air and rail procurement commands the dominant share of spend allocation. Intra-European airline capacity restoration on routes from Frankfurt, Paris, and Amsterdam directly supports volume recovery, while Deutsche Bahn and Air France-KLM code-sharing agreements enable carbon-efficient intermodal routing.
- Accommodation:Lodging procurement now requires verified Scope 1 and Scope 2 emission disclosure under EU Green Deal contract terms. German chemical sector buyers reject hotel properties unable to document linen laundering energy sources within thirty-day request windows.
- Travel Management:Technology-enabled policy enforcement and negotiated rate access capture disproportionate margin pools. Platforms embedding automated GHG Protocol Scope 3 calculation address procurement skill scarcity that elongates supplier requalification cycles.
- Events:Incentive travel and conference logistics face REACH chemical disclosure complexity for venue amenities. Corporate buyers consolidate event spend onto managed programs with embedded sustainability reporting rather than fragmenting across point solutions.
Transportation absorbs the largest share of direct spend. Travel Management delivers the steepest margin expansion trajectory.
Booking Channel:
Control over data architecture and rate access determines channel economics for European enterprises.
- Online:Self-service platforms with real-time inventory access serve cost-conscious segments. GDPR data localization requirements fragment cloud-hosted architectures, inflating technology provider operational costs for redundant EU data residency investments.
- Travel Agencies:Traditional intermediaries retain relevance for complex multi-leg itineraries and negotiated rate access. Legacy GDS migration friction extends eighteen-month integration timelines when corporate departments transition to API-native alternatives.
- Direct:Supplier-direct bookings bypass intermediary fees but sacrifice consolidated reporting. Airlines and hotel chains target this channel for high-frequency routes where corporate volume justifies bilateral contracts.
- Corporate Bookings:Centralized procurement platforms with embedded policy enforcement serve mature enterprise segments. French and Italian manufacturing conglomerates prioritize consolidated invoicing and automated EU Taxonomy alignment documentation.
Corporate Bookings channel the highest transaction value. Online platforms gain share fastest among mid-market adopters.
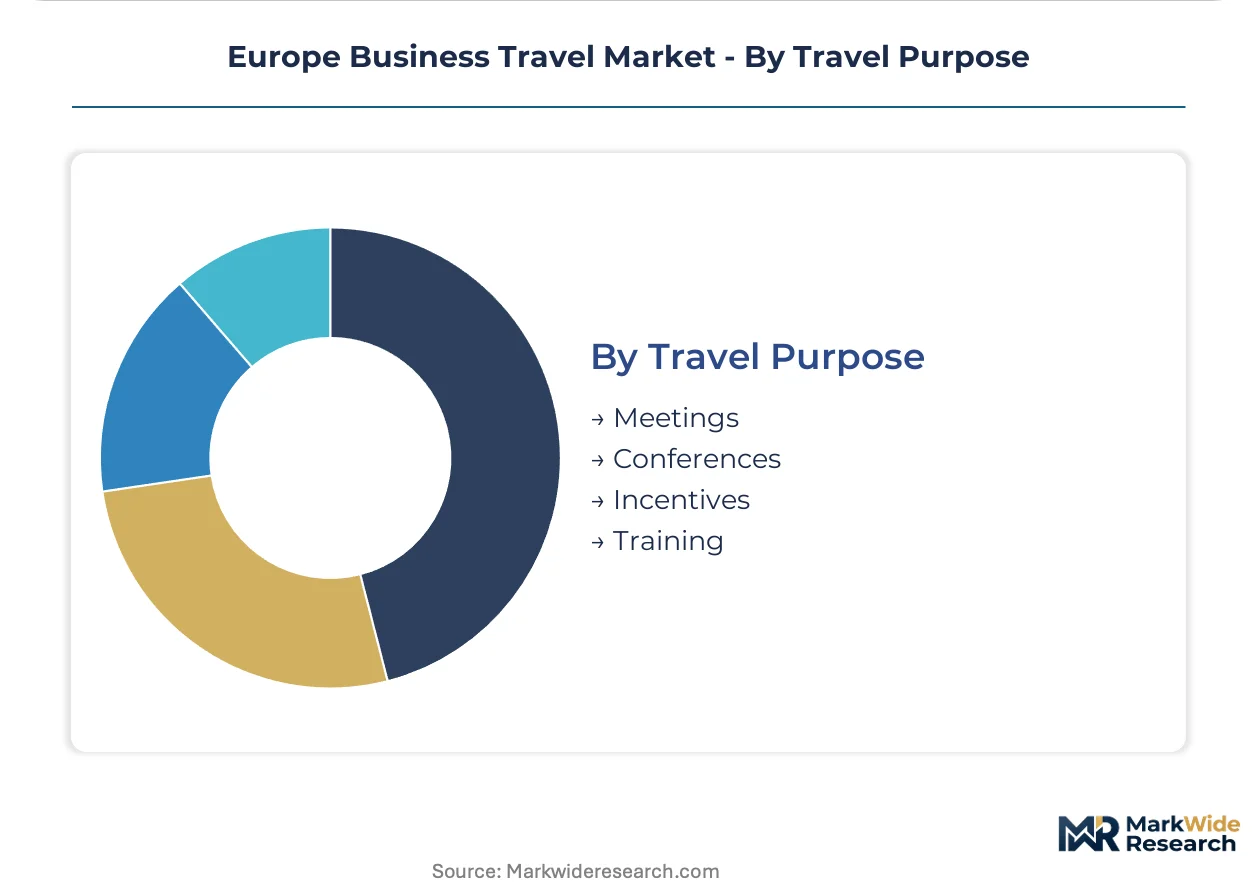
Travel Purpose:
Trip duration and advance booking windows vary sharply across commercial intent categories.
- Meetings:Relationship maintenance and contract negotiation trips average two to four nights with flexible advance purchase windows. Technology sector employers have normalized quarterly in-person gatherings, generating predictable booking patterns.
- Conferences:Industry event attendance requires concentrated inventory procurement during fixed-date windows. Amsterdam and Barcelona conference hubs drive seasonal demand spikes that test supplier capacity allocation.
- Incentives:Reward travel programs prioritize destination experience over cost optimization. Sustainability verification now gates preferred provider status as ESG compliance reshapes supplier evaluation criteria.
- Training:Knowledge transfer trips that cannot replicate through virtual channels sustain baseline demand. Automotive and electronics production expansion in Wrocław and Brno generates underpenetrated supplier audit and quality assurance site visit demand.
Meetings constitute the largest purpose category. Incentives expand most quickly as employer retention strategies emphasize experiential rewards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is compressing as EU Green Deal emission disclosure requirements harmonize compliance costs across member states, yet procurement sophistication gaps persist between mature Western European headquarters and emerging Central European manufacturing corridors. Corporate travel demand concentrates where CSRD mandates bite deepest and where industrial production generates supplier audit traffic.
Germany
Automotive and chemical sector procurement departments in Stuttgart and Ludwigshafen apply EU Green Deal hotel disclosure requirements most stringently, rejecting properties unable to document linen laundering energy sources within thirty-day windows. CSRD Scope 3 reporting obligations for listed enterprises create captive demand for carbon-accounting booking platforms. Frankfurt anchors aviation capacity restoration with expanding SAF blending infrastructure at its airport hub.
United Kingdom
Technology sector employers in London and Cambridge have normalized quarterly in-person gatherings, generating predictable booking patterns for managed travel programs. GDPR data localization requirements fragment cloud-hosted platform architectures, inflating technology provider operational costs for redundant EU data residency investments. The capital's venture ecosystem sustains founder-led investor meeting traffic to Berlin and Paris.
France
Pharmaceutical headquarters in Paris and Lyon drive demand for integrated policy enforcement and automated carbon accounting dashboards under CSRD mandates. Air France-KLM code-sharing agreements with Deutsche Bahn enable seamless rail-air intermodal routing that captures sustainability-mandated corporate accounts. Manufacturing conglomerates with complex multi-jurisdictional footprints prioritize consolidated invoicing and automated EU Taxonomy alignment documentation.
Netherlands
SaaS sector employers in Amsterdam and Rotterdam represent the fastest-climbing adoption curve for cloud-native booking platforms as hybrid work models stabilize. Amsterdam Schiphol anchors expanding SAF blending capacity, enabling carriers to offer verified lower-carbon itineraries. Mid-market enterprises here pilot dynamic pricing algorithms converged with real-time carbon intensity data fastest, compressing procurement and sustainability functions into single-dashboard workflows.
Poland
Automotive and electronics production expansion in Wrocław generates underpenetrated SME travel demand for supplier audit and quality assurance site visits. REACH chemical disclosure complexity for hotel amenities adds administrative burden to hospitality category management as Western European buyers extend compliance requirements eastward. Rail infrastructure bottlenecks limit viable alternatives to short-haul aviation for time-sensitive itineraries under four hours.
Europe Business Travel Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue SaaS-native platform architecture and automated carbon accounting specialization. The market structures around legacy corporate relationships, mid-market cloud adoption, and sustainability-embedded procurement consolidation. Three archetypes dominate: legacy-managed travel incumbents with large-account retention capabilities, cloud-native challengers collapsing minimum contract thresholds, and diversified travel platforms integrating leisure inventory for blended trip management. Competitive moves concentrate on strategic partnerships for rail-air intermodal integration and portfolio diversification into embedded sustainability reporting.
Within the legacy-managed travel tier, CWT leverages its corporate relationships to sustain large-account retention across the continent. BCD Travel anchors its position through specialized sector programs. TravelPerk occupies the cloud-native challenger position, exemplifying the SaaS-native architecture targeting mid-market European enterprises with reduced implementation friction.
| Leading Market Players |
|---|
| CWT (Carlson Wagonlit Travel) |
| Corporate Travel Management |
| American Express Global Business Travel |
| FCM Travel |
| TravelPerk |
| BCD Travel |
| Expedia Group |
| Navan Group |
| Booking Holdings (Egencia) |
| Others |
Cost & Logistics Intelligence
EU Green Deal emission disclosure requirements now gate both qualified supplier status and premium-tier pricing access for European corporate travel programs, forcing procurement departments to reject accommodations and carriers unable to document carbon intensity within contractual windows. This sustainability mandate compresses the supplier base eligible for preferred rate negotiations while elevating technology-enabled platforms that automate compliance documentation.
Pricing Analysis
Corporate booking channel margins absorb the steepest compression as SaaS-native platforms collapse minimum contract thresholds for mid-market enterprises. Three-tier pricing structure across premium, standard, and economy levels stratifies by ESG compliance verification and automated carbon accounting integration. Pricing pressure stems from kerosene cost volatility forcing mid-contract fare renegotiations that erode managed travel program value propositions. SME segments exhibit highest price sensitivity, while German automotive and French pharmaceutical headquarters prioritize compliance documentation over rate optimization.
Supply Chain Analysis
Sustainable aviation fuel supply rests on Amsterdam Schiphol and Frankfurt Airport blending infrastructure expansion, with carriers sourcing verification certificates from third-party auditors. Kerosene feedstock, rail rolling stock, and cloud data residency infrastructure anchor cost structures across transportation and technology layers. Single-source vulnerability concentrates in legacy GDS platforms requiring eighteen-month migration timelines to API-native alternatives. Distribution runs through consolidated managed travel programs with embedded sustainability reporting rather than fragmented point solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe business travel functions as a regulatory compounder where CSRD Scope 3 mandates create captive demand for carbon-accounting infrastructure that deepens with each compliance cycle.
For Market Incumbents: Anticipate SaaS-native challengers collapsing minimum contract thresholds in Dutch and Scandinavian mid-market segments by accelerating API-native platform migration roadmaps and embedding automated EU Taxonomy alignment documentation. Defensive consolidation of rail-air intermodal partnerships secures sustainability-mandated accounts abandoning pure aviation programs.
For New Entrants and Emerging Players: Travel management company partnerships offer fastest path to qualified supplier status for Polish and Czech manufacturing corridor penetration. SME automotive and electronics supplier audit traffic in Wrocław and Brno represents most penetrable white space. Target carbon accounting skill scarcity with GHG Protocol Scope 3 automation as primary go-to-market wedge.
For Investors and Strategic Acquirers: Roll-up economics work for cloud-native booking platforms because CSRD mandates are compressing procurement departments toward consolidated invoicing with embedded compliance documentation. Five-to-ten year viability hinges on EU data residency architecture and SAF verification integration. Acquisition target archetype: mid-market SaaS platforms with automated carbon accounting and redundant EU hosting. Watch SAF mandate acceleration as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Air Intermodal Partnership | Deutsche Bahn and Air France-KLM code-sharing captures sustainability-mandated corporate accounts. |
| API-Native Platform Migration | Eighteen-month GDS transition timelines favor early movers in SaaS-native booking architecture. |
| SAF Verification Infrastructure | Amsterdam Schiphol and Frankfurt Airport blending capacity enables verified lower-carbon itinerary premiums. |
| Carbon Accounting Automation | GHG Protocol Scope 3 calculation addresses procurement skill scarcity elongating supplier requalification. |
| EU Data Residency Investment | GDPR passenger name record restrictions fragment cloud architectures and inflate operational costs. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with travel management executives, corporate procurement officers, airline yield managers, hospitality chain sustainability directors, and EU regulatory affairs specialists with secondary validation across CSRD implementation guidance, EEA emission inventory databases, airline RPK traffic disclosures, and hotel chain ESG reporting. Bottom-up account-level spend analysis and top-down market sizing triangulated volume estimates across the analysis window.
Historical reference periods anchored the projection horizon through segmented modeling across client type, service bundle, booking channel, and travel purpose dimensions with additional granularity for ESG compliance tier and data residency architecture. CAGRs derived from regression analysis against macroeconomic indicators, regulatory implementation timelines, and technology adoption curves with SAF infrastructure deployment and hybrid work stabilization patterns as key forecast inputs.
Revisions become necessary when regulatory acceleration exceeds modeled CSRD phase-in schedules or when SAF supply constraints trigger carrier capacity adjustments. Forecasts reflect documented assumptions on emission disclosure threshold evolution and corporate procurement centralization rates. A small set of named triggers warrants ongoing watch: EU AI Act governance implementation, REACH chemical disclosure expansion, and sustainable aviation fuel mandate progression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Travel Services
Bleisure Travel Market
Business Travel Services
Brazil Business Travel Lodging Market
Business Travel Services
Europes Golden Generation Travel Market
Business Travel Services
Business Travel Lodging Market
Business Travel Services
United States Business Travel Market
Business Travel Services
Business Travel Market
Business Travel Services
Airline a-La-Carte Services Market
Business Travel Services
Latin America Business Travel Market