
 Tourism Market | 2026-2036
Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Tourism Market Outlook
The capital-intensity divergence between asset-heavy hotel operators and platform-based intermediaries is redrawing competitive boundaries in tourism. Marriott International sustains its position through captive real estate portfolios and loyalty-program lock-in across premium urban corridors. Booking Holdings Inc. leverages algorithmic pricing engines and pay-at-stay models to dominate digital distribution without property ownership burdens. Airbnb Inc. differentiates through supply-side network effects in non-standard accommodation, competing directly with both hotel chains and traditional vacation rental brokers.
Tourism encompasses the commercial organization of temporary displacement for leisure, business, or personal purposes, integrating transportation logistics, lodging provision, curated experiences, and destination services into coordinated consumption packages. The sector operates through high-fixed-cost, low-marginal-cost infrastructure where perishable inventory—unsold hotel nights, empty airline seats—drives dynamic yield management systems. Accommodation commands the largest value pool within service type segmentation, while online travel agencies capture disproportionate margin expansion through booking channel consolidation. Leisure travelers anchor volume across customer type categories, though business traveler recovery patterns remain structurally uncertain as corporate travel policies recalibrate. Coastal destinations and urban centers concentrate demand within destination type segmentation, with rural escapes representing the fastest-growing margin opportunity as overtourism pressures reshape traveler preferences.
The International Air Transport Association coordinates carbon offset standards that pressure carriers toward fleet renewal timelines, while the EU Green Deal's sustainable aviation fuel mandates reshape route economics on transatlantic and intra-European corridors. National tourism boards in Thailand, Indonesia, and the Philippines impose carrying-capacity limits on marine protected areas, constraining supply growth in high-demand coastal zones. The US FAA and counterpart civil aviation authorities in Japan and South Korea are advancing urban air mobility certification frameworks that could open new last-mile tourism access models. Stakeholders must monitor regulatory fragmentation between emissions-trading jurisdictions and assess whether platform liability frameworks will shift booking economics toward direct-channel investment.
Market Dynamics
The EU Green Deal's carbon-border adjustments on aviation fuel are forcing carriers to accelerate sustainable propulsion investments while redirecting route economics away from high-emission corridors. This regulatory pressure compounds with infrastructure bottlenecks in Southeast Asian island economies where visitor growth outpaces hotel and transport capacity expansion.
Growth Catalysts
- Sustainable Aviation Fuel Mandates:The EU Green Deal mandates progressive blending requirements that pull capital toward biofuel refining capacity and hydrogen propulsion R&D. Airlines reconfigure fleet procurement timelines to meet compliance windows.
- Experiential Travel Premiumization:High-net-worth travelers prioritize curated immersion over standardized packages, expanding margin pools for boutique operators and destination management companies.
- Urban Air Mobility Certification:The US FAA advances eVTOL frameworks that open last-mile tourism access to remote coastal and alpine destinations previously requiring multi-hour ground transfers.
Market Restraints
- Jet Fuel Price Volatility:Crude oil supply disruptions and refining capacity constraints compress carrier operating margins, particularly on thin long-haul routes dependent on price-sensitive leisure demand.
- Carrying-Capacity Limits:Thailand's Department of National Parks imposes strict visitor quotas on marine protected areas, constraining supply growth in high-demand coastal zones where infrastructure already saturates.
- Aviation Emissions Trading Fragmentation:Divergent carbon accounting methodologies between the EU ETS, UK ETS, and emerging Asian schemes create compliance complexity for multinational carriers.
Strategic Opportunities
- Rural Escape Infrastructure:Underserved hinterland regions in Portugal, Croatia, and Japan offer first-mover advantages for eco-lodge developers as overtourism pressures displace demand from urban cores.
- Direct-Channel Investment:Platform liability uncertainty under evolving EU Digital Services Act interpretations creates openings for hotel chains to reduce OTA dependency through proprietary booking engines.
- AI-Native Yield Management:Machine learning pricing algorithms converge with real-time demand sensing to optimize perishable inventory across fragmented accommodation supply.
Industry Challenges
- Sustainability Certification Talent Gap:Shortages of auditors qualified under GSTC and EarthCheck standards delay eco-label acquisition for properties seeking premium positioning.
- Legacy PMS Integration Friction:Hotel operators face complex API reconciliation when connecting decades-old property management systems to modern distribution platforms and guest-facing apps.
- Cross-Border Data Compliance:GDPR, China's PIPL, and emerging ASEAN frameworks create jurisdictional conflicts for guest data handling in international booking flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tourism Market |
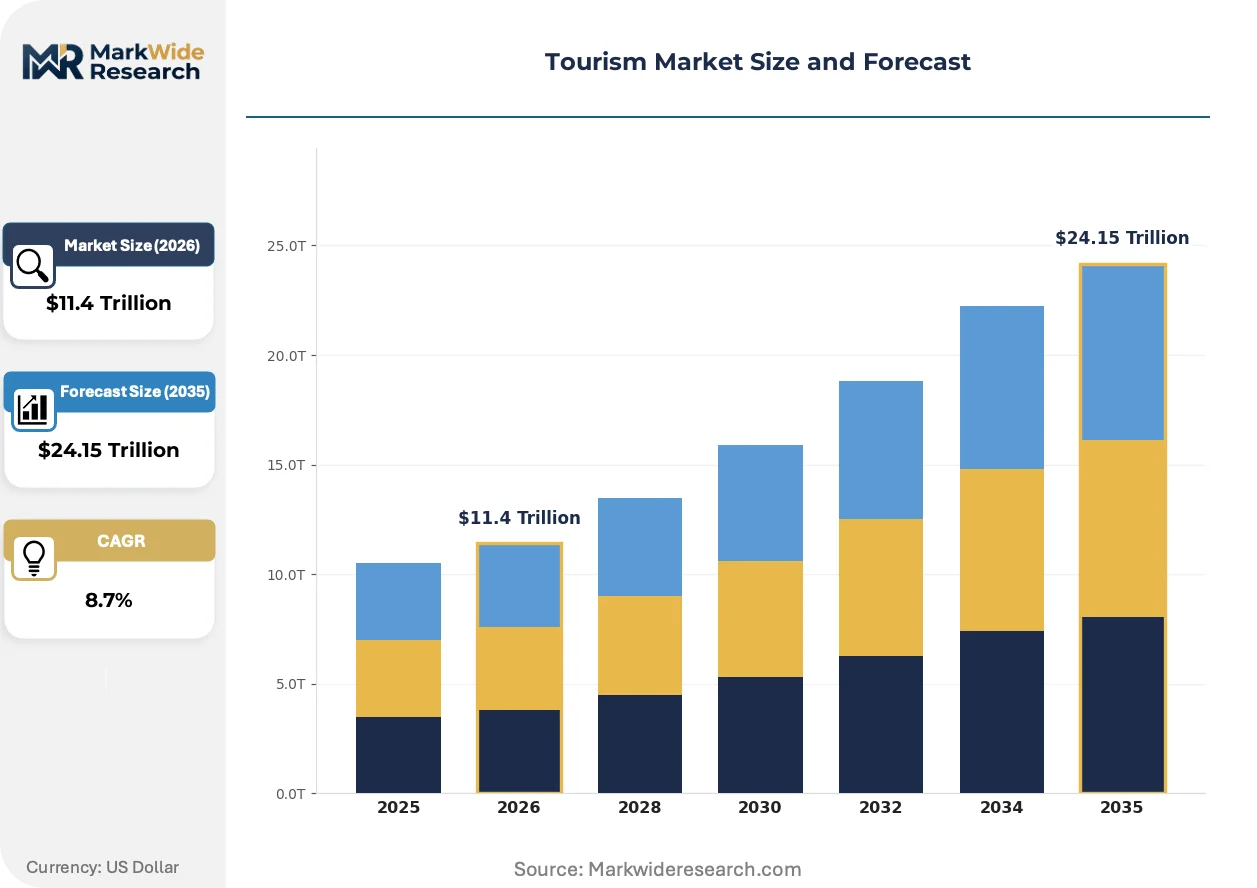
| Market Size in 2026 | $11.4 Trillion |
| Market Size in 2035 | $24.15 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodation, Transportation, Tour Packages, Activities Customer Type: Leisure Travelers, Business Travelers, Group Travelers, Solo Travelers Destination Type: Urban Destinations, Rural Escapes, Coastal Areas, Mountain Regions Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Mobile Apps |
| Companies Covered | Booking Holdings Inc., Marriott International, Airbnb Inc., Expedia Group Inc., TUI AG, Carnival Corporation, Accor Hotels, Trip.com Group, Hyatt Hotels Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tourism Market Strategic Shifts
Digital distribution infrastructure is decomposing traditional intermediation layers while regulatory carbon accounting and shifting traveler values reconfigure competitive advantage across accommodation and transport segments.
Artificial intelligence is decomposing static pricing calendars into dynamic, micro-segmented yield engines. Independent hotels and mid-size chains deploy machine learning tools that adjust rates in fifteen-minute intervals based on flight search spikes, weather patterns, and local event calendars. Revenue management teams shrink while algorithmic precision expands margin capture on perishable room nights.
The EU Green Deal's sustainable aviation fuel mandates are compressing fleet renewal timelines for European carriers. Airlines accelerate A320neo and 787 retirements while negotiating long-term offtake agreements with biofuel refiners in the Netherlands and Finland. Intra-European short-haul routes face the steepest cost adjustments as blending requirements tighten fastest on continental corridors.
Traveler booking behavior is fragmenting across specialized vertical platforms. Adventure seekers migrate to Viator and GetYourGuide for activity-first trip construction, bypassing traditional OTA hotel-air bundles. Corporate travel managers unbundle accommodation from transport procurement, negotiating direct rates with aparthotel providers for extended-stay remote work assignments. This disintermediation concentrates in North American and Nordic markets where platform fatigue and data privacy concerns accelerate most sharply.
Tourism Market Segmentation
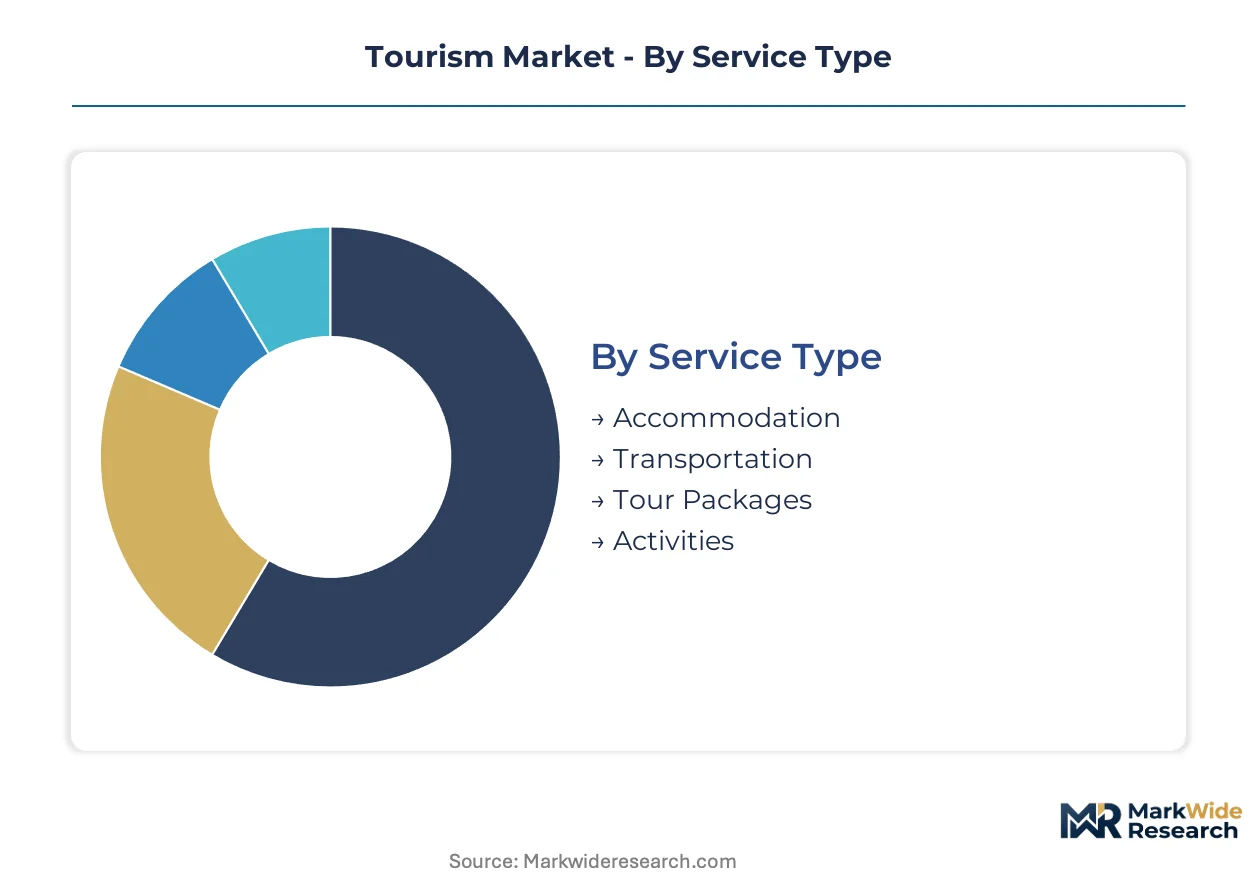
Tourism segmentation reveals how capital allocation and regulatory pressure concentrate across distinct consumption patterns. Understanding these divides exposes where margin pools shift and where compliance burdens land heaviest.
Service Type:
EU Green Deal carbon accounting treats each service category differently, with aviation-facing transport segments facing steeper compliance costs than accommodation or activities.
- Accommodation:Hotels, resorts, and alternative lodging command the largest value pool through perishable inventory yield management. EU ETS coverage of stationary energy use drives property-level efficiency investments in Germany, France, and the Netherlands. Coastal properties in Thailand and Indonesia face additional carrying-capacity limits from national park authorities.
- Transportation:Airlines, rail operators, and ground transport providers manage high-fixed-cost fleet assets where sustainable aviation fuel mandates reshape route economics. The EU Green Deal's progressive blending requirements compress operating margins on intra-European short-haul corridors while accelerating fleet renewal timelines.
- Tour Packages:Bundled offerings integrating multiple services face margin pressure from unbundling trends and direct-channel investment by component suppliers.
- Activities:Experience providers including guided tours, adventure sports, and cultural programming capture premium pricing through curated differentiation.
Accommodation handles the majority of throughput; rural escape accommodation within this category is climbing the fastest on share.
Customer Type:
Cost tier differentiation separates price-sensitive mass leisure from premium corporate and solo segments with divergent booking behaviors.
- Leisure Travelers:Price-sensitive vacation demand anchors volume across all destination types. Search behavior concentrates on Viator and GetYourGuide for activity-first trip construction, bypassing traditional bundled offerings in North American and Nordic markets.
- Business Travelers:Corporate demand faces structural uncertainty as travel policies recalibrate post-pandemic, with extended-stay remote work assignments shifting procurement toward aparthotel direct rates.
- Group Travelers:Coordinated bookings for events, weddings, and incentive travel sustain higher per-trip spend but face longer sales cycles.
- Solo Travelers:Independent explorers prioritize flexibility and safety, driving demand for verified review platforms and female-focused accommodation networks.
Leisure travelers generate the dominant transaction volume; solo travelers are expanding most quickly on demographic share.
Destination Type:
Application-based segmentation tracks how overtourism pressures and infrastructure capacity reshape traveler flows across geographic contexts.
- Urban Destinations:Metropolitan centers concentrate business and cultural demand but face displacement as overtourism pressures mount. Barcelona, Amsterdam, and Venice impose visitor quotas and tourist taxes to manage congestion.
- Coastal Areas:Beach and marine destinations face the tightest regulatory constraints. Thailand's Department of National Parks enforces strict visitor quotas on marine protected areas, constraining supply growth where infrastructure already saturates.
- Rural Escapes:Hinterland regions in Portugal, Croatia, and Japan offer first-mover advantages for eco-lodge developers as demand shifts away from urban cores.
- Mountain Regions:Alpine and high-altitude destinations benefit from seasonal pricing power but face climate vulnerability and access infrastructure limitations.
Urban destinations absorb the largest visitor flows; rural escapes show the steepest expansion trajectory as preference shifts accelerate.
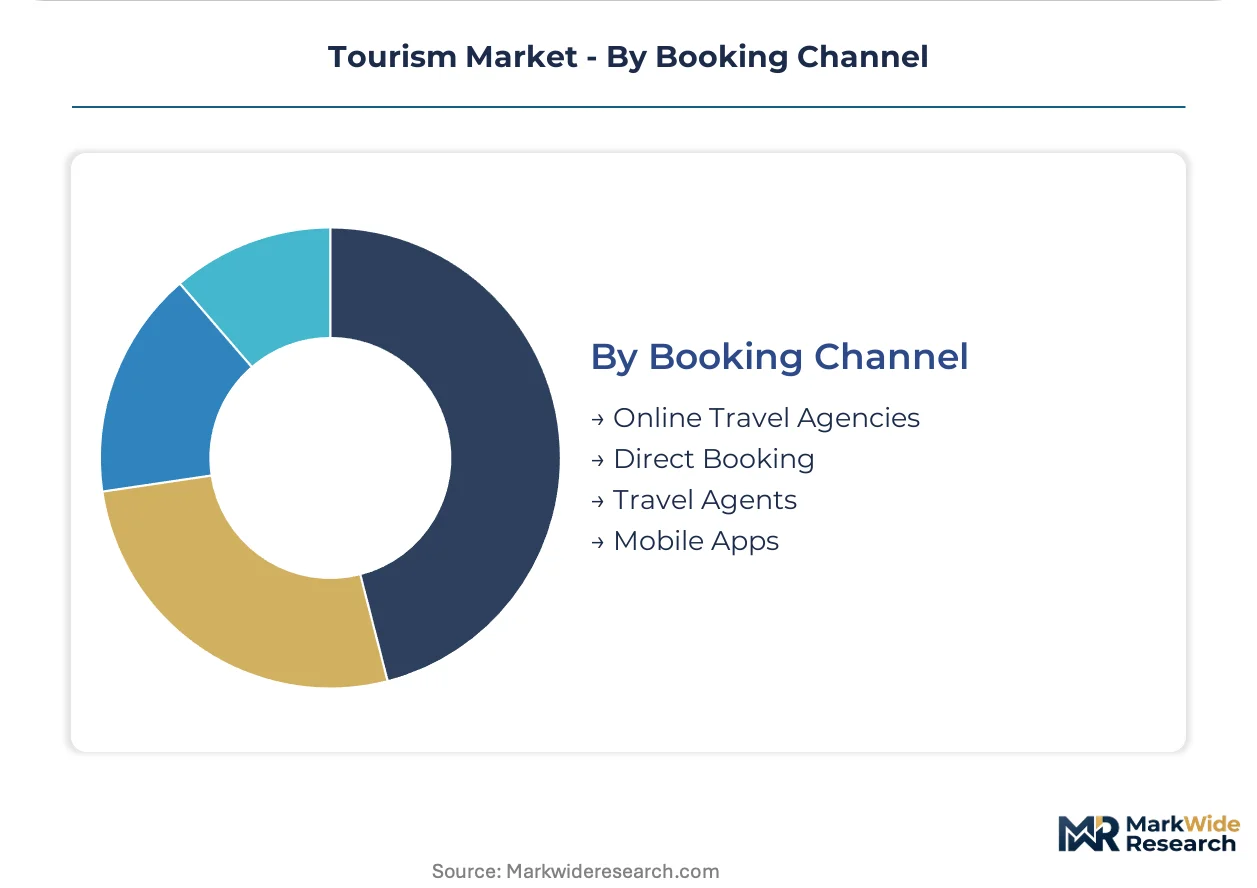
Booking Channel:
Margin concentration varies sharply by channel control, with platform-based intermediaries capturing disproportionate value versus direct relationships.
- Online Travel Agencies:Algorithmic pricing engines and pay-at-stay models dominate digital distribution. EU Digital Services Act liability uncertainty creates openings for supplier direct-channel investment.
- Direct Booking:Proprietary engines and loyalty-program lock-in reduce OTA dependency. Marriott International sustains premium positioning through captive real estate portfolios and urban corridor concentration.
- Travel Agents:Traditional intermediation persists in complex multi-destination itineraries and corporate account management.
- Mobile Apps:Last-minute and impulse bookings concentrate here, with real-time location services enabling proximity-based yield optimization.
Online travel agencies process the dominant booking volume; direct booking channels are gaining share fastest as platform fatigue spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Mediterranean coastal economies while Southeast Asian island markets absorb volume growth without commensurate rate capture. Regulatory divergence on aviation emissions and visitor carrying capacities fragments competitive dynamics across destination clusters.
United States
Urban air mobility certification by the FAA unlocks eVTOL access to remote coastal and alpine destinations. The Department of Transportation coordinates with metropolitan planning organizations on vertiport infrastructure. Greater Miami and the Florida Keys cluster experimental last-mile tourism access models.
Thailand
Marine protected area quotas constrain supply growth in Phuket and Krabi where visitor demand saturates existing hotel capacity. The Department of National Parks enforces strict daily visitor limits on Similan and Surin archipelagos. Bangkok's Suvarnabhumi Airport anchors hub-and-spoke distribution to island economies.
Germany
EU Green Deal sustainable aviation fuel mandates compress fleet renewal timelines for Lufthansa and Eurowings. The Federal Aviation Office coordinates national compliance with blending requirements. Munich and Frankfurt concentrate biofuel offtake negotiations with Nordic refiners.
Indonesia
Bali's carrying-capacity pressures spread to Lombok and the Gili Islands as overtourism redirects flows. The Ministry of Tourism and Creative Economy imposes visitor levies on high-traffic zones. Labuan Bajo and the Komodo National Park cluster premium eco-lodge development.
Japan
Rural escape demand accelerates in Hokkaido and Kyushu as overtourism strains Kyoto and Osaka. The Japan Tourism Agency promotes decentralization through regional revitalization subsidies. The Setouchi inland sea and Noto Peninsula concentrate first-mover eco-lodge investment.
Tourism Market Competitive Environment
Concentration sits with platform-based intermediaries that capture margin without asset ownership burdens. Asset-heavy hotel operators defend position through captive real estate and loyalty-program lock-in. Three archetypes dominate: algorithmic pricing engines, supply-side network aggregators, and experiential boutique curators. Competitive moves center on direct-channel investment to reduce OTA dependency and AI-native yield management deployment.
Within the platform-based tier, Booking Holdings Inc. and Airbnb Inc. exemplify divergent network-effect strategies. Marriott International anchors the asset-heavy archetype through urban corridor concentration and loyalty infrastructure. These three entities represent the structural fault lines between digital distribution dominance and property-level margin defense.
| Leading Market Players |
|---|
| Booking Holdings Inc. |
| Marriott International |
| Airbnb Inc. |
| Expedia Group Inc. |
| TUI AG |
| Carnival Corporation |
| Accor Hotels |
| Trip.com Group |
| Hyatt Hotels Corporation |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day booking lead times for peak-season coastal inventory concentrate pricing power with property owners in Thailand and Indonesia while compressing margins for intermediary platforms. This perishability dynamic ties yield management sophistication directly to supply chain control over limited room nights.
Pricing Analysis
The customization-premium spread between configured experiential packages and standardized tour bundles widens as affluent travelers prioritize curated immersion. Three-tier pricing structure across premium, standard, and economy levels dominates accommodation, with EU Green Deal carbon accounting adding compliance-grade differentiation. Pricing pressure stems from sustainable aviation fuel mandates compressing carrier operating margins on intra-European short-haul corridors. Leisure travelers anchor volume with acute price sensitivity, while solo explorers and corporate extended-stay segments absorb premium positioning with lower elasticity.
Supply Chain Analysis
Inventory lead times stretch longest for marine-protected-area permits and eco-lodge construction materials in Southeast Asian island economies. Supply concentrates in Thailand, Indonesia, and the Philippines for coastal accommodation, while Germany and the Netherlands anchor sustainable aviation fuel refining capacity. Jet fuel, biofuel feedstock, and construction-grade timber constitute critical input dependencies. Single-source vulnerability sits with carrier fleet procurement concentrated at Airbus and Boeing. Distribution runs through platform-based intermediaries consolidating fragmented accommodation supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tourism incumbents face substitution defense against experience-first vertical platforms that disintermediate traditional hotel-air bundles. Platform fatigue and data privacy concerns accelerate direct-channel migration as the core threat.
For Market Incumbents: Consolidate loyalty-program lock-in through captive real estate acquisition in premium urban corridors. Deepen backward integration into sustainable aviation fuel offtake agreements to hedge EU Green Deal compliance costs. Platform liability uncertainty under evolving EU Digital Services Act interpretations creates openings to reduce OTA dependency through proprietary booking engine investment. For New Entrants and Emerging Players: Anchor in rural escape accommodation across Portugal, Croatia, and Japan where overtourism pressures displace demand from saturated urban cores. Target eco-lodge development in hinterland regions with first-mover infrastructure advantages. Deploy AI-native yield management tools to optimize perishable inventory against legacy property management systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across platform-based intermediaries relative to asset-heavy hotel operators. Long-term viability favors algorithmic pricing engines with network-effect moats over captive real estate portfolios facing carbon-border adjustment pressures. Acquisition targets should demonstrate direct-channel momentum or proprietary sustainability certification. Watch for urban air mobility certification milestones as inflection indicators for last-mile tourism access models.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Channel Platform Development | Reduces OTA dependency as EU Digital Services Act liability frameworks evolve. |
| Sustainable Aviation Fuel Offtake Agreements | Secures compliance pathway under EU Green Deal progressive blending mandates. |
| Rural Escape Infrastructure Buildout | Captures displaced demand from overtourism-stressed urban destinations. |
| AI-Native Yield Management Deployment | Optimizes perishable inventory against fragmented accommodation supply. |
| Urban Air Mobility Certification Pursuit | Unlocks FAA-approved eVTOL access to remote coastal and alpine destinations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of corporate sustainability disclosures, EU regulatory filings, and national tourism board statistics. Interviews with revenue management directors, sustainable aviation fuel procurement leads, destination marketing executives, and eco-lodge developers informed demand-side and supply-side assessments. SEC 10-K filings, IATA carbon offset registries, and Thailand Department of National Parks visitor data provided validation anchors. Bottom-up property-level capacity estimates triangulated against top-down national arrival projections.
Segmentation dimensions modeled span service type, customer type, destination type, and booking channel across the projection horizon. Accommodation throughput, carrier seat capacity, and activity provider density fed volume estimates. CAGRs derived from historical growth rate regression adjusted for regulatory inflection points including EU Green Deal implementation timelines and marine protected area quota expansions.
Material uncertainties — jet fuel price volatility, aviation emissions trading fragmentation, and carrying-capacity limit enforcement variability — sit outside the modeled envelope. Forecasts reflect assumptions about fleet renewal timelines and traveler preference shifts toward experiential curation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Malaysia Tourism Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
China Online Travel Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
North America Driving Vacation Market
Travel and Tourism
Ethno Tourism Community Based Eco Tourism Market
Travel and Tourism
India Wellness Tourism Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Luxury Tourism Market