
 Global AWS Managed Services Market | 2026-2036
Global AWS Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global AWS Managed Services Market Foresight
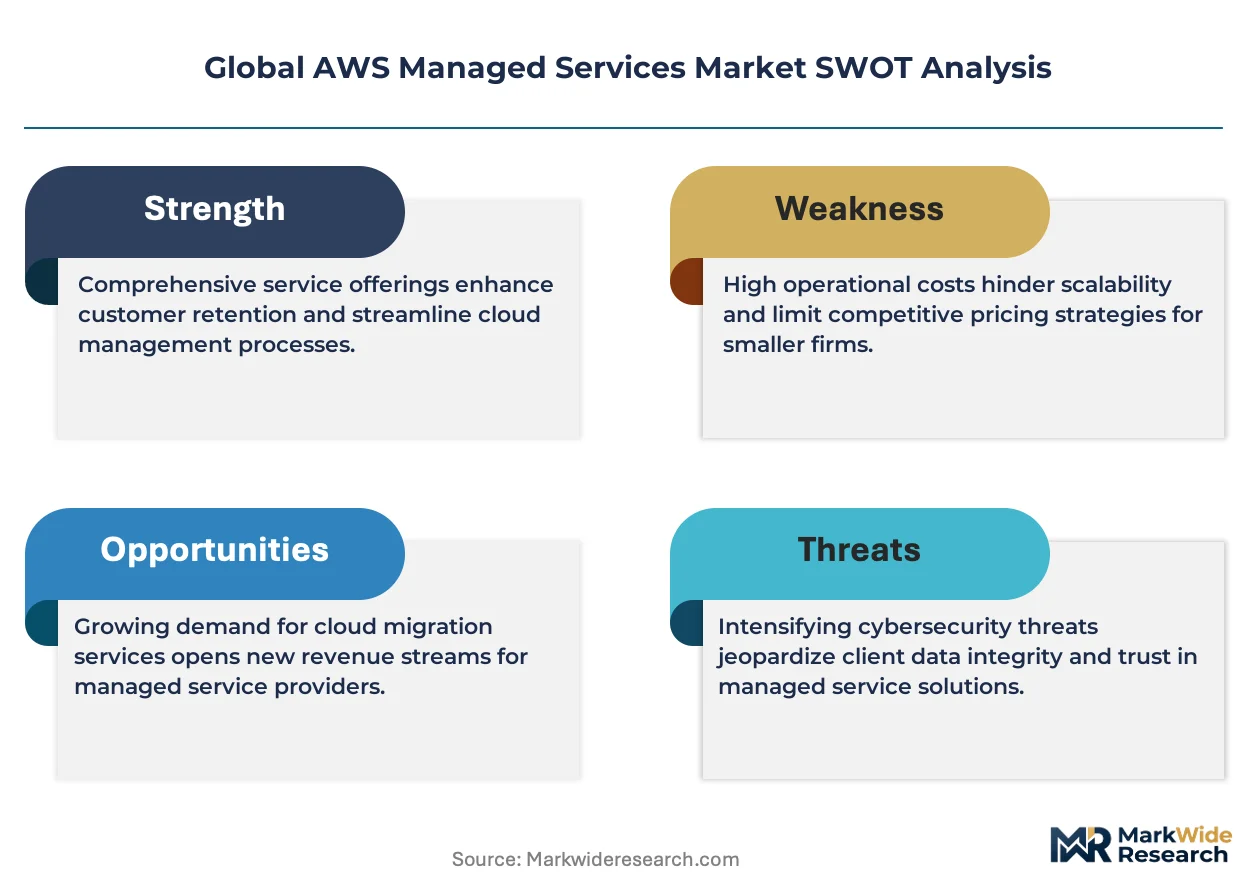
AWS MSP Partner Network certification is unwinding the competitive landscape, forcing smaller consultancies to either invest in accredited specializations or exit the channel. Accenture leverages its multi-industry footprint to bundle SAP migrations with managed operations. Rackspace anchors its position through dedicated AWS centers of excellence in North America and Europe. DXC Technology Company competes by embedding mainframe modernization into its managed services portfolio.
AWS managed services encompass the ongoing operation, optimization, and governance of cloud infrastructure running on Amazon Web Services, typically delivered through 24/7 monitoring, automated patching, and cost-optimization algorithms that maintain service-level agreements between 99.9% and 99.99% availability. These services eliminate the need for in-house platform expertise while ensuring workload security and performance continuity. Infrastructure Management and Security Management command the largest revenue pools as enterprises prioritize uptime guarantees and threat surface reduction. Hybrid Cloud deployment is expanding fastest as regulated sectors maintain on-premises data gravity while bursting compute to AWS.
GDPR and the EU AI Act shape European procurement by mandating data localization and algorithmic transparency, while HIPAA governs healthcare workloads in the United States and Japan's METI guidelines influence cloud security baselines across Asia-Pacific. The SEC's cybersecurity disclosure rules are pushing publicly traded clients toward audited managed services with documented incident response protocols. Stakeholders must evaluate whether their MSP holds current competencies in sovereign cloud architectures before committing to multi-year outsourcing contracts.
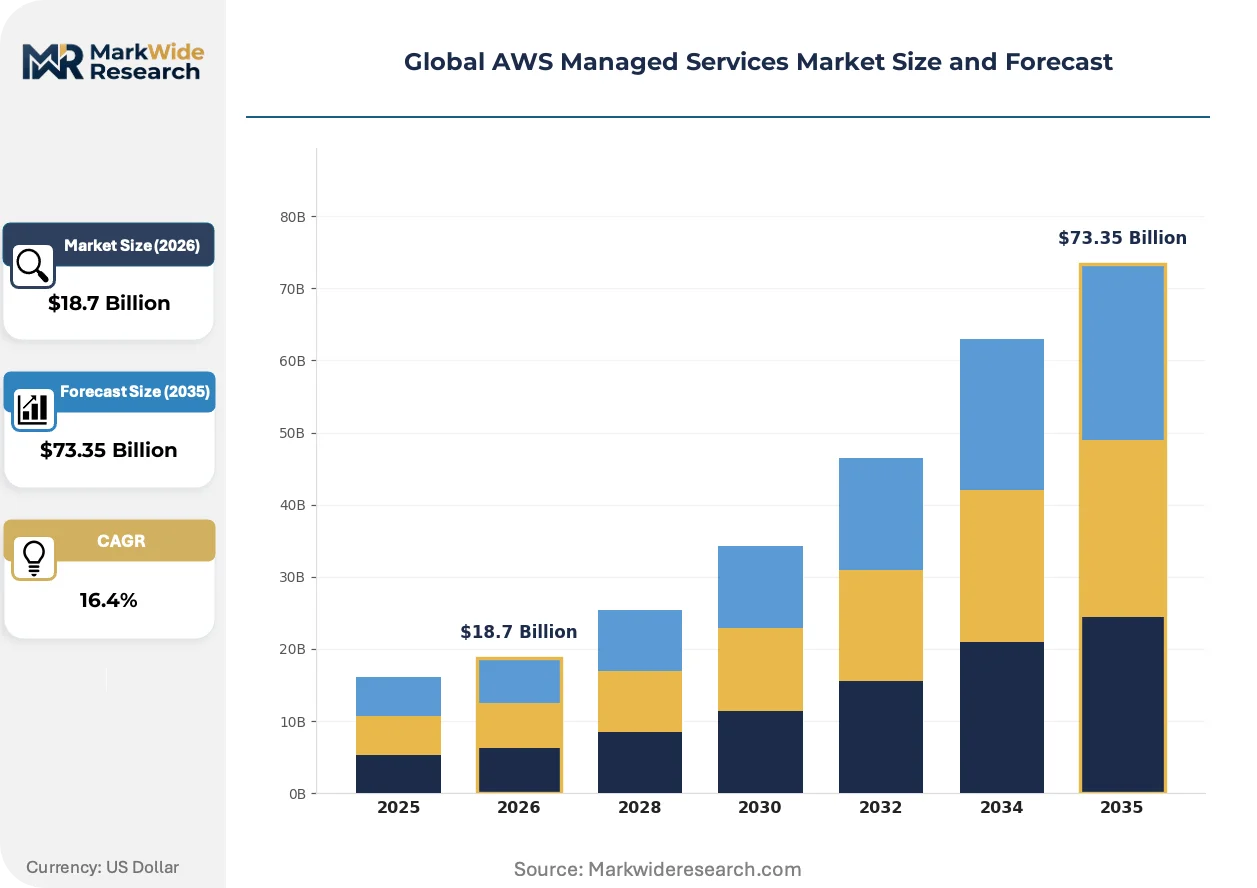
Market Dynamics
AWS MSP Partner Network certification requirements are forcing channel consolidation as smaller consultancies face steep accreditation costs, while sovereign cloud mandates from GDPR and the EU AI Act reshape procurement criteria across European financial services and automotive verticals.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements are accelerating managed services procurement among German automotive manufacturers seeking pre-audited AWS environments with documented model governance.
- Healthcare data gravity:HIPAA-regulated US hospital systems are offloading infrastructure operations to MSPs with documented Business Associate Agreements and 24/7 security operations center coverage.
- Hybrid burst patterns:Japanese industrial conglomerates under METI cybersecurity guidelines are maintaining on-premises data lakes while bursting compute-intensive workloads to AWS through managed sovereign configurations.
Market Restraints
- Certification cost barriers:AWS MSP competency requirements demand six-figure annual investments in accredited staff training and audit documentation, squeezing mid-tier consultancies.
- Data residency fragmentation:Divergent localization requirements across Germany, France, and Switzerland force MSPs to maintain redundant sovereign cloud footprints, inflating operational overhead.
- Mainframe integration complexity:Legacy COBOL systems in US financial services resist API-based connectivity, extending migration timelines and compressing margin realization for hybrid managed contracts.
Strategic Opportunities
- India BIS cloud security standards:The Bureau of Indian Standards' emerging data center certification framework creates first-mover advantage for MSPs establishing local AWS Outposts with indigenous encryption controls.
- Generative AI operations:Convergence of large language model inference pipelines with FinOps automation is opening managed MLOps service lines for training workload optimization.
- CSRD sustainability reporting:The EU Corporate Sustainability Reporting Directive mandates carbon footprint disclosure, creating demand for MSPs with AWS carbon accounting dashboards and renewable energy matching tools.
Industry Challenges
- Platform engineering talent scarcity:Kubernetes and Terraform expertise commands 40% wage premiums above traditional sysadmin roles, constraining MSP headcount expansion.
- Multi-cloud credential proliferation:Simultaneous AWS, Azure, and GCP certification requirements fragment technical training budgets and extend engineer onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AWS Managed Services Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure Management, Migration Support, Security Management, Application Monitoring, Backup & Recovery, Compliance Management Deployment Model: Public Cloud, Hybrid Cloud, Multi-Cloud, Private Cloud Client Type: Small & Medium Enterprises, Large Enterprises, Government Agencies, Non-Profit Organizations, Startups Industry Vertical: Banking, Telecommunications, Manufacturing, Media & Entertainment, Aerospace, Education |
| Companies Covered | Accenture, Rackspace, DXC Technology Company, Claranet, Capgemini, Slalom, Onica, Cloudreach, Mission Cloud Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AWS Managed Services Market Shifts & Advancements
Agentic AI operations and sovereign cloud architectures are compressing traditional managed services delivery models, while procurement criteria harden around documented compliance automation and carbon transparency.
FinOps automation platforms embedded within AWS Cost Explorer are displacing manual tagging governance and spreadsheet-based allocation models. Mid-market SaaS vendors in the United States are adopting these tools within 90-day implementation windows. The displacement of reactive cost reviews by real-time anomaly detection is compressing MSP pricing power for basic monitoring tiers.
The EU AI Act's risk classification framework for algorithmic systems is mandating pre-deployment conformity assessments across Frankfurt and Stuttgart automotive engineering centers. German OEMs now require MSPs to maintain EU-notified body relationships for high-risk AI workload validation. This regulatory architecture is fragmenting previously standardized AWS managed service catalogs into jurisdiction-specific compliance bundles.
Consumption-based contracting is replacing fixed-fee managed services arrangements among UK fintech challengers and Series C SaaS scaleups. Buyers are unbundling 24/7 coverage from optimization advisory, purchasing the latter on outcome-tied SLO achievement. This pattern is most visible in London's payments infrastructure sector, where Stripe-integrated platforms negotiate pure-variable pricing tied to cloud spend reduction metrics.
Global AWS Managed Services Market Segmentation
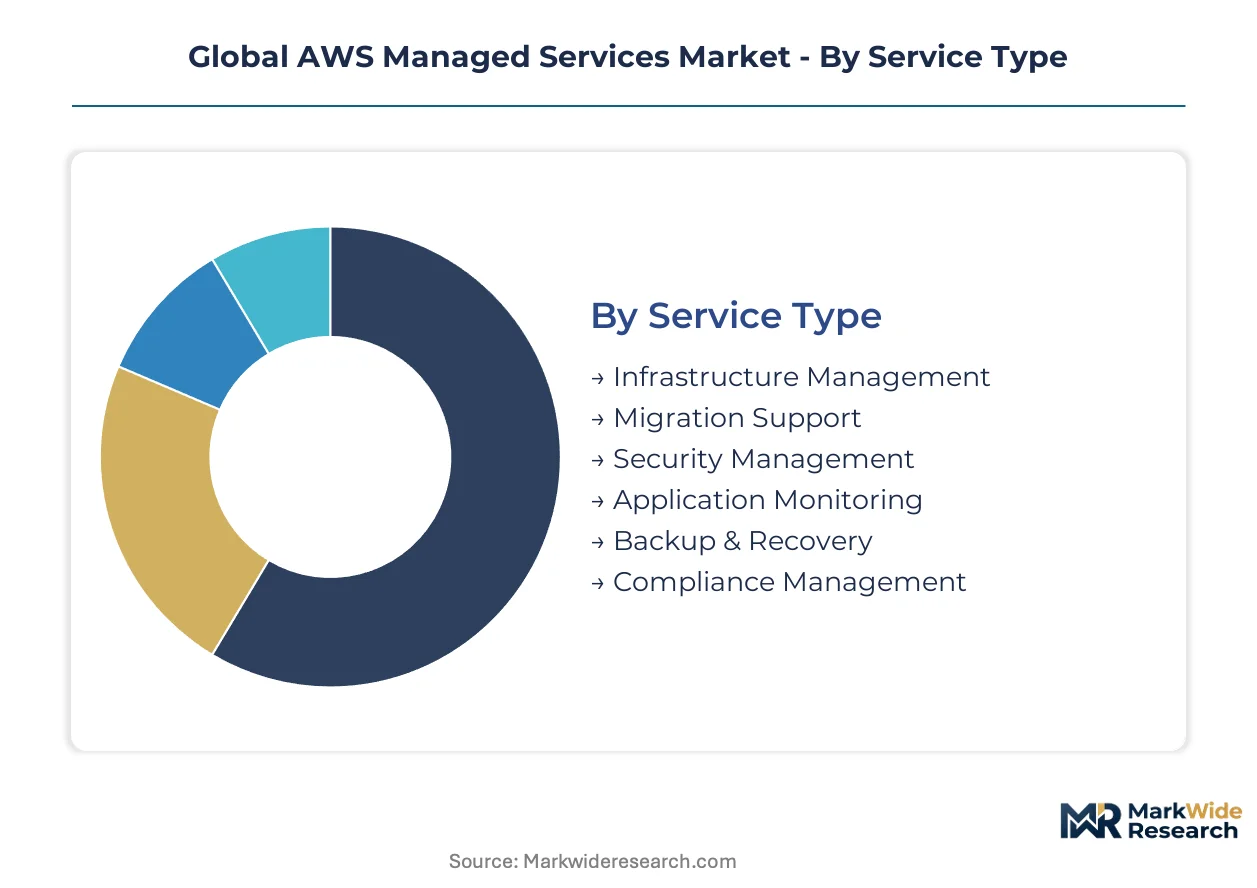
AWS managed services segmentation reveals how procurement patterns diverge across workload criticality, regulatory exposure, and internal platform maturity. Buyers self-select into service tiers based on whether they seek operational offload, compliance insulation, or cost optimization leverage.
Service Type:
German automotive manufacturers and US hospital systems anchor domestic demand for compliance-heavy segments, while migration services flow disproportionately to export-led consultancies serving cross-border cloud transformations.
- Infrastructure Management:Continuous monitoring, automated patching, and capacity orchestration of EC2, EKS, and serverless compute estates. US financial institutions under SEC cybersecurity disclosure rules are consolidating 24/7 coverage contracts with MSPs holding documented runbook automation. This segment holds the largest share; momentum sits with Security Management.
- Security Management:Threat detection, incident response, and identity governance across AWS GuardDuty, Security Hub, and IAM configurations. German OEMs navigating EU AI Act high-risk system classifications require MSPs with EU-notified body relationships for pre-audited environments.
- Migration Support:Lift-and-shift, re-platforming, and refactoring of on-premises workloads to AWS-native architectures. Japanese industrial conglomerates under METI guidelines drive sovereign cloud migration demand.
- Application Monitoring:APM integration with CloudWatch, X-Ray, and third-party observability stacks for latency and error-rate SLOs.
- Backup & Recovery:Automated snapshot policies, cross-region replication, and ransomware-resistant air-gapped storage orchestration.
- Compliance Management:Continuous control monitoring, audit evidence collection, and regulatory mapping for HIPAA, GDPR, and sector-specific frameworks.
Infrastructure Management commands the deepest contract values; Compliance Management is climbing the fastest as regulatory density intensifies.
Deployment Model:
Cost tier stratification separates commodity public cloud engagements from premium sovereign configurations requiring redundant data residency investments.
- Hybrid Cloud:Orchestrated workloads spanning on-premises data centers and AWS regions with seamless burst capacity. German automotive engineering centers in Stuttgart and Frankfurt maintain this architecture to satisfy GDPR data localization while accessing elastic compute for AI training pipelines.
- Public Cloud:Native AWS consumption without on-premises infrastructure retention, dominant among US Series C SaaS scaleups seeking pure-variable pricing tied to cloud spend metrics.
- Multi-Cloud:Parallel AWS, Azure, and GCP operations requiring abstraction layers and unified governance tooling.
- Private Cloud:Dedicated AWS Outposts or Local Zones deployments for air-gapped or ultra-low-latency requirements in Swiss banking and defense contracting.
Hybrid Cloud holds the largest share; Multi-Cloud is expanding most quickly as buyers seek vendor diversification.
Client Type:
Volume concentration sits with Large Enterprises, though Startups represent the steepest expansion trajectory for consumption-based contracting models.
- Large Enterprises:Multi-year managed services agreements spanning infrastructure, security, and FinOps optimization with dedicated account engineering.
- Small & Medium Enterprises:Standardized service catalogs with limited customization, purchased through AWS Marketplace listings and partner-led assessments.
- Government Agencies:FedRAMP, StateRAMP, and sovereign cloud mandates requiring cleared personnel and air-gapped operational environments.
- Startups:Usage-based arrangements unbundling 24/7 coverage from advisory services, prevalent among UK fintech challengers negotiating Stripe-integrated platform economics.
- Non-Profit Organizations:AWS credit programs and donated service tiers with basic monitoring and cost alerting.
Large Enterprises anchor contract value; Startups are gaining share fastest through outcome-tied pricing experimentation.
Industry Vertical:
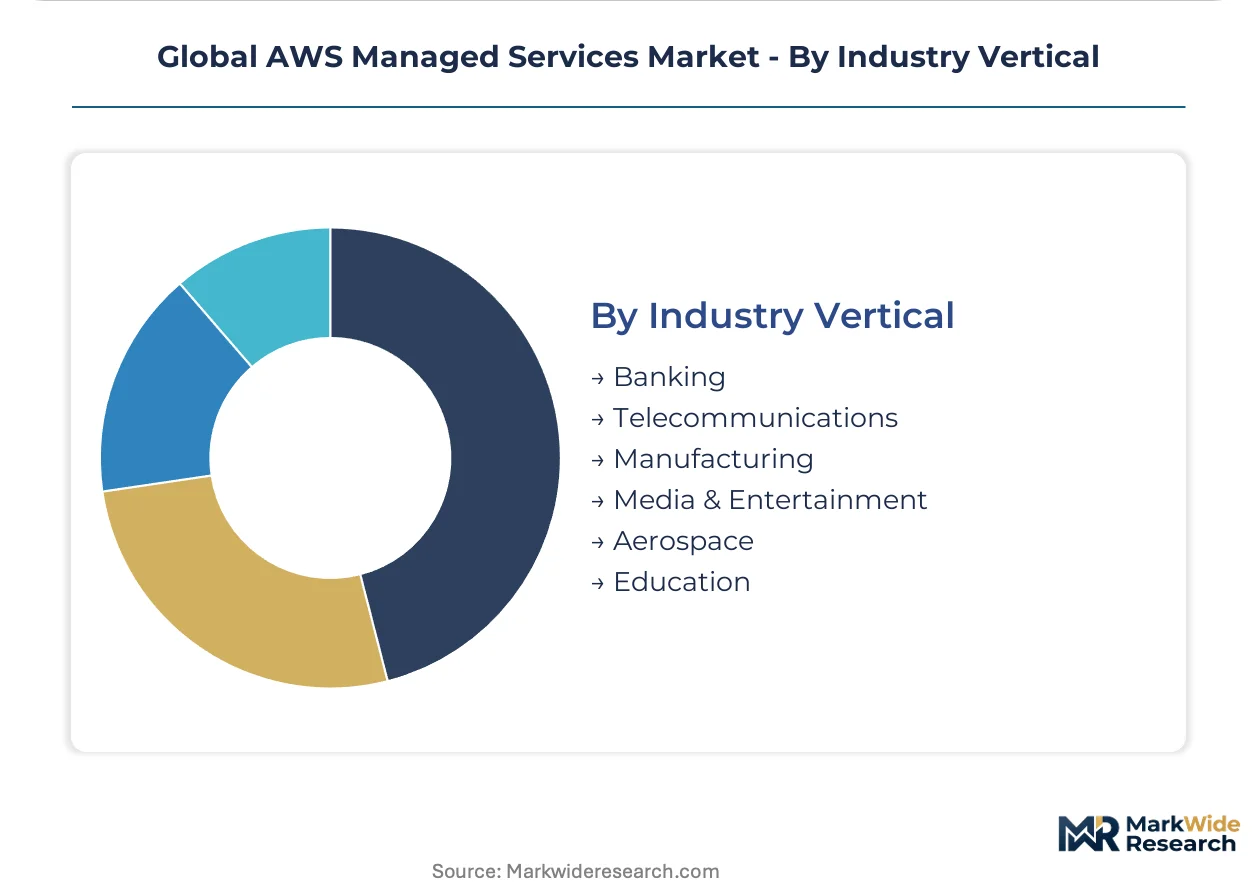
Application-specific requirements fragment service delivery, with Banking and Telecommunications demanding the most intensive compliance automation.
- Banking:PCI-DSS, SOX, and Basel III-aligned managed services with real-time fraud detection integration and audit-ready control documentation. US regional banks under SEC cybersecurity rules are consolidating MSP relationships to reduce third-party risk surface.
- Telecommunications:5G core network function virtualization, subscriber data management, and latency-sensitive edge orchestration on AWS Wavelength zones.
- Manufacturing:Industrial IoT data lake management, predictive maintenance pipelines, and OT-IT convergence security for German automotive and Japanese electronics supply chains.
- Media & Entertainment:Render farm burst capacity, content delivery optimization, and DRM-protected streaming infrastructure.
- Aerospace:ITAR-controlled workloads, digital twin simulation, and supply chain traceability on GovCloud partitions.
- Education:Learning management system hosting, research computing grants, and student data privacy compliance for FERPA-regulated institutions.
Banking holds the largest share; Manufacturing is expanding most quickly as industrial IoT data gravity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions and automotive manufacturers concentrate managed services procurement in jurisdictions with stringent data residency frameworks. Sovereign cloud configurations dominate vendor selection criteria across European financial centers and German industrial clusters.
United States
Hospital systems and regional banks drive HIPAA-compliant and SEC-audited managed services procurement. The SEC's cybersecurity disclosure rules mandate documented incident response protocols for publicly traded clients. Healthcare data gravity centers on Boston and Nashville hospital networks offloading infrastructure operations to MSPs with 24/7 security operations center coverage.
Germany
Automotive OEMs in Stuttgart and Frankfurt require pre-audited AWS environments with EU-notified body relationships for high-risk AI workload validation. The EU AI Act and GDPR mandate algorithmic transparency and data localization across manufacturing engineering centers. Sovereign cloud configurations dominate procurement from Bosch, Siemens, and BMW Group supply chain partners.
United Kingdom
Fintech challengers and Series C SaaS scaleups in London's payments infrastructure sector negotiate consumption-based contracting with pure-variable pricing. The Financial Conduct Authority's operational resilience requirements shape MSP selection for Stripe-integrated platforms. Unbundled advisory services tied to cloud spend reduction metrics are displacing fixed-fee arrangements.
Japan
Industrial conglomerates under METI cybersecurity guidelines maintain on-premises data lakes while bursting compute-intensive workloads to AWS through managed sovereign configurations. Automotive and electronics supply chains in Nagoya and Osaka require hybrid burst patterns for AI training pipelines. Sovereign cloud migration demand flows to export-led consultancies serving cross-border transformations.
India
The Bureau of Indian Standards' emerging data center certification framework creates first-mover opportunity for MSPs establishing local AWS Outposts with indigenous encryption controls. IT services exporters in Bangalore and Hyderabad drive demand for managed MLOps service lines. BIS cloud security standards are accelerating procurement among domestic fintechs and multinational captive centers.
Global AWS Managed Services Market Competitive Landscape
Player mix skews toward global systems integrators with multi-industry footprints and specialized cloud-native consultancies with accredited AWS competencies. Tiered accreditation requirements from the AWS MSP Partner Network are forcing channel consolidation as smaller consultancies face six-figure annual investments in certified staff training. Strategic archetypes include SAP migration bundlers, sovereign cloud specialists, and mainframe modernization embedders. Dominant competitive moves center on geographic expansion into Frankfurt and London financial centers and portfolio diversification into FinOps automation and generative AI operations.
Within the global systems integrator tier, Accenture leverages its multi-industry footprint to bundle SAP migrations with managed operations, while Capgemini anchors European demand through dedicated centers of excellence. DXC Technology Company occupies a position exemplifying mainframe modernization embedders, competing by integrating legacy COBOL connectivity into hybrid managed contracts. Rackspace represents the dedicated AWS specialist archetype, maintaining sovereign cloud configurations across North American and European financial services clients. These three entities collectively illustrate how accreditation density and vertical specialization determine competitive positioning.
| Leading Market Players |
|---|
| Accenture |
| Rackspace |
| DXC Technology Company |
| Claranet |
| Capgemini |
| Slalom |
| Onica |
| Cloudreach |
| Mission Cloud Services |
| Others |
Supply & Pricing Matrix
Ninety-day certification lead times for AWS MSP Partner Network competencies compress margin realization while amplifying pricing power for accredited incumbents. Supply chain concentration in India and Poland for platform engineering talent directly shapes cost structures across service tiers.
Pricing Analysis
Cost-plus contracts with annual AWS certification fee indexation dominate multi-year engagements. Three-tier pricing structure across premium sovereign cloud, standard hybrid, and economy public cloud tiers separates buyers by compliance exposure and data residency requirements. Price differentiation hinges on EU AI Act pre-audited environment availability and dedicated FinOps engineering bandwidth. Pricing pressure stems from consumption-based contracting adoption among UK fintech challengers unbundling advisory from 24/7 coverage. Startups exhibit highest price sensitivity; German automotive OEMs demonstrate lowest elasticity due to regulatory non-negotiability.
Supply Chain Analysis
Inbound logistics costs for AWS Outposts hardware face container availability constraints on Asia-Europe trade lanes extending deployment timelines. Supply concentrates in India for platform engineering talent, Ireland for EU data residency infrastructure, and Singapore for Asia-Pacific security operations center coverage. Raw material dependencies span specialized compute instances, indigenous encryption modules, and FedRAMP-compliant physical security components. Single-source vulnerability sits with AWS-native certification pathways controlling partner accreditation density. Distribution runs through direct enterprise sales, AWS Marketplace listings, and systems integrator sub-contracting networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German automotive OEMs and US hospital systems consolidate vendor relationships to reduce third-party risk surface under SEC cybersecurity disclosure rules and EU AI Act mandates.
For Market Incumbents: Compound accreditation density through sovereign cloud specialization investments in Frankfurt and London financial centers. Defend against emerging cloud-native consultancies by embedding generative AI operations capabilities and securing EU-notified body relationships for high-risk AI workload validation. Prioritize FinOps automation platform integration to offset pricing pressure from consumption-based contracting adoption. For New Entrants and Emerging Players: Differentiate on India BIS cloud security standards compliance as domestic fintech procurement accelerates. Target managed MLOps service lines for training workload optimization where platform engineering talent scarcity constrains incumbent expansion. Pursue AWS Outposts deployment partnerships with indigenous encryption control providers as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier consultancies facing six-figure annual certification cost barriers and channel consolidation pressure. Long-term viability favors specialists with documented EU AI Act compliance automation and carbon accounting dashboard capabilities. Watch AWS MSP Partner Network tier requirements as the inflection signal for accelerated M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | Frankfurt and Stuttgart automotive engineering centers mandate EU-notified body relationships for high-risk AI workload validation. |
| FinOps Automation Platform Integration | Real-time anomaly detection displaces manual tagging governance among US Series C SaaS scaleups seeking pure-variable pricing. |
| Generative AI Operations Service Line Launch | Convergence of LLM inference pipelines with cost optimization opens managed MLOps revenue streams. |
| India BIS Cloud Security Standards Compliance | Bureau of Indian Standards certification creates first-mover advantage for AWS Outposts with indigenous encryption controls. |
| Carbon Accounting Dashboard Development | EU Corporate Sustainability Reporting Directive mandates renewable energy matching tools for MSP selection criteria. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of AWS MSP Partner Network accreditation records, EU AI Act regulatory filings, and hyperscaler capex disclosures. Interviews with cloud procurement officers, platform engineering directors, and managed services contract negotiators informed demand-side validation. Secondary sources include SEC cybersecurity disclosure filings, GDPR enforcement actions, and METI cybersecurity guideline updates. Bottom-up service tier sizing triangulates against top-down cloud spend attribution models.
Segmentation dimensions modeled encompass service type, deployment architecture, client scale tier, and industry vertical regulatory exposure across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves for sovereign cloud configurations and compliance-heavy segments. Forecast inputs incorporate AWS certification pipeline capacity, EU AI Act implementation timelines, and platform engineering wage premium trajectories.
Material uncertainties — regulatory enforcement intensity, certification requirement modifications, and talent supply shocks — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained data residency fragmentation and hybrid cloud adoption continuity. Practitioners should keep alternative scenarios live as EU AI Act high-risk system classifications and SEC disclosure rule amendments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Asia-Pacific Enterprise Asset Management Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Shared Services Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Helpdesk Management Market