
 Aviation Record-Keeping Blockchain Market | 2026-2036
Aviation Record-Keeping Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Record-Keeping Blockchain Market Analysis
Multi-source blockchain procurement is expanding across aviation enterprises seeking resilience against vendor lock-in. IBM Corporation leverages its Hyperledger expertise to anchor enterprise-grade aviation deployments across maintenance and compliance workflows. Microsoft Corporation sustains cloud-integrated ledger offerings that compete on scalability with Azure-hosted infrastructure. Moog Inc. specializes in hardware-software convergence for secure flight-data recording, differentiating through embedded cryptographic modules.
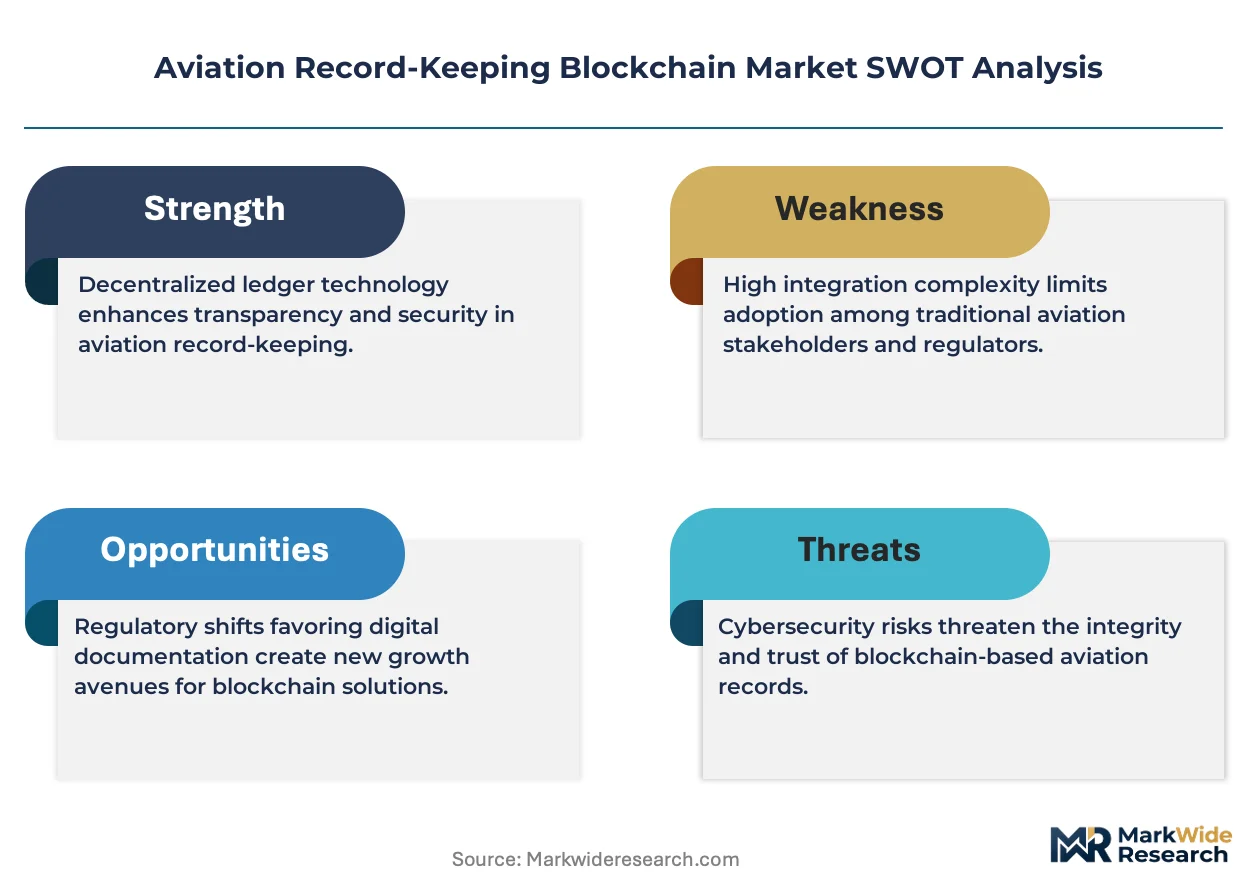
Aviation record-keeping blockchain denotes distributed ledger architectures engineered for tamper-evident logging of flight operations, maintenance events, and regulatory credentials, typically employing consensus mechanisms with sub-second finality and AES-256 encryption for data-at-rest. These systems serve to eliminate information asymmetry between airlines, regulators, and maintenance providers while automating audit trails through smart-contract execution. Private blockchain configurations currently dominate enterprise deployments where data sovereignty and permissioned access govern operational requirements, while consortium blockchain models are gaining traction among airline alliances seeking shared MRO transparency without full data exposure. Flight data management as a use case occupies the deepest margin pools due to the complexity of integrating real-time sensor streams with immutable archival.
The FAA mandates digital record integrity standards under Part 121 and Part 135 operating certificates, while EASA's MDR and EU AI Act provisions shape algorithmic auditability for automated compliance systems. China's NMPA and MIIT coordinate GB standards for aviation data security, creating fragmented but navigable certification pathways for cross-border platform providers. Stakeholders must monitor evolving interoperability mandates between national aviation authorities to determine ledger architecture investments that withstand multi-jurisdictional operational requirements.
Market Dynamics
Immutable ledger architectures are forcing aviation enterprises to rebuild data infrastructure around cryptographic verification rather than paper-based attestation. The FAA's Part 135 modernization timeline and EASA's digital record mandates are compressing procurement cycles for permissioned blockchain systems.
Growth Catalysts
- FAA Part 135 Digital Mandate:The FAA's operating certificate modernization requires tamper-evident maintenance logs, driving carrier investments in Hyperledger-based record systems.
- Sensor-to-ledger integration:Real-time flight data streaming from engine health monitoring units now writes directly to immutable archives, eliminating manual transcription errors.
- Airline alliance data sharing:Consortium blockchain models enable shared MRO transparency between partner carriers without exposing competitive operational data.
Market Restraints
- Legacy fleet integration costs:Retrofitting 1990s-era aircraft with IoT gateways and cryptographic modules demands capital outlays that regional carriers cannot absorb.
- Specialized talent scarcity:Blockchain architects with aviation domain knowledge command premium compensation, constraining deployment velocity for mid-tier operators.
- Cross-border data sovereignty:China's GB standards for aviation data security conflict with EU GDPR portability requirements, fragmenting platform architectures.
Strategic Opportunities
- Pilot credential portability:Tokenized certification records create interoperable licensing across jurisdictions, reducing re-certification friction for mobile flight crews.
- India's UDAN regional aviation expansion:The country's regional connectivity scheme generates greenfield demand for digitized record systems without legacy technical debt.
- AI Act algorithmic audit trails:EASA's automated compliance systems require immutable logging of decision pathways, opening specialized smart-contract markets.
Industry Challenges
- Multi-jurisdictional certification timelines:Simultaneous FAA, EASA, and CAAC approvals for flight-data recorders extend product launch windows by 18-24 months.
- Legacy ERP integration complexity:SAP and Oracle maintenance modules require custom API bridges to write to distributed ledgers without disrupting existing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Record-Keeping Blockchain Market |
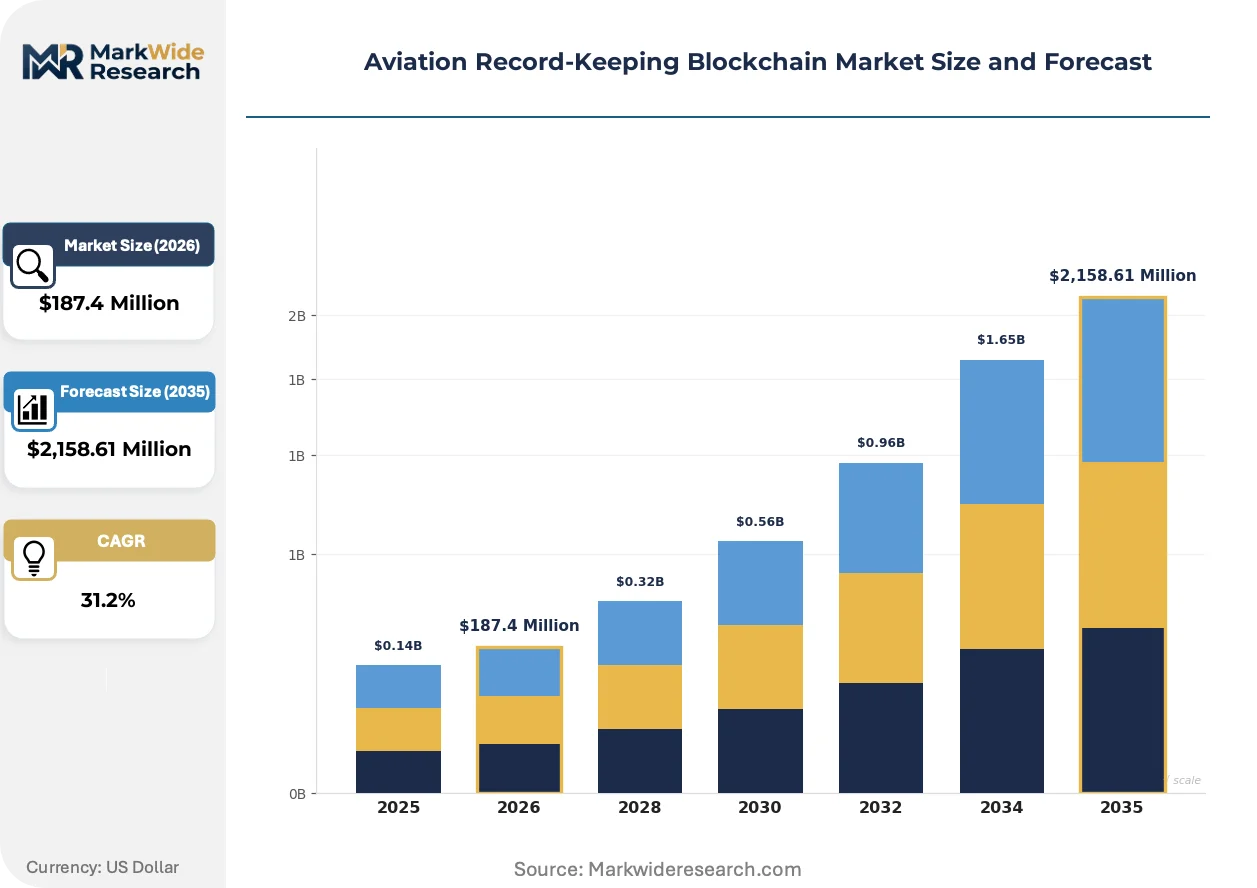
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,158.61 Million |
| CAGR (2026 – 2036) | 31.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Use Case: Flight Data Management, Maintenance Tracking, Compliance Assurance, Identity Verification End User: Airlines, MRO Providers, Regulatory Authorities, Ground Handling Services Service Type: Consulting, Integration, Support, Training |
| Companies Covered | IBM Corporation, Infosys Limited, Microsoft Corporation, Aeron Labs, Zamna Technologies, Winding Tree, LeewayHertz, Filament, Moog Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Record-Keeping Blockchain Market Emerging Trajectories
Aviation blockchain is pivoting from pilot projects to production-grade deployments as consensus latency drops below operational thresholds. Three convergent developments are restructuring competitive positioning around data finality speed and cross-carrier interoperability.
Zero-knowledge proof architectures are rewriting how sensitive flight data gets shared between competitors. These cryptographic protocols allow MRO providers to verify maintenance compliance without revealing proprietary operational metrics. Major carriers in the United States and Germany are piloting zk-SNARK implementations for engine performance benchmarking, compressing audit preparation from weeks to hours while preserving competitive confidentiality.
EASA's MDR and EU AI Act provisions are mandating algorithmic auditability for automated compliance systems. Airlines operating under EASA jurisdiction must now maintain immutable logs of AI-driven maintenance scheduling decisions. This regulatory pressure is accelerating procurement of smart-contract platforms that embed regulatory logic directly into execution code, particularly among low-cost carriers with lean compliance teams.
Maintenance procurement is consolidating around long-term platform partnerships rather than point solutions. Airlines are selecting single-vendor blockchain stacks for 10-15 year horizons, bundling flight data, crew credentials, and supply chain provenance into unified architectures. This behavioral shift is most visible among US network carriers, where procurement teams prioritize vendor stability over feature velocity in vendor selection criteria.
Aviation Record-Keeping Blockchain Market Segmentation
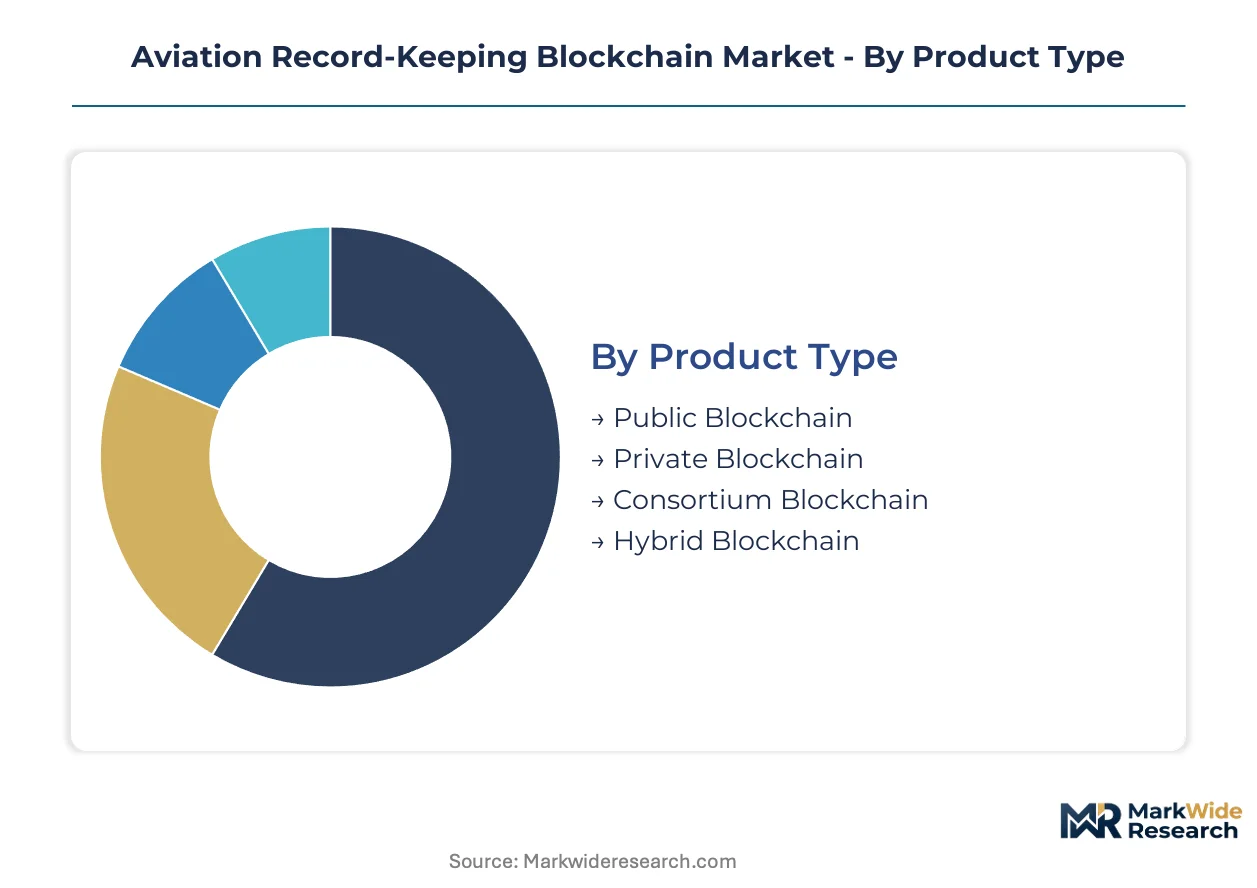
Aviation enterprises select blockchain architectures based on data sovereignty requirements and cross-carrier collaboration depth. Segment choices directly determine compliance pathway complexity and long-term vendor commitment.
Product Type:
Upgrade cycles for legacy record-keeping systems favor architectures that minimize disruption to existing ERP workflows while meeting emerging cryptographic mandates.
- Private Blockchain:Permissioned ledger configurations restrict node participation to pre-verified airline and MRO personnel, enabling sub-second transaction finality for maintenance logs. US network carriers favor this architecture for Part 135 compliance, prioritizing data control over interoperability.
- Consortium Blockchain:Multi-party governance structures distribute consensus authority across airline alliances without exposing proprietary operational data. Star Alliance and oneworld members pilot these models for shared MRO transparency.
- Public Blockchain:Open participation networks offer maximal transparency but introduce latency unacceptable for real-time flight data streaming. Experimental deployments concentrate in pilot credential verification pilots.
- Hybrid Blockchain:Dual-layer architectures isolate sensitive maintenance records on private chains while anchoring verification hashes to public networks for audit integrity.
Private Blockchain sits at the top of the volume ranking, with Consortium Blockchain climbing the fastest.
Use Case:
Application complexity varies sharply across operational domains, with sensor integration density and regulatory scrutiny determining deployment priority.
- Flight Data Management:Real-time ingestion of engine health monitoring and flight parameter streams demands consensus mechanisms capable of handling high-velocity sensor throughput. EASA's algorithmic auditability mandates under the EU AI Act accelerate procurement for automated decision logging.
- Maintenance Tracking:Immutable logging of component lifecycles and repair events eliminates information asymmetry between airlines and MRO providers. FAA Part 135 modernization compresses procurement timelines for US regional carriers.
- Compliance Assurance:Smart-contract automation of regulatory reporting reduces manual audit preparation from weeks to hours for low-cost carriers with lean compliance teams.
- Identity Verification:Tokenized pilot and technician credentials enable cross-jurisdictional license portability without re-certification friction.
Maintenance Tracking commands the largest deployment base, while Flight Data Management exhibits the steepest expansion trajectory.
End User:
Customer type determines procurement scale and integration complexity, with legacy technical debt varying dramatically across operator categories.
- Airlines:Full-service and low-cost carriers drive platform standardization, bundling flight data, crew credentials, and supply chain provenance into unified architectures spanning 10-15 year vendor commitments.
- MRO Providers:Third-party maintenance specialists seek zero-knowledge proof capabilities to verify compliance without revealing competitive operational metrics to airline clients.
- Regulatory Authorities:FAA, EASA, and CAAC procurement of audit infrastructure creates demand for read-only node access and cross-border data portability standards.
- Ground Handling Services:Ramp operations and cargo handlers adopt lightweight credential verification modules for subcontractor workforce management.
Airlines anchor current procurement volume, with MRO Providers gaining share fastest as outsourcing trends deepen.
Service Type:
Service mix reflects the gap between aviation domain expertise and distributed ledger technical capability among operator staff.
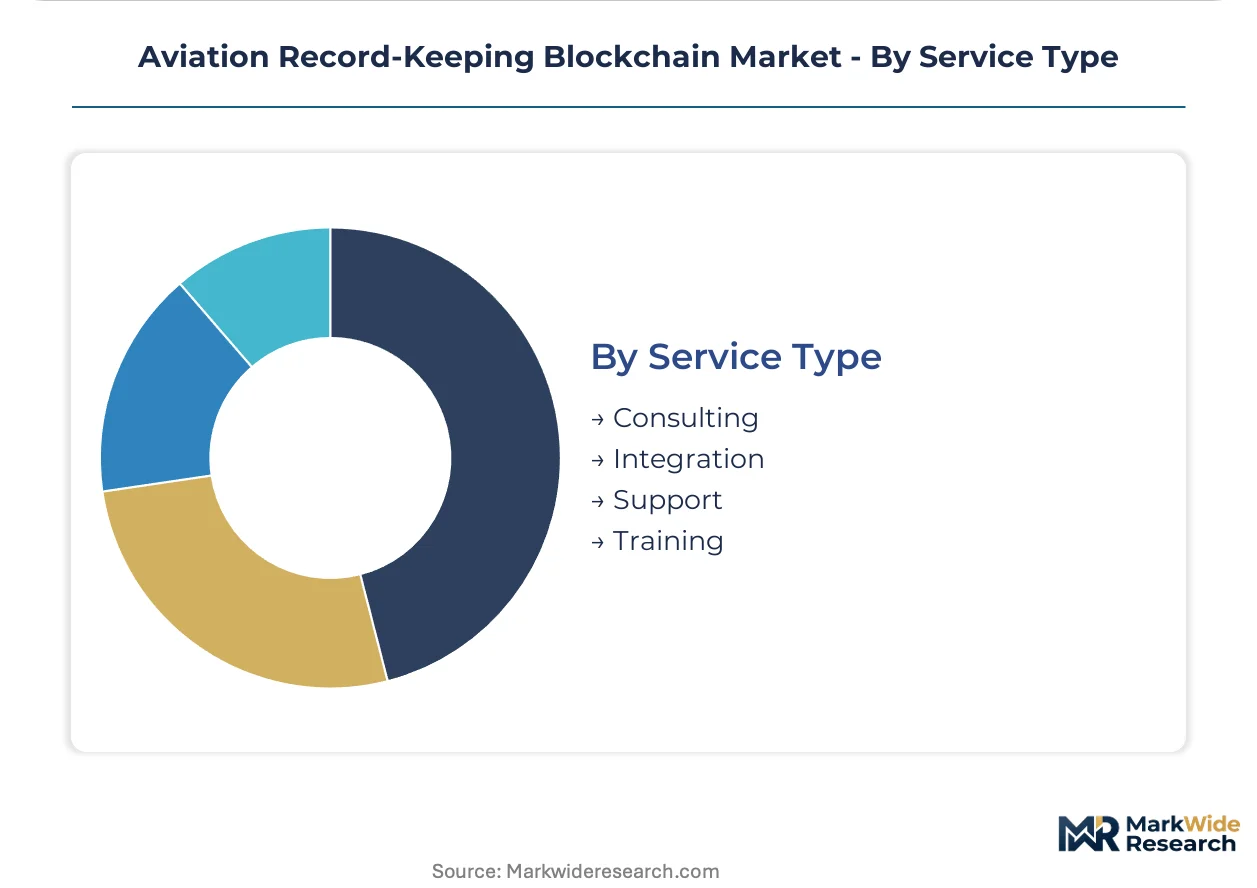
- Integration:Custom API bridges connecting SAP and Oracle maintenance modules to Hyperledger Fabric or R3 Corda dominate professional services revenue, particularly for US network carriers with complex legacy ERP estates.
- Consulting:Architecture design and regulatory pathway navigation command premium pricing given the scarcity of blockchain architects with aviation certification knowledge.
- Support:24/7 node monitoring and consensus troubleshooting ensures continuous availability for flight-critical record systems.
- Training:Crew and maintenance staff certification on cryptographic key management and smart-contract interaction protocols.
Integration services lead current revenue, with Consulting expanding most quickly as regulatory mandates multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle-Tacoma anchors global aviation blockchain procurement, with Boeing's engineering ecosystem and AWS cloud infrastructure creating concentrated demand for flight-data ledger systems. FAA Part 135 mandates and legacy fleet digitization initiatives are compressing deployment timelines across North American carriers.
United States
Network carriers in Dallas-Fort Worth and Atlanta drive enterprise-scale Hyperledger deployments for maintenance log integrity. FAA Part 121 and Part 135 operating certificate modernization requires tamper-evident record systems by 2027. Chicago's MRO corridor hosts pilot programs for sensor-to-ledger integration on narrow-body retrofits.
Germany
Lufthansa Group and Lufthansa Technik in Hamburg anchor European demand for zero-knowledge proof architectures in MRO benchmarking. EASA's MDR and EU AI Act algorithmic auditability mandates accelerate smart-contract procurement for automated compliance. Munich's aerospace cluster pilots zk-SNARK implementations for engine performance verification without data exposure.
China
COMAC and state-owned carriers in Shanghai generate procurement for GB-standard aviation data security platforms. NMPA and MIIT coordinate certification pathways for cross-border ledger providers under national data sovereignty requirements. Beijing's regulatory technology corridor tests hybrid blockchain models isolating sensitive maintenance records from public verification anchors.
India
UDAN regional aviation expansion creates greenfield demand in Mumbai and Bengaluru for digitized record systems without legacy technical debt. DGFT and Ministry of Civil Aviation coordinate digital infrastructure standards for tier-2 airport connectivity. Hyderabad's IT corridor hosts development centers for tokenized pilot credential verification platforms.
United Kingdom
Heathrow-based carriers and Gatwick MRO specialists pursue GDPR-compliant ledger architectures for cross-border crew certification portability. The Civil Aviation Authority's digital record-keeping guidance shapes procurement specifications for low-cost operators. London's fintech-aviation intersection drives experimentation in tokenized licensing for mobile flight crews.
Aviation Record-Keeping Blockchain Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue consortium governance and zero-knowledge specialization. The vendor base distributes across three maturity tiers: legacy technology conglomerates with aviation verticals, blockchain-native specialists with aerospace domain knowledge, and hardware-software convergence players with embedded cryptographic capabilities. Dominant competitive moves include long-term platform partnerships spanning 10-15 year horizons and strategic API bridge development for SAP and Oracle ERP integration.
Within the enterprise technology tier, IBM Corporation and Microsoft Corporation exemplify cloud-integrated ledger offerings competing on scalability and regulatory pathway navigation. Moog Inc. occupies a distinct position among hardware-software convergence specialists, differentiating through embedded cryptographic modules for secure flight-data recording. These three anchors represent divergent strategic bets: enterprise-grade infrastructure deployment, cloud-native scalability, and physical-digital system integration.
| Leading Market Players |
|---|
| IBM Corporation |
| Infosys Limited |
| Microsoft Corporation |
| Aeron Labs |
| Zamna Technologies |
| Winding Tree |
| LeewayHertz |
| Filament |
| Moog Inc. |
| Others |
Supply Flow & Price Mechanics
FAA Part 135 digital mandate compression is forcing blockchain vendors to absorb legacy integration costs while maintaining SaaS margins, reshaping how platform providers structure long-term carrier contracts and hardware-software bundling.
Pricing Analysis
Embedded cryptographic module costs pass through to end-users via tiered subscription structures anchored to fleet size and sensor integration density. Pricing stratifies across enterprise-grade Hyperledger deployments, mid-tier consortium configurations, and lightweight credential-verification modules for regional operators. Cost compression in the mid-market intensifies because IBM and Microsoft cloud-integrated offerings commoditize base-layer consensus infrastructure. Regional carriers with thin IT budgets exhibit highest price sensitivity, while US network carriers prioritize vendor stability and 10-15 year partnership horizons over per-seat economics.
Supply Chain Analysis
China's GB standards for aviation data security and domestic-content mandates in India's UDAN scheme are reshaping sourcing patterns for cryptographic hardware and ledger infrastructure. Manufacturing concentrates in the United States for FAA-certified flight-data recorders, Germany for EASA-compliant engine monitoring systems, and China for cost-optimized IoT gateway components. Supply chains draw from specialized semiconductor foundries for AES-256 encryption chips, aerospace-grade sensor manufacturers, and cloud infrastructure providers. Single-source vulnerability runs through embedded cryptographic module suppliers certified to multiple aviation authorities simultaneously. Distribution runs through direct enterprise sales teams for major carriers and systems integrators for mid-tier operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aviation blockchain hinges on automation of legacy ERP integration workflows, reducing professional services drag as carriers demand faster deployment timelines.
For Market Incumbents: Lock in long-term platform partnerships by embedding smart-contract logic directly into FAA and EASA compliance workflows before regulatory mandates harden technical specifications. Acquire specialized aviation-domain blockchain architects to defend against talent scarcity constraining deployment velocity for mid-tier operators. Prioritize API bridge development for SAP and Oracle maintenance modules to deepen switching costs. For New Entrants and Emerging Players: The price-point gap between premium enterprise Hyperledger deployments and economy-tier credential-verification modules creates white-space for zero-knowledge proof specialization in MRO benchmarking. Target India's UDAN regional aviation expansion with greenfield digitization offerings unburdened by legacy technical debt. Pursue pilot credential portability as the most penetrable use case, leveraging tokenized licensing friction reduction for mobile flight crews as the go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with hardware-software convergence specialists with embedded cryptographic capabilities and multi-jurisdictional certification traction. The 5-10 year viability window favors platforms already navigating simultaneous FAA, EASA, and CAAC approval timelines. Watch for EASA algorithmic auditability mandate enforcement as the inflection signal accelerating smart-contract procurement among low-cost carriers.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Knowledge Proof Specialization | zk-SNARK implementations for Lufthansa Technik engine benchmarking compress audit preparation while preserving competitive confidentiality. |
| Long-Term Platform Partnership | 10-15 year vendor commitments from US network carriers bundle flight data, crew credentials, and supply chain provenance into unified architectures. |
| Regulatory Pathway Navigation | Simultaneous FAA Part 135, EASA MDR, and EU AI Act compliance positioning extends product launch windows but locks out unqualified competitors. |
| Sensor-to-Ledger Integration | Real-time engine health monitoring unit streaming eliminates manual transcription errors and creates recurring data-ingestion revenue streams. |
| Consortium Governance Model | Star Alliance and oneworld shared MRO transparency pilots distribute consensus authority without exposing proprietary operational metrics. |
Methodological Framework
Multiple input streams — primary interviews with airline CTOs, MRO procurement directors, and regulatory compliance officers, alongside secondary validation through FAA docket filings, EASA regulatory impact assessments, and hyperscaler aviation vertical disclosures — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations captured deployment timelines, vendor selection criteria, and integration complexity factors across North American, European, and Asia-Pacific carrier archetypes.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning private, consortium, and hybrid blockchain architectures; flight data management, maintenance tracking, compliance assurance, and identity verification use cases; and airlines, MRO providers, regulatory authorities, and ground handling services end-user categories. CAGRs were derived from modeled adoption curves incorporating FAA Part 135 modernization timelines and EASA digital mandate enforcement patterns.
Caveats apply where multi-jurisdictional certification timeline extensions, legacy ERP integration complexity overruns, or cross-border data sovereignty fragmentation could materially shift the outlook. Forecasts reflect assumptions regarding regulatory mandate adherence schedules and carrier procurement cycle normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Global Blockchain Software Market
Blockchain Technology
Blockchain in Sports Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Tokenization Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Decentralized Identity Market