
 Broadcasting Equipment Market | 2026-2036
Broadcasting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Broadcasting Equipment Market Analysis
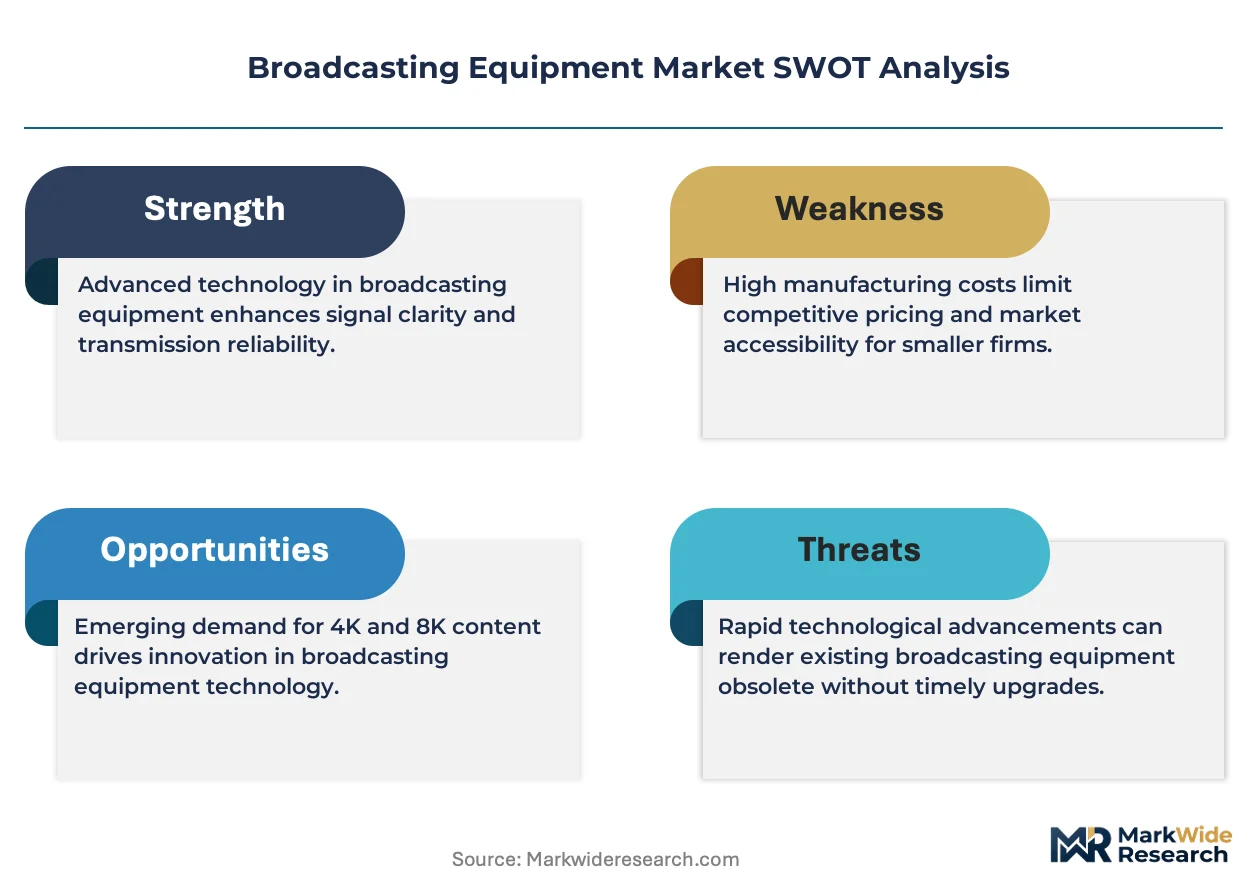
Ultra-high-definition production tiers is redrawing competitive boundaries across the Broadcasting Equipment landscape. Sony Corporation leverages its imaging sensor heritage to dominate cinema-grade camera modules for live sports. Grass Valley sustains engineering depth in real-time production switchers that broadcast stations still specify for flagship studios.
Broadcasting equipment comprises signal acquisition, processing, routing, and distribution hardware engineered to operate within strict latency tolerances, typically sub-frame at 16.67ms for 60Hz workflows, enabling real-time audiovisual transmission to mass audiences. Video encoders lead technology investment as broadcasters migrate MPEG-2 infrastructure to HEVC and AV1 compression to conserve bandwidth without perceptible quality loss. IP-based architectures represent the fastest-expanding technology segment, displacing dedicated SDI cabling with SMPTE ST 2110 packetized flows that collapse separate audio, video, and data infrastructures into unified Ethernet fabrics.
The FCC mandates ATSC 3.0 next-generation broadcast standards, while the EBU coordinates spectral efficiency frameworks across European public broadcasters, and China's MIIT governs terrestrial digital television transmission protocols that shape product certification requirements. Regulatory divergence across these jurisdictions fragments testing regimes and extends product development cycles for multinational vendors. Stakeholders must track which spectrum allocation decisions and emission standards win adoption in priority markets before committing manufacturing capacity to specific modulation or interface configurations.
Market Dynamics
The Broadcasting Equipment market is undergoing a fundamental architectural transition as IP-based packetized workflows replace dedicated SDI infrastructures, compressing capital deployment timelines while expanding interoperability requirements across hybrid production environments.
Growth Catalysts
- ATSC 3.0 mandate:The FCC's next-generation broadcast standard compels US stations to upgrade transmission chains, creating immediate demand for compatible encoders, modulators, and monitoring systems.
- Cloud-native production:Streaming platforms and national broadcasters are procuring virtualized production switchers and software-defined routing to enable distributed remote workflows.
- China network modernization:State broadcasters under MIIT direction are replacing legacy terrestrial transmitters with digital infrastructure across provincial networks.
Market Restraints
- Semiconductor supply concentration:FPGA and high-speed ADC shortages from concentrated Asian foundries extend lead times for video processing hardware.
- Regulatory fragmentation:Divergent emission standards between FCC, EBU spectral frameworks, and China's MIIT protocols multiply certification costs for multinational vendors.
- Capital intensity barrier:Full IP migration requires simultaneous replacement of cameras, routers, and control surfaces, freezing mid-tier broadcaster upgrade cycles.
Strategic Opportunities
- India terrestrial expansion:TRAI-mandated digital switchover in secondary cities creates greenfield demand for transmitters and headend equipment.
- 5G broadcast convergence:3GPP Release 16 broadcast capabilities enable hybrid terrestrial-mobile distribution architectures for live sports.
- Remote production as-a-service:Cloud-based production suites allow regional broadcasters to access flagship-tier capabilities without studio capital expenditure.
Industry Challenges
- IP timing synchronization:SMPTE ST 2059 PTP implementation demands specialized network engineering scarce outside major metropolitan clusters.
- Legacy integration complexity:Hybrid SDI-IP facilities require signal format translation at every boundary, multiplying failure points and maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broadcasting Equipment Market |
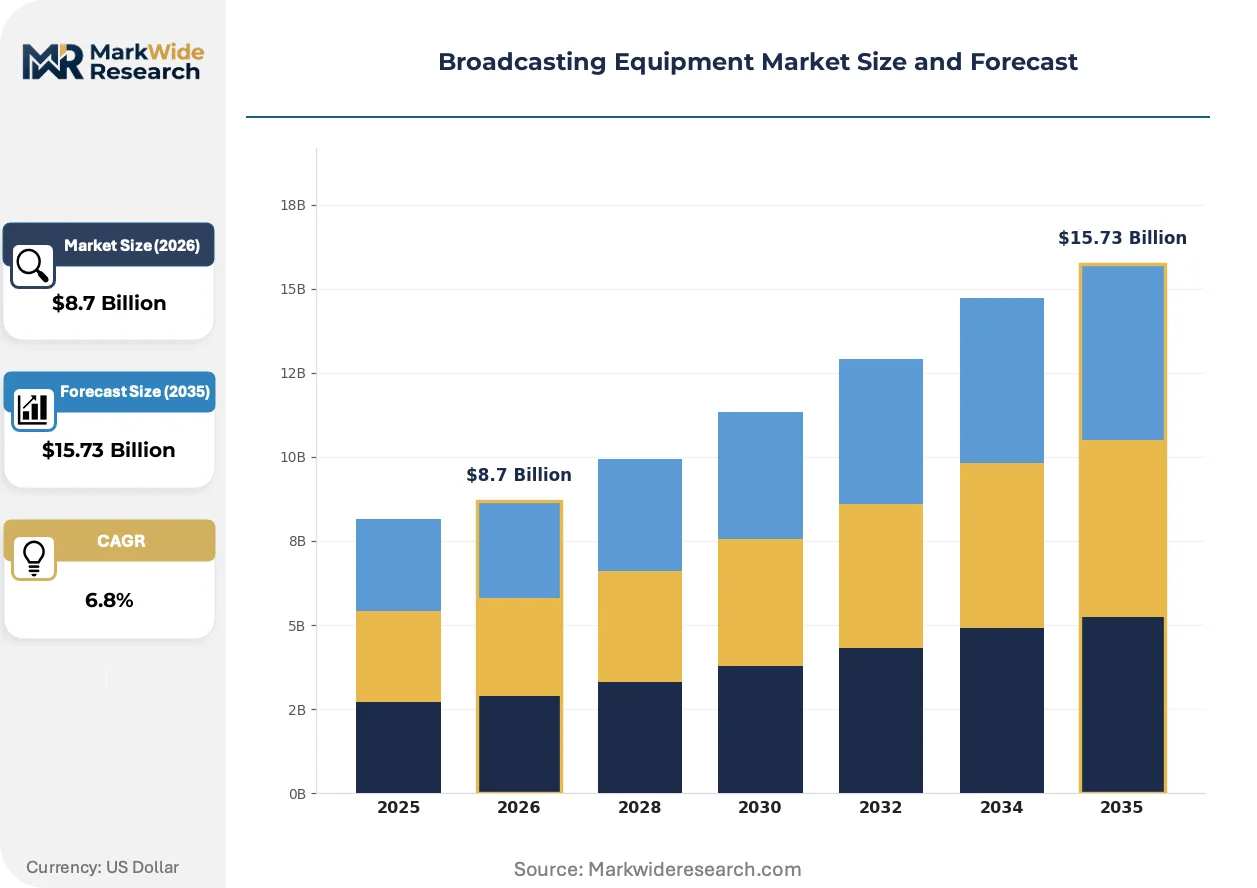
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Processors, Video Encoders, Signal Routers, Transmitters Technology: Analog, Digital, IP-Based, Cloud-Enabled Application: Television Broadcasting, Radio Broadcasting, Live Streaming, Content Creation End User: Broadcast Stations, Media Companies, Streaming Platforms, Independent Producers |
| Companies Covered | Cisco Systems Inc, Telefonaktiebolaget LM Ericsson, CommScope, Evertz Microsystems Ltd, Harmonic Inc, EVS Broadcast Equipment, Grass Valley, Sony Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broadcasting Equipment Market Emerging Trajectories
Broadcast infrastructure is compressing from purpose-built hardware stacks toward software-defined platforms, enabling functional reconfiguration without physical replacement. This shift is redrawing vendor competitive boundaries around codec efficiency, cloud orchestration, and subscription-based commercial models.
SMPTE ST 2110 packetized video transport is displacing baseband SDI as the dominant studio interconnect. National broadcasters in Germany and Japan are deploying full-facility IP routing for live production. This displacement collapses separate audio, video, and metadata infrastructures into unified Ethernet fabrics, reducing cabling mass and enabling dynamic resource allocation across facility locations.
The EU's F-Gas Regulation is accelerating transmitter cooling system redesign. Vacuum-tube power amplifiers face phase-out timelines for high-global-warming-potential refrigerants. Solid-state transmitter architectures using liquid cooling loops are gaining preference in Scandinavian and Benelux public broadcaster procurement specifications.
Equipment procurement is consolidating toward outcome-based performance contracts. Major sports rights holders now specify latency, availability, and format support thresholds rather than hardware SKUs. French and Italian broadcast consortiums have adopted service-level agreements with financial penalties for transmission failures, transferring operational risk to systems integrators.
Broadcasting Equipment Market Segmentation
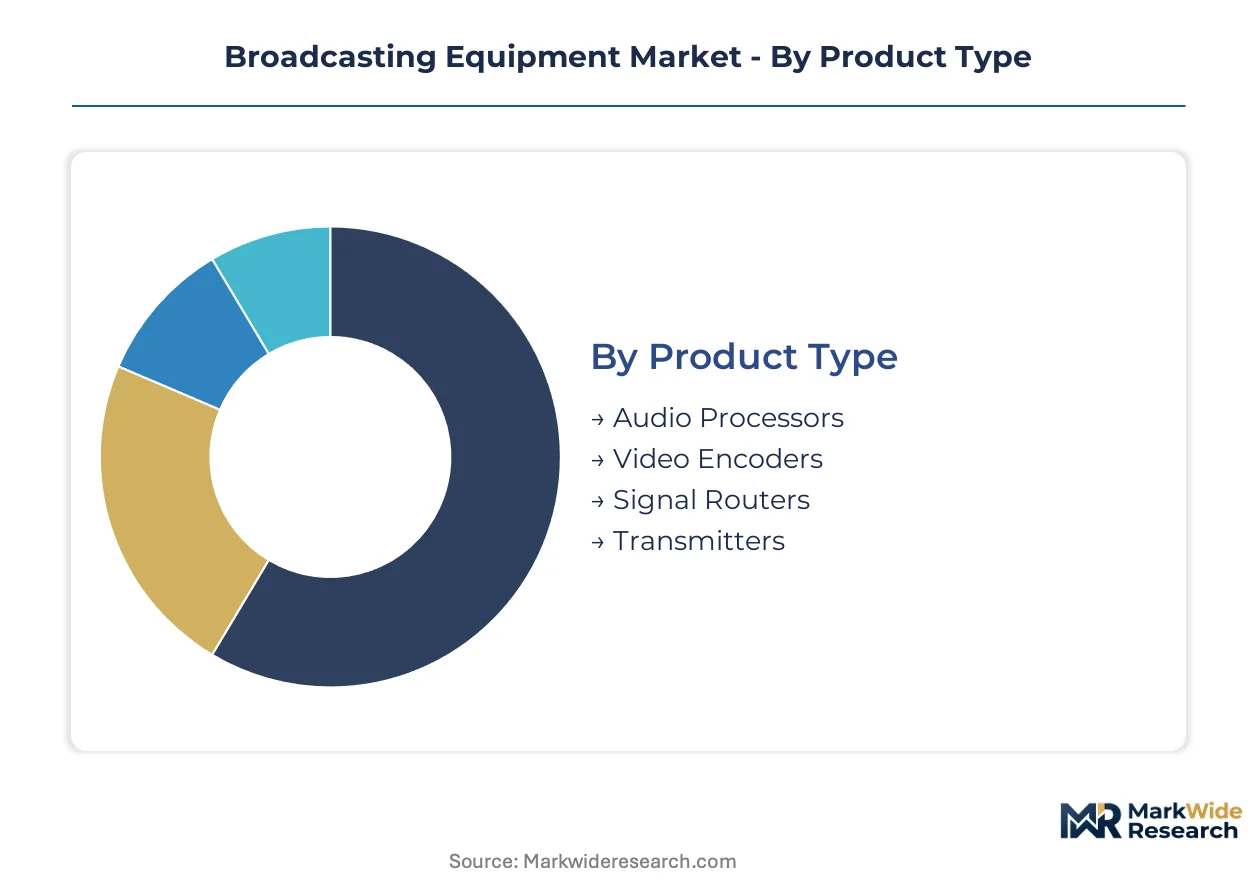
Broadcasting equipment segmentation reveals how capital allocation priorities differ across infrastructure tiers. Product architecture choices cascade through technology adoption curves and end-user procurement specifications.
Product Type:
Margin pools concentrate in processing and encoding hardware where codec transitions create recurring replacement cycles.
- Video Encoders:Hardware and software systems compress raw video into distribution-ready formats using HEVC, AV1, or VVC algorithms. US broadcast stations under FCC ATSC 3.0 mandates are replacing MPEG-2 infrastructure, while European public broadcasters prioritize bandwidth efficiency for multiplexed terrestrial channels.
- Transmitters:Radio-frequency amplification systems convert baseband signals to broadcast-ready electromagnetic waves. China's provincial network modernization under MIIT direction drives concentrated demand for solid-state architectures with liquid cooling to meet EU F-Gas Regulation environmental standards.
- Audio Processors:Real-time mixing, equalization, and loudness normalization engines for broadcast chains.
- Signal Routers:Crosspoint switching matrices directing video, audio, and metadata between facility destinations.
The dominant share belongs to Video Encoders, while Transmitters is closing the gap fastest.
Technology:
Procurement velocity varies sharply by infrastructure maturity, with greenfield deployments skipping legacy generations entirely.
- IP-Based:SMPTE ST 2110 packetized workflows replace dedicated SDI cabling with unified Ethernet transport for video, audio, and metadata. German and Japanese national broadcasters have deployed full-facility IP routing, though hybrid SDI-IP boundaries multiply integration complexity for regional stations.
- Cloud-Enabled:Virtualized production switchers and software-defined routing accessed via subscription models. Streaming platforms and sports rights holders specify latency thresholds and availability SLAs rather than hardware ownership, transferring operational risk to systems integrators.
- Digital:Compressed baseband systems using ASI or SDI interconnects with embedded signaling.
- Analog:Legacy composite and component video infrastructure in phased retirement across developed markets.
IP-Based systems command the largest installed base investment, though Cloud-Enabled configurations are expanding most quickly among streaming-native operators.
Application:
Content format requirements dictate equipment specification tiers, with live production demanding the tightest latency tolerances.
- Television Broadcasting:Terrestrial, cable, and satellite transmission chains with regulatory-mandated technical standards. FCC ATSC 3.0 next-generation broadcast standards compel US station groups to upgrade transmission chains, creating immediate demand for compatible encoders and monitoring systems.
- Live Streaming:Internet-delivered real-time content with adaptive bitrate packaging. 5G broadcast convergence under 3GPP Release 16 enables hybrid terrestrial-mobile distribution architectures for live sports, requiring synchronized encoding across multiple delivery paths.
- Radio Broadcasting:Audio-focused transmission with RDS and HD Radio data services.
- Content Creation:Production and post-production facilities generating library assets for delayed distribution.
Television Broadcasting retains the deepest equipment footprint, yet Live Streaming is gaining share fastest as sports rights migrate to direct-to-consumer platforms.
End User:
Capital intensity barriers segment procurement behavior, with scale determining whether ownership or service models prevail.
- Streaming Platforms:Technology-native operators building cloud-first infrastructure without legacy facility constraints. These buyers procure virtualized production suites and software-defined routing, enabling distributed remote workflows without studio capital expenditure.
- Broadcast Stations:Licensed terrestrial and satellite operators with regulatory compliance obligations. US station groups balance FCC mandate-driven upgrades against semiconductor supply concentration extending lead times for FPGA-dependent hardware.
- Media Companies:Multi-platform content owners integrating broadcast and streaming operations.
- Independent Producers:Freelance and small-studio operators accessing production capabilities via rental or subscription.
Broadcast Stations represent the largest historical customer base, while Streaming Platforms are climbing the fastest as content investment shifts to direct-to-consumer models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FPGA and high-speed ADC supply chains cluster in Taiwan and South Korea, compressing lead times for broadcast hardware manufacturers serving diverse regulatory environments. National spectrum policies and transmitter modernization programs are redrawing procurement geography.
United States
Station groups under FCC ATSC 3.0 mandates are replacing MPEG-2 encoding chains with HEVC infrastructure. The FCC's spectrum repackaging deadlines force transmitter upgrades across mid-market affiliates. Atlanta and Dallas-Fort Worth anchor regional broadcast clusters where systems integrators concentrate deployment capacity.
Germany
Public broadcasters under ARD and ZDF coordination are deploying full-facility SMPTE ST 2110 IP routing for live production. The EU F-Gas Regulation accelerates solid-state transmitter adoption with liquid cooling systems. Munich and Cologne host engineering centers where broadcast technology vendors customize products for EBU spectral efficiency frameworks.
China
State broadcasters directed by MIIT are modernizing provincial terrestrial networks with digital infrastructure. GB standards for terrestrial digital television transmission shape product certification requirements. Beijing and Shanghai concentrate procurement decisions for national network upgrades while Shenzhen supplies component manufacturing.
Japan
NHK and commercial broadcasters are integrating 8K production capabilities for live sports transmission. METI coordinates technical standards for next-generation broadcast architectures. Tokyo and Osaka anchor broadcast engineering clusters where domestic vendors customize equipment for NHK's Super Hi-Vision specifications.
India
TRAI-mandated digital switchover in secondary cities creates greenfield demand for transmitters and headend equipment. The Ministry of Information and Broadcasting directs terrestrial network expansion into underserved regions. Mumbai and Bengaluru concentrate systems integration capabilities for regional broadcaster upgrades.
Broadcasting Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the broadcasting equipment landscape. Japanese and European incumbents dominate imaging sensor and real-time processing tiers, while Chinese and Taiwanese fabricators capture volume production of encoding and transmission hardware. Two strategic archetypes define competitive positioning: integrated systems houses delivering end-to-end facility infrastructure, and specialized component suppliers focusing on single-function excellence. Consolidation through strategic partnerships and geographic licensing agreements represents the dominant competitive move, alongside backward integration into FPGA and ADC supply chains.
Within the integrated systems tier, Cisco Systems Inc and Sony Corporation exemplify divergent strategic positions. Cisco Systems Inc occupies a position emphasizing network infrastructure convergence for IP-based broadcast workflows. Sony Corporation anchors the imaging-centric archetype, leveraging sensor heritage for cinema-grade acquisition modules. Grass Valley sits within the broadcast-native engineering tier, sustaining specification dominance for real-time production switchers that flagship studios continue to mandate. These three represent the spectrum from IT-native to broadcast-purist competitive positioning.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| Telefonaktiebolaget LM Ericsson |
| CommScope |
| Evertz Microsystems Ltd |
| Harmonic Inc |
| EVS Broadcast Equipment |
| Grass Valley |
| Sony Corporation |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Taiwan's leading FPGA foundries shapes price floors across video processing hardware tiers, compressing margins for mid-range encoders while concentrating premium pricing power among vendors with captive semiconductor supply.
Pricing Analysis
FCC ATSC 3.0 mandates dictate the pricing tier structure across US broadcast equipment procurement, with HEVC-compatible encoder configurations commanding premium positioning against legacy MPEG-2 alternatives. Three-tier pricing stratifies across premium cinema-grade camera modules, standard studio production chains, and economy-tier regional broadcaster packages. Cost compression in mid-market switchers intensifies because cloud-native production alternatives eliminate capital expenditure barriers. Streaming platforms exhibit lowest price sensitivity due to subscription-model operational flexibility, while independent producers face acute budget constraints driving rental-market preference.
Supply Chain Analysis
Taiwan Strait shipping lanes underpin critical FPGA and high-speed ADC delivery schedules for broadcast hardware manufacturers. Component sourcing draws from Taiwan, South Korea, and Japan for advanced semiconductors, with China supplying aluminum enclosures and passive thermal management systems. Single-source vulnerability concentrates in 7nm and 5nm foundry capacity for programmable logic devices. Distribution runs through systems integrators holding regional deployment contracts with national broadcasters and streaming platform engineering divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATSC 3.0 regulatory mandates and IP-based workflow disruption create a high-growth inflection window where technology transition winners will consolidate market position before cloud-native alternatives mature.
For Market Incumbents: Fortify engineering depth in real-time production switchers against cloud-native virtualization threats by deepening backward integration into FPGA supply chains and expanding certification engineering capacity for EBU spectral efficiency frameworks. Prioritize outcome-based service contracts with sports rights holders to transfer operational risk and lock recurring revenue streams. For New Entrants and Emerging Players: CE marking fast-track pathways for liquid-cooled solid-state transmitters open procurement access to Scandinavian and Benelux public broadcasters facing EU F-Gas Regulation compliance deadlines. Target India's TRAI-mandated digital switchover in secondary cities as the most penetrable geography, leveraging systems integrator partnerships for localized deployment capability without legacy facility retrofit burden. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized component suppliers with single-function excellence in codec efficiency and cloud orchestration layers over integrated systems houses facing margin compression. Long-term viability hinges on differentiation defensibility against hyperscaler vertical integration into broadcast infrastructure. Monitor 3GPP Release 16 broadcast capability adoption rates as the critical inflection signal for hybrid terrestrial-mobile architecture investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into FPGA Supply | Captive semiconductor access insulates Sony and Grass Valley from Taiwan foundry allocation volatility. |
| Cloud-Native Production Platform Launch | Virtualized switcher deployment enables Evertz Microsystems to capture streaming platform procurement outside traditional broadcast cycles. |
| SMPTE ST 2110 Certification Investment | Full-facility IP routing credentials unlock German ARD and ZDF specification requirements for flagship studio infrastructure. |
| Outcome-Based Service Contract Expansion | Harmonic Inc transfers transmission failure risk to systems integrators through French and Italian broadcaster SLA structures. |
| India Systems Integrator Partnership | Regional deployment alliances position CommScope for TRAI-mandated transmitter procurement in secondary city markets. |
Methodological Framework
A spread of perspectives from broadcast engineering directors, streaming platform CTOs, systems integrator procurement leads, and semiconductor supply chain managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC filing databases, EBU technical standards documentation, MIIT GB certification registries, and customs trade data for broadcast equipment imports. Bottom-up equipment procurement modeling triangulated against top-down market sizing from national broadcaster capital expenditure disclosures.
Segmentation dimensions modeled span product type, technology architecture, application format, and end-user capital intensity tier across the projection horizon. CAGRs derive from equipment replacement cycle analysis, regulatory mandate implementation schedules, and greenfield deployment velocity in emerging markets. Forecast inputs incorporate FPGA lead time fluctuations, spectrum reallocation timelines, and cloud-native production adoption curves specific to sports rights holder procurement patterns.
Decision-makers should treat outputs as directional under assumptions of sustained semiconductor supply normalization and stable regulatory enforcement timelines; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as 3GPP Release 16 broadcast capability deployment and EU F-Gas Regulation phase-out schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Global Volt/VAR Management Market
Electronic Devices & Electrical Systems
Global Hybrid Devices Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market
Electronic Devices & Electrical Systems
Global Sequence of Events Recorder Market
Electronic Devices & Electrical Systems
Blu-Ray Media and Devices Market
Electronic Devices & Electrical Systems
Global Automotive Electronic Devices Market
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
USB Devices Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
High Current Springs Market
Electronic Devices & Electrical Systems
Electronic Skin Market
Electronic Devices & Electrical Systems
Electronic Treadle Market