
 Smart Pet Kennel Market | 2026-2036
Smart Pet Kennel Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pet Kennel Market Insights
Subscription leasing and asset-light ownership models is tilting competitive dynamics toward players with recurring-revenue infrastructure. PetSafe Brands leverages its channel control across veterinary and retail networks to sustain hardware attach rates. MidWest Homes for Pets anchors its position through manufacturing scale in metal and polymer enclosure production. Dogness International Corporation specializes in IoT-integrated feeding and monitoring systems that differentiate on software connectivity rather than commodity cage construction.
A smart pet kennel is an electronically enhanced enclosure incorporating sensors, climate modules, and wireless communication hardware to monitor animal welfare, automate feeding cycles, and transmit biometric or environmental data to remote caregivers. Units typically integrate temperature probes, cameras, and RFID or cellular gateways operating on 2.4 GHz or sub-GHz bands for real-time status alerting. Automatic feeders and smart cameras command the dominant revenue share as pet owners prioritize visible reassurance and dietary precision during absences. Wi-Fi connectivity leads installation volumes in residential settings while cellular modules capture growth among kennel operators requiring off-grid reliability in rural or multi-site deployments. AI features represent the fastest-expanding technology segment as machine learning enables anomaly detection in pet behavior patterns.
FCC Part 15 rules in the United States and CE marking under the EU Radio Equipment Directive shape electromagnetic compliance costs and certification timelines for connected kennel hardware. REACH and RoHS constraints in Europe limit certain plastics and coatings in enclosure manufacturing, pushing suppliers toward halogen-free polymer formulations. Stakeholders must monitor how emerging cybersecurity mandates for IoT consumer devices in multiple jurisdictions will alter firmware development budgets and aftermarket liability exposure.
Market Dynamics
Subscription-based hardware leasing is compressing upfront purchase barriers and tilting competitive advantage toward recurring-revenue infrastructure operators. PetSafe Brands leverages veterinary network control to sustain hardware attach rates, while Dogness International Corporation differentiates through IoT software connectivity rather than commodity enclosure construction.
Growth Catalysts
- Pet Humanization Trajectory:Urban households in the United States, Germany, and Japan treat companion animals as family members, creating sustained demand for welfare-monitoring enclosures with climate control and biometric sensors.
- REACH and RoHS Compliance Migration:European environmental directives on halogen-free polymers push enclosure manufacturers toward advanced material formulations that simultaneously reduce electromagnetic interference susceptibility.
- Cellular Module Reliability:Rural kennel operators and multi-site deployments favor sub-GHz and cellular gateways over Wi-Fi for off-grid operational continuity, expanding addressable market beyond residential settings.
Market Restraints
- FCC Part 15 Certification Burden:United States electromagnetic compatibility testing for 2.4 GHz radio-enabled devices extends product launch timelines and concentrates development resources among well-capitalized players.
- Polymer Input Volatility:Specialized halogen-free thermoplastics required for CE marking face supply concentration among European compounders, creating margin pressure during petrochemical price cycles.
- Legacy Kennel Substitution:Conventional metal and polymer enclosures without connectivity modules retain cost advantage in price-sensitive segments, limiting premium smart unit penetration.
Strategic Opportunities
- AI-Enabled Anomaly Detection:Machine learning algorithms processing behavioral pattern data from camera and motion sensors create software differentiation beyond hardware commoditization.
- Veterinary Channel Integration:Clinical endorsement networks provide trusted distribution pathways for biometric monitoring units targeting post-surgical and chronic condition management applications.
- Cybersecurity Mandate Preparation:Emerging IoT device security regulations across multiple jurisdictions reward early firmware investment with reduced aftermarket liability exposure.
Industry Challenges
- RF Engineering Talent Scarcity:Sub-GHz and cellular gateway optimization for pet enclosure form factors requires specialized electromagnetic design expertise concentrated among consumer electronics hubs.
- Multi-Standard Certification Parallelism:Simultaneous FCC, CE marking, and emerging cybersecurity compliance demands fragment quality assurance resources and compress development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pet Kennel Market |
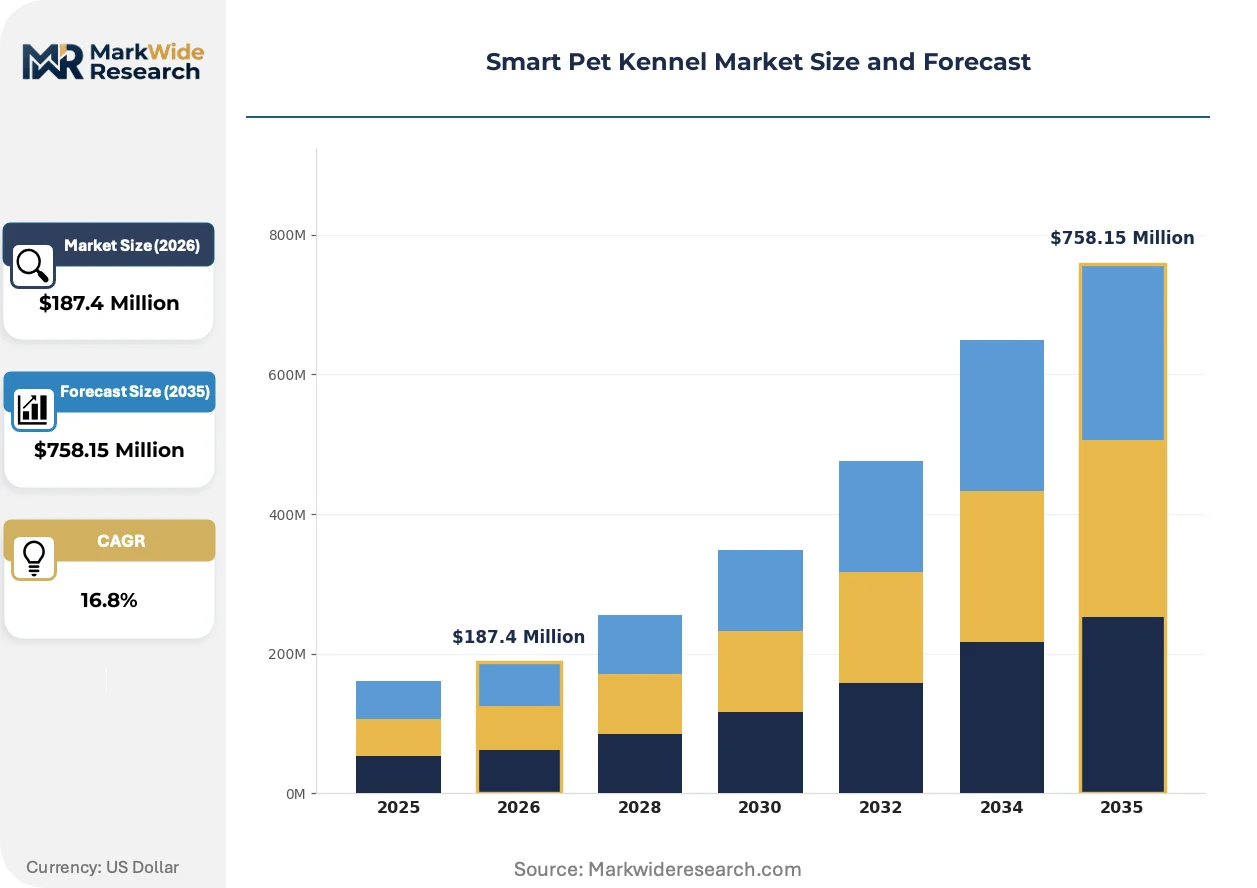
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Feeders, Smart Cameras, Temperature Control, GPS Trackers Connectivity: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Pet Owners, Kennel Operators, Veterinarians, Pet Care Services Technology: IoT Solutions, Mobile Applications, AI Features, Smart Sensors |
| Companies Covered | Petmate, MidWest Homes for Pets, Ferplast S.p.A., PetSafe Brands, Sure Petcare, Wagz, Inc., Dogness International Corporation, PetPace LLC, Tractive GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pet Kennel Market Trends and Innovations
Machine learning inference at the edge is transforming how welfare data gets processed, reducing cloud dependency while enabling real-time behavioral alerts. This shift compresses latency for anomaly detection and creates new firmware architecture requirements.
Embedded vision systems with on-device inference is digitizing how pet owners verify companion welfare during absences. Premium urban households deploy camera-integrated kennels for visible reassurance, while the technology compresses demand for separate monitoring hardware purchases. Edge processing reduces bandwidth costs and enables subscription tier differentiation based on AI feature depth.
FCC Part 15 rule evolution in the United States tightens electromagnetic compatibility thresholds for 2.4 GHz consumer devices. This regulatory pressure extends pre-market testing timelines and concentrates certification investment among established radio hardware suppliers. Residential Wi-Fi-dependent kennel manufacturers face particular compliance cost pressure as threshold stringency increases.
Leasing models displace outright purchase for urban apartment dwellers seeking flexibility without capital commitment. Veterinary and retail channels accommodate this shift through hardware-as-a-service arrangements that bundle maintenance and upgrade rights. Germany and Japan exhibit strongest leasing penetration where pet humanization rates intersect with space-constrained living patterns.
Smart Pet Kennel Market Segmentation
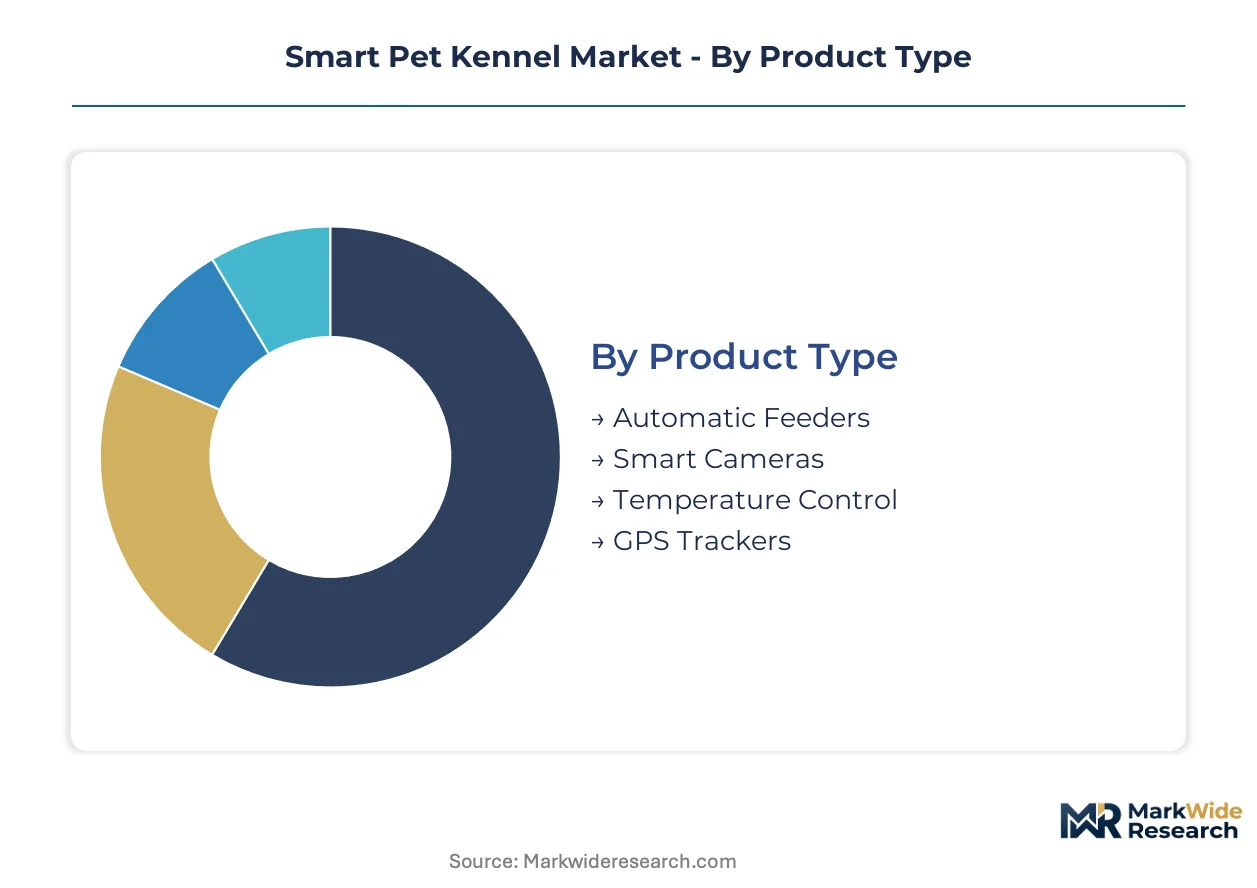
Smart pet kennel segmentation reveals how hardware specifications, network architectures, and user workflows create distinct purchasing logics across residential and commercial deployments. Understanding these divides clarifies where subscription models displace outright purchase and where certification burdens concentrate development investment.
Product Type:
Product variation tracks the use-case spectrum from dietary automation to environmental assurance and location security.
- Automatic Feeders:Precision portioning mechanisms with programmable scheduling dominate residential demand among working professionals. United States urban households prioritize these units for dietary consistency during extended absences, with FCC Part 15 certification requirements extending launch timelines for radio-enabled models.
- Smart Cameras:Embedded vision systems with edge inference enable real-time behavioral monitoring without cloud dependency. Germany and Japan exhibit strongest penetration where pet humanization rates intersect with subscription leasing preferences for visible reassurance.
- Temperature Control:Climate modules integrate thermostatic regulation with humidity sensing for breed-specific welfare requirements.
- GPS Trackers:Location hardware targets outdoor and multi-site kennel operations requiring asset visibility beyond enclosure boundaries.
Established volume favors automatic feeders; emerging adoption favors smart cameras.
Connectivity:
Network architecture selection hinges on deployment environment reliability requirements and electromagnetic compliance cost tolerance.
- Wi-Fi:2.4 GHz modules dominate residential installations where broadband infrastructure is assumed. REACH and RoHS constraints in Europe push enclosure manufacturers toward halogen-free polymers that simultaneously reduce electromagnetic interference susceptibility.
- Cellular:Sub-GHz and cellular gateways capture rural kennel operators and multi-site deployments requiring off-grid operational continuity. FCC Part 15 threshold tightening in the United States concentrates certification investment among established radio hardware suppliers.
- Bluetooth:Short-range protocols serve proximity-based pairing for initial device configuration and localized data sync.
- Zigbee:Mesh networking enables whole-home integration with existing smart home ecosystems for climate and security coordination.
Residential density favors Wi-Fi; operational continuity demands favor cellular.
End User:
Customer type segmentation exposes divergent procurement patterns between asset-light consumers and compliance-bound institutions.
- Pet Owners:Individual consumers drive unit economics through subscription leasing models that compress upfront capital barriers. Urban households in space-constrained environments prioritize flexible hardware-as-a-service arrangements.
- Kennel Operators:Commercial multi-site deployments require cellular-enabled units with centralized fleet management and maintenance bundling.
- Veterinarians:Clinical endorsement networks provide trusted distribution pathways for biometric monitoring units targeting post-surgical recovery applications.
- Pet Care Services:Daycare and boarding facilities demand ruggedized enclosures with integrated feeding and climate systems for high-turnover animal populations.
Subscription infrastructure favors pet owners; integrated service contracts favor kennel operators.
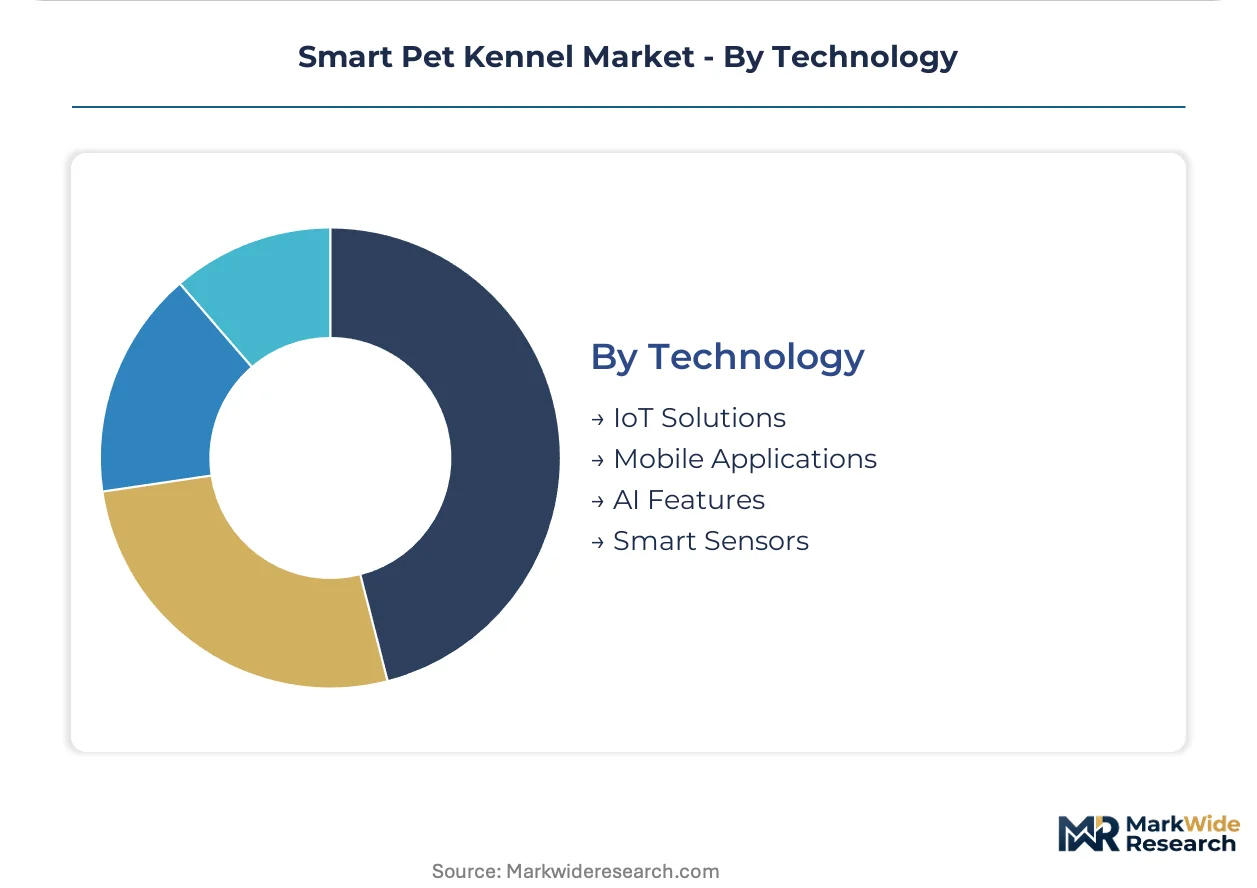
Technology:
Technology stack differentiation determines firmware development budgets and aftermarket liability exposure under emerging cybersecurity mandates.
- IoT Solutions:Sensor-to-cloud architectures enable remote monitoring and automated welfare alerts through gateway connectivity. Multi-standard certification parallelism across FCC, CE marking, and cybersecurity compliance fragments quality assurance resources.
- AI Features:Machine learning algorithms processing behavioral pattern data create software differentiation beyond hardware commoditization. Edge inference reduces bandwidth costs and enables subscription tier differentiation based on feature depth.
- Mobile Applications:Companion software interfaces consolidate control across feeding schedules, camera feeds, and environmental alerts.
- Smart Sensors:Biometric and environmental probes provide raw data streams for anomaly detection and welfare verification.
Deployment scale favors IoT solutions; margin expansion favors AI features.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 rule evolution in the United States is tightening electromagnetic compatibility thresholds for radio-enabled pet devices. CE marking under the EU Radio Equipment Directive and emerging cybersecurity mandates across multiple jurisdictions are reshaping where manufacturers prioritize certification investment and channel partnerships.
United States
Urban households in New York, Los Angeles, and Chicago treat companion animals as family members, creating sustained demand for welfare-monitoring enclosures with climate control and biometric sensors. FCC Part 15 certification requirements for 2.4 GHz radio-enabled devices extend product launch timelines and concentrate development resources among well-capitalized players. The Dallas-Fort Worth metroplex anchors manufacturing and distribution infrastructure for polymer enclosure production serving domestic and export markets.
Germany
REACH and RoHS constraints push enclosure manufacturers toward halogen-free polymer formulations that simultaneously reduce electromagnetic interference susceptibility. The EU Radio Equipment Directive shapes electromagnetic compliance costs and certification timelines for connected kennel hardware entering European markets. Bavaria's industrial corridor around Munich hosts precision engineering clusters specializing in IoT-integrated feeding and monitoring systems.
Japan
Space-constrained living patterns in Tokyo, Osaka, and Yokohama intersect with high pet humanization rates to drive subscription leasing penetration for flexible hardware-as-a-service arrangements. METI oversight of radio equipment standards ensures rigorous electromagnetic compatibility testing for devices operating on 2.4 GHz and sub-GHz bands. The Kanto region's electronics manufacturing ecosystem supplies sensor modules and wireless communication hardware to domestic smart pet device assemblers.
United Kingdom
Veterinary channel integration provides trusted distribution pathways for biometric monitoring units targeting post-surgical recovery applications in London, Manchester, and Birmingham. The UK Product Security and Telecommunications Infrastructure Act imposes emerging cybersecurity mandates for IoT consumer devices that alter firmware development budgets and aftermarket liability exposure. Scotland's emerging tech corridor around Edinburgh hosts software development operations for machine learning-enabled behavioral pattern detection.
China
MIIT radio transmission equipment certification requirements govern sub-GHz and cellular gateway modules produced in Shenzhen and Dongguan for export markets. GB standards for electromagnetic compatibility create parallel compliance pathways for domestic sales versus international certification. The Yangtze River Delta manufacturing belt around Shanghai supplies precision metal and polymer enclosure components to global smart pet kennel assemblers.
Smart Pet Kennel Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that rewards recurring-revenue infrastructure over hardware margins alone. The vendor base spans veterinary network operators, manufacturing-scale enclosure producers, and IoT software connectivity specialists. Three archetypes dominate: network-leveraged incumbents with distribution depth, scale-driven fabricators with captive polymer and metal supply, and software-differentiated challengers with machine learning capabilities. Competitive moves concentrate on veterinary channel partnerships and edge-AI firmware development.
Among network-leveraged incumbents, PetSafe Brands exemplifies channel control across veterinary and retail networks. MidWest Homes for Pets occupies a position as a scale-driven fabricator with manufacturing concentration in metal and polymer enclosure production. Dogness International Corporation represents the software-differentiated archetype, specializing in IoT-integrated systems that compete on connectivity rather than commodity cage construction.
| Leading Market Players |
|---|
| Petmate |
| MidWest Homes for Pets |
| Ferplast S.p.A. |
| PetSafe Brands |
| Sure Petcare |
| Wagz, Inc. |
| Dogness International Corporation |
| PetPace LLC |
| Tractive GmbH |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's electronics manufacturing corridor dictates component availability timelines for radio-enabled pet enclosures, translating upstream semiconductor allocation into downstream subscription pricing power for integrated hardware-software bundles. FCC Part 15 certification bottlenecks in the United States amplify this dynamic by concentrating qualified supplier relationships among capitalized players capable of absorbing extended pre-market testing cycles.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FCC Part 15 and CE marking compliance under the EU Radio Equipment Directive commanding material premiums over uncertified alternatives. Subscription-based hardware leasing dominates the pricing model, compressing upfront capital barriers while embedding maintenance and upgrade rights into recurring fees. Price differentiation rests on electromagnetic compliance grade and after-sales service bundling, with veterinary channel endorsements supporting least price-sensitive positioning. Cost compression in standard Wi-Fi-dependent units is intensifying as threshold stringency rises, while rural kennel operators show greatest price sensitivity due to cellular module premiums.
Supply Chain Analysis
Extended payment terms from Shenzhen and Dongguan assemblers to European compounders of halogen-free polymers lubricate working capital through the certification-intensive production cycle. Geographic supply concentration centers on China for sensor modules and wireless gateways, Germany for precision engineering clusters, and Japan for electronics manufacturing ecosystems. Raw material dependencies draw from specialized thermoplastics, sub-GHz radio chipsets, and edge-AI processors. Single-source vulnerability runs through European halogen-free polymer compounders subject to petrochemical price cycles. Distribution runs through veterinary networks and retail channels accommodating hardware-as-a-service arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart pet kennel economics increasingly hinge on recurring-revenue infrastructure, with AI-enabled behavioral monitoring subscriptions expanding faster than commodity enclosure sales as urban households prioritize visible reassurance over capital ownership.
For Market Incumbents: Pre-empt software-differentiated challengers by embedding machine learning inference at the edge before hardware commoditization accelerates. Deepen veterinary channel control through clinical endorsement networks targeting post-surgical recovery applications. Fortify certification investment against FCC Part 15 threshold tightening to maintain launch timeline advantages over undercapitalized entrants. For New Entrants and Emerging Players: Rural kennel operators in cellular-dependent deployments represent the most penetrable white-space target, with off-grid operational continuity requirements underserved by Wi-Fi-centric incumbents. Veterinary channel bypass through direct-to-operator fleet management contracts offers lower friction entry than retail network buildout. White-label edge-AI firmware licensing to established enclosure manufacturers reduces capital requirements versus integrated hardware development. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-differentiated challengers with machine learning capabilities over scale-driven fabricators facing polymer input volatility. Long-term viability across the projection horizon rests on recurring-revenue infrastructure ownership rather than transactional hardware margins. The signal to monitor is cybersecurity mandate implementation timelines across multiple jurisdictions, which would accelerate firmware development budget requirements and consolidate competitive positions among early compliance investors.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Clinical endorsement networks provide trusted distribution pathways for biometric monitoring units targeting post-surgical applications. |
| Edge-AI Firmware Development | On-device inference reduces cloud dependency while enabling subscription tier differentiation based on behavioral anomaly detection depth. |
| Cellular Module Integration | Sub-GHz and cellular gateways capture rural kennel operators requiring off-grid operational continuity beyond residential Wi-Fi coverage. |
| Halogen-Free Polymer Sourcing | REACH and RoHS compliance migration pushes enclosure manufacturing toward advanced formulations reducing electromagnetic interference susceptibility. |
| Cybersecurity Mandate Preparation | Early firmware investment in emerging IoT device security regulations reduces aftermarket liability exposure across multiple jurisdictions. |
Research Methodology
A standing panel of veterinary practice managers, smart home integration specialists, polymer procurement leads at enclosure manufacturers, and FCC certification consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC equipment authorization databases, EU Radio Equipment Directive notified body filings, pet industry trade association shipment reports, and smart home ecosystem partnership announcements. Bottom-up unit economics from subscription leasing providers triangulated against top-down market sizing from connected device penetration models.
Scenario-bracketing framed demand trajectories across pet humanization intensity variations and regulatory compliance cost escalations throughout the projection horizon. Segmentation dimensions modeled included connectivity architecture, end-user procurement pattern, and technology stack differentiation. CAGRs derived from installed base growth rates and replacement cycle compression across the analysis window. Forecast inputs incorporated electromagnetic certification timeline elasticity and AI feature adoption curves specific to companion animal monitoring applications.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by radio hardware suppliers or cybersecurity mandate acceleration by regulators would shift outcomes. Macroeconomic deviation in pet discretionary spending, regulatory fragmentation in IoT security standards, or breakthrough battery technology enabling untethered deployment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Electric Pet Clippers Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Pet Fitness Care Market
Pet Care Products
Vegan Pet Food Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
Dog Treats Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Dog Float Market
Pet Care Products
Dog Raincoats Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Aquarium Market
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Dry Pet Food Market