
 North America Pet Treats Market | 2026-2036
North America Pet Treats Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pet Treats Market Insights
Veterinary nutritionist talent is bifurcating the competitive landscape, with premium brands racing to secure formulation expertise while mass-market players automate standard recipes. Mars, Incorporated leverages captive veterinary research networks to sustain new product pipelines. Nestle Purina Petcare anchors its position through scale manufacturing in Midwest production hubs. Wellness Pet Company differentiates via limited-ingredient formulations that command shelf space in specialty retail.
North America pet treats comprise formulated edible products designed for intermittent feeding, typically containing protein meals, starches, and functional additives processed through extrusion, baking, or dehydration to achieve specific texture, digestibility, and shelf stability parameters. The dog treat category dominates volume, with dental chews capturing disproportionate margin pools due to veterinary endorsement and repeat purchase rates. Grain-free ingredient positioning competes for premium shelf space, though organic certification trails in penetration against meat-based formulations that dominate mass-market velocity.
The FDA Center for Veterinary Medicine enforces ingredient safety and labeling standards, while the Association of American Feed Control Officials coordinates state-level feed control programs that shape interstate commerce requirements. USDA oversight of rendered protein sources and state agriculture department inspections constrain raw material sourcing flexibility for smaller manufacturers. Stakeholders must monitor evolving clean-label enforcement patterns and veterinary channel certification requirements as determinants of brand access and pricing power.
Market Dynamics
Millennial pet owner premiumization is fragmenting demand into veterinary-endorsed functional segments versus mass-market commodity tiers, forcing manufacturers to dual-track formulation capabilities and channel strategies simultaneously.
Growth Catalysts
- Veterinary Channel Certification:FDA Center for Veterinary Medicine guidelines on dental health claims are legitimizing functional treat categories. Pet specialty retailers now require veterinary nutritionist sign-off for premium shelf placement.
- Rendered Protein Traceability:USDA oversight of rendering facilities is improving raw material quality consistency. Midwest production hubs benefit from proximity to integrated protein supply chains.
- California Clean-Label Mandates:State agriculture department enforcement of ingredient disclosure is accelerating limited-ingredient formulation adoption. Coastal corridor consumers reward transparent sourcing with repeat purchase loyalty.
Market Restraints
- Input Cost Volatility:Drought cycles in US Great Plains regions destabilize grain and legume pricing. Smaller manufacturers lack forward-contracting scale to buffer commodity swings.
- Supply Concentration Risk:Three Midwest rendering cooperatives control majority domestic animal protein meal output. Disruption at any single facility cascades through multiple brand supply chains.
- Regulatory Friction:Interstate feed control program inconsistencies between state agriculture departments create labeling compliance burdens. Reformulation costs multiply for brands selling across multiple jurisdictions.
Strategic Opportunities
- Underpenetrated Canadian Veterinary Channel:Health Canada veterinary health product regulations are formalizing functional treat classification. Early movers can establish clinic-exclusive distribution before market saturation.
- Subscription Direct-to-Consumer Models:Chewy and Amazon Pet are reconfiguring replenishment economics. Brands capturing auto-ship data gain predictive demand visibility for production planning.
- Human-Grade Ingredient Positioning:USDA inspected-and-passed facility certification is creating price-realization separation. Premium positioning justifies 40-60 point gross margin expansion over conventional tiers.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Board-certified veterinary nutritionists command compensation premiums exceeding mid-market manufacturer R&D budgets. Formulation quality gaps emerge between well-capitalized and resource-constrained players.
- Extrusion Equipment Capex Intensity:Continuous processing lines for dental chew texturization require eight-figure capital deployment. Financing constraints limit production capacity expansion for emerging brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pet Treats Market |
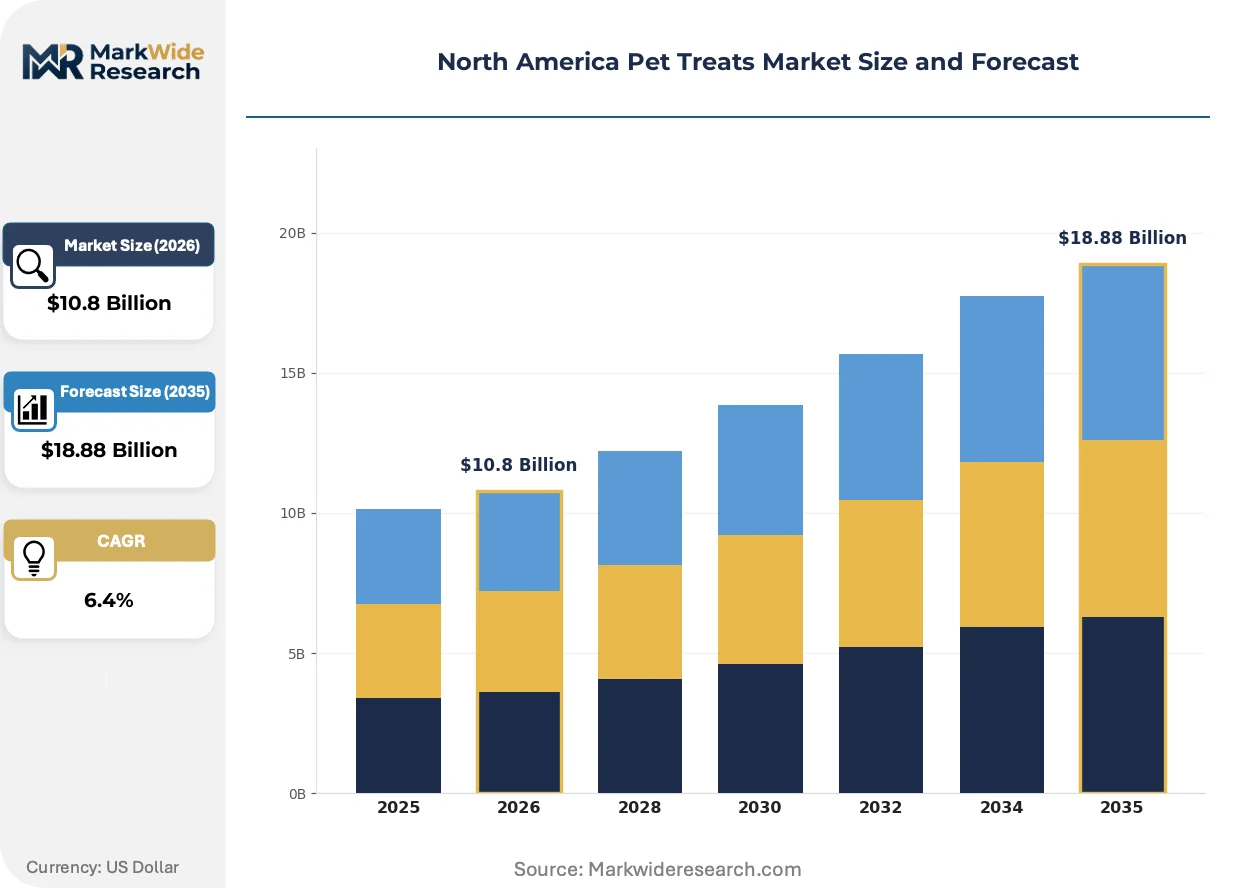
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chews, Biscuits, Jerky, Dental Treats Ingredient Type: Meat-Based, Grain-Free, Organic, Vegan Target Animal: Dogs, Cats, Birds, Small Mammals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Veterinarians |
| Companies Covered | Mars, Incorporated, General Mills Inc., Nestle Purina Petcare, The J.M. Smucker Company, Hill's Pet Nutrition, Inc., Spectrum Brands Holdings Inc., Wellness Pet Company, Colgate-Palmolive Company, SCHELL & KAMPETER, INC., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pet Treats Market Trends and Innovations
Cold-pressed manufacturing technology is compressing thermal degradation in functional ingredient retention. Regulatory scrutiny of grain-free cardiac safety claims is reshaping formulation roadmaps. Channel consolidation among pet specialty retailers is compressing brand negotiation leverage.
High-pressure processing (HPP) is displacing traditional heat-pasteurization in raw and minimally-processed treat segments. Premium brands including Stella & Chewy's and Primal Pet Foods have scaled HPP infrastructure to preserve enzyme activity and probiotic viability. This technology is displacing conventional extrusion for shelf-stable raw positioning, compressing the addressable market for legacy baking and dehydration equipment suppliers.
FDA Center for Veterinary Medicine investigation into canine dilated cardiomyopathy (DCM) associations with grain-free diets is forcing formulation transparency. The agency's 2019-2023 data call compelled brands to submit legume and pulse inclusion rates. Grain-inclusive and ancient-grain positioning is regaining shelf space in mass-market channels previously dominated by grain-free SKUs.
Pet humanization is rotating procurement authority from household primary shoppers to specialized pet parents. Millennial and Gen Z cohorts research ingredient sourcing via QR-coded packaging before purchase. This behavior is most visible in California and Northeast corridor urban markets, where independent pet specialty stores outpace mass-market velocity for premium-tier products.
North America Pet Treats Market Segmentation
Channel fragmentation in North America pet treats is forcing manufacturers to calibrate formulation, packaging, and pricing simultaneously across veterinary, specialty retail, and mass-market outlets. Each segment commands distinct margin profiles and repeat-purchase economics that reshape portfolio allocation decisions.
Product Type:
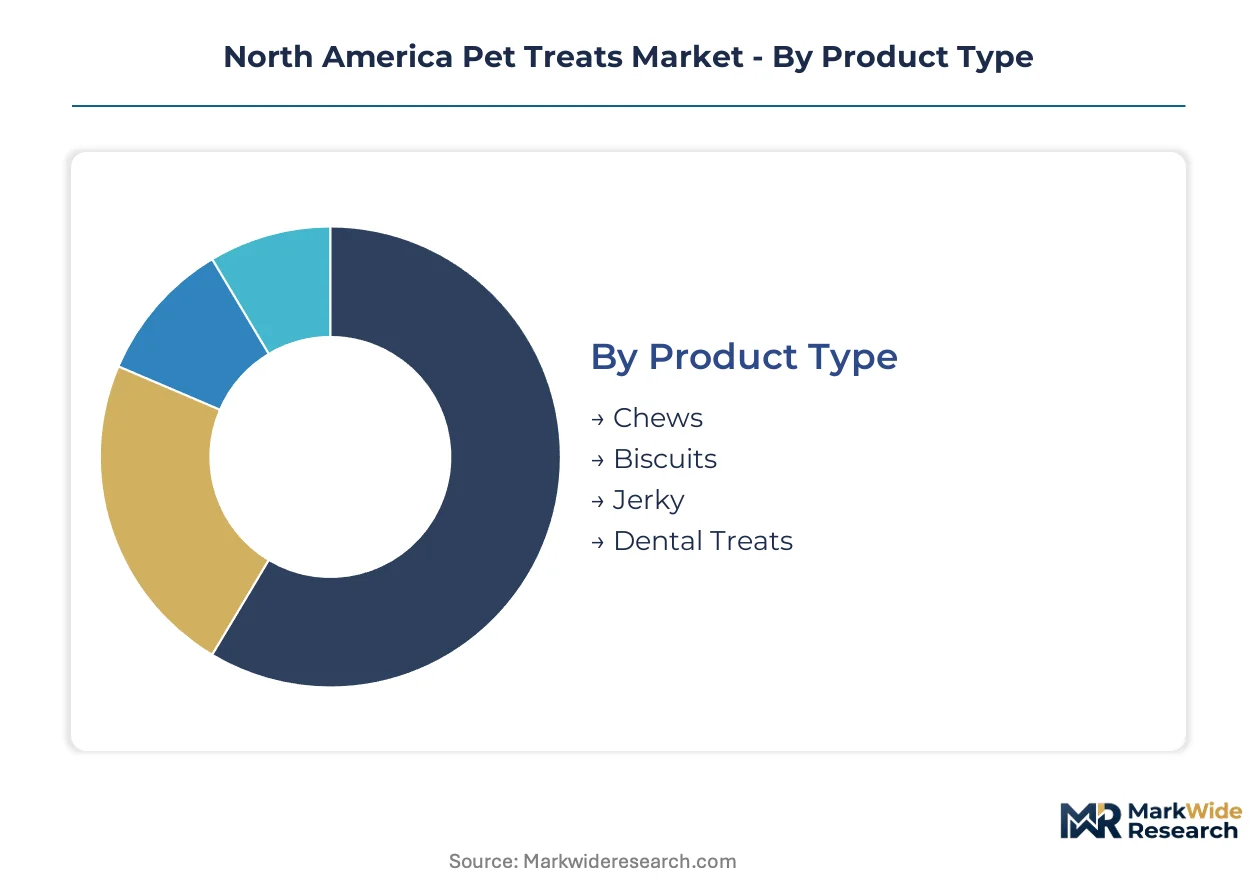
Channel-mix dynamics concentrate dental and functional chews through veterinary and specialty retail, while biscuits and jerky flow predominantly through mass-market and e-commerce replenishment channels.
- Chews:Extruded or molded protein matrices designed for extended consumption duration and mechanical dental cleaning action. Demand clusters in the US Northeast corridor where urban pet owners prioritize apartment-friendly quiet consumption. Veterinary endorsement drives premium placement and subscription retention.
- Dental Treats:VOHC-accepted formulations bearing specific tartar-control claims per FDA Center for Veterinary Medicine guidelines. California and Pacific Northwest consumers demonstrate highest per-capita expenditure on veterinary-certified SKUs, with clinic-exclusive distribution commanding 40-point gross margin premiums over retail-equivalent products.
- Biscuits:Baked starch-protein composites targeting training reinforcement and portion-controlled feeding occasions. Midwest manufacturing hubs exploit grain supply proximity for cost-competitive mass-market velocity.
- Jerky:Dehydrated whole-muscle strips preserving intact protein structure and palatability intensity. Human-grade USDA facility certification enables premium positioning in specialty retail and direct-to-consumer channels.
Chews dominate installed base. Dental treats are where expansion concentrates.
Ingredient Type:
Cost-tier stratification separates commodity protein meals from certified organic and human-grade positioning, with grain-free formulations occupying a contested middle ground following FDA DCM investigations.
- Meat-Based:Rendered protein meals and fresh muscle tissue formulations supplying complete amino acid profiles for carnivore-optimized nutrition. Midwest rendering cooperative supply chains anchor mass-market cost structures.
- Grain-Free:Legume, pulse, and tuber starch substitutions eliminating gluten-containing grains. FDA Center for Veterinary Medicine DCM data calls have compressed veterinary channel placement, though consumer loyalty persists in California specialty retail.
- Organic:USDA Organic certified ingredients with prohibited substance restrictions and traceability documentation. Premium pricing justifies limited distribution through independent pet specialty and natural grocery channels in Northeast urban markets.
- Vegan:Plant-protein concentrates and synthetic amino acid fortification eliminating animal-derived inputs. Niche positioning attracts sustainability-motivated millennial cohorts in Pacific Coast metropolitan areas.
Meat-based formulations command volume leadership. Organic certification is climbing the fastest as specialty retail buyers consolidate shelf space around transparent sourcing credentials.
Target Animal:
Application-specific formulation requirements separate canine dental chews from feline palatability engineering and small-mammal digestive sensitivity protocols.
- Dogs:Dominant species segment with established veterinary dental protocols and training-treat consumption occasions. Size-stratified SKUs address breed-specific caloric and mechanical requirements across mass-market and premium channels.
- Cats:Obligate carnivore formulations emphasizing high protein density and texture variety for finicky consumption patterns. Veterinary channel concentrates in feline obesity and urinary health functional positioning.
- Birds:Seed and pellet-compatible treat formats with beak-wear and foraging enrichment functionality. Avian veterinary specialists in Florida and California corridor drive prescription-grade distribution.
- Small Mammals:Fiber-optimized formulations for rodent and lagomorph digestive physiology. Limited ingredient transparency appeals to hyper-informed Gen Z owners in urban specialty retail.
Dogs retain installed base dominance. Cats represent the steepest expansion trajectory as feline veterinary wellness protocols formalize treat-based medication delivery.
Distribution Channel:
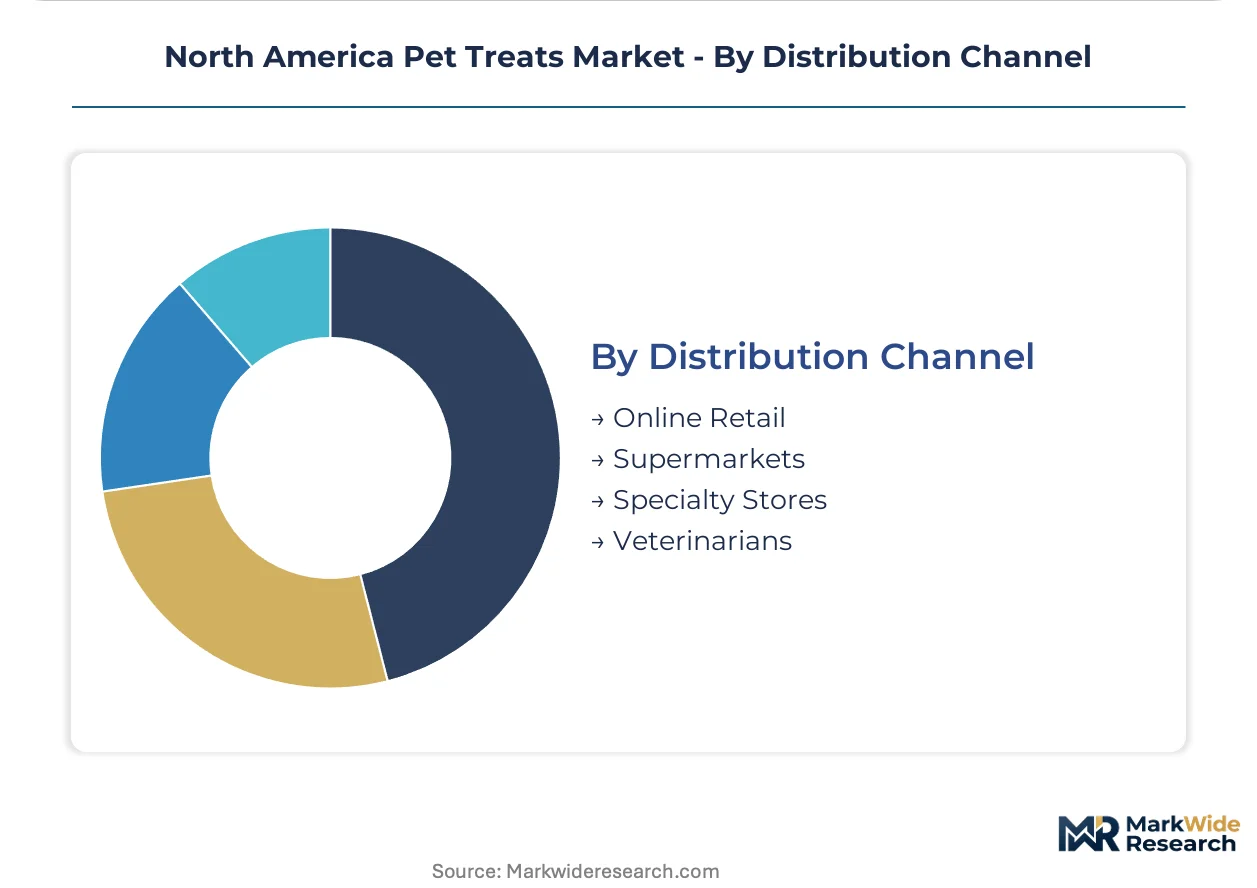
Customer-type stratification concentrates subscription-native millennials through online retail, while veterinary channel access requires nutritionist credentialing and clinic-exclusive SKU development.
- Online Retail:Chewy and Amazon Pet auto-ship infrastructure capturing replenishment economics with predictive demand algorithms. Data capture enables personalized formulation recommendations and lifetime value optimization.
- Specialty Stores:Independent pet retail in California and Northeast corridors demanding limited-ingredient transparency and local sourcing narratives. Shelf-space negotiation hinges on veterinary nutritionist sign-off and QR-coded traceability.
- Supermarkets:Mass-market velocity driving biscuit and mainstream jerky placement with price-promotion dependency and private-label encroachment.
- Veterinarians:Clinic-exclusive distribution for dental and therapeutic treats with prescription-style endorsement. FDA Center for Veterinary Medicine health claim compliance mandatory for category access.
Supermarkets dominate transaction volume. Online retail is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine guidelines and USDA rendering oversight anchor the United States as the dominant regulatory geography, while Health Canada and Mexico's SENASICA shape complementary demand corridors across the continent.
United States
Millennial pet owner premiumization in California and the Northeast corridor drives veterinary-endorsed functional treat demand. FDA Center for Veterinary Medicine dental health claim guidelines legitimize VOHC-accepted formulations for clinic distribution. Midwest production hubs exploit proximity to integrated protein rendering cooperatives for cost-competitive mass-market supply.
Canada
Health Canada veterinary health product regulations are formalizing functional treat classification ahead of market saturation. Provincial feed control programs under the Canadian Food Inspection Agency enforce ingredient traceability standards. Ontario and Quebec veterinary channels concentrate early-mover distribution for dental and therapeutic SKUs.
Mexico
Rising middle-class pet ownership in Mexico City and Guadalajara metro areas expands addressable base for imported premium brands. SENASICA oversight of rendered protein imports constrains raw material sourcing flexibility for local manufacturers. Northern border states leverage maquiladora infrastructure for cost-optimized export production to US markets.
Pacific Northwest
Human-grade ingredient positioning attracts sustainability-motivated millennial cohorts in Seattle and Portland urban markets. State agriculture department clean-label enforcement accelerates limited-ingredient formulation adoption. Regional specialty retail chains consolidate shelf space around QR-coded traceability and local sourcing narratives.
Southeast United States
Avian veterinary specialists in Florida drive prescription-grade treat distribution for companion bird segments. State feed control programs under the Association of American Feed Control Officials framework create labeling compliance burdens for interstate brands. Atlanta and Miami logistics hubs facilitate e-commerce replenishment infrastructure for direct-to-consumer subscription models.
North America Pet Treats Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Mars, Incorporated and Nestle Purina Petcare anchoring the consolidated upper layer through captive veterinary research networks and Midwest scale manufacturing. Mid-market manufacturers automate standard recipes while premium challengers race to secure board-certified veterinary nutritionist talent. Two dominant competitive moves define current positioning: dual-track formulation capabilities serving veterinary and mass-market channels simultaneously, and backward integration into USDA-inspected rendering supply chains.
Within the integrated multinational tier, Mars, Incorporated and Nestle Purina Petcare exemplify scale-driven archetypes leveraging captive R&D infrastructure. Wellness Pet Company occupies a position within the premium specialist tier, differentiating through limited-ingredient formulations that command specialty retail shelf space. These three entities represent the structural bifurcation between mass-market velocity players and veterinary-credentialed premium challengers.
| Leading Market Players |
|---|
| Mars, Incorporated |
| General Mills Inc. |
| Nestle Purina Petcare |
| The J.M. Smucker Company |
| Hill's Pet Nutrition, Inc. |
| Spectrum Brands Holdings Inc. |
| Wellness Pet Company |
| Colgate-Palmolive Company |
| SCHELL & KAMPETER, INC. |
| Others |
Pricing and Supply Chain Analysis
USDA inspected-and-passed facility certification gates both raw material qualification and price differentiation simultaneously, separating human-grade positioning from conventional tiers while constraining supplier eligibility to a narrow pool of compliant renderers.
Pricing Analysis
Long-term offtake contracts with Midwest rendering cooperatives anchor cost structures for mass-market tiers, while spot-market protein meal purchases expose smaller manufacturers to commodity volatility. Price differentiation rests on veterinary nutritionist formulation credentials and VOHC acceptance status. Pricing pressure stems from drought-driven grain and legume cost compression in the US Great Plains. Mass-market supermarket buyers exhibit highest price sensitivity; veterinary channel purchasers show lowest elasticity due to clinic-exclusive endorsement value.
Supply Chain Analysis
The United States dominates rendered protein meal production through integrated Midwest cooperatives, with Canada and Mexico serving secondary sourcing roles for specialty ingredients. Supply chains draw from domestic animal protein rendering, imported novel proteins, and regional grain processing. Single-source vulnerability concentrates in three Midwest rendering cooperatives controlling majority domestic output. Distribution runs through veterinary clinics, pet specialty retailers, and e-commerce auto-ship platforms in descending margin order.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from fresh-food and refrigerated pet nutrition formats that bypass conventional treat shelf positioning entirely.
For Market Incumbents: Consolidate backward integration into USDA-inspected rendering supply chains to secure input cost stability. Acquire board-certified veterinary nutritionist talent before compensation premiums escalate further. Defend clinic-exclusive distribution relationships against fresh-food subscription entrants targeting veterinary endorsement channels. For New Entrants and Emerging Players: Differentiate on human-grade ingredient positioning with QR-coded traceability to capture Pacific Northwest and Northeast urban specialty retail. Target underpenetrated Canadian veterinary channels before Health Canada regulations formalize functional treat classification. Deploy direct-to-consumer auto-ship models to bypass shelf-space negotiation leverage of consolidated pet specialty retailers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dental chew extrusion equipment and HPP infrastructure. Prioritize acquisition targets with captive veterinary nutritionist teams and established clinic-exclusive SKU portfolios. Watch FDA Center for Veterinary Medicine enforcement patterns on grain-free cardiac safety claims as inflection indicator for formulation roadmap viability.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Nutritionist Acquisition | Board-certified talent scarcity commands premium compensation and gates premium shelf placement. |
| USDA Facility Certification Investment | Inspected-and-passed status enables 40-60 point gross margin expansion over conventional tiers. |
| Canadian Veterinary Channel Entry | Health Canada regulatory formalization creates first-mover clinic-exclusive distribution opportunity. |
| HPP Infrastructure Deployment | High-pressure processing preserves enzyme activity for raw and minimally-processed treat positioning. |
| Subscription Auto-Ship Integration | Chewy and Amazon Pet data capture enables predictive demand visibility for production planning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across veterinary clinics, pet specialty retail buyers, brand managers at treat manufacturers, and procurement leads at Midwest rendering cooperatives. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, USDA rendering facility inspection records, Association of American Feed Control Officials feed control program standards, and Nielsen retail audit data. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure estimates.
Across the projection horizon, the analytical framework modeled product type, ingredient certification tier, target animal species, and distribution channel segmentation dimensions. CAGRs were derived from regression analysis of historical velocity trends and elasticity-adjusted demand projections. Forecast inputs incorporated veterinary channel penetration rates and e-commerce auto-ship adoption curves specific to pet treat replenishment economics.
The analysis sits within stated boundaries; outcomes outside sustained millennial premiumization or stable FDA regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding protein meal cost trajectories and state-level feed control program harmonization. Recalibration cycles align with material shifts in FDA DCM investigation conclusions and Health Canada veterinary health product regulation finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Bowl Market
Pet Care Products
Poland Pet Food Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Dog Collars Market
Pet Care Products
US Dog Food Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Plant-Based Pet Food Market