
 Durable Juvenile Products Market | 2026-2036
Durable Juvenile Products Market Size, Share, and Industry Trends Forecast 2026-2036
Durable Juvenile Products Market Analysis
Vietnam is tilting toward durable juvenile product manufacturing as labor costs and tariff exposure redirect supply chains from traditional hubs. Goodbaby International Holdings leverages its China-based vertical manufacturing to sustain cost leadership across stroller and car seat lines. Dorel Juvenile anchors North American distribution through retail partnerships and in-house design centers. Artsana competes on European brand heritage and pediatric safety certification depth.
Durable juvenile products encompass strollers, car seats, high chairs, and playards engineered to ASTM F833 and EN 1888 structural load specifications with polymer-composite frames and five-point harness systems for child mobility and safety. Car seats command concentrated margin pools due to crash-test certification barriers and replacement-cycle regulations, while stroller demand fragments across premium urban compact designs and multi-child utility configurations. Fabric and plastic material segments dominate bill-of-materials composition, though metal frame subsets capture premium positioning through lightweight alloy innovation.
The US Consumer Product Safety Commission and the European Committee for Standardization enforce mandatory third-party testing and chemical-content thresholds that elevate compliance costs for market entry. China's GB standards and CCC certification create parallel technical requirements for domestic sales, fragmenting test-protocol harmonization. Stakeholders must monitor regulatory divergence between jurisdictions as a determinant of portfolio rationalization and regional factory qualification timelines.
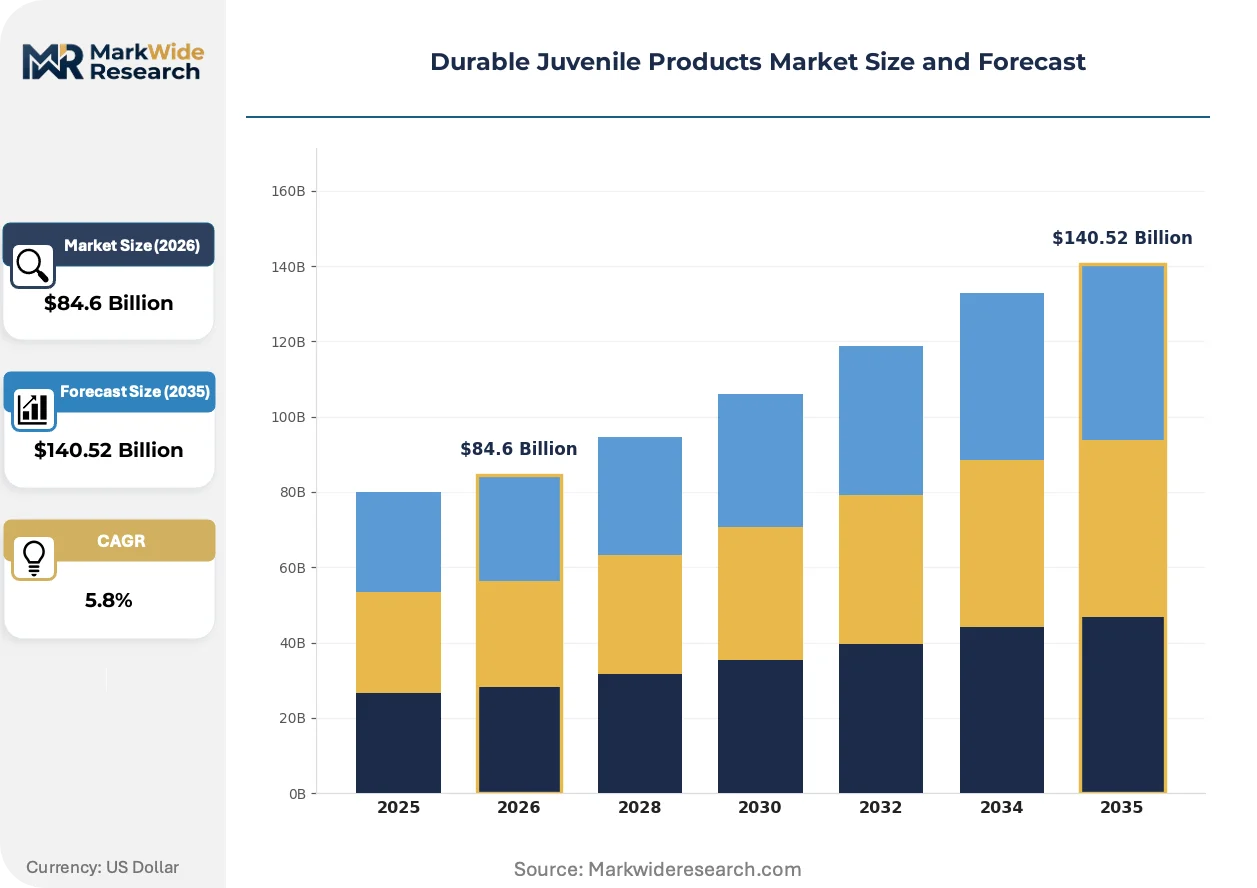
Market Dynamics
Supply chain reconfiguration toward Vietnam and domestic Chinese manufacturing is compressing lead times and reshaping competitive positioning among stroller and car seat producers. This geographic shift interacts with tightening chemical-content regulations across multiple jurisdictions to elevate compliance costs for new market entrants.
Growth Catalysts
- EU General Product Safety Regulation:Mandatory third-party testing requirements create certification barriers that favor established manufacturers with in-house testing laboratories over smaller competitors.
- Five-point harness polymer-composite engineering:Lightweight frame innovations reduce shipping costs and enable compact urban stroller configurations that align with apartment-dwelling parent preferences in dense metropolitan areas.
- Vietnam manufacturing expansion:Labor cost differentials and tariff mitigation strategies redirect stroller assembly capacity from traditional coastal China hubs toward Ho Chi Minh City industrial zones.
Market Restraints
- Polymer resin input volatility:Crude oil price fluctuations directly impact polymer-composite frame material costs, compressing margin pools for mid-tier stroller producers unable to pass through increases.
- China CCC certification fragmentation:Parallel GB standards testing requirements create duplicative compliance burdens for brands seeking domestic Chinese sales alongside export markets.
- Extended car seat replacement cycles:Durable engineering and multi-stage convertible designs reduce purchase frequency, capping volume growth in mature replacement markets.
Strategic Opportunities
- India urban middle-class expansion:Underpenetrated organized retail channels in Mumbai and Delhi present first-mover advantages for car seat brands establishing localized distribution partnerships.
- Subscription-based stroller access models:Urban parents in London and New York increasingly favor short-term leasing arrangements over ownership, creating recurring revenue streams for fleet operators.
- EU Green Deal chemical-content mandates:Phthalate-free polymer specifications accelerate demand for bio-based frame materials that command premium positioning in German and French retail channels.
Industry Challenges
- Crash-test engineer scarcity:Specialized certification expertise for EN 1888 and ASTM F833 structural validation concentrates among limited testing laboratory personnel, extending product development timelines.
- Multi-jurisdiction labeling complexity:Simultaneous compliance with US Consumer Product Safety Commission warning label requirements, EU multilingual packaging mandates, and China GB marking specifications fragments packaging standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durable Juvenile Products Market |
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $140.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strollers, Car Seats, High Chairs, Playards End User: Parents, Caregivers, Retailers, Distributors Material: Fabric, Plastic, Metal, Wood Age Group: Infants, Toddlers, Preschoolers, Children |
| Companies Covered | Dorel Juvenile, Goodbaby International Holdings, Artsana, Newell Brands, Britax, Graco, Chicco, Evenflo, Stokke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durable Juvenile Products Market Emerging Trajectories
Embedded sensor integration and connected safety systems are digitizing product functionality across the stroller and car seat categories. These hardware-software convergences reshape how parents interact with juvenile mobility products and how manufacturers capture post-purchase value.
Smart harness tension monitoring is digitizing real-time safety feedback for parents. Premium stroller lines in South Korea and Japan now incorporate load-cell sensors that transmit restraint status to smartphone applications. This connectivity layer enables subscription-based firmware updates and usage analytics that extend customer lifetime value beyond the initial hardware sale.
REACH chemical restriction expansions are forcing polymer reformulation across European supply chains. The European Chemicals Agency's updated phthalate and flame-retardant thresholds require frame manufacturers to qualify alternative plasticizers and intumescent coatings. German car seat producers are accelerating bio-polymer pilot programs to preempt regulatory compression on conventional petroleum-based materials.
Direct-to-parent digital channels are displacing traditional baby specialty retail in North American and Western European markets. Urban millennial buyers increasingly research crash-test ratings through independent safety advocacy platforms before purchasing through manufacturer-owned storefronts. This disintermediation concentrates margin capture with brand owners while reducing wholesale dependency on Toys R Us and Buy Buy Baby legacy footprints.
Durable Juvenile Products Market Segmentation
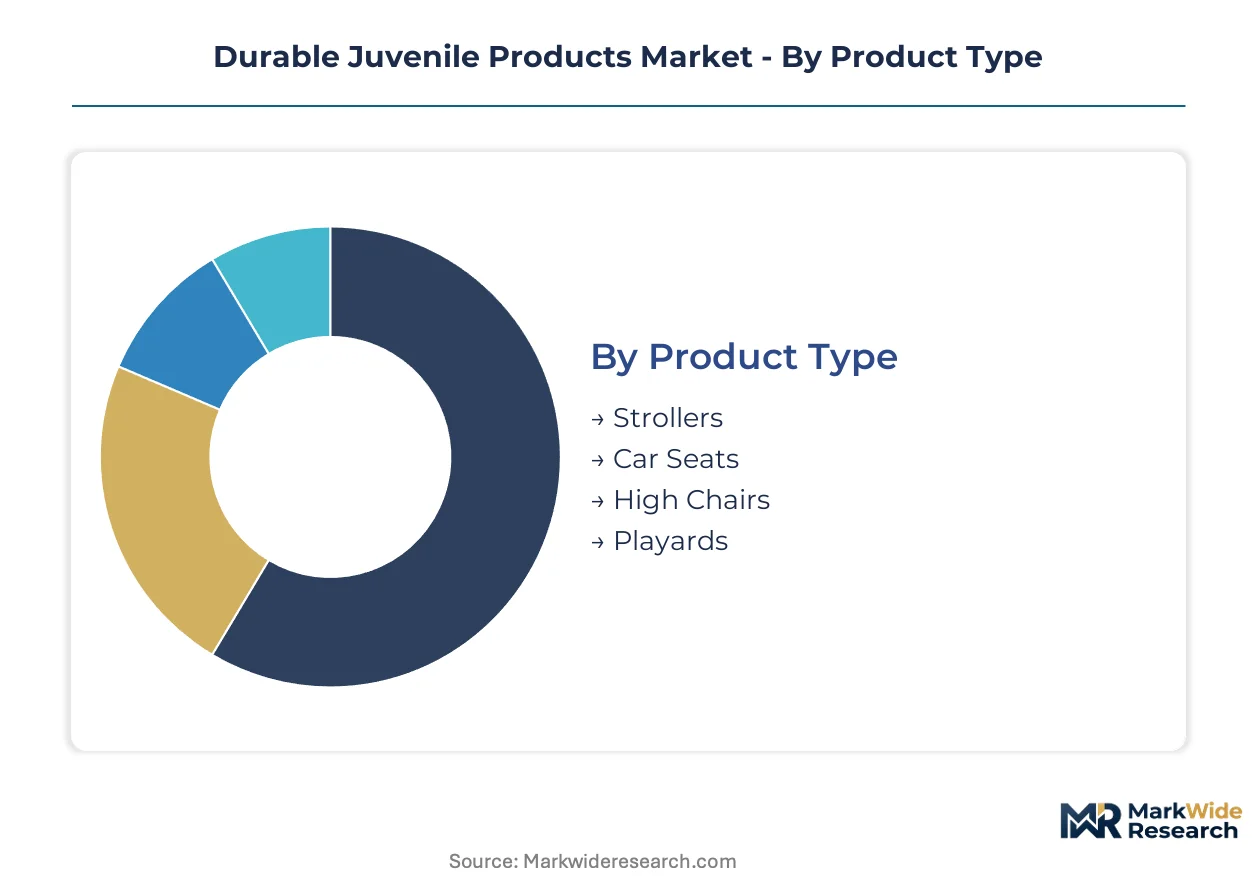
Segmentation in durable juvenile products reveals how safety engineering, material science, and channel economics fragment demand across distinct buyer workflows. Manufacturers must align certification depth and margin structure to the specific constraints of each product-material-end user intersection.
Product Type:
Use cases span from daily mobility solutions to stationary feeding and sleeping environments, each carrying distinct crash-test or structural load certification requirements.
- Strollers:Polymer-composite frames meeting ASTM F833 and EN 1888 specifications enable weight reduction below 7kg for urban compact configurations. Demand concentrates in Chinese metropolitan clusters where apartment-dwelling parents prioritize foldable footprints and subway-compatible dimensions.
- Car Seats:Five-point harness systems with load-cell sensor integration command concentrated margin pools due to FMVSS 213 and ECE R44/04 crash-test certification barriers. Replacement-cycle regulations in California and Bavaria sustain recurring purchase mandates despite extended product lifecycles.
- High Chairs:ASTM F404-compliant restraint systems with dishwasher-safe tray surfaces serve mealtime containment needs across home and commercial childcare settings.
- Playards:Mesh-sided collapsible enclosures meeting ASTM F406 structural stability tests address portable sleep and containment requirements for travel and secondary caregiver environments.
The dominant share belongs to Car Seats, while Strollers is closing the gap fastest.
End User:
Channel economics diverge sharply between direct parental procurement and institutional volume purchasing, reshaping certification documentation and pricing transparency requirements.
- Parents:Primary decision-makers conducting crash-test rating research through independent safety advocacy platforms before purchasing through manufacturer-owned digital storefronts.
- Caregivers:Institutional purchasers in licensed childcare facilities requiring batch consistency and simplified sanitization protocols for high-frequency daily use.
- Retailers:Multi-brand distributors negotiating slotting fees and return privileges while managing inventory exposure to seasonal birth-rate fluctuations.
- Distributors:Wholesale intermediaries consolidating freight volumes across stroller and car seat SKUs for regional pharmacy and hypermarket chains.
Parental direct purchasing commands the dominant revenue share, while Caregivers is expanding most quickly as formal childcare enrollment rises.
Material:
Bill-of-materials composition determines weight, durability, and regulatory compliance cost structures across frame and textile subsystems.
- Fabric:Polyester-nylon blends with REACH-compliant flame-retardant treatments dominate stroller canopy and car seat upholstery applications.
- Plastic:Polypropylene and ABS polymer-composite formulations constitute the majority of high chair trays, playard frames, and stroller joint housings.
- Metal:Aluminum alloy tubing in stroller chassis and high chair legs captures premium positioning through sub-5kg total product weights.
- Wood:Birch and beech hardwoods in heirloom-positioned high chairs and nursery furniture serve aesthetic differentiation in German and French retail channels.
Plastic maintains the dominant share, though Metal is gaining share fastest on lightweighting imperatives.
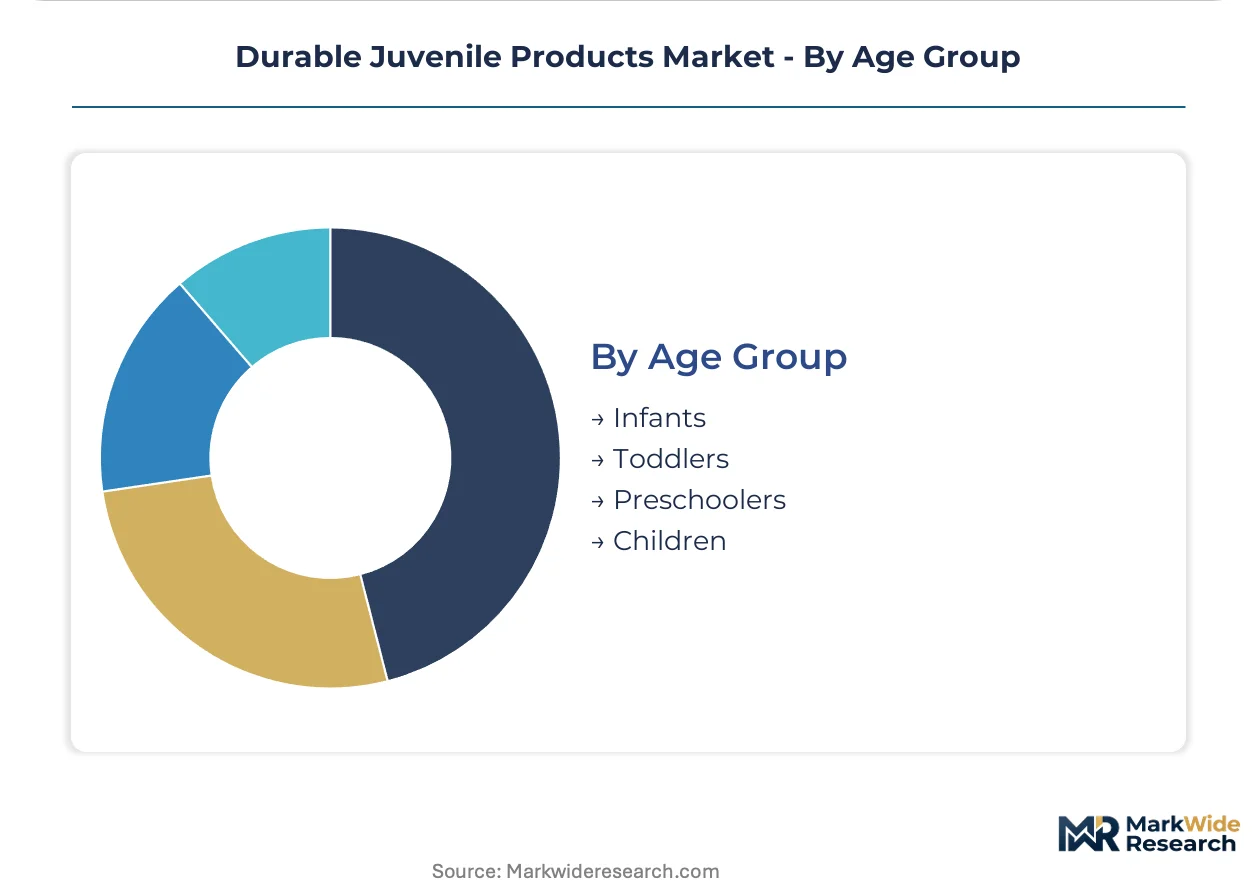
Age Group:
Developmental milestones dictate restraint system geometry, weight capacity ranges, and product replacement cadence across the childhood continuum.
- Infants:Rear-facing car seats with newborn insert systems and flat-lying stroller bassinet attachments serve birth-to-12-month physiological requirements.
- Toddlers:Forward-facing convertible car seats and upright stroller seating accommodate 1-3 year mobility and feeding independence transitions.
- Preschoolers:Booster seats and activity-centered high chairs address 3-5 year social participation and safety positioning needs.
- Children:Backless boosters and youth stroller configurations extend product utility through 8-12 year ranges in select jurisdictions.
Infants commands the dominant share, while Toddlers is climbing the fastest on convertible product attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Consumer Product Safety Commission anchors the dominant geography through mandatory third-party testing requirements that elevate compliance costs for new entrants. China and Vietnam reshape supply-side configuration through manufacturing capacity expansion and labor cost differentials. European regulatory divergence under REACH and the EU Green Deal fragments test-protocol harmonization.
United States
California and Texas metropolitan clusters concentrate parental purchasing power for premium stroller configurations. The US Consumer Product Safety Improvement Act mandates third-party testing and chemical-content thresholds that compress margin pools for mid-tier producers. Greater Los Angeles and Dallas-Fort Worth anchor distribution infrastructure for direct-to-parent digital channels displacing legacy retail footprints.
Germany
Bavaria and Baden-Württemberg industrial zones sustain automotive-tier engineering capabilities transferred to car seat crash-test validation. The EU General Product Safety Regulation and ECHA REACH chemical restrictions force polymer reformulation across frame supply chains. Stuttgart and Munich host specialized testing laboratories where EN 1888 structural validation expertise concentrates among limited engineering personnel.
China
Guangdong and Zhejiang provinces concentrate vertically integrated manufacturing for stroller and car seat assembly. GB standards and CCC certification create parallel technical requirements duplicative with export market protocols. Shenzhen and Ningbo industrial parks reshape procurement patterns through domestic middle-class consumption expansion and coastal manufacturing capacity.
Vietnam
Ho Chi Minh City industrial zones capture redirected assembly capacity from traditional China hubs through labor cost differentials and tariff mitigation strategies. The Ministry of Industry and Trade oversees export-oriented manufacturing qualification timelines for EU and US-bound production. Binh Duong and Dong Nai provinces anchor supply chain reconfiguration compressing lead times for European stroller distributors.
India
Maharashtra and Delhi-NCR urban corridors present underpenetrated organized retail channels for car seat brands establishing localized distribution. The Bureau of Indian Standards and CDSCO oversee emerging product safety frameworks for juvenile mobility categories. Mumbai and Bangalore concentrate rising middle-class consumption driving first-mover advantages for international entrants.
Durable Juvenile Products Market Vendor Landscape
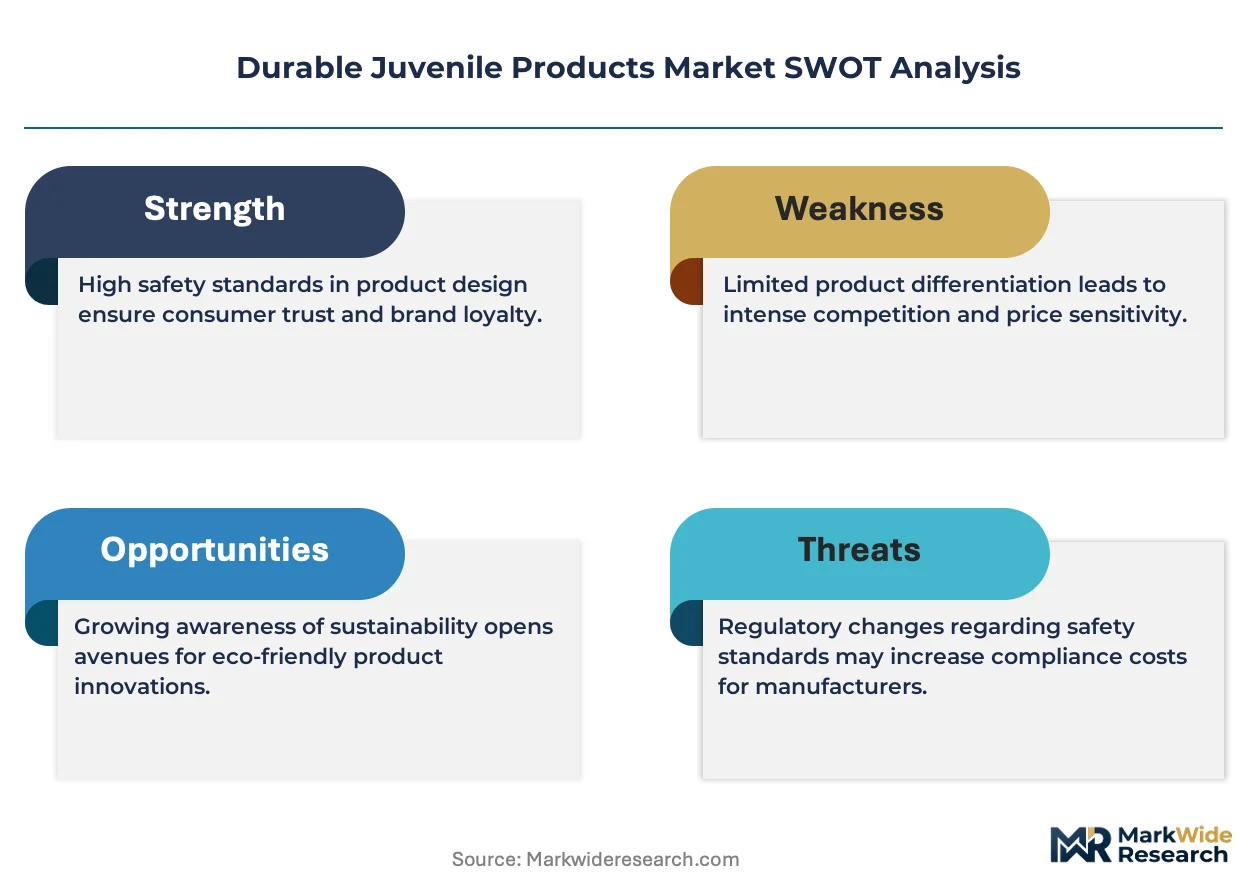
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where crash-test certification depth separates premium positioning from commodity assembly. The vendor base organizes around three archetypes: vertically integrated manufacturers with captive testing laboratories, brand licensors outsourcing production to contract fabricators, and regional assemblers serving domestic markets with simplified certification. M&A activity concentrates testing laboratory acquisition and geographic manufacturing expansion. Portfolio diversification moves span adjacent mobility categories and subscription-based access models.
Within the vertically integrated tier, Goodbaby International Holdings and Dorel Juvenile exemplify divergent geographic anchoring strategies. Artsana occupies a position representing European brand heritage and pediatric safety certification depth. These three entities sit within distinct competitive vectors: China-based manufacturing scale, North American distribution anchoring, and continental European regulatory compliance specialization.
| Leading Market Players |
|---|
| Dorel Juvenile |
| Goodbaby International Holdings |
| Artsana |
| Newell Brands |
| Britax |
| Graco |
| Chicco |
| Evenflo |
| Stokke |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on China-sourced polymer-composite frames determines both pricing tier spreads and supply chain shape across stroller and car seat production. Buyers face widening cost differentials between Vietnam-assembled and China-origin units as manufacturers reconfigure factory footprints to mitigate duty impacts.
Pricing Analysis
China-to-Vietnam price spreads now exceed transport-adjusted labor cost differentials across premium stroller lines. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated models from basic polymer-frame configurations, with certification grade and volume scale as primary differentiation drivers. Cost compression in mid-tier segments is intensifying because polymer resin input volatility transfers directly to frame material costs. Institutional caregivers exhibit highest price sensitivity due to batch procurement mandates, while direct-to-parent digital buyers absorb premium positioning for connected safety features.
Supply Chain Analysis
Polypropylene and ABS resin feedstock draws from petrochemical complexes in China, South Korea, and Saudi Arabia before compounding into stroller frame substrates. Aluminum alloy tubing for lightweight chassis rests on extrusion capacity concentrated in Guangdong, Zhejiang, and Ho Chi Minh City industrial zones. Single-source vulnerability concentrates in specialized five-point harness webbing production tethered to limited textile mills. Distribution runs through manufacturer-owned digital storefronts displacing legacy baby specialty retail in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart harness sensor platforms are redefining this market as a hardware-software ecosystem where firmware subscription revenue displaces one-time hardware margins. Interoperability between stroller load-cell sensors and pediatric health applications creates network effects that concentrate value capture with integrated platform operators.
For Market Incumbents: Build certification moats through captive EN 1888 and ASTM F833 testing laboratory acquisition. Incumbent manufacturers should consolidate crash-test engineering talent in Stuttgart and Munich to preempt development timeline extension from specialist scarcity. Channel control through direct-to-parent digital storefronts defends margin position against wholesale dependency erosion. For New Entrants and Emerging Players: Pursue subscription-based stroller access models in London and New York urban corridors where apartment-dwelling parents favor short-term leasing over ownership. White-space concentration sits in India organized retail channels across Mumbai and Delhi-NCR where car seat penetration remains underdeveloped. Go-to-market execution through localized distribution partnerships with pharmacy and hypermarket chains accelerates footprint establishment. For Investors and Strategic Acquirers: The market sits at a platform-economics inflection phase that favors vertically integrated manufacturers with captive testing infrastructure. Long-term viability across the projection horizon hinges on sensor integration capabilities and recurring revenue attachment rates. Acquisition target archetype: mid-cap specialists with GB standards certification and Vietnam manufacturing qualification. Signal to watch: firmware update subscription attach rates on premium stroller lines as indicator of ecosystem monetization traction.| Strategic Initiative | Industry Significance |
|---|---|
| Testing Laboratory Acquisition | Captive EN 1888 validation capability compresses product development timelines for crash-test certification. |
| Vietnam Manufacturing Footprint | Ho Chi Minh City assembly capacity mitigates tariff exposure on US-bound stroller and car seat shipments. |
| Sensor Platform Integration | Load-cell harness monitoring enables recurring firmware subscription revenue beyond initial hardware sale. |
| Direct-to-Consumer Channel Launch | Manufacturer-owned digital storefronts disintermediate legacy retail and concentrate margin capture with brand owners. |
| Bio-Polymer Material Transition | REACH-compliant frame materials preempt ECHA chemical restriction expansion in German and French retail channels. |
Methodological Framework
A standing panel of product safety engineers, stroller category buyers at major retailers, car seat crash-test specialists, and supply chain directors at polymer compounders provided ongoing calibration across primary fieldwork. Secondary validation drew from CPSC recall databases, EU RAPEX safety alerts, GB standards documentation, and customs trade records. Bottom-up SKU-level demand modeling and top-down category value triangulation anchored volume and value estimates.
Scenario-bracketing around polymer resin price volatility, tariff regime shifts, and regulatory divergence produced bounded forecast ranges across the analysis window. Segmentation dimensions modeled include product type, material composition, end-user channel, and age group developmental stage. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution, with replacement-cycle regulations and birth rate patterns as category-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in crude oil prices, China-US trade policy, and EU chemical restriction timelines would shift the trajectory. Cross-checking against independent safety advocacy platform sales data and retailer inventory turnover metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Global Baby Play Mats Market
Baby Products
Baby Bottle Warmers Market
Baby Products
Silicone Baby Product Market
Baby Products
Baby Changing Station Market
Baby Products
Japan Baby Care Product Market
Baby Products
North America Baby Bottle Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Postpartum Products Market
Baby Products
India Baby Care Products Market
Baby Products
Canada Baby Care Products Market
Baby Products
Baby Slings Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Baby Wipes Market
Baby Products
Pregnancy Products Market
Baby Products
Feeding Pillow Market
Baby Products
Stroller Rental Market