
 LAMEA Baby Care Products Market | 2026-2036
LAMEA Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Baby Care Products Market Analytics
Aftermarket service revenue from subscription diaper replenishment and pediatric telehealth bundling is narrowing as direct-to-consumer platforms capture recurring spend. The Procter & Gamble Company leverages its Lagos manufacturing footprint to control last-mile distribution economics. Johnson & Johnson sustains pharmacy channel dominance through clinician endorsement programs. Kimberly-Clark Corporation anchors its competitive position with locally sourced fluff pulp supply chains.
LAMEA baby care products encompass topical formulations, absorbent hygiene articles, and cleansing substrates engineered with pH-balanced surfactant systems, superabsorbent polymer cores, and hypoallergenic emollient bases, manufactured through hot-melt adhesive lamination and aqueous gel extrusion processes to maintain infant skin barrier integrity. Diapers and wipes command the largest volume pools, though baby lotion and shampoo segments attract disproportionate margin capture through premium natural-positioned SKUs. Online distribution channels exhibit the steepest trajectory, while supermarkets retain inventory breadth across mass and mid-tier price bands.
ANVISA in Brazil enforces pediatric cosmetic safety dossiers that elevate barrier-to-entry costs for new entrants. South Africa's national pharmaceutical regulator mandates child-resistant packaging and ingredient disclosure thresholds that reshape product development timelines. Nigeria's Standards Organisation regulates absorbent hygiene product absorbency ratings, directing procurement specifications for institutional buyers. Stakeholders must monitor regulatory harmonization pressures between Mercosur and AfCFTA frameworks that could fragment compliance architectures.
Market Dynamics
ANVISA's tightened pediatric cosmetic safety dossiers in Brazil are forcing reformulation investments across the LAMEA baby care value chain, compressing margins for non-compliant suppliers while elevating barriers for new entrants.
Growth Catalysts
- ANVISA Safety Dossiers:Brazil's cosmetic regulator mandates dermatologist-tested formulations, pulling premium natural-positioned SKUs into mainstream pharmacy channels.
- Urban Millennial Parents:São Paulo and Lagos buyer clusters prioritize hypoallergenic emollient bases, creating concentrated demand pools for pH-balanced surfactant systems.
- Modern Trade Penetration:Nigeria's Lagos-Abuja corridor sees supermarket inventory breadth expanding across mid-tier price bands, capturing rising disposable incomes.
Market Restraints
- Fluff Pulp Supply Concentration:Kimberly-Clark's locally sourced supply chains in South Africa create input dependency for competing absorbent hygiene manufacturers.
- Superabsorbent Polymer Cost Volatility:Petroleum-derived SAP cores expose diaper producers to feedstock price swings with limited hedging instruments in regional markets.
- Regulatory Fragmentation Risk:Potential Mercosur-AfCFTA harmonization pressures threaten to multiply compliance architectures without unified standards.
Strategic Opportunities
- Pediatric Telehealth Bundling:Direct-to-consumer platforms in Nigeria can integrate subscription diaper replenishment with clinician endorsement programs.
- Natural-Positioned SKU Expansion:Baby lotion and shampoo segments attract disproportionate margin capture through aqueous gel extrusion process innovations.
- Online Channel Steepest Trajectory:Brazil's e-commerce infrastructure enables last-mile distribution economics control independent of traditional pharmacy dominance.
Industry Challenges
- Child-Resistant Packaging Compliance:South Africa's national pharmaceutical regulator mandates extended product development timelines for infant skincare formulations.
- Absorbency Rating Certification:Nigeria's Standards Organisation regulates institutional procurement specifications, requiring specialized testing infrastructure.
- Hot-Melt Adhesive Lamination Skill Gap:Technical workforce scarcity for maintaining infant skin barrier integrity in manufacturing processes constrains capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Baby Care Products Market |
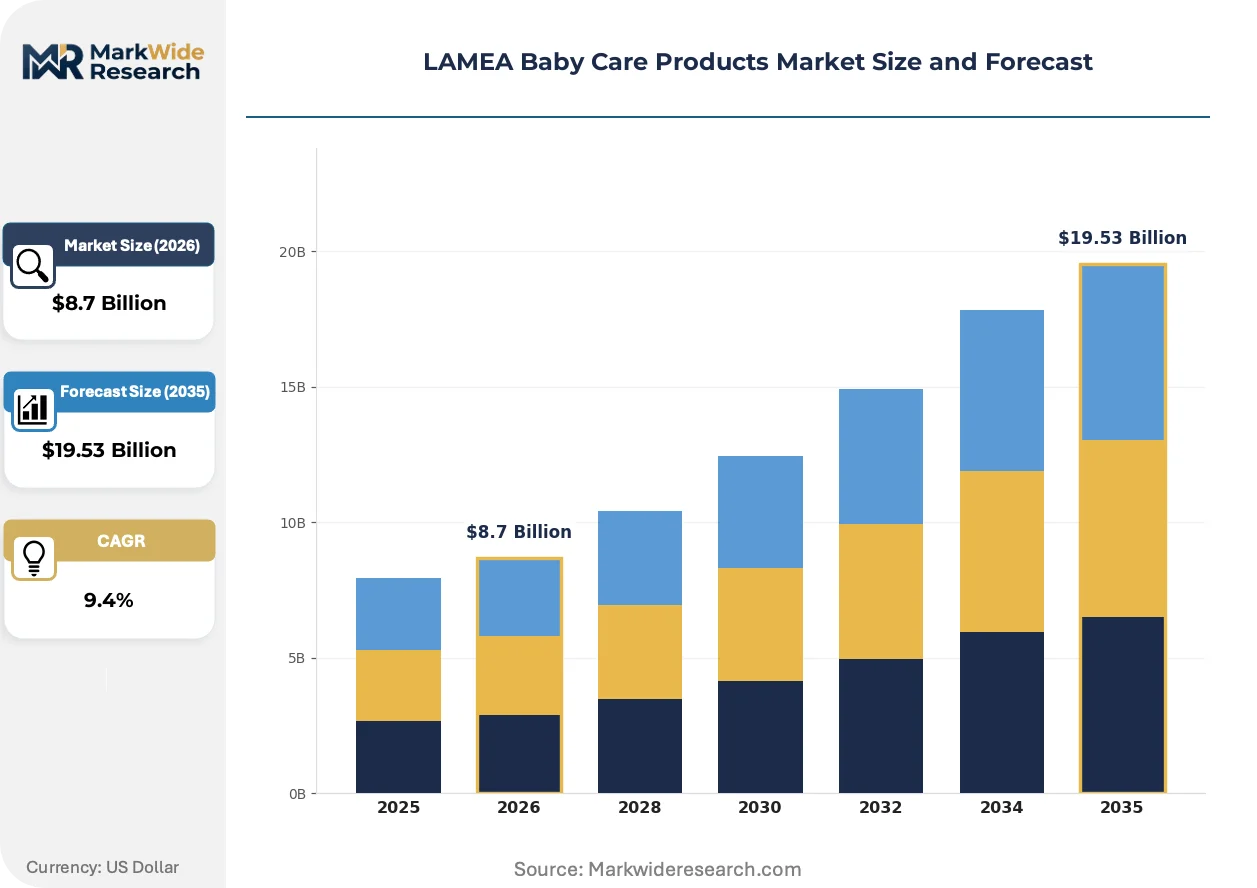
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Wipes, Baby Lotion, Shampoo Customer Type: Parents, Guardians, Caregivers, Retailers Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores Age Group: Newborns, Infants, Toddlers, Preschoolers |
| Companies Covered | The Procter & Gamble Company, Johnson & Johnson, Kimberly-Clark Corporation, Unilever PLC, Beiersdorf AG, L'Oreal S.A., Reckitt Benckiser Group PLC, Himalaya Wellness Company, Artsana S.p.A., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Baby Care Products Market Evolving Landscape
Formulation science and channel architecture are actively reshaping competitive positioning in LAMEA baby care, with technology convergence and regulatory pressure driving premiumization at the product level while digital platforms reconfigure distribution economics.
Superabsorbent polymer core engineering is migrating from petroleum-derived substrates toward bio-based alternatives. Urban millennial parents in São Paulo demand higher absorbency ratings with reduced environmental footprint. This shift is compressing traditional SAP suppliers while enabling new entrants with cellulose-based innovations to capture pharmacy shelf space.
Brazil's ANVISA enforcement of pediatric cosmetic safety dossiers elevates barrier-to-entry costs across topical formulation categories. Manufacturers must submit dermatologist-testing documentation before market authorization. Baby lotion and shampoo segments face the steepest compliance timelines, with reformulation investments concentrating among established players with captive laboratory infrastructure.
Subscription-based replenishment models are displacing traditional supermarket bulk purchasing among Lagos-Abuja corridor households. Direct-to-consumer platforms bundle diaper auto-delivery with pediatric telehealth access, capturing recurring spend that aftermarket service revenue previously commanded. This channel rotation is most visible in Nigeria's modern trade penetration zones where smartphone penetration enables app-based ordering.
LAMEA Baby Care Products Market Segmentation
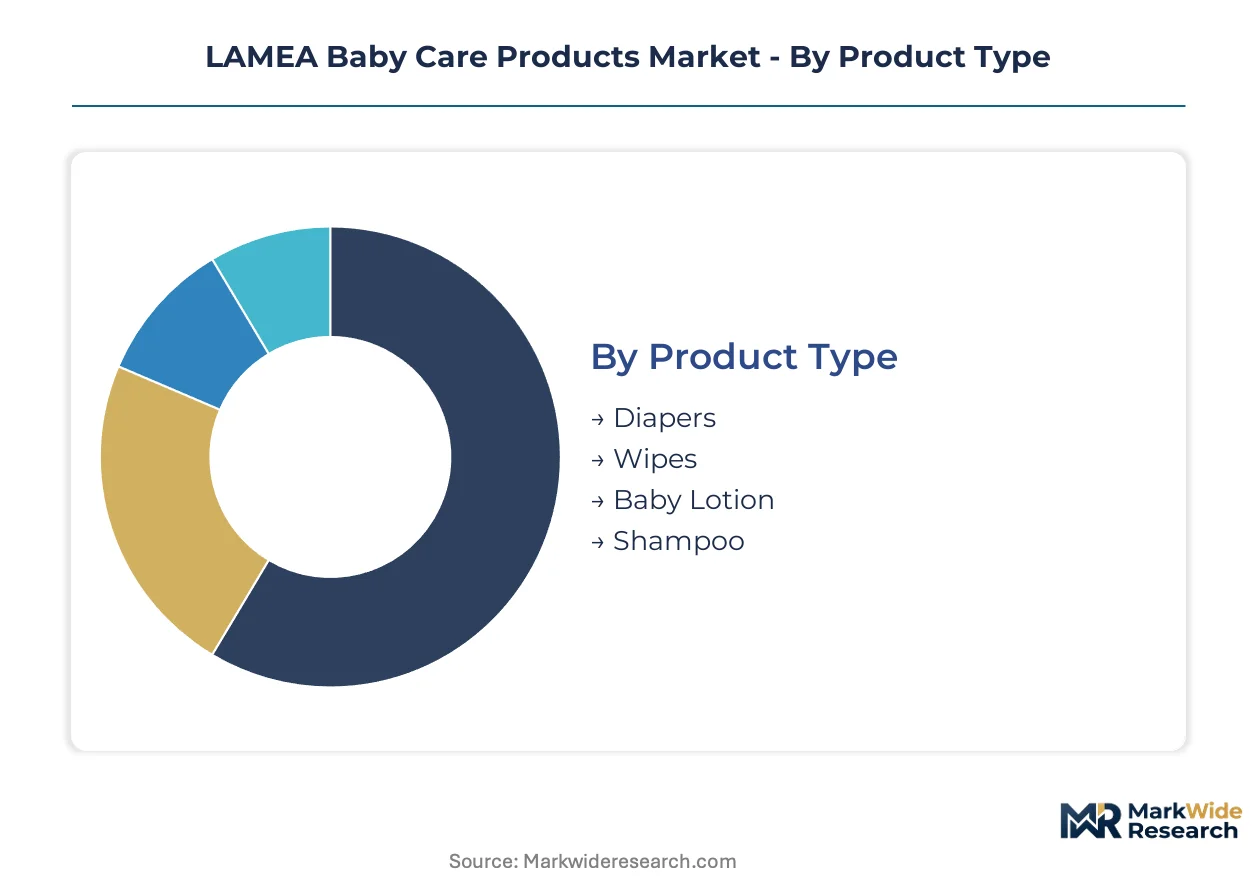
Segmentation in LAMEA baby care products determines where formulation investments concentrate and which channels capture recurring revenue. Understanding these splits reveals why diapers and wipes dominate volume while lotions and shampoos command premium positioning in pharmacy networks.
Product Type:
After-sales service intensity varies sharply across product categories, with absorbent hygiene requiring replenishment infrastructure and topical formulations demanding clinical support channels.
- Diapers:Superabsorbent polymer cores engineered through hot-melt adhesive lamination dominate manufacturing. Demand concentrates in Nigeria's Lagos-Abuja corridor where modern trade penetration enables subscription auto-delivery models.
- Wipes:pH-balanced surfactant systems on nonwoven substrates require dermatologist-tested formulation dossiers for ANVISA compliance. São Paulo's urban millennial parents pull premium natural-positioned SKUs into mainstream pharmacy inventory.
- Baby Lotion:Hypoallergenic emollient bases with aqueous gel extrusion processes serve infant skin barrier integrity requirements.
- Shampoo:Mild cleansing formulations with tear-free surfactant systems target daily hygiene routines.
By volume, Diapers leads. By growth pace, Baby Lotion is ahead.
Customer Type:
Cost tier differentiation separates institutional procurement from household purchasing, with retailers acting as volume aggregators for absorbent hygiene.
- Parents:Primary decision-makers prioritizing dermatologist-tested formulations and pediatric telehealth bundling options in direct-to-consumer platforms.
- Guardians:Secondary caregivers with distinct price sensitivity profiles and bulk purchasing patterns in supermarket channels.
- Caregivers:Institutional buyers including daycare operators and healthcare facilities with standardized absorbency rating requirements.
- Retailers:Inventory aggregators controlling last-mile distribution economics through locally sourced supply chain relationships.
By transaction frequency, Parents dominate. By volume per transaction, Retailers lead.
Distribution Channel:
Channel maturity determines margin capture, with digital platforms exhibiting the steepest trajectory while established formats retain inventory breadth.
- Online:Direct-to-consumer platforms integrating subscription diaper replenishment with pediatric telehealth access capture recurring spend from Lagos-Abuja corridor households.
- Supermarkets:Modern trade penetration zones in Nigeria and Brazil retain mass and mid-tier price band breadth for bulk purchasing.
- Pharmacies:Clinician endorsement programs sustain Johnson & Johnson's channel dominance for premium topical formulations.
- Specialty Stores:Curated natural-positioned SKU assortments serve urban millennial parent preferences in São Paulo.
By current share, Supermarkets leads. By expansion trajectory, Online is climbing fastest.
Age Group:
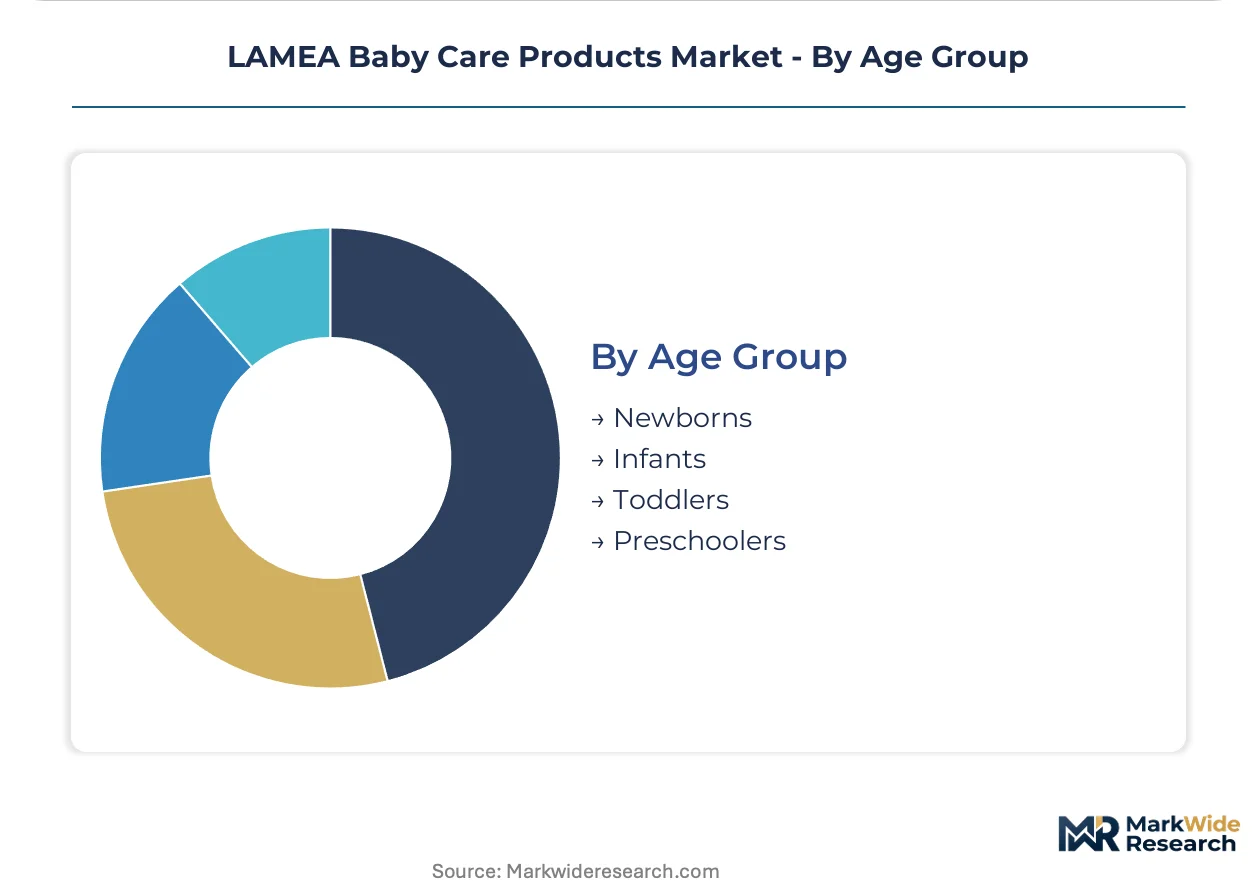
Application requirements shift dramatically across developmental stages, from newborn skin barrier sensitivity to preschooler independence in hygiene routines.
- Newborns:Highest dermatological sensitivity requiring pH-balanced emollient bases and hypoallergenic certification standards.
- Infants:Rapid growth cycles driving diaper size progression and highest per-capita consumption intensity.
- Toddlers:Transition products including training pants and mild cleansing formulations for developing independence.
- Preschoolers:Standardized personal care routines with reduced formulation sensitivity and lower per-unit consumption.
By unit consumption intensity, Infants leads. By premium positioning opportunity, Newborns commands highest margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across LAMEA, with Nigerian buyers in informal trade zones exhibiting acute sensitivity while São Paulo's urban millennial parents absorb premium positioning for dermatologist-tested formulations. Brazil's regulatory stringency elevates compliance costs that compress margins in mass-market segments. South Africa's developed retail infrastructure enables tiered pricing architecture that segments demand more cleanly than elsewhere in the region.
Brazil
ANVISA's pediatric cosmetic safety dossiers mandate dermatologist-tested documentation for infant skincare authorization, compelling reformulation investments among established manufacturers. São Paulo anchors demand concentration where urban millennial parents pull premium natural-positioned SKUs into mainstream pharmacy channels. The city's modern trade penetration enables subscription auto-delivery models that capture recurring spend from convenience-seeking households.
Nigeria
The Lagos-Abuja corridor concentrates acute demand as rising disposable incomes reshape purchasing patterns toward mid-tier price bands. The Standards Organisation regulates absorbent hygiene product absorbency ratings, directing procurement specifications for institutional buyers including healthcare facilities and daycare operators. Lagos-based direct-to-consumer platforms integrate subscription diaper replenishment with pediatric telehealth access, displacing traditional supermarket bulk purchasing.
South Africa
The national pharmaceutical regulator mandates child-resistant packaging and ingredient disclosure thresholds that extend product development timelines for topical formulations. Johannesburg and Cape Town retail zones retain inventory breadth across mass and premium tiers, enabling clearer demand segmentation than in less developed markets. Locally sourced fluff pulp supply chains create input dependencies that shape competitive positioning among absorbent hygiene manufacturers.
Saudi Arabia
SFDA oversight of cosmetic safety standards elevates barrier-to-entry costs for imported infant skincare formulations, favoring established multinationals with regulatory affairs infrastructure. Riyadh and Jeddah urban clusters exhibit demand for premium-positioned products aligned with Gulf consumer preferences for clinically endorsed formulations. Modern pharmacy chains in these metros sustain clinician endorsement programs that reinforce brand loyalty among first-time parents.
United Arab Emirates
MOHAP registration requirements for infant care products create compliance timelines that disadvantage smaller importers without dedicated regulatory capacity. Dubai's retail infrastructure serves as a regional distribution hub, with re-export flows extending into adjacent Gulf and East African markets. The emirate's e-commerce penetration enables direct-to-consumer platforms to capture recurring spend from expatriate households seeking familiar international brands.
LAMEA Baby Care Products Market Competitive Landscape
Capability concentration sits with multinational manufacturers possessing captive laboratory infrastructure for ANVISA dossier preparation; scale advantage sits with regionally anchored players controlling last-mile distribution economics. The market structures around three archetypes: global FMCG conglomerates with diversified baby care portfolios, regional specialists with deep pharmacy channel relationships, and emerging direct-to-consumer platforms leveraging subscription mechanics. Dominant competitive moves include strategic partnerships with pediatric telehealth providers and backward integration into locally sourced raw material supply chains.
Among global FMCG conglomerates, The Procter & Gamble Company, Johnson & Johnson, and Kimberly-Clark Corporation exemplify the capability-scale dual advantage. P&G's Lagos manufacturing footprint represents regional production anchoring that controls distribution economics. Johnson & Johnson occupies a position within the clinician endorsement archetype that sustains pharmacy channel dominance. Kimberly-Clark exemplifies supply chain integration through locally sourced fluff pulp relationships that create competitive moats in absorbent hygiene categories.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| Johnson & Johnson |
| Kimberly-Clark Corporation |
| Unilever PLC |
| Beiersdorf AG |
| L'Oreal S.A. |
| Reckitt Benckiser Group PLC |
| Himalaya Wellness Company |
| Artsana S.p.A. |
| Others |
Value Network & Pricing Analysis
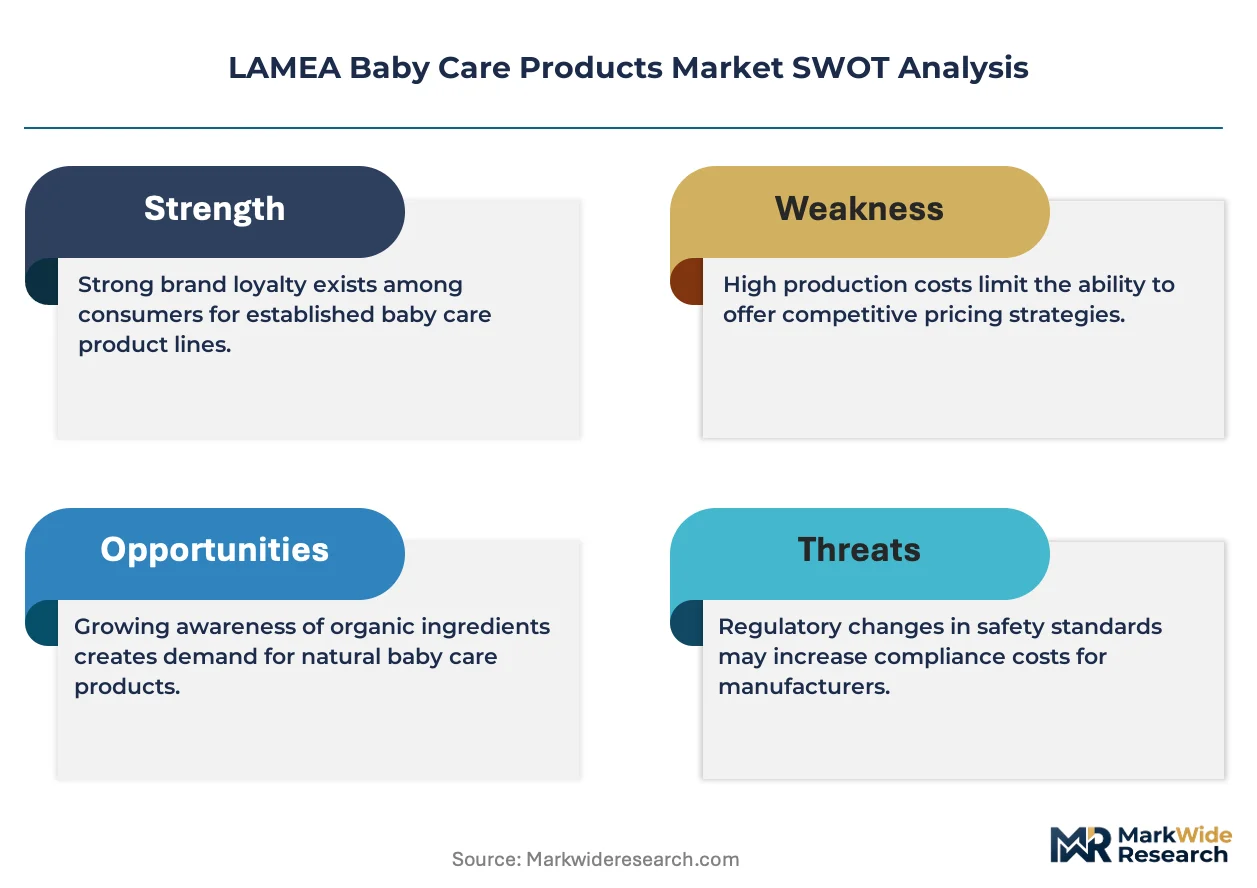
ANVISA pediatric cosmetic safety dossiers in Brazil create a regulatory chokepoint that simultaneously widens pricing tier spreads between compliant and non-compliant suppliers while forcing supply chain consolidation toward manufacturers with captive laboratory infrastructure. This single-source dependency on dermatologist-tested formulation capabilities elevates premium tier pricing power while compressing mass-market margins across the LAMEA value chain.
Pricing Analysis
Subscription diaper replenishment and pediatric telehealth bundling now drives lifetime value capture for direct-to-consumer platforms in Nigeria's Lagos-Abuja corridor. Three-tier pricing structure across premium dermatologist-certified, standard pharmacy-grade, and economy supermarket tiers separates buyers by certification level and channel access. Cost compression in mass-market diaper segments is intensifying because petroleum-derived superabsorbent polymer feedstock volatility lacks regional hedging instruments. Institutional buyers including daycare operators exhibit highest price sensitivity, while São Paulo's urban millennial parents absorb premium positioning for natural-positioned SKUs with minimal elasticity.
Supply Chain Analysis
Tariff exposure between Brazil and Mercosur trading partners dominates supply chain risk calculus for topical formulation importers seeking ANVISA compliance. Manufacturing concentration centers on Brazil, South Africa, and Nigeria for finished goods, with raw material dependencies on imported superabsorbent polymers, fluff pulp, and pH-balanced surfactant systems. Single-source vulnerability persists in petroleum-derived SAP cores and specialized hot-melt adhesive lamination equipment. Distribution runs through pharmacy networks for premium tiers, supermarket modern trade for mid-market volume, and direct-to-consumer platforms for subscription replenishment in urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ANVISA's dermatologist-testing mandates create switching costs that institutionalize incumbent advantages and fragment competitive response capabilities.
For Market Incumbents: Entrench pharmacy channel dominance through clinician endorsement program expansion in São Paulo and Lagos. Deepen backward integration into locally sourced fluff pulp supply chains to neutralize Kimberly-Clark's South African cost advantage. Defensive capacity investment in ANVISA-compliant laboratory infrastructure raises barriers against emerging direct-to-consumer platforms seeking formulation credibility.
For New Entrants and Emerging Players: Nigeria's secondary cities beyond the Lagos-Abuja corridor represent the most penetrable white-space geography for subscription diaper replenishment models. Target caregiver institutional procurement with absorbency rating certification from Nigeria's Standards Organisation as the entry wedge. Natural-positioned baby lotion SKUs in specialty retail channels offer lower regulatory friction than pharmacy-dependent segments.
For Investors and Strategic Acquirers: Regional direct-to-consumer platforms with proven subscription mechanics and pediatric telehealth integration present the highest-value acquisition archetype for portfolio exposure to channel rotation. Long-term viability rests on capturing recurring spend displacement from traditional supermarket bulk purchasing. Monitor ANVISA enforcement intensity as the inflection signal for compliance cost trajectories and margin compression timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Telehealth Bundling | Direct-to-consumer platforms in Nigeria capture recurring spend through clinician-endorsed diaper subscription integration. |
| ANVISA Compliance Laboratory Investment | Captive dermatologist-testing infrastructure elevates barrier-to-entry costs for infant skincare market authorization. |
| Locally Sourced Fluff Pulp Integration | Kimberly-Clark's South African supply chain relationships create input cost advantages in absorbent hygiene manufacturing. |
| Natural-Positioned SKU Extension | Baby lotion and shampoo segments command disproportionate margin capture through aqueous gel extrusion process innovations. |
| Modern Trade Channel Penetration | Supermarket inventory breadth expansion across Nigeria's mid-tier price bands captures rising disposable incomes. |
Research Methodology
Desk research of ANVISA regulatory filings, Nigerian Standards Organisation absorbency specifications, and South African pharmaceutical packaging mandates preceded structured interviews with brand managers at multinational FMCG conglomerates, category buyers at modern trade retailers, supply chain planners at absorbent hygiene manufacturers, and regulatory affairs specialists at topical formulation companies. Secondary validation drew from customs trade data, pharmacy channel audit reports, and e-commerce platform transaction disclosures. Bottom-up demand modeling across product type, customer segment, distribution channel, and age group dimensions was cross-checked against top-down macroeconomic consumption indicators.
Fixed assumptions across the projection horizon include ANVISA enforcement continuity at current intensity levels, petroleum-derived superabsorbent polymer cost volatility within historical bands, and smartphone penetration enabling direct-to-consumer platform growth in urban corridors. Segmentation dimensions modeled encompass product formulation complexity, channel maturity tier, customer procurement scale, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for identified inflection vectors including modern trade penetration rates and subscription adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by emerging direct-to-consumer platforms or accelerated ANVISA harmonization with Mercosur standards would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Digital Monitor Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Baby Wipes Market
Baby Products
Global Baby Carriers Market
Baby Products
Baby Stroller Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
Baby Nipple/Teat Market
Baby Products
Baby Products Detergents Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Global Baby Product Market
Baby Products
Canada Baby Care Products Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Australia Baby Care Products Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
Potty Training Seat Market
Baby Products
Brazil Baby Care Products Market