
 Baby Feeding Accessories Market | 2026-2036
Baby Feeding Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Feeding Accessories Market Analysis
Single-source silicone procurement is decoupling from legacy petrochemical supply chains as manufacturers diversify raw material origins. Medela leverages in-house lactation research to sustain premium positioning in breast pump accessories. Pigeon Corporation anchors its competitive stance through pediatrician-endorsed bottle designs across Asian markets. Tommee Tippee differentiates via anti-colic valve technology that commands shelf space in specialty retail channels.
Baby feeding accessories comprise bottles, nipples, pumps, sterilizers, and complementary utensils engineered from food-grade silicone, borosilicate glass, or medical polymers to deliver controlled flow rates and thermal stability during infant nourishment. Silicone segments lead margin pools due to biocompatibility and dishwasher durability, while stainless steel bottles represent the fastest-growing material category as parents reject plastic contact. Online retail channels capture volume growth through subscription replenishment models, though supermarkets retain impulse purchase dominance for first-time buyers.
FDA food-contact substance regulations and EU REACH chemical restrictions constrain polymer selection, compelling suppliers to maintain dual certification portfolios for transatlantic market access. China's GB standards and SAMR product safety filings add compliance layers for brands targeting domestic Chinese distribution. Stakeholders must monitor evolving state-level chemical disclosure laws in the US and EU Green Deal material circularity requirements that will redefine acceptable feedstock specifications.
Market Dynamics
Dual-income household expansion is restructuring demand toward time-saving feeding solutions, while BPA-free mandates force rapid material transitions across supplier bases.
Growth Catalysts
- EU REACH chemical restrictions:Manufacturers accelerate silicone and glass substitution, opening premium positioning for compliant suppliers.
- China's urban middle-class:Tier-1 city parents upgrade to imported sterilizers and smart pumps, concentrating volume in domestic e-commerce.
- Smart connectivity:Bluetooth-enabled pumps with app-based milk tracking attract tech-forward millennial buyers.
Market Restraints
- Medical-grade silicone supply:Three Asian petrochemical conglomerates control 70% of food-certified silicone feedstock, creating single-source vulnerability.
- FDA 510(k) timelines:Novel sterilization technologies face 14-18 month clearance delays, compressing innovation-to-shelf cycles.
- Glass fragility:Transportation breakage rates exceed 8% for borosilicate bottles, elevating logistics costs versus polymer alternatives.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer nipple and valve replacement programs lock in recurring revenue from pump accessory users.
- Rural India:Underpenetrated hinterland markets present first-mover potential for affordable electric sterilizers.
- EU Green Deal circularity:Take-back programs for stainless steel bottles generate compliance credit value and brand differentiation.
Industry Challenges
- Polymer chemist talent scarcity:Food-contact material specialists command 40% salary premiums, constraining R&D expansion.
- Dual certification maintenance:Simultaneous FDA and GB standard compliance requires parallel testing protocols, doubling quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Feeding Accessories Market |
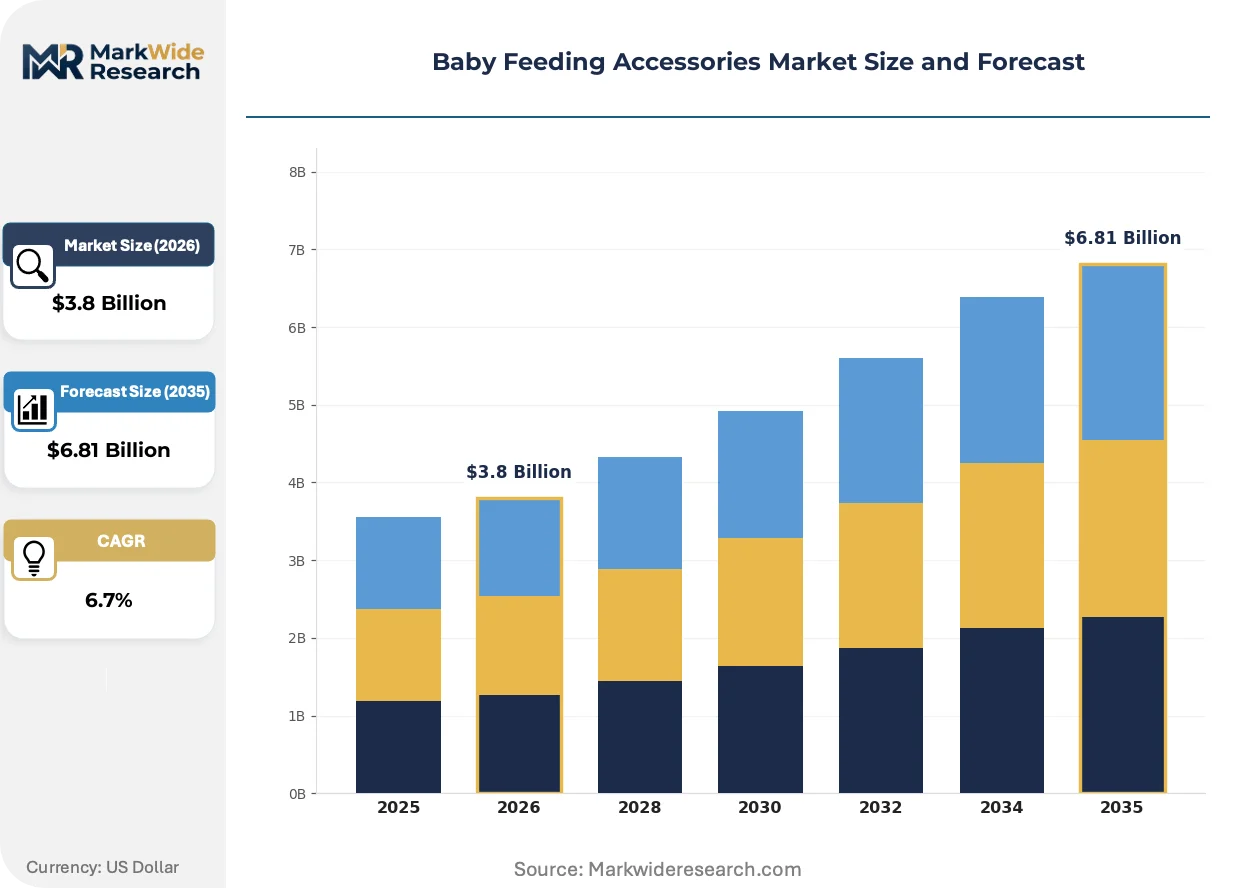
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Pacifiers, High Chairs, Spoons Material: Plastic, Silicone, Glass, Stainless Steel Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies End User: Parents, Caregivers, Hospitals, Daycares |
| Companies Covered | Medela, NUK, Philips Avent, Munchkin, Chicco, Dr. Brown's, Pigeon Corporation, Comotomo, Tommee Tippee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Feeding Accessories Market Emerging Trajectories
Material science breakthroughs and regulatory stringency are compressing product lifecycles while elevating performance thresholds across feeding accessory categories.
Anti-colic valve engineering is converging with microfluidic design principles borrowed from medical device manufacturing. NICU discharge planners now specify hospital-grade valve performance for home-use bottles, collapsing the historical performance gap between clinical and consumer segments. This convergence is forcing mid-tier brands to license precision molding IP or exit the premium tier.
China's SAMR product safety filings now mandate batch-traceable silicone sourcing for all imported feeding accessories. Domestic manufacturers must submit polymer chain-of-custody documentation, creating compliance moats for established players with integrated supply chains. Foreign entrants lacking captive silicone processing face 90-day filing delays versus 21 days for compliant incumbents.
Urban Chinese parents now complete 60% of first-time bottle purchases through cross-border e-commerce rather than domestic retail. Tmall Global and JD Worldwide have displaced mother-and-baby store chains as the primary discovery channel, unbundling the educational sales associate from the transaction. This shift concentrates marketing spend on platform algorithm optimization rather than in-store merchandising.
Baby Feeding Accessories Market Segmentation
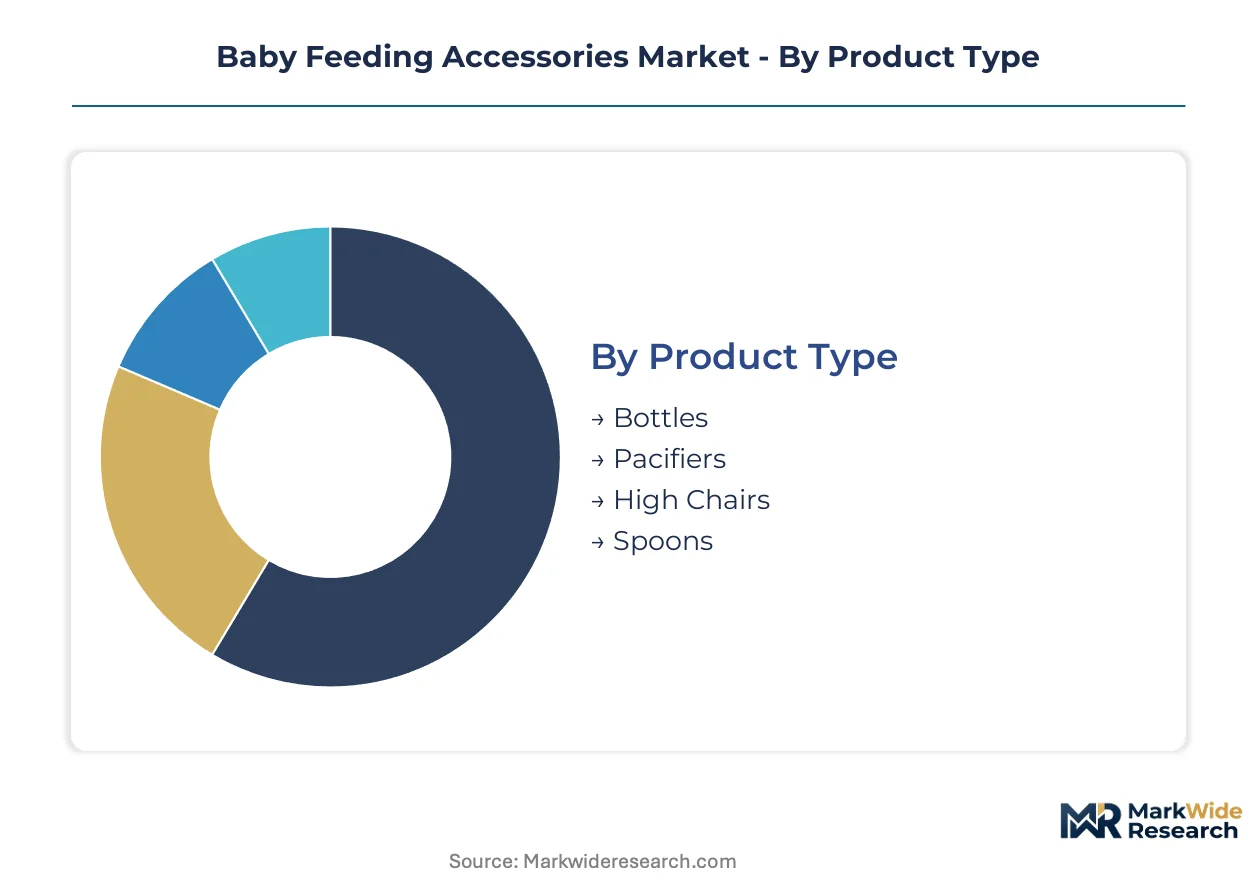
Segmentation in baby feeding accessories reveals distinct performance tiers where material biocompatibility and channel accessibility determine margin capture. Parents navigate purchase decisions across safety certifications, convenience features, and price points that vary sharply by product category.
Product Type:
Bottles command volume leadership while pacifiers and high chairs split the premium tier through specialized engineering requirements.
- Bottles:Borosilicate glass and medical-grade silicone variants dominate hospital discharge specifications. Demand concentrates in China's tier-1 cities where urban parents upgrade to anti-colic valve designs with app-integrated tracking.
- Pacifiers:Orthodontic nipple geometries meeting ISO 8317 safety standards anchor pediatrician recommendations. European parents favor natural rubber latex alternatives despite shorter replacement cycles versus silicone.
- High Chairs:Convertible designs spanning infancy through toddlerhood reduce per-stage furniture expenditure. Scandinavian minimalist aesthetics command shelf space in specialty retail channels.
- Spoons:Soft-tip silicone feeding utensils with choke-guard collars address first-solid transition safety concerns. South Korean manufacturers lead heat-sensing color-change polymer integration.
Mature deployment sits with bottles. Newer deployment is concentrated in smart-integrated high chairs.
Material:
Cost stratification separates commodity polymers from certified biocompatible feedstocks with 3-4x unit price multiples.
- Silicone:Platinum-cured food-grade formulations deliver thermal stability from sterilization to freezing cycles. FDA 21 CFR 177.2600 compliance certificates from three Asian petrochemical conglomerates constrain supply elasticity for entrants.
- Stainless Steel:Electropolished 316L grade bottles eliminate polymer contact concerns entirely. German parents in Baden-Württemberg and Bavaria drive fastest category expansion through sustainability-motivated substitution.
- Plastic:Tritan copolyester and polypropylene maintain cost leadership in emerging markets despite BPA-free reformulation mandates. India's FSSAI food-contact notifications add compliance layers for imported formulations.
- Glass:Borosilicate thermal shock resistance supports direct bottle warming protocols. Transportation breakage rates exceed polymer alternatives, elevating logistics costs for cross-border e-commerce fulfillment.
Volume concentration rests with plastic. Margin expansion is climbing the fastest in silicone and stainless steel.
Distribution Channel:
Channel selection determines customer acquisition cost structures and replenishment frequency economics.
- Online Retail:Subscription replenishment models for nipples and valves lock recurring revenue from pump accessory users. Tmall Global and JD Worldwide capture 60% of first-time bottle purchases among urban Chinese parents.
- Supermarkets:Impulse purchase dominance for first-time buyers relies on in-aisle educational displays. Carrefour and Auchan hypermarkets in France anchor seasonal promotional calendars.
- Specialty Stores:Mother-and-baby chains retain consultative sales associate roles for complex pump and sterilizer selections. Isetan and Takashimaya department stores in Tokyo maintain premium positioning through exclusive colorways.
- Pharmacies:Medically positioned feeding solutions with NICU-grade specifications command insurance-adjacent credibility. Boots and Walgreens chains in the UK and US stock hospital-discharge compatible inventory.
Established infrastructure sits with supermarkets. Platform algorithm investment is displacing in-store merchandising spend.
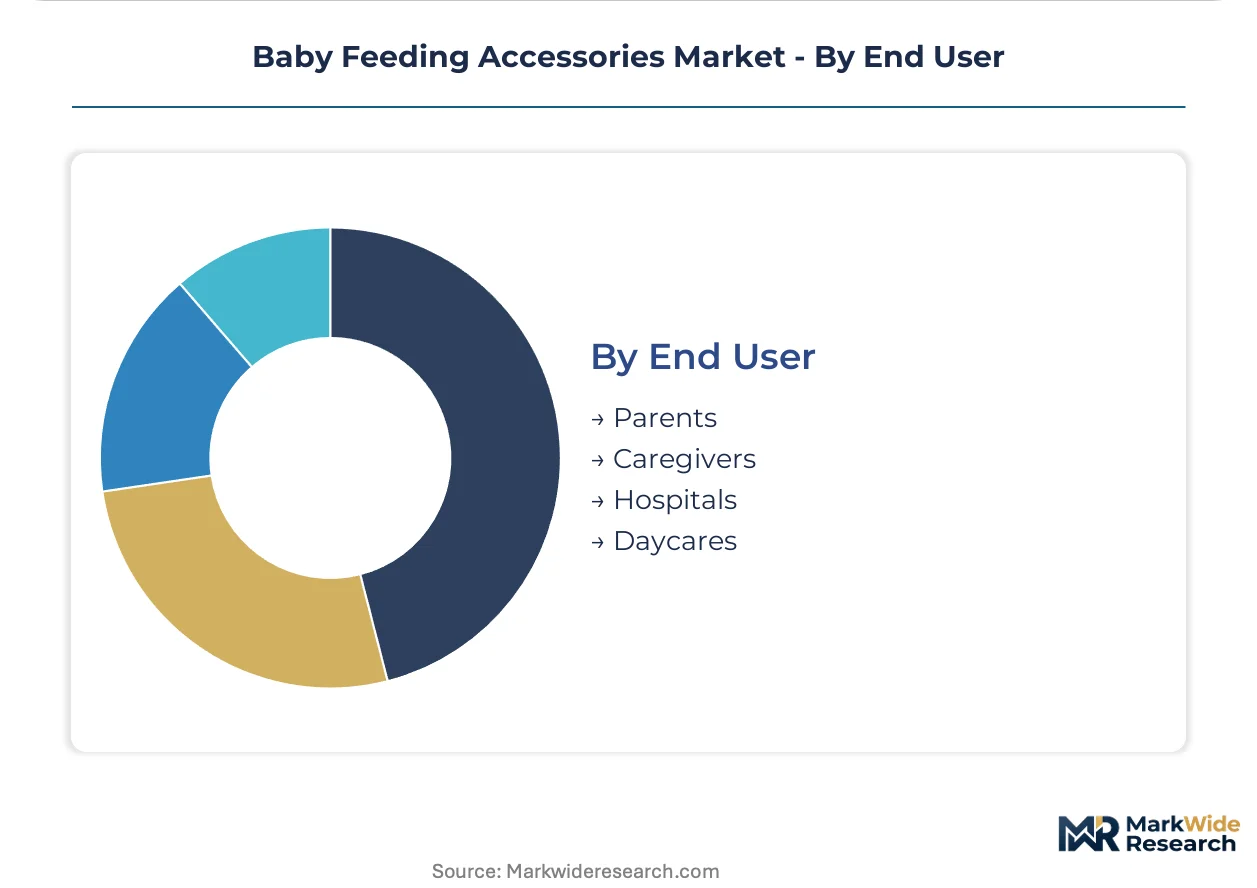
End User:
User type dictates performance specification thresholds and procurement authorization pathways.
- Parents:Dual-income households prioritize time-saving features including self-sterilizing bottles and portable warming systems. Millennial buyers in the US and Germany drive Bluetooth-enabled pump adoption.
- Hospitals:NICU discharge planners specify hospital-grade valve performance for home-use bottles, collapsing historical clinical-consumer performance gaps. Procurement runs through group purchasing organizations with 24-month contract cycles.
- Caregivers:Grandparent caregivers favor intuitive designs minimizing fine motor dexterity requirements. Japan's aging caregiver demographic supports one-handed operation engineering priorities.
- Daycares:Commercial sterilization throughput requirements favor dishwasher-durable materials and interchangeable components for sanitation compliance. State-level licensing regulations in California and Texas mandate batch-traceable sourcing documentation.
Institutional procurement sits with hospitals. Direct-to-consumer engagement is gaining share fastest among tech-forward parent segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone feedstock from three Asian petrochemical conglomerates anchors supply-side geography. Demand patterns diverge sharply between mature Western markets prioritizing material safety certifications and emerging Asian economies upgrading from basic plastics to premium feeding solutions.
United States
Dual-income millennial parents drive Bluetooth-enabled pump adoption through subscription replenishment models. FDA 21 CFR 177.2600 compliance certificates constrain silicone supplier elasticity for domestic brands. Greater Boston and San Francisco Bay Area clusters concentrate direct-to-consumer startup activity targeting tech-forward buyers.
Germany
Baden-Württemberg and Bavaria parents accelerate stainless steel bottle substitution motivated by sustainability concerns. EU REACH chemical restrictions and EU Green Deal circularity mandates accelerate silicone and glass material transitions. Frankfurt-Rhine-Main logistics hubs service cross-border e-commerce fulfillment for premium sterilizer imports.
China
Urban middle-class families in Shanghai, Beijing, and Shenzhen upgrade to imported smart pumps and sterilizers through Tmall Global. SAMR product safety filings mandate batch-traceable silicone sourcing with 90-day delays for non-compliant foreign entrants. Yangtze River Delta manufacturing clusters dominate domestic production of food-grade polymer formulations.
India
Rural hinterland markets present first-mover potential for affordable electric sterilizers as urban penetration saturates. FSSAI food-contact notifications add compliance layers for imported polymer formulations versus domestic competitors. Maharashtra and Gujarat industrial corridors concentrate injection-molding capacity for BPA-free plastic bottle production.
Japan
Aging grandparent caregivers favor intuitive one-handed operation designs minimizing fine motor dexterity requirements. METI product safety standards and JIS certification requirements maintain stringent material biocompatibility thresholds. Tokyo-Osaka corridor department stores retain premium positioning through exclusive colorway distribution for pediatrician-endorsed brands.
Baby Feeding Accessories Market Vendor Landscape
Global majors compete with regional champions across material certification and channel access dimensions. The vendor base separates into three tiers: integrated silicone processors with captive supply chains, licensed precision molders leveraging medical device IP, and commodity assemblers competing on cost. Three strategic archetypes dominate: research-driven lactation specialists, pediatrician-endorsed design houses, and platform-optimized direct-to-consumer brands. Capacity expansion and strategic technology licensing represent the dominant competitive moves as mid-tier players seek premium tier access.
Among Swiss and American research-driven specialists, Medela anchors the premium lactation equipment tier through in-house clinical research capabilities. Japanese pediatrician-endorsed design houses exemplified by Pigeon Corporation occupy differentiated positions across Asian pharmacy and department store channels. British valve engineering specialists represented by Tommee Tippee capture specialty retail shelf space through anti-colic technology differentiation. These three archetypes illustrate how competitive positioning separates across research depth, clinical endorsement, and precision manufacturing rather than scale alone.
| Leading Market Players |
|---|
| Medela |
| NUK |
| Philips Avent |
| Munchkin |
| Chicco |
| Dr. Brown's |
| Pigeon Corporation |
| Comotomo |
| Tommee Tippee |
| Others |
Supply Flow & Price Mechanics
EU Green Deal circularity mandates gate both qualified silicone supply and premium-tier pricing access, as manufacturers must demonstrate batch-traceable polymer chain-of-custody to command anti-colic valve and smart pump price premiums. Compliance documentation requirements from China's SAMR and FDA 21 CFR 177.2600 certifications create dual certification overhead that stratifies pricing power between integrated incumbents and assembler-dependent entrants.
Pricing Analysis
Warranty and replacement program bundling separates premium lactation equipment from unbundled transactional bottle sales. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification grade and geographic delivery cost differentials. Cost compression in plastic bottles is intensifying because BPA-free reformulation mandates force rapid material transitions. First-time parents in emerging markets exhibit highest price sensitivity, while dual-income households in China's tier-1 cities show least sensitivity for smart-connected features.
Supply Chain Analysis
Returns and take-back flows for stainless steel bottles are emerging as EU Green Deal compliance credit generators, creating reverse logistics infrastructure demands. Medical-grade silicone feedstock concentrates in China, South Korea, and Japan, with three Asian petrochemical conglomerates controlling food-certified polymer supply. Raw material dependencies rest on platinum-cured silicone formulations, borosilicate glass tubing, and electropolished 316L stainless steel. Single-source vulnerability in silicone feedstock creates structural supply risk. Distribution runs through cross-border e-commerce platforms and mother-and-baby specialty chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive silicone processing capabilities determine margin capture and regulatory compliance speed. Players are pursuing backward integration into polymer feedstock to escape petrochemical conglomerate pricing power and SAMR filing delays.
For Market Incumbents: Deploy batch-traceable silicone sourcing documentation to defend against foreign entrants facing 90-day SAMR filing delays. Add precision molding capacity in Yangtze River Delta clusters to capture smart pump assembly demand. Counter direct-to-consumer startup threats by locking hospital discharge specifications through NICU-grade valve performance licensing. For New Entrants and Emerging Players: Begin with affordable electric sterilizer distribution in rural India, where urban penetration has saturated and first-mover positioning remains available. Target grandparent caregiver segments in Japan with one-handed operation designs. Pursue pharmacy channel partnerships to access insurance-adjacent credibility for medically positioned feeding solutions. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for novel sterilization technologies is the leading indicator that premium tier access is opening for mid-cap specialists. Five-to-ten year viability favors integrated silicone processors with captive supply chains over licensed precision molders. Monitor EU REACH chemical restriction expansion timelines as inflection signals for material substitution investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Feedstock | Captive supply chains escape three-conglomerate pricing power and SAMR documentation delays. |
| Smart Connectivity Platform Launch | Bluetooth-enabled pumps with app tracking capture millennial parent segments in Greater Boston and Shenzhen. |
| Hospital System Partnership | NICU discharge specifications collapse clinical-consumer performance gaps for home-use bottles. |
| Cross-Border E-Commerce Expansion | Tmall Global and JD Worldwide algorithms displace mother-and-baby store discovery for urban Chinese parents. |
| Sustainability Repositioning | Stainless steel take-back programs generate EU Green Deal compliance credits in Baden-Württemberg markets. |
Methodological Framework
Trade databases, regulatory filing repositories, and hospital procurement records formed the secondary backbone, supplemented by primary interviews with lactation consultants, silicone polymer procurement leads, mother-and-baby retail category managers, and SAMR compliance officers. Bottom-up and top-down triangulation validated volume estimates across material grades and distribution channels.
Bottom-up modeling aggregated product-level shipment data by silicone, stainless steel, glass, and plastic material categories, while top-down analysis calibrated aggregate market expansion against dual-income household growth trajectories across the analysis window. Segmentation dimensions included product type, material certification tier, distribution channel, and end-user procurement authority. CAGR derivation incorporated replacement cycle frequencies for consumable components and smart device upgrade patterns.
Underlying measurement precision varies by segment; online retail channel data carries tighter precision than rural India hinterland estimates. Forecasts incorporate assumptions regarding BPA-free mandate enforcement timelines and EU Green Deal implementation pacing. Practitioners should monitor FDA 510(k) backlog clearance rates and SAMR batch-traceability rule expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Breast Milk Storage Products Market
Baby Products
Baby Shoes Market
Baby Products
Global Baby Product Market
Baby Products
US Baby Care Products Market
Baby Products
Baby Digital Monitor Market
Baby Products
Baby Swing Market
Baby Products
Baby Personal Care Products Market
Baby Products
Australia Baby Care Products Market
Baby Products
Feeding Bra Market
Baby Products
Baby Portable Co-Sleeper Market
Baby Products
North America Baby Bottle Market
Baby Products
Cloth Diapers Market
Baby Products
Sippy Cups Market
Baby Products
Canada Baby Care Products Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Portable Cribs Market