
 China Pet Clothing Market | 2026-2036
China Pet Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
China Pet Clothing Market Insights
Market Context with Strategic Players
China's updated GB 18401 national textile safety standard is rebalancing material sourcing priorities across the pet clothing supply chain. Yangzhou Pet Clothing Manufacturer leverages its integrated dyeing and cutting facilities to sustain cost leadership in cotton-based jackets. Shenzhen Petop Pet Products Co., Ltd. anchors its position through direct-to-consumer channels on domestic e-commerce platforms. Dongguan Pet Wear Ltd. differentiates via specialized costume production for seasonal festivals.
Technical Definition and Structural Segments
Pet clothing encompasses engineered garments designed for thermoregulation, hygiene management, and aesthetic modification of domestic animals, typically constructed from woven or knitted textiles with adjustable closures sized to breed-specific anthropometrics. Cotton and polyester segments dominate current volume, though fleece variants command premium positioning in northern provinces with extended heating seasons. Jackets and sweaters represent the mature core, while costumes capture accelerated growth from holiday-themed purchasing by pet boutiques and online shoppers.
Regulatory Frame and Forward-Looking Close
SAMR enforces labeling compliance under GB standards, while MEE oversight of textile wastewater discharge shapes manufacturing location decisions for producers serving export and domestic channels simultaneously. MIIT's industrial cluster policies incentivize automation upgrades that reduce unit labor costs in garment assembly. Stakeholders must monitor how evolving dual carbon goals redirect energy-intensive dyeing operations toward western provinces with renewable power capacity.
Market Dynamics
MIIT's industrial cluster policies are compressing production timelines across China's pet apparel sector by accelerating automation adoption in Yangtze River Delta dyeing and assembly facilities.
Growth Catalysts
- Dual carbon goals:Beijing's renewable energy mandates are redirecting energy-intensive textile operations toward western provinces with hydroelectric capacity, lowering carbon-adjusted production costs for export-oriented manufacturers.
- Antimicrobial bamboo fiber:Suzhou-based textile mills are scaling enzymatic processing of bamboo viscose to meet GB 18401 safety standards, creating premium positioning for hygiene-conscious urban pet owners.
- Festival costume demand:Shanghai and Beijing boutiques are expanding seasonal inventory cycles around Lunar New Year and Singles' Day, pulling specialized garment volumes through domestic e-commerce channels.
Market Restraints
- Cotton input volatility:Xinjiang cotton sourcing restrictions are forcing Hangzhou manufacturers toward higher-cost imported fiber, compressing margin structures on mid-tier jacket lines.
- MEE wastewater compliance:Textile discharge regulations are eliminating small-batch dyeing operations in Jiangsu province, concentrating finishing capacity among capital-intensive integrated producers.
- Functional substitutes:Heated pet beds and climate-controlled carriers are displacing thermoregulatory outerwear purchases among apartment-dwelling owners in southern provinces.
Strategic Opportunities
- Underpenetrated inland cities:Chengdu and Xi'an pet retail footprints remain 60% below coastal penetration rates, creating first-mover positioning for direct-to-consumer brands with localized sizing databases.
- Smart textile convergence:Integration of flexible sensors with moisture-wicking knits is enabling health-monitoring garments for aging companion animals, opening veterinary channel partnerships.
- SAMR traceability mandates:Upcoming blockchain-labeling requirements for textile origin documentation favor early adopters with integrated supply chain visibility systems.
Industry Challenges
- Pattern-making automation:Shortage of technicians fluent in both breed-specific anthropometric databases and CAD nesting software is constraining made-to-measure service scaling.
- GB standard recertification:Biennial textile safety testing timelines are creating inventory hold periods that disrupt just-in-time fulfillment commitments to Tmall flagship stores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pet Clothing Market |
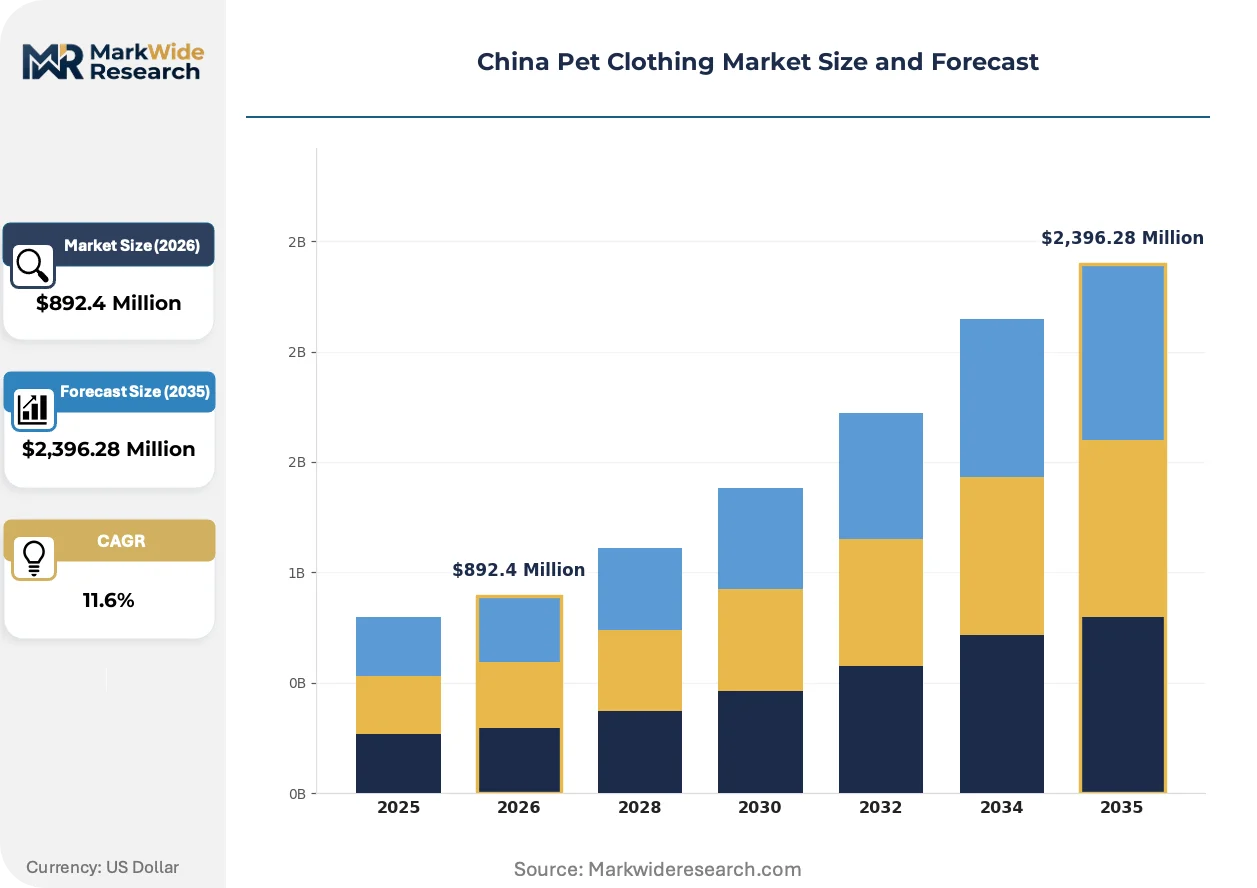
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $2,396.28 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Sweaters, Dresses, Costumes Material: Cotton, Polyester, Nylon, Fleece Customer Type: Pet Owners, Retailers, Online Shoppers, Pet Boutiques Size: Small, Medium, Large, Extra Large |
| Companies Covered | Yangzhou Pet Clothing Manufacturer, Dongguan Pet Wear Ltd., Shenzhen Petop Pet Products Co., Ltd., Zhejiang Pet Outfitters, Shandong Pet Textile Co., Qingdao Pet Products Co., Ltd., Ningbo Pet Fashion Co., Ltd., Jiangsu Pet Garment Group, Guangzhou Pet Apparel Factory, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pet Clothing Market Trends and Innovations
Digital manufacturing workflows are collapsing traditional seasonal production cycles across China's pet apparel sector, compressing design-to-shelf timelines while fragmenting order batch sizes.
On-demand knitting technology is decentralizing production geography across the Yangtze River Delta. Shanghai-based studios are deploying single-garment 3D knitting cells that eliminate cutting waste and enable same-day fulfillment. Boutique pet retailers in Beijing are adopting this capability to offer customized fit adjustments without maintaining finished goods inventory, compressing working capital requirements for seasonal collections.
GB 18401-2022 textile safety amendments are tightening formaldehyde and pH limits on infant-grade adjacent products. SAMR enforcement is extending these standards to pet garments marketed with human-contact claims, forcing Hangzhou manufacturers toward certified organic cotton sourcing. Costume segments with synthetic embellishments face elevated testing costs that favor larger producers with in-house laboratory capacity.
Subscription-based wardrobe refresh models are displacing transactional e-commerce in tier-one cities. Tmall and JD.com flagship stores now offer quarterly garment rotation services with prepaid styling consultations, locking in recurring revenue from millennial pet owners. This pattern concentrates highest adoption in Shanghai and Shenzhen, where apartment storage constraints favor minimal pet accessory footprints.
China Pet Clothing Market Segmentation
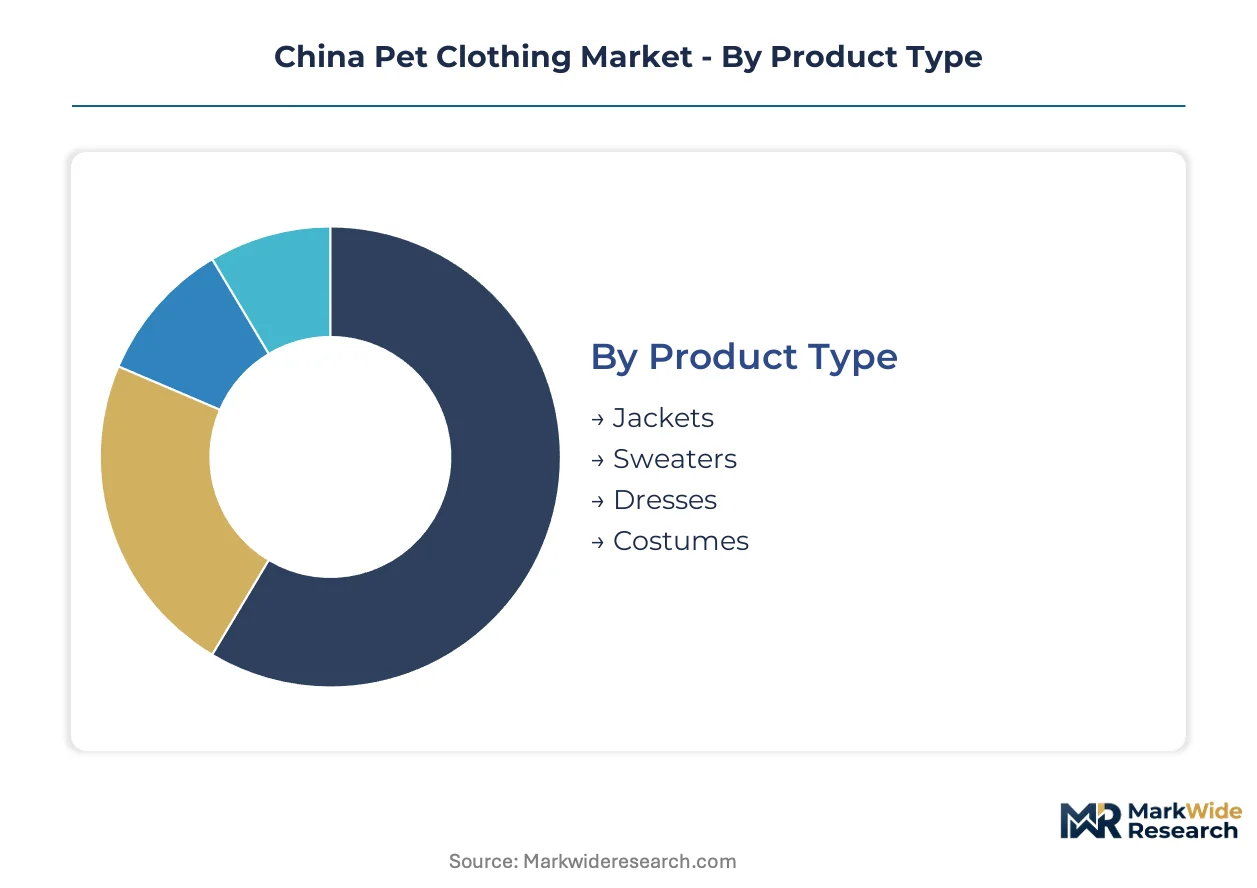
Segmentation in China's pet clothing market reveals how manufacturing capabilities, material sourcing constraints, and distribution channel evolution create distinct competitive arenas. Producers serving Shanghai and Beijing boutiques face fundamentally different margin structures than those supplying Tmall flagship stores or export channels.
Product Type:
Yangzhou's integrated dyeing facilities concentrate jacket and sweater output, while Suzhou studios specialize in small-batch costume production for seasonal festivals.
- Jackets:Engineered outerwear with adjustable closures and water-resistant coatings dominates thermoregulatory applications. Northern provinces with extended heating seasons drive replacement cycles, though heated pet beds in southern apartments constrain growth in Guangdong and Fujian.
- Sweaters:Knitted garments constructed from cotton-polyester blends serve as transitional weather solutions. Beijing and Tianjin pet boutiques maintain higher inventory depth here than Shanghai retailers, reflecting climate-driven demand patterns.
- Dresses:Aesthetic-focused garments with decorative embellishments target urban millennial owners. Hangzhou manufacturers leverage proximity to Alibaba's headquarters for rapid e-commerce fulfillment.
- Costumes:Festival-themed designs for Lunar New Year and Singles' Day generate concentrated revenue spikes. Dongguan producers capture this demand through direct-to-consumer channels with compressed design-to-shelf timelines.
Jackets absorb the bulk of installed capacity; costumes are expanding most quickly.
Material:
Cost tiers separate commodity synthetics from certified organic inputs, with GB 18401 compliance creating a middle tier of tested conventional cotton.
- Cotton:Natural fiber garments face Xinjiang sourcing restrictions that force Hangzhou manufacturers toward imported fiber, elevating input costs on mid-tier lines. SAMR traceability mandates favor producers with blockchain-enabled origin documentation.
- Polyester:Synthetic staple dominates volume production through Yangzhou's integrated spinning and weaving facilities. MEE wastewater regulations are eliminating small-batch dyeing operations, concentrating finishing among capital-intensive producers.
- Nylon:High-tenacity fiber serves functional outerwear requiring abrasion resistance. Military-surplus nylon from Sichuan suppliers occasionally enters the pet apparel supply chain through secondary markets.
- Fleece:Synthetic pile fabrics command premium positioning in northern provinces. Suzhou-based mills are scaling recycled-content fleece to align with dual carbon goals and municipal procurement preferences.
Polyester commands the largest production footprint; fleece gains share fastest among premium-positioned lines.
Customer Type:
Channel structure fragments between inventory-heavy retail and asset-light digital models, with subscription services emerging in tier-one cities.
- Pet Owners:End consumers purchasing through Tmall and JD.com flagship stores increasingly favor quarterly wardrobe refresh subscriptions over transactional buying. Shanghai apartment storage constraints accelerate this shift.
- Retailers:Brick-and-mortar pet stores in Chengdu and Xi'an maintain 60% lower penetration than coastal counterparts, creating first-mover opportunities for brands with localized sizing databases.
- Online Shoppers:Digital-native purchasers drive demand for same-day fulfillment enabled by on-demand 3D knitting cells in Shanghai studios.
- Pet Boutiques:Curated retail channels in Beijing and Shenzhen stock higher-margin seasonal collections with specialized sizing for brachycephalic breeds.
Online shoppers generate the highest transaction velocity; pet boutiques capture the steepest margin expansion.
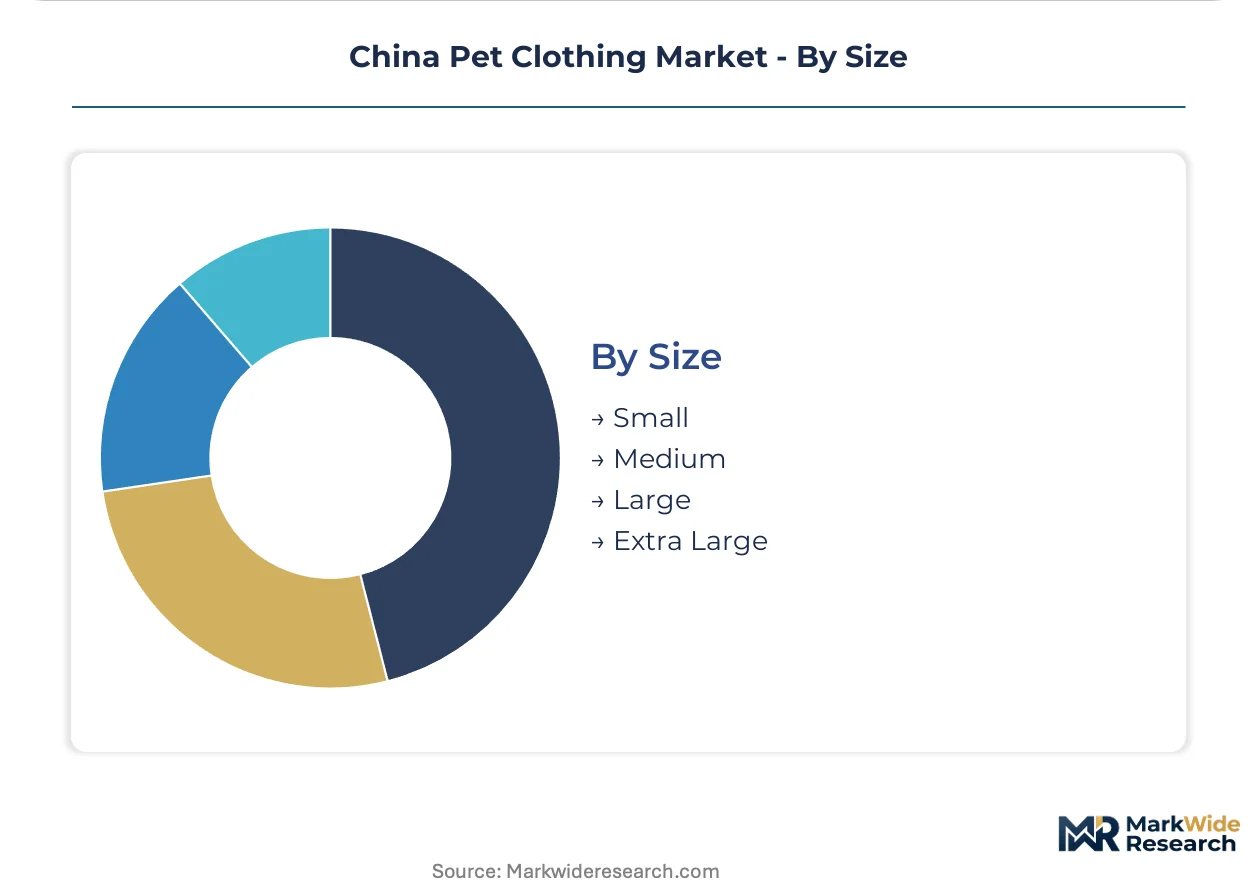
Size:
Breed-specific anthropometric databases constrain pattern-making automation, with small-size production dominating current output.
- Small:Garments for toy breeds and cats represent the mature volume core. Technician shortages fluent in both CAD nesting software and breed-specific measurements limit made-to-measure scaling.
- Medium:Mid-size offerings for popular companion breeds like Shiba Inu and Corgi align with urban ownership patterns in tier-one cities.
- Large:Big-breed clothing faces thinner demand concentration, with veterinary channel partnerships emerging for health-monitoring smart textile integration.
- Extra Large:Oversized garments for giant breeds remain underpenetrated, with limited domestic production capability outside specialized export-oriented facilities.
Small sizes anchor current manufacturing investment; large sizes show the most rapid adoption of sensor-integrated smart textiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangzhou anchors China's pet clothing production through integrated dyeing and cutting corridors serving both domestic boutiques and export channels.
Yangtze River Delta
Shanghai and Hangzhou pet boutiques drive premium outerwear demand through seasonal wardrobe refresh subscriptions. SAMR enforces GB 18401 textile safety standards across all finished goods entering domestic retail. Suzhou-based mills specialize in small-batch costume production for Lunar New Year and Singles' Day e-commerce spikes.
Pearl River Delta
Shenzhen's direct-to-consumer brands leverage proximity to JD.com and Tmall logistics hubs for same-day fulfillment commitments. MIIT industrial cluster policies accelerate automation adoption in Dongguan assembly facilities. Guangzhou pet apparel factories concentrate on export-oriented costume lines with compressed design-to-shelf timelines.
Beijing-Tianjin-Hebei
Beijing pet boutiques maintain deeper sweater inventory than Shanghai retailers, reflecting climate-driven replacement cycles in northern heating seasons. MEE wastewater discharge regulations eliminate small-batch dyeing operations in surrounding Hebei province. Tianjin port infrastructure supports imported cotton fiber intake for manufacturers pivoting away from Xinjiang sourcing.
Shandong Peninsula
Qingdao pet products manufacturers serve Japanese and South Korean export markets through established maritime freight corridors. Dual carbon goals redirect energy-intensive finishing operations toward western provinces with renewable hydroelectric capacity. Shandong Pet Textile Co. exemplifies the region's vertically integrated spinning-to-garment production model.
Sichuan-Chongqing
Chengdu pet retail penetration remains 60% below coastal tier-one cities, creating first-mover positioning for brands with localized sizing databases. Chongqing's inland port infrastructure reduces logistics costs for western province distribution. Sichuan-based suppliers occasionally channel military-surplus nylon into secondary pet apparel markets through informal procurement networks.
China Pet Clothing Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive dyeing capacity and direct-to-consumer digital brands. Yangzhou Pet Clothing Manufacturer and Dongguan Pet Wear Ltd. anchor the production-heavy tier through in-house finishing operations. Boutique-facing specialists and export-oriented fabricators comprise the remaining competitive clusters. Capacity consolidation and e-commerce channel expansion represent the dominant competitive moves reshaping participant positioning.
Among Yangtze River Delta integrated producers, Yangzhou Pet Clothing Manufacturer exemplifies cost leadership through captive supply of dyed cotton inputs. Dongguan Pet Wear Ltd. occupies a position within the costume-specialist archetype, leveraging compressed production timelines for festival-driven demand spikes. Shenzhen Petop Pet Products Co., Ltd. represents the direct-to-consumer digital-native tier, anchoring its market presence through domestic e-commerce platform relationships rather than inventory-heavy retail partnerships.
| Leading Market Players |
|---|
| Yangzhou Pet Clothing Manufacturer |
| Dongguan Pet Wear Ltd. |
| Shenzhen Petop Pet Products Co., Ltd. |
| Zhejiang Pet Outfitters |
| Shandong Pet Textile Co. |
| Qingdao Pet Products Co., Ltd. |
| Ningbo Pet Fashion Co., Ltd. |
| Jiangsu Pet Garment Group |
| Guangzhou Pet Apparel Factory |
| Others |
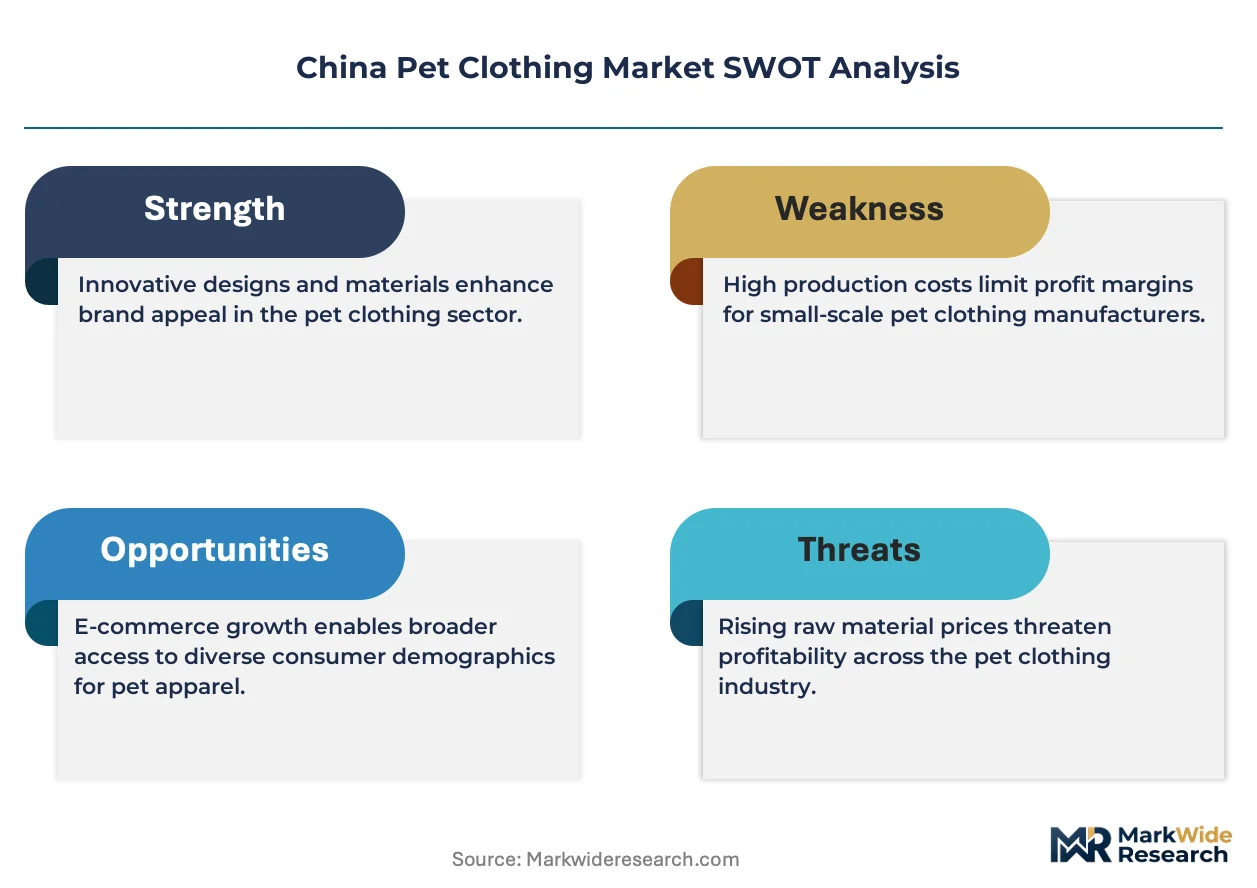
Pricing and Supply Chain Analysis
Captive dyeing capacity in Yangzhou's integrated mills anchors both supply security and margin control for cotton-based jacket producers serving domestic boutiques. This backward integration into finishing operations insulates manufacturers from MEE wastewater compliance shocks while compressing unit costs below modular competitors.
Pricing Analysis
Certification-grade pricing separates GB 18401-compliant organic cotton garments from untested conventional lines. Three-tier pricing structure across premium, standard, and economy levels reflects material sourcing tier and laboratory testing depth. Cost compression in mid-tier polyester jackets is intensifying because Hangzhou manufacturers absorb elevated imported fiber costs from Xinjiang sourcing restrictions. Price-sensitive volume buyers on Tmall flagship stores drive transactional discounting, while Beijing pet boutiques accept premium positioning for brachycephalic-specific sizing.
Supply Chain Analysis
Single-source vulnerability sits with Xinjiang cotton fiber, forcing Hangzhou and Suzhou mills toward higher-cost imported alternatives. Raw material procurement draws from domestic bamboo viscose, recycled-content fleece, and military-surplus nylon through Sichuan secondary channels. Tariff exposure on US-bound costume exports concentrates risk among Dongguan producers with compressed design-to-shelf timelines. Distribution runs through JD.com and Tmall logistics hubs for same-day fulfillment commitments in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finishing capacity scarcity from MEE wastewater elimination in Jiangsu province props pricing power for integrated producers with captive dyeing operations. Supply constraints favor incumbents with certified laboratory capacity and blockchain-enabled origin documentation.
For Market Incumbents: Hedge against cotton input volatility through long-term supply agreements with Vietnamese and Australian fiber suppliers. Defend margin structures by accelerating automation adoption in Yangzhou assembly corridors before MIIT incentive windows close. Counter heated pet bed substitution threats by integrating flexible sensor technology into large-breed health-monitoring garments. For New Entrants and Emerging Players: Enter via Chengdu and Xi'an retail corridors where pet apparel penetration trails coastal benchmarks by sixty percent. White-space positioning favors direct-to-consumer brands with localized sizing databases for inland city climate patterns. Capture first-mover advantage through subscription-based wardrobe refresh models before Tmall flagship saturation spreads inland. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated textile conglomerates seeking pet vertical diversification. Long-term viability hinges on dual carbon alignment and SAMR traceability compliance infrastructure. Monitor blockchain-labeling mandate implementation timelines as inflection signal for supply chain visibility premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dyeing Operations | Captive finishing capacity insulates margins from MEE compliance shocks in Jiangsu province. |
| Smart Textile Sensor Integration | Veterinary channel partnerships unlock health-monitoring revenue from aging companion animal demographics. |
| Direct-to-Consumer Platform Launch | JD.com and Tmall flagship relationships bypass inventory-heavy retail partnerships in tier-one cities. |
| Blockchain Origin Documentation | SAMR traceability mandates favor early adopters with integrated supply chain visibility systems. |
| Inland City Distribution Expansion | Chengdu and Xi'an retail footprints offer sixty-percent penetration gaps against coastal benchmarks. |
Research Methodology
Document review covered SAMR regulatory filings, MIIT industrial policy circulars, and GB standards documentation, complemented by interviews with Yangzhou dyeing facility managers, Hangzhou textile procurement leads, Shanghai pet boutique category buyers, and Tmall platform merchant operations specialists. Secondary validation drew from customs export records, Yangtze River Delta environmental compliance disclosures, and domestic e-commerce transaction databases. Bottom-up volume estimates triangulated against top-down sector expenditure models.
Historical production capacity trajectories cross-referenced against panel input from manufacturing executives and retail channel planners. Segmentation modeling spanned product type, material grade, customer channel, and size tier across the projection horizon. CAGR derivation incorporated input cost elasticity assumptions, regulatory compliance cost pass-through rates, and substitution effect coefficients from heated pet bed displacement patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under dual carbon goal acceleration or Xinjiang sourcing restriction expansion scenarios. Forecasts reflect documented assumptions on automation adoption curves and e-commerce penetration ceilings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Fitness Care Market
Pet Care Products
Pet Car Seat Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Pet Beds Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Hair Dryer for Pets Market
Pet Care Products
Dog Treats Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Small Breed Dog Food Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Pet Perfume Market
Pet Care Products
Dog Collars Market