
 Equestrian Footwear Market | 2026-2036
Equestrian Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Equestrian Footwear Market Insights
Professional rider demand is expanding faster than amateur segments as FEI-sanctioned event calendars densify across North America and Western Europe. Ariat International leverages its heritage western boot expertise to dominate English riding crossover categories. DeNiro Boot Company sustains artisanal Italian manufacturing to anchor premium dressage and show-jumping channels. Mountain Horse competes through cold-climate technical specialization, occupying a defensible position in Nordic and Canadian markets.
Equestrian footwear comprises purpose-built boots engineered with reinforced toe caps, steel or composite shanks, and oil-tanned full-grain leather uppers designed to prevent foot entrapment in stirrups while transmitting rider cues to the horse. Primary construction employs Goodyear welt or Blake stitching for resoling longevity under repetitive flexion and moisture exposure. Riding boots command the largest value pool due to mandatory protective standards across competitive disciplines, while synthetic materials represent the fastest-growing material category as vegan leather alternatives gain traction among younger recreational users. Direct sales channels capture disproportionate margin as bespoke fitting services justify price premiums unavailable through mass retail.
ASTM F2413 safety standards in the United States and REACH chemical restrictions in Europe govern chromium-free tanning processes and sole slip-resistance coefficients, effectively filtering low-cost imports from unverified supply bases. The EU Green Deal's leather traceability requirements are forcing tannery documentation upgrades that smaller competitors struggle to fund. Stakeholders must monitor evolving FEI equipment rules and carbon-footprint disclosure mandates that will determine which manufacturers retain access to sponsored athlete visibility.
Market Dynamics
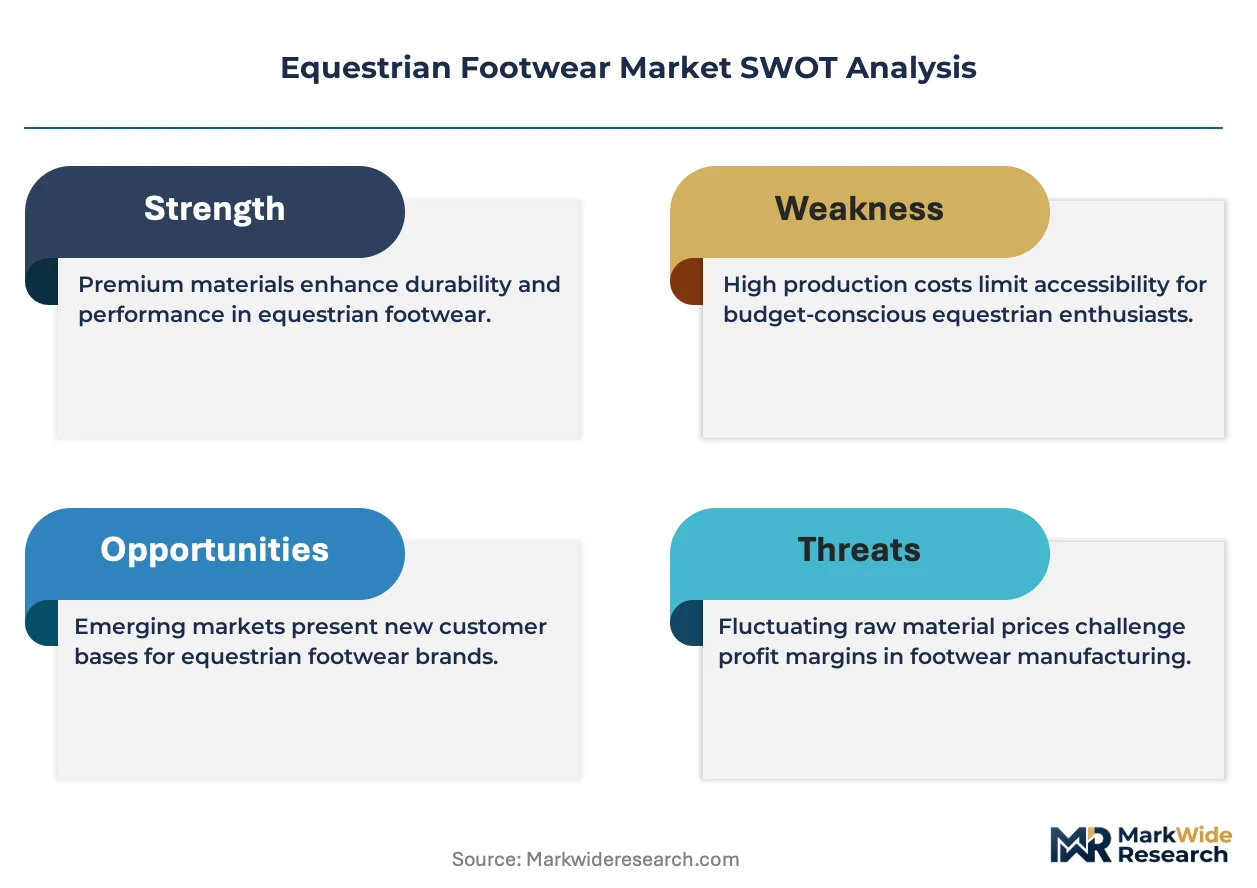
FEI equipment rule evolution and REACH chemical restrictions are compressing supplier margins while forcing tannery documentation upgrades that smaller Italian and Portuguese manufacturers cannot fund, consolidating production among vertically integrated heritage brands.
Growth Catalysts
- ASTM F2413 safety mandates:US competitive circuits now require certified protective toe caps and slip-resistant soles, eliminating uncertified imports from unverified Asian supply bases and redirecting procurement toward documented manufacturers.
- Cold-climate technical specialization:Nordic and Canadian recreational riders demand insulated waterproof membranes and thermal-rated outsoles, creating defensible premium segments for technical specialists with R&D infrastructure.
- Vegan leather material science:Microfiber and bio-based polyurethane alternatives are capturing younger recreational users who prioritize animal welfare, expanding addressable market beyond traditional leather-dependent demographics.
Market Restraints
- Full-grain leather input volatility:Oil-tanned hides from certified European tanneries face price pressure from EU Green Deal traceability requirements and reduced South American supply.
- Artisanal production concentration:Hand-finished Blake stitching and bespoke lasting capabilities concentrate in Tuscany and Le Marche, creating geographic supply risk without near-term replication pathways.
- Synthetic performance gap:Composite shanks and vegan uppers still fail to match leather's moisture-wicking and stirrup-feedback properties in FEI-sanctioned endurance disciplines.
Strategic Opportunities
- Direct-to-rider fitting services:3D foot scanning and mobile bespoke units bypass retail margin capture while justifying price premiums unavailable through mass equestrian retailers.
- Carbon-footprint disclosure mandates:Early compliance with emerging EU Green Deal leather traceability requirements positions heritage manufacturers for sponsored athlete visibility and Olympic procurement.
- English-Western crossover design:Hybrid silhouettes blending dressage boot elegance with western heel stability address growing amateur segments in US hunter-jumper barns.
Industry Challenges
- Master last-maker scarcity:Hand-carved wooden lasts for bespoke fitting require decades of apprenticeship; retiring Italian artisans lack sufficient replacement pipelines.
- Dual certification complexity:Simultaneous REACH chromium-free tanning and ASTM F2413 safety testing extends product development timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equestrian Footwear Market |
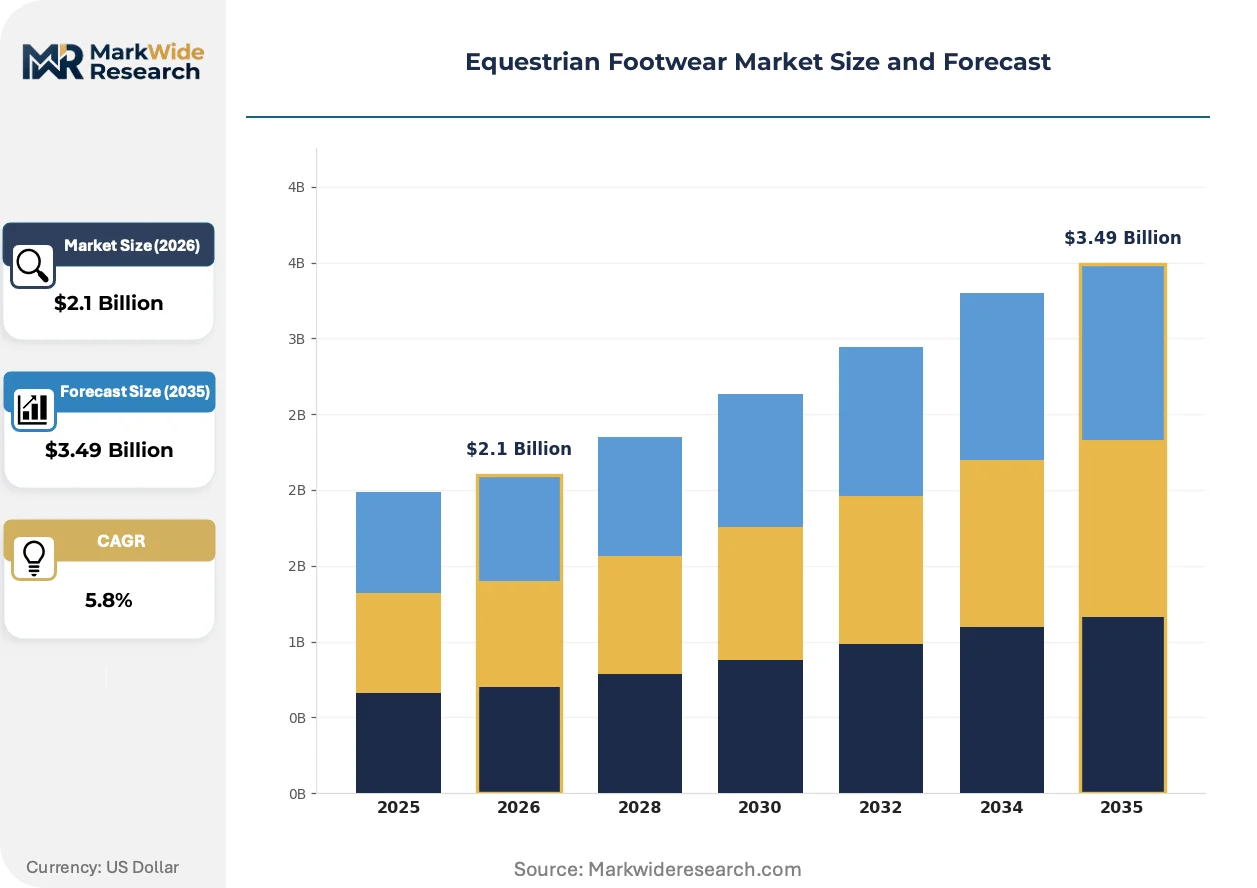
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Riding Boots, Jodhpur Boots, Paddock Boots, Galloping Boots Material: Leather, Synthetic, Rubber, Neoprene End User: Professional Riders, Amateurs, Trainers, Recreational Users Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Ariat International, DeNiro Boot Company, Tredstep Ireland, Mountain Horse, Equetech, Parlanti Roma, Justin Boots, TCX, Gaerne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equestrian Footwear Market Trends and Innovations
Material substitution and regulatory disclosure requirements are fragmenting competitive advantage away from scale manufacturing toward traceable supply chain control and artisanal technical credibility.
Composite shank technology is decentralizing protective footwear production by enabling thinner, lighter midsole structures that transmit rider cues without traditional steel reinforcement. Amateur and recreational segments in Germany and the United Kingdom are adopting these alternatives fastest, compressing demand for heavy legacy constructions while opening supplier qualification to non-leather specialists.
EU Green Deal leather traceability mandates now require documented chain-of-custody from slaughterhouse to finished goods, forcing tannery partnerships with verified European hide sources. Italian and Spanish manufacturers with captive tannery operations capture compliance advantage, while import-dependent competitors face exclusion from sponsored athlete procurement channels.
After-sales resoling and refurbishment services are unbundling from original purchase, with elite training facilities in Wellington, Florida and Surrey, England contracting directly with cobblers for fleet maintenance. This bypasses traditional retail service relationships, concentrating lifetime value capture among manufacturers with established refurbishment infrastructure rather than point-of-sale competitors.
Equestrian Footwear Market Segmentation
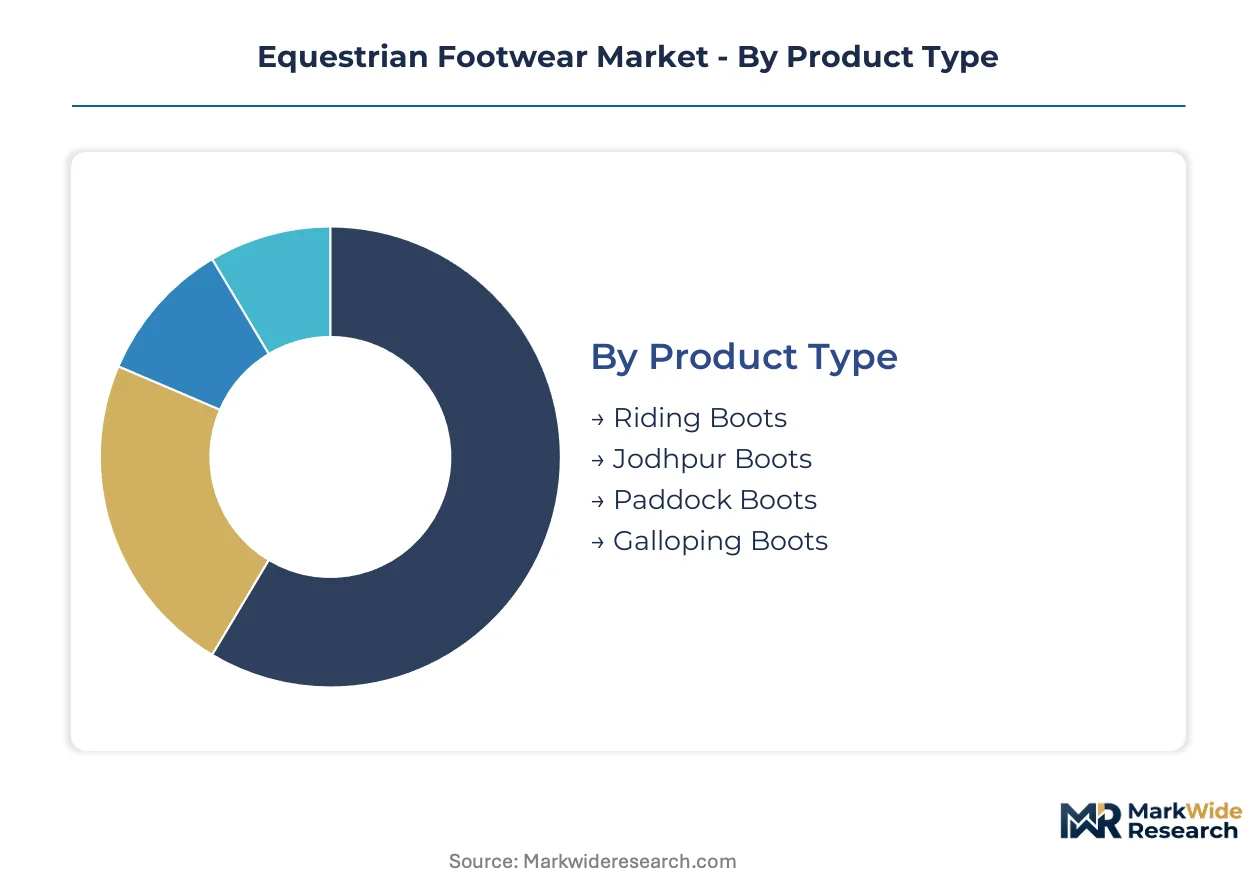
Equestrian footwear segmentation reflects divergent performance requirements across competitive disciplines and climate conditions. Material science advances and regulatory certification tiers fragment purchasing criteria, creating distinct margin pools that manufacturers must target precisely.
Product Type:
Discipline-specific biomechanical demands drive selection, with competitive circuits mandating certified protective constructions that recreational use does not require.
- Riding Boots:Full-height designs with reinforced toe caps, steel or composite shanks, and oil-tanned leather uppers engineered for stirrup entrapment prevention. FEI-sanctioned events in Germany, the United Kingdom, and the United States mandate ASTM F2413 or equivalent certification, anchoring premium procurement volumes.
- Paddock Boots:Ankle-height constructions with Blake-stitched soles for stableyard durability and quick ground mounting. English riding academies in Surrey, England and Wellington, Florida specify these for daily training rotation, generating consistent replacement cycles.
- Jodhpur Boots:Low-profile elastic-sided designs paired with gaiters for junior and amateur segments prioritizing convenience over maximum protection.
- Galloping Boots:Lightweight synthetic constructions for exercise riders and conditioning work where extended walking comfort outweighs competitive certification requirements.
Riding Boots lead on scale; Paddock Boots lead on momentum.
Material:
Input cost trajectories and traceability mandates are reweighting procurement decisions away from traditional leather dependence toward verified alternatives.
- Leather:Full-grain oil-tanned hides from certified European tanneries deliver unmatched moisture-wicking and stirrup feedback. EU Green Deal chain-of-custody requirements concentrate supply among Italian and Spanish manufacturers with captive tannery operations.
- Synthetic:Microfiber and bio-based polyurethane alternatives capture younger recreational users prioritizing animal welfare. German and United Kingdom amateur segments adopt these fastest, though FEI endurance disciplines still reject them for competitive use.
- Rubber:Waterproof compounds for cold-climate recreational use in Nordic regions and Canada, typically in insulated paddock boot constructions.
- Neoprene:Flexible synthetic rubber for galloping and exercise applications requiring quick drying and minimal maintenance.
Leather dominates revenue concentration; Synthetic climbs the fastest.
End User:
Performance tier and replacement frequency separate volume buyers from margin-accretive segments with bespoke service expectations.
- Professional Riders:FEI-registered competitors requiring certified protective footwear with documented supply chains for sponsored athlete visibility. Olympic-level infrastructure in Germany, the United Kingdom, and the United States anchors concentrated demand.
- Amateurs:Hunter-jumper barn participants in North America and Western Europe driving English-Western crossover adoption. This segment accepts composite shank alternatives and synthetic uppers, expanding addressable supply base.
- Trainers:High-volume users with fleet maintenance needs, increasingly contracting directly with refurbishment services rather than retail channels.
- Recreational Users:Weekend riders and trail enthusiasts prioritizing cold-climate technical features and vegan material options.
Professional Riders command premium pricing; Amateurs expand the addressable base.
Distribution Channel:
Margin capture and customer relationship depth vary sharply across channel structures, with direct engagement justifying price premiums unavailable through mass retail.
- Direct Sales:3D foot scanning and mobile bespoke fitting units serving elite training facilities. Wellington, Florida and Surrey, England facilities contract directly for fleet maintenance, capturing lifetime value beyond point-of-sale.
- Specialty Stores:Staffed fitting expertise and immediate inventory access for competitive riders requiring same-day replacement. German and United Kingdom equestrian retail clusters concentrate this channel's relevance.
- Online Retail:Convenience-driven purchasing for replacement of known sizes and styles, expanding fastest among amateur and recreational segments.
- Department Stores:Limited presence due to specialized fitting requirements; residual volume in mass-market synthetic entry products.
Direct Sales leads on margin; Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as REACH compliance costs in Europe push manufacturing toward jurisdictions with lower documentation burdens. Manufacturers with captive tannery operations in Italy and Spain retain competitive advantage against import-dependent competitors.
United States
ASTM F2413 certification mandates now govern FEI-sanctioned competitive circuits from Wellington, Florida to California's thermal desert show grounds. The EPA oversees chemical disclosure requirements for imported leather treatments. Elite training infrastructure in Wellington and the Hamptons anchors premium procurement volumes for Olympic-level athletes.
Germany
REACH chemical restrictions and chromium-free tanning requirements concentrate supply among manufacturers with verified European hide sourcing. The EU Green Deal's chain-of-custody mandates filter smaller Portuguese competitors from sponsored athlete channels. Munich and Hamburg host the densest clusters of specialty retail fitting services for competitive dressage and show-jumping disciplines.
United Kingdom
FEI event calendar densification across Surrey and Gloucestershire drives professional rider replacement cycles. ECHA enforcement of restricted substance lists governs imported footwear chemistry. The Cotswolds and Home Counties concentrate amateur hunter-jumper barns where English-Western crossover designs gain fastest traction.
Italy
Artisanal Blake-stitching capabilities in Tuscany and Le Marche create geographic supply moats for bespoke dressage boot production. REACH compliance documentation requirements favor vertically integrated manufacturers with captive tannery operations. Florence and Milan anchor heritage brand headquarters with direct access to master last-making apprenticeship pipelines.
Canada
Cold-climate recreational demand for insulated waterproof membranes concentrates in Alberta and British Columbia equestrian communities. Health Canada administers product safety standards parallel to ASTM protocols. The Calgary and Vancouver metropolitan areas host technical specialists competing through thermal-rated outsole specialization rather than competitive certification compliance.
Equestrian Footwear Market Competitive Landscape
Vertical integration into captive tannery operations dominates the current landscape as REACH documentation requirements escalate. The vendor base stratifies between heritage European manufacturers with in-house hide processing and import-dependent competitors facing exclusion from sponsored athlete procurement. Three archetypes define positioning: artisanal Italian specialists with master last-making capabilities, technical cold-climate innovators from Nordic regions, and western-heritage crossover players leveraging scale manufacturing. Consolidation pressures concentrate among smaller Portuguese and Asian suppliers unable to fund dual certification timelines. Geographic expansion through mobile bespoke fitting units and strategic partnerships with elite training facilities represent the dominant competitive vectors.
Among heritage European specialists, Ariat International, DeNiro Boot Company, and Mountain Horse occupy distinct positioning archetypes. The California-based entity exemplifies western-heritage scale manufacturing translated into English riding crossover categories. The Italian manufacturer anchors artisanal premium dressage and show-jumping channels through Tuscan production concentration. The Nordic competitor sits within technical cold-climate specialization, serving defensible premium segments in Canadian and Scandinavian recreational markets where thermal performance outweighs competitive certification requirements.
| Leading Market Players |
|---|
| Ariat International |
| DeNiro Boot Company |
| Tredstep Ireland |
| Mountain Horse |
| Equetech |
| Parlanti Roma |
| Justin Boots |
| TCX |
| Gaerne |
| Others |
Pricing and Supply Chain Analysis
Captive tannery operations in Italy and Spain anchor both supply security and pricing power for heritage manufacturers, insulating them from REACH documentation cost spikes that smaller Portuguese competitors cannot absorb. This backward integration into hide processing creates margin buffers against EU Green Deal traceability mandates while enabling premium positioning in sponsored athlete procurement channels.
Pricing Analysis
Direct-to-rider channels bypass traditional retail markups while justifying price premiums through bespoke fitting services unavailable through mass equestrian retailers. Pricing stratifies across FEI-certified premium constructions, standard competitive-grade products, and entry-level recreational tiers. Cost compression in synthetic material categories intensifies as microfiber alternatives gain traction among German and United Kingdom amateur segments. Professional riders demonstrate lowest price sensitivity due to mandatory certification requirements and sponsored equipment obligations.
Supply Chain Analysis
Direct-to-OEM channels handle fleet maintenance contracts from elite training facilities in Wellington, Florida and Surrey, England, bypassing traditional retail service relationships. Manufacturing concentrates in Italy, Spain, and Portugal, with full-grain oil-tanned hides sourced from certified European tanneries. Supply chain risk centers on master last-maker scarcity in Tuscany and Le Marche, where decades-long apprenticeship pipelines face generational attrition. Distribution runs through specialty retail clusters in Germany and the United Kingdom, direct sales units serving Olympic-level infrastructure, and online channels capturing amateur replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost differentials between REACH-compliant European tanneries and unverified Asian supply bases create geographic-arbitrage pressure, compressing margins for import-dependent competitors while rewarding captive production assets.
For Market Incumbents: Extend refurbishment infrastructure to capture lifetime value from trainer fleet maintenance contracts, insulating against synthetic material substitution in amateur segments. Deepen backward integration into verified European hide sourcing to preempt EU Green Deal exclusion risks. For New Entrants and Emerging Players: Capture cold-climate recreational white space in Alberta and British Columbia through thermal-rated outsole specialization, bypassing FEI certification barriers that concentrate competitive supply. Target vegan leather positioning among younger United Kingdom and German recreational users prioritizing animal welfare credentials. For Investors and Strategic Acquirers: Roll-up economics work for Italian artisanal specialists with captive tannery operations because REACH documentation requirements filter smaller competitors from sponsored athlete visibility. Monitor FEI equipment rule evolution as inflection indicator for compliance-advantaged manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tannery Acquisition | REACH documentation requirements favor vertically integrated Italian and Spanish manufacturers with verified European hide sourcing. |
| Mobile Bespoke Fitting Expansion | Direct-to-rider units serving Wellington and Surrey elite facilities capture margin unavailable through retail channels. |
| Synthetic Material R&D Partnership | Microfiber alternatives address German and United Kingdom amateur demand while reducing leather input volatility exposure. |
| Refurbishment Infrastructure Buildout | After-sales resoling contracts with trainer fleets concentrate lifetime value among established service providers. |
| Cold-Climate Technical Line Launch | Thermal-rated constructions target defensible premium segments in Nordic and Canadian recreational markets. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with FEI-registered professional riders, specialty retail fitting specialists, Italian tannery operations managers, and elite training facility procurement officers combined with secondary validation against customs trade records, REACH registration databases, FEI equipment rule filings, and ASTM certification registries. Triangulation across these sources ensures dimensional coverage of both demand-side replacement cycles and supply-side compliance positioning.
Historical trendline analysis of riding boot, paddock boot, and synthetic material category trajectories informed projection frameworks across the analysis window. Segmentation dimensions modeled include discipline-specific product type, material certification tier, end-user performance level, and distribution channel structure. CAGRs derive from fitted growth curves applied to verified baseline volumes, with FEI event calendar densification and regulatory compliance cost trajectories serving as key forecast inputs.
Underlying measurement precision varies by segment; professional rider demand carries tighter precision than recreational user estimates due to FEI registration data availability. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and material substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Second Hand Designer Shoes Market
Footwear
Sneakers Market
Footwear
Global Men Leather Shoes Market
Footwear
Slip Resistant Shoes Market
Footwear
Duck Boots Market
Footwear
Protective Footwear Market
Footwear
Riding Boots Market
Footwear
Leather Sneakers Market
Footwear
Western Boots Market
Footwear
Outdoor Trail Running Shoes Market
Footwear
Middle East and Africa Athletic Footwear Market
Footwear
Global Footwear Market
Footwear
Custom Shoes Market
Footwear
Refurbished Sneaker Market
Footwear
South America Athletic Footwear Market
Footwear
Waterproof Sneakers Market