
 Global Footwear Market | 2026-2036
Global Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Footwear Market Analysis
Modular sneaker systems with interchangeable soles and uppers is repositioning buyer choice toward customizable longevity rather than disposable replacement cycles. Nike leverages its Flyknit manufacturing scale to control premium knit-upper supply chains. Adidas sustains innovation velocity through its Futurecraft platform and localized speedfactory concepts. ASICS Corporation anchors technical credibility in marathon and trail-running communities where performance validation commands price premiums.
Footwear encompasses protective and fashion-oriented garments constructed for the human foot, typically incorporating outsoles of rubber or ethylene-vinyl acetate, midsoles of polyurethane or compressed ethylene foam, and uppers of leather, textile, or synthetic polymer matrices engineered for flex resistance, moisture management, and biomechanical support. Its primary commercial purpose spans functional protection, athletic performance enhancement, occupational safety compliance, and fashion expression across consumer and institutional procurement channels. Sneakers now generate the dominant volume pool as athleisure dissolves boundaries between gym, workplace, and social contexts. Leather materials retain margin concentration in formal and premium casual lines where European tannery traceability certifications command buyer premiums. Online retail channels are capturing the fastest volume growth trajectory as direct-to-consumer platforms bypass wholesale markups and compress inventory cycles.
The European Chemicals Agency enforces REACH substance restrictions on footwear adhesives and synthetic dyes, while China's Ministry of Ecology and Environment imposes dual carbon goals that constrain petroleum-based polyurethane production quotas. The US Consumer Product Safety Commission monitors children's footwear for phthalate content and small-part hazards, shaping import testing protocols for Asian manufacturers. Stakeholders must monitor how biomaterial certification schemes and extended producer responsibility frameworks in the EU and California reshape cost structures and supplier qualification requirements.
Market Dynamics
Athletic-casual hybridization is collapsing traditional category boundaries as performance specifications migrate into everyday wear contexts, forcing manufacturers to engineer single SKUs for multiple use cases simultaneously.
Growth Catalysts
- Bio-based polyurethane expansion:China's dual carbon goals under MEE are redirecting petrochemical capacity toward plant-derived feedstocks, creating compliant material pipelines for export-bound production.
- REACH substance restrictions:ECHA enforcement on footwear adhesives and synthetic dyes is accelerating solvent-free bonding technology adoption across European supply chains.
- Tier-one city retail penetration:Organized retail expansion in Mumbai, Delhi, and Bangalore is concentrating branded footwear demand through mall-based distribution networks.
Market Restraints
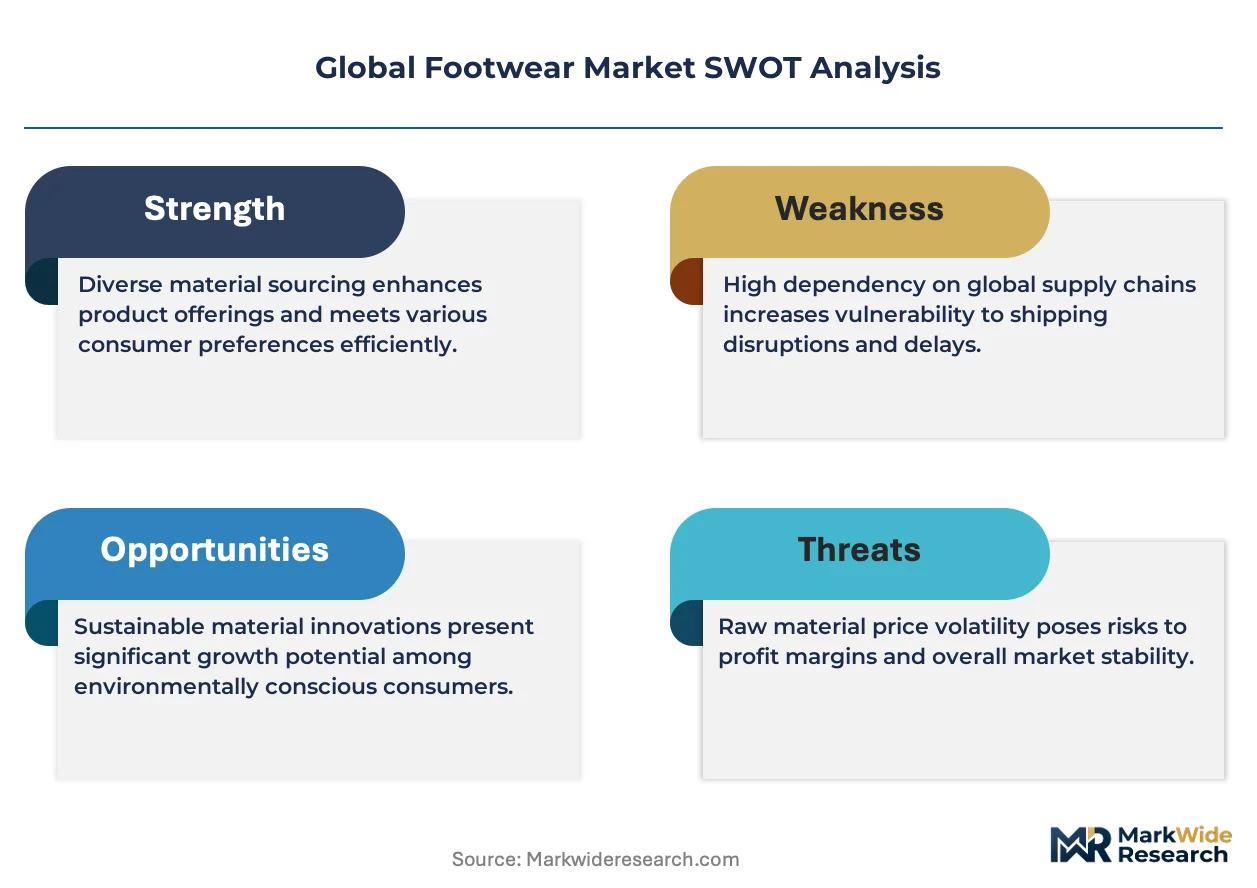
- Petroleum-based input volatility:Ethylene-vinyl acetate and synthetic rubber pricing remains tethered to crude oil futures, compressing margin predictability for mid-tier manufacturers.
- Tannery traceability certification scarcity:European leather sourcing now requires LWG (Leather Working Group) validation, limiting qualified supplier pools to audited Italian and Spanish tanneries.
- Biomechanical customization technical ceiling:Mass-customized foot-scan-to-production systems remain capital-intensive, constraining deployment beyond flagship retail footprints.
Strategic Opportunities
- Extended producer responsibility frameworks:EU and California EPR mandates for end-of-life footwear collection are creating closed-loop material recovery revenue streams.
- Direct-to-consumer platform expansion:Bypassing wholesale markups through proprietary e-commerce is compressing inventory cycles and capturing margin previously allocated to multi-brand retailers.
- Modular sneaker system architecture:Interchangeable sole-upper platforms enable longevity-based revenue models through component replacement rather than full-product substitution.
Industry Challenges
- Speedfactory reconfiguration complexity:Localized automated production requires workforce reskilling for robotics maintenance and digital workflow management.
- Biomaterial certification timeline compression:USDA BioPreferred and TUV Austria OK Compost validation cycles extend product launch schedules by 8-14 months.
- Multi-channel inventory synchronization:Real-time stock visibility across DTC platforms, wholesale accounts, and marketplace listings demands ERP system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Footwear Market |
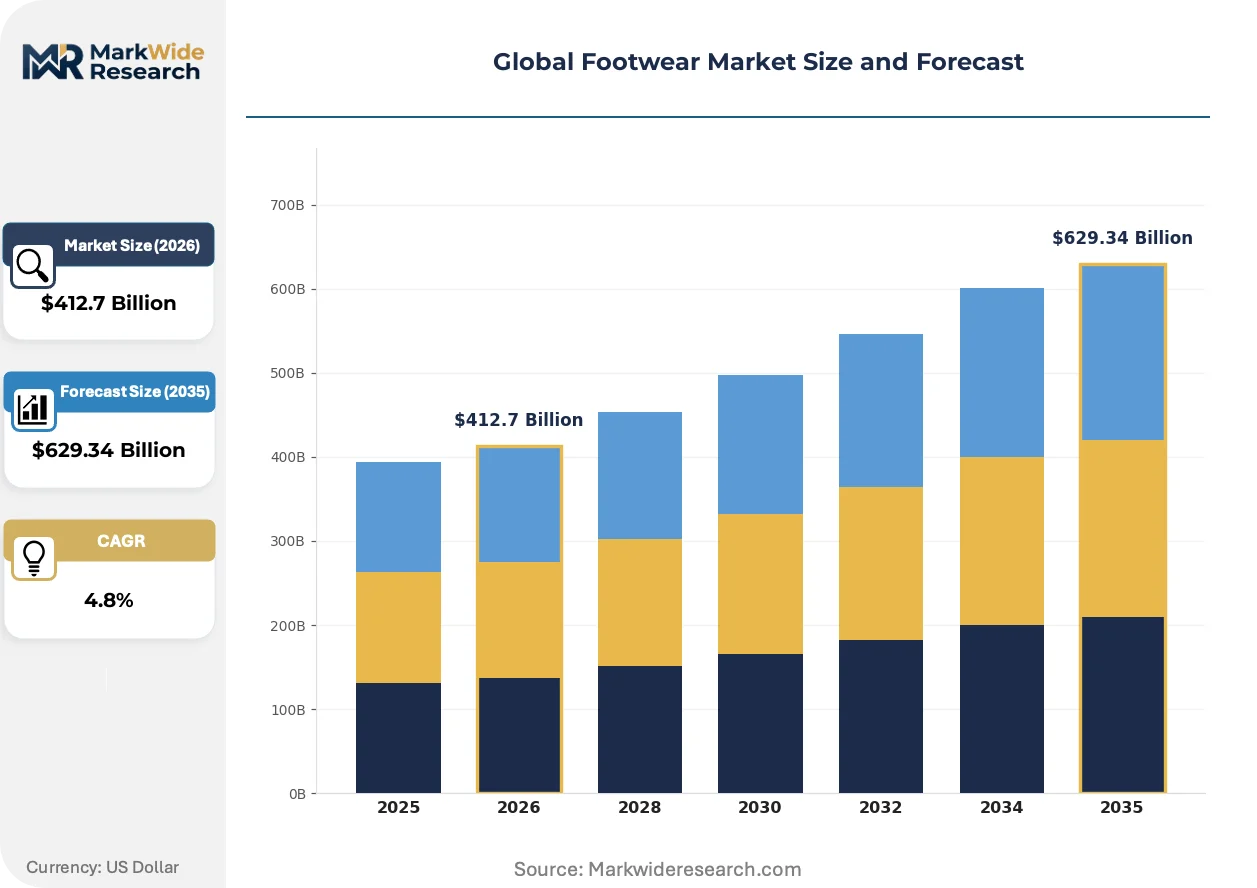
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $629.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sneakers, Sandals, Boots, Formal Shoes Material: Leather, Synthetic, Rubber, Canvas End User: Men, Women, Children, Unisex Sales Channel: Online Retail, Brick-and-Mortar, Third-Party Retailers, Supermarkets |
| Companies Covered | Nike, Adidas, ASICS Corporation, Puma, Skechers USA, New Balance Athletics, VF Corporation, Under Armour, Crocs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Footwear Market Emerging Trajectories
Digital manufacturing workflows and material science convergence are collapsing traditional design-to-shelf timelines while regulatory pressure on chemical inputs accelerates formulation replacement cycles.
3D-printed midsole lattice structures are rewriting cushioning performance benchmarks by enabling zonal density variation without tooling investment. Marathon and trail-running segments are adopting these platforms fastest, with specialty retailers now requiring scan-to-sole matching as a service standard. The technology is compressing SKU proliferation costs while enabling regional micro-factories to serve demand without inventory risk.
REACH Annex XVII restrictions on azo dyes and chromium VI in leather tanning are forcing reformulation of coloration and preservation chemistries across Asian export facilities. ECHA enforcement audits have intensified since 2023, with non-compliant batches facing port-of-entry destruction. Italian tanneries are capturing premium positioning through certified clean-process guarantees that command buyer preference in formal footwear lines.
Buyers now expect seamless inventory visibility across physical retail, brand-owned apps, and third-party marketplaces as a baseline service condition. This omni-channel integration is displacing traditional wholesale relationships where stock risk sat entirely with distributors. Germany and South Korea represent the most advanced implementations, with consumers accepting 48-hour ship-from-store fulfillment as the default expectation.
Global Footwear Market Segmentation
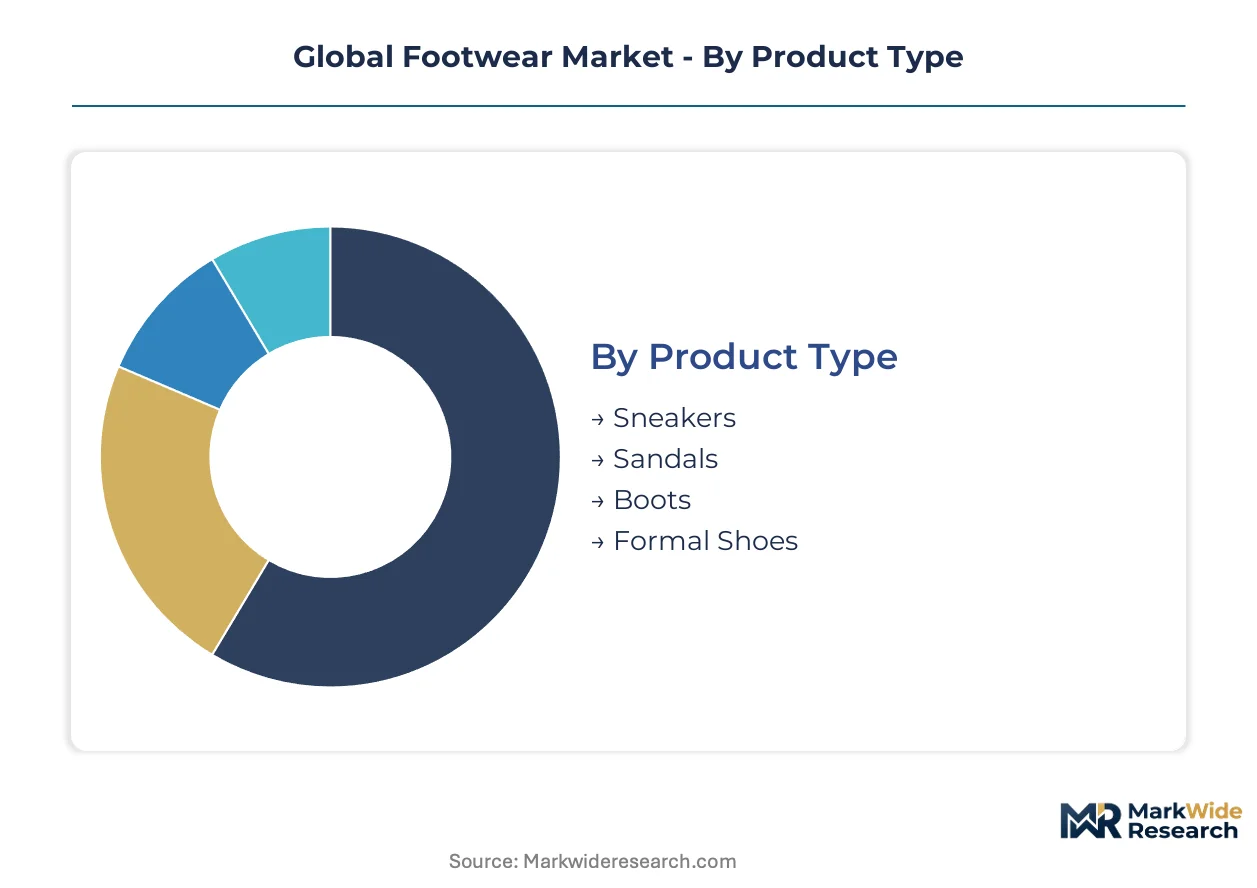
Segmentation in footwear reveals how manufacturing capacity, material sourcing constraints, and channel economics concentrate margin capture across distinct product architectures. Understanding these divisions exposes where supply bottlenecks and pricing power align.
Product Type:
Sneaker manufacturing clusters dominate global production capacity, with specialized knit-upper and foam-midsole tooling concentrated in coastal Chinese provinces and Vietnam.
- Sneakers:Engineered knit uppers and ethylene-vinyl acetate midsoles define performance-casual hybrids. Demand concentrates in Mumbai, Delhi, and Bangalore as India's organized retail penetration deepens, driven by athleisure boundary dissolution between gym and workplace contexts.
- Boots:Full-grain leather uppers with welted or direct-attach construction methods serve occupational safety and outdoor recreation segments. German and Italian technical bootmakers command price premiums through certified safety ratings and alpine performance validation.
- Sandals:Molded polyurethane or rubber footbeds with minimal upper coverage serve tropical climates and casual contexts.
- Formal Shoes:Blake-stitched or Goodyear-welted leather construction with stacked heels and leather soles retains margin concentration in European tannery-certified supply chains.
Sneakers absorb the bulk of installed capacity; sandals are expanding most quickly in South and Southeast Asian climates.
Material:
Material selection determines regulatory compliance pathways, with bio-based feedstocks and certified leather commanding procurement premiums amid ECHA REACH and China's MEE dual carbon enforcement.
- Leather:Full-grain and corrected-grain hides from LWG-certified Italian and Spanish tanneries supply formal and premium casual lines. REACH Annex XVII chromium VI restrictions limit qualified supplier pools to audited facilities with clean-process guarantees.
- Synthetic:Polyurethane and bio-based polymer matrices engineered for flex resistance and moisture management dominate performance footwear. China's petrochemical capacity redirection toward plant-derived feedstocks under MEE dual carbon goals is reshaping compliant material pipelines.
- Rubber:Natural and synthetic rubber compounds form outsoles and protective elements, with pricing volatility tethered to crude oil futures and Southeast Asian plantation yields.
- Canvas:Cotton or hemp textile uppers with vulcanized rubber soles serve price-accessible casual segments and heritage brand positioning.
Synthetic materials carry the heaviest volume load; bio-based polyurethane variants are climbing the fastest as regulatory timelines compress.
End User:
End-user segmentation tracks how sizing complexity, biomechanical requirements, and fashion velocity differentially strain manufacturing and inventory systems.
- Women:Higher SKU proliferation rates driven by fashion velocity and seasonal color rotation. European and South Korean markets show strongest demand for performance-casual hybrids with technical specifications.
- Men:Greater concentration in athletic performance and occupational safety categories with longer product lifecycles and lower return rates.
- Children:Phthalate content and small-part hazard monitoring by the US Consumer Product Safety Commission shapes Asian export testing protocols and material selection constraints.
- Unisex:Modular sizing and neutral aesthetics reduce inventory risk for direct-to-consumer platforms while capturing gender-fluid fashion trends in urban markets.
Women's footwear commands the widest SKU breadth; unisex lines are gaining share fastest among digitally native brands.
Sales Channel:
Channel segmentation exposes how inventory risk allocation and margin capture are restructuring as direct-to-consumer platforms displace wholesale intermediaries.
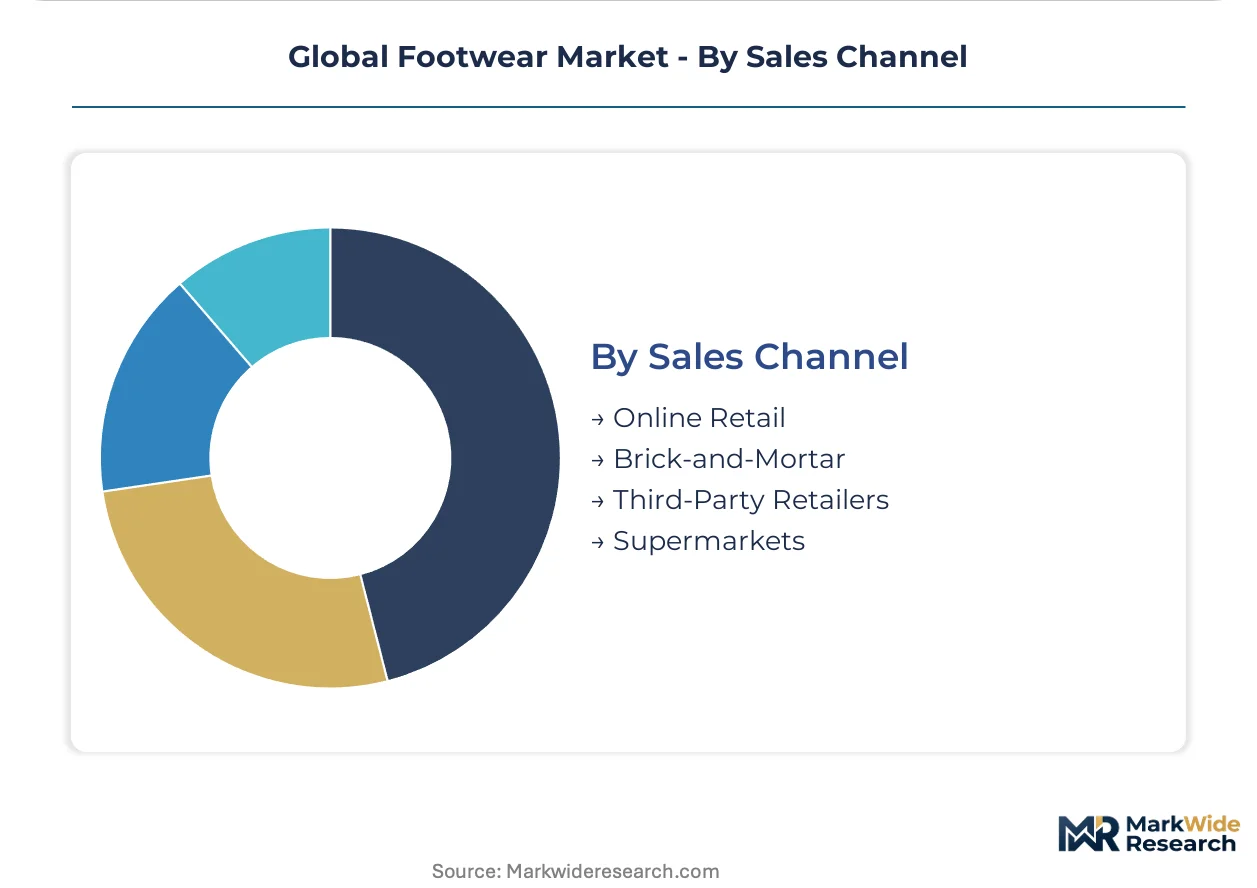
- Online Retail:Brand-owned e-commerce and marketplace listings bypass wholesale markups while compressing inventory cycles. Germany and South Korea lead omni-channel integration with 48-hour ship-from-store fulfillment as default expectation.
- Brick-and-Mortar:Flagship and mall-based retail in India's tier-one cities concentrates branded demand through experiential try-on and immediate fulfillment.
- Third-Party Retailers:Multi-brand wholesale accounts retain importance in markets with underdeveloped logistics infrastructure and high-touch fitting requirements.
- Supermarkets:Mass-market price-accessible lines with minimal service component serve routine replacement purchase occasions.
Brick-and-Mortar holds the deepest historical penetration; Online Retail is expanding most quickly as proprietary platforms capture margin previously allocated to distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the bulk of manufacturing capacity while the United States and Western Europe absorb the highest value consumption. This production-consumption divide shapes trade flows, regulatory compliance costs, and brand positioning strategies across major markets.
United States
Athleisure penetration in workplace and social contexts sustains sneaker volume leadership. The US Consumer Product Safety Commission enforces phthalate restrictions and small-part standards for children's footwear, directing Asian export testing protocols. Los Angeles and New York City concentrate brand headquarters and flagship retail footprints where direct-to-consumer platforms capture margin previously allocated to wholesale distributors.
Germany
Marathon and trail-running communities validate technical performance specifications that command price premiums. ECHA REACH Annex XVII restrictions on azo dyes and chromium VI in leather tanning accelerate solvent-free bonding technology adoption. Bavaria and Baden-Württemberg host specialized technical bootmakers and automated manufacturing research facilities serving alpine performance segments.
China
Coastal provinces in Fujian and Guangdong concentrate knit-upper and foam-midsole tooling for global sneaker supply. The Ministry of Ecology and Environment imposes dual carbon goals that redirect petrochemical capacity toward plant-derived polyurethane feedstocks. Qingdao and Dongguan clusters are pivoting export-bound production toward bio-based synthetic compliance for European and North American markets.
India
Tier-one cities drive branded footwear demand through organized retail penetration in Mumbai, Delhi, and Bangalore. BIS certification requirements for footwear safety and quality standards shape import substitution strategies for domestic manufacturers. Tamil Nadu and Uttar Pradesh industrial corridors are expanding export-oriented leather tanning and synthetic upper production capacity.
Vietnam
Manufacturing cost advantages attract mid-tier athletic footwear assembly from Chinese coastal provinces. The country's national environmental regulator enforces wastewater treatment standards for tannery and synthetic material facilities. Ho Chi Minh City and Binh Duong province concentrate export-processing zones where speedfactory automation trials compress design-to-shelf timelines for regional brands.
Global Footwear Market Vendor Landscape
The competitive structure tilts toward brand-led differentiation rather than commodity manufacturing scale. Athletic-casual hybridization has collapsed traditional category boundaries, forcing manufacturers to engineer single SKUs for multiple use scenarios. Three archetypes dominate: heritage sportswear houses with technical credibility, digitally native direct-to-consumer platforms, and vertically integrated Asian manufacturers supplying private-label programs. Competitive moves concentrate on proprietary material science partnerships and localized automated production networks.
Within the heritage sportswear tier, Nike and Adidas exemplify brand equity built through manufacturing scale control and innovation platform architectures. ASICS Corporation anchors technical credibility in marathon and trail-running validation communities where performance testing commands price premiums. These companies represent how sustained R&D investment and athlete endorsement networks create defensive positioning against private-label encroachment in premium segments.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| ASICS Corporation |
| Puma |
| Skechers USA |
| New Balance Athletics |
| VF Corporation |
| Under Armour |
| Crocs |
| Others |
Supply Flow & Price Mechanics
Specialized knit-upper technicians in Fujian and Guangdong provinces anchor labor-cost differentials that widen pricing-tier spreads between automated premium lines and manual-assembly economy batches.
Pricing Analysis
Margin tightening in mid-tier athletic footwear reflects petroleum-based input volatility tethered to crude oil futures. Three-tier pricing structure across premium, standard, and economy levels separates LWG-certified European leather constructions from speedfactory-automated synthetics and basic canvas vulcanized lines. Price differentiation hinges on certification grade and vertical integration depth. Brand-owned direct-to-consumer platforms capture margin previously allocated to wholesale distributors, while private-label importers show highest price sensitivity.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Los Angeles anchor hub-and-spoke patterns serving European and North American demand. Manufacturing concentrates in China, Vietnam, and Indonesia, drawing from ethylene-vinyl acetate, synthetic rubber, and bio-based polyurethane feedstocks. Single-source vulnerability persists in knit-upper tooling concentrated in coastal Chinese provinces. Distribution runs through brand-owned e-commerce platforms, third-party marketplaces, and mall-based retail networks in India's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Footwear manufacturing is becoming a vertical-integration race as brands pursue captive control over bio-based material pipelines to secure regulatory compliance and margin capture.
For Market Incumbents: Deploy proprietary speedfactory networks to compress design-to-shelf timelines against digitally native direct-to-consumer entrants. Reinforce technical credibility through marathon and trail-running athlete validation communities where performance testing commands price premiums. Secure LWG-certified tannery partnerships to defend formal footwear margins against REACH Annex XVII enforcement. For New Entrants and Emerging Players: EPR mandates in the EU and California open a window for closed-loop material recovery service models that incumbent brands underinvest in. Target modular sneaker system architecture where component replacement revenue models displace full-product substitution cycles. Pursue 3D-printed midsole lattice partnerships with regional micro-factories to bypass capital-intensive tooling barriers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated Asian manufacturers given dual carbon goal compliance pipelines redirecting petrochemical capacity toward plant-derived feedstocks. Long-term viability favors targets with certified bio-based material portfolios and automated production footprints. Monitor biomaterial certification timeline compression as inflection indicator for product launch velocity advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Material Pipeline Investment | MEE dual carbon goals in China redirect compliant feedstock access toward export-bound producers. |
| Speedfactory Automation Deployment | Localized production in Binh Duong province compresses inventory cycles for regional brand fulfillment. |
| Direct-to-Consumer Platform Expansion | Proprietary e-commerce in Germany and South Korea captures margin from wholesale distributor displacement. |
| Modular System Architecture Development | Interchangeable sole-upper platforms enable longevity-based revenue through component replacement. |
| REACH Compliance Certification | ECHA solvent-free bonding validation secures European port-of-entry access against batch destruction risk. |
Methodological Framework
Independent corroboration across brand supply chain executives, retail category managers, and biomaterial R&D directors underwrites the qualitative findings. Primary interviews with tannery procurement leads, speedfactory operations heads, and ESG compliance officers combined with secondary validation from customs trade data, SEC footwear segment filings, and Leather Working Group audit records. Bottom-up SKU-level modeling and top-down category spend analysis triangulate volume estimates.
Rate-of-change decomposition across the projection horizon segments volume by product type, material certification tier, end-user demographic, and sales channel. Modeled dimensions include sneaker-boot-sandal-formal splits, LWG-certified versus conventional leather, and online versus brick-and-mortar velocity. CAGRs derive from historical shipment trajectories adjusted for regulatory compliance timelines and channel shift elasticities. Bio-based polyurethane feedstock availability and REACH enforcement intensity serve as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for 3D-printed midsole lattice manufacturing would alter the outlook. Forecasts reflect assumptions around EPR mandate implementation pace and dual carbon goal enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Women's Non-Athletic Footwear Market
Footwear
Chunky Sneaker Market
Footwear
Trail Running Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Global Recovery Footwear Market
Footwear
US Slip Resistant Shoes Market
Footwear
PVC Footwear Market
Footwear
Slip on Shoes Market
Footwear
Sandals Market
Footwear
Custom Shoes Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Cowboy Boots Market
Footwear
Slip Resistant Shoes Market
Footwear
Winter Footwear Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
Waterproof Sneakers Market