
 Asia-Pacific Avalanche Radar Market | 2026-2036
Asia-Pacific Avalanche Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Avalanche Radar Market Insights
Capital-intensity divergence between in-house antenna fabrication and outsourced RF module sourcing is bifurcating competitive tiers in the Asia-Pacific avalanche radar landscape. Vaisala Oyj leverages its Helsinki-rooted atmospheric sensing heritage to anchor premium positioning across Japanese ski resort networks. Wyssen Avalanche Control AG competes through integrated avalanche control systems that bundle radar with remote-triggered ordnance deployment. Geobrugg AG sustains its foothold via rockfall-monitoring cross-selling into Himalayan infrastructure corridors.
Asia-Pacific avalanche radar denotes ground-based or airborne microwave sensing systems that emit pulsed or frequency-modulated continuous wave signals to detect snowpack density variations and surface displacement at ranges exceeding three kilometers, primarily safeguarding transportation corridors, mining operations, and recreational terrain from catastrophic mass-movement events. Fixed radar installations command the dominant share of current procurement budgets due to their integration with permanent weather station networks across alpine prefectures. Portable radar units represent the fastest-expanding category as India's Border Roads Organisation and New Zealand's Department of Conservation prioritize rapid-deployment capabilities for seasonal hazard zones. Pulse Doppler technology leads the technology dimension by maturity, while frequency modulated continuous wave architectures are gaining traction where fine-range resolution for snowpack stratigraphy analysis justifies higher unit costs.
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces structural safety standards that mandate continuous slope monitoring above designated railway and highway corridors, directly stimulating replacement cycles for legacy sensor networks. India's BIS certification requirements for electromagnetic equipment deployed in mountainous terrain create compliance barriers that favor established suppliers with domestic testing partnerships. Australia's TGA-equivalent spectrum management protocols and South Korea's MFDS-aligned import inspection regimes for industrial sensing hardware further fragment market access conditions. Stakeholders must weigh the trade-off between standardized product platforms and geography-specific certification investments when allocating regional manufacturing capacity.
Market Dynamics
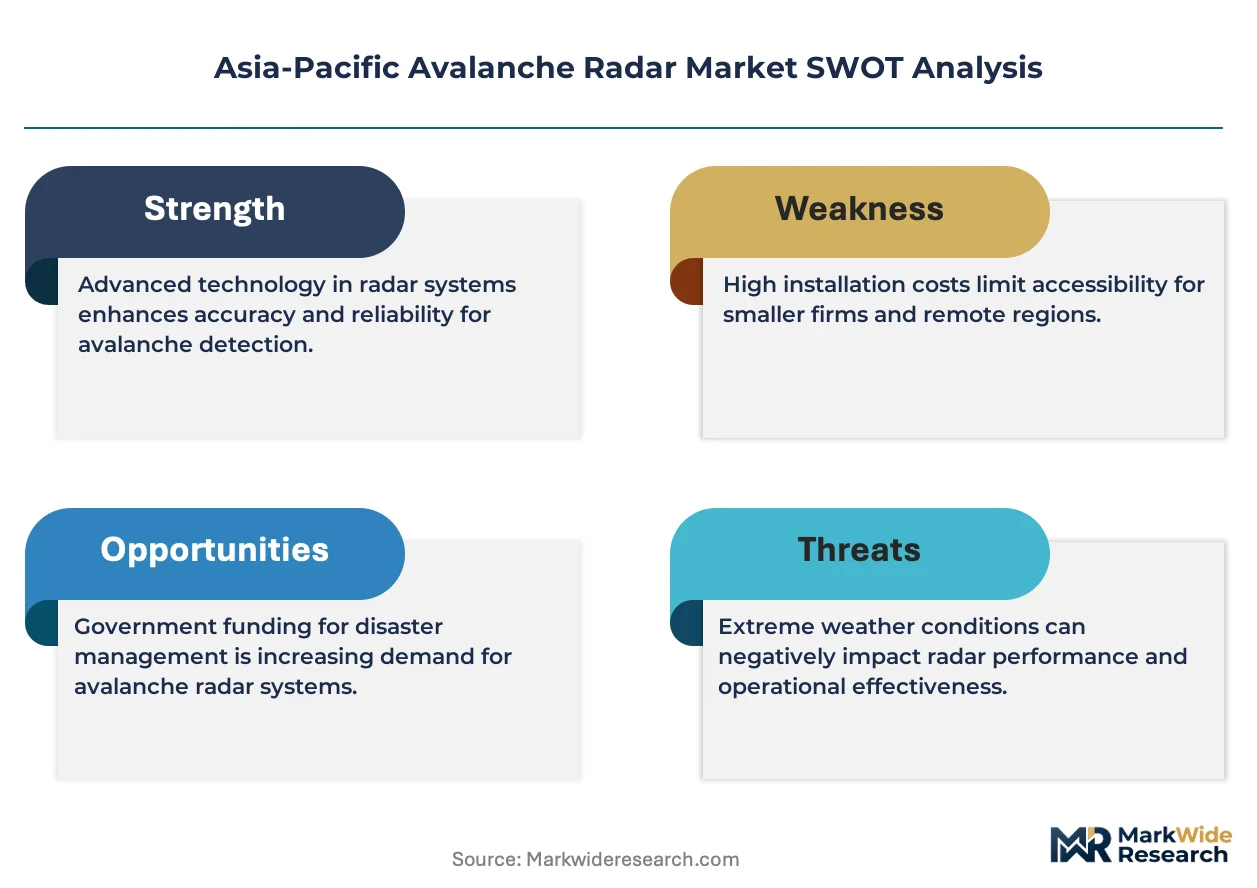
Fixed radar installations are displacing legacy geophone networks across Japanese railway corridors, while India's Border Roads Organisation accelerates portable unit procurement for seasonal Himalayan deployment. This bifurcation between permanent infrastructure and rapid-response capability is redrawing supplier specialization boundaries across the region.
Growth Catalysts
- Japan's MLIT structural safety mandates:Continuous slope monitoring requirements above designated transport corridors force replacement cycles for aging sensor networks. Railway operators in Nagano and Niigata prefectures now specify radar-integrated weather stations.
- Himalayan infrastructure corridor expansion:Road and tunnel projects spanning India, Nepal, and Bhutan generate concentrated demand for avalanche detection systems. The Asian Development Bank's financing of trans-border connectivity routes embeds safety equipment procurement clauses.
- FMCW technology maturation:Frequency modulated continuous wave architectures enable snowpack stratigraphy analysis at fine-range resolution. Ski resorts in New Zealand's Southern Alps prioritize these units for powder stability assessment.
Market Restraints
- Gallium nitride RF component supply concentration:High-performance radar front-ends depend on specialized semiconductor foundries concentrated in Taiwan and South Korea. Geopolitical friction threatens input cost stability and delivery timelines.
- India's BIS electromagnetic equipment certification:Mountainous terrain deployment standards create multi-month testing protocols. Domestic testing partnership requirements favor incumbent suppliers with established laboratory relationships.
- Optical satellite interferometry substitution:InSAR-based slope monitoring offers lower capital expenditure for wide-area surveillance. Mining operators in Australia's Snowy Mountains region increasingly pilot these alternatives for pit wall stability.
Strategic Opportunities
- Bhutan's untapped hydropower construction pipeline:Dam and transmission line projects through glaciated valleys require integrated hazard detection. The country's strict environmental impact assessment rules mandate real-time monitoring systems.
- Drone-mounted radar convergence:Miniaturized FMCW units paired with long-endurance unmanned aerial vehicles enable rapid slope surveying. New Zealand's Department of Conservation trials these for backcountry avalanche forecasting.
- Australia's Bureau of Meteorology equipment standards:Accelerated certification timelines for radar systems meeting interoperability protocols create first-mover advantages. Suppliers aligning with these specifications gain preferred vendor status for federal procurement.
Industry Challenges
- Microwave engineering talent scarcity:RF circuit design and antenna optimization expertise concentrates in legacy defense and telecommunications sectors. Avalanche radar manufacturers compete for limited specialist pools in Sydney, Tokyo, and Bangalore.
- Legacy geophone network integration:Railway operators in Hokkaido and Honshu demand seamless data fusion between new radar installations and existing seismic sensor grids. Protocol standardization delays complicate system architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Avalanche Radar Market |
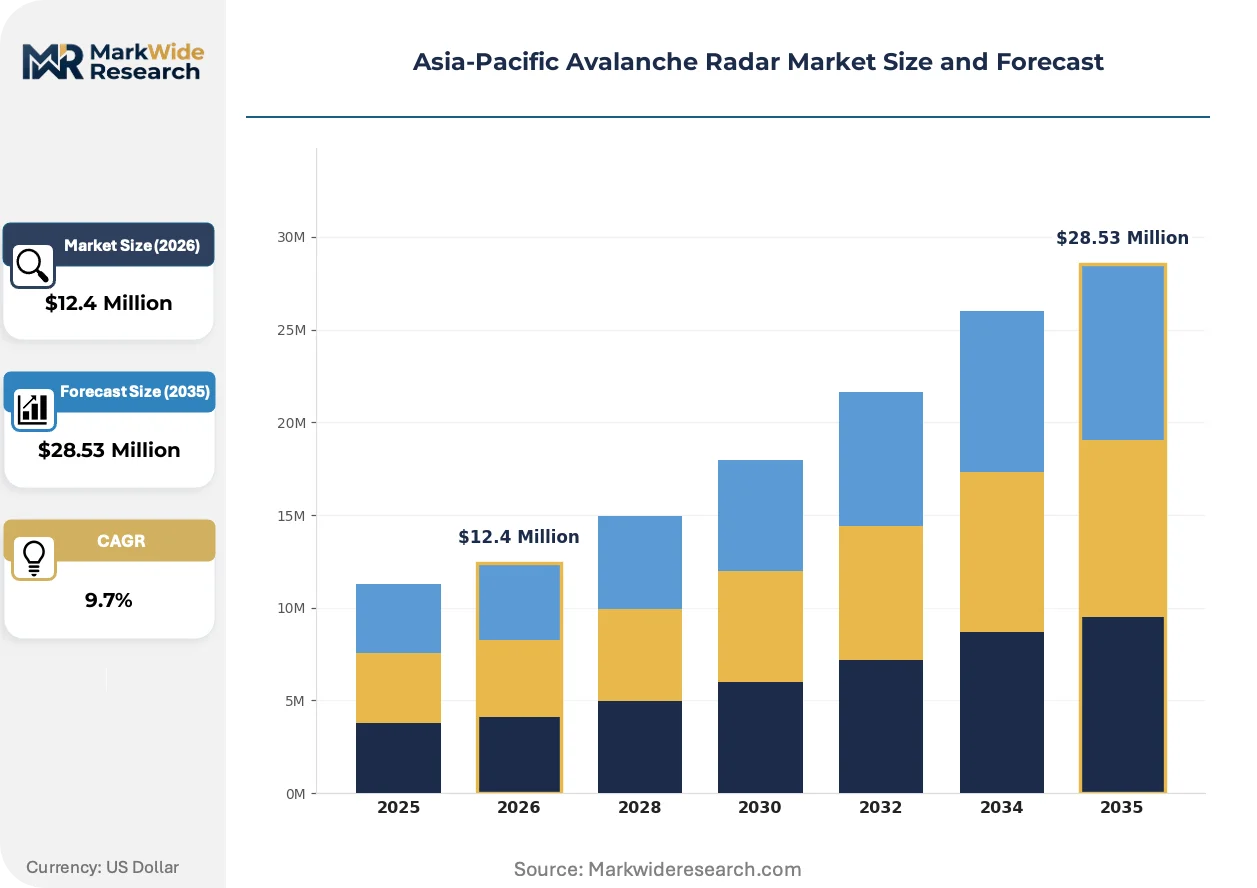
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $28.53 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Radar, Portable Radar, Ground-Based Radar, Drone-Based Radar End User: Government Agencies, Research Institutions, Ski Resorts, Emergency Services Application: Snow Avalanches, Rock Avalanches, Landslide Monitoring, Snowpack Analysis Technology: Pulse Doppler Radar, Frequency Modulated Continuous Wave, Synthetic Aperture Radar, Microwave Radar |
| Companies Covered | Vaisala Oyj, Recco AB, Geobrugg AG, Kongsberg Gruppen, L.B. Foster Company, Wyssen Avalanche Control AG, Hexagon AB, Leica Geosystems, GEOPRAEVENT AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Avalanche Radar Market Trends and Innovations
Software-defined radar architectures are compressing hardware refresh cycles while enabling post-deployment feature upgrades. This shift decouples physical sensor longevity from functional obsolescence, altering capital planning horizons for infrastructure operators.
Frequency modulated continuous wave radar is fragmenting the traditional pulse Doppler installed base. FMCW units deliver millimeter-scale range resolution for snowpack density profiling. Japanese ski resort operators in Niseko and Hakuba lead adoption, compressing procurement timelines for legacy systems. The technology is fragmenting supplier revenue models toward software-licensing overlays on hardware platforms.
India's BIS certification framework for electromagnetic equipment deployed in mountainous terrain is tightening import inspection protocols. Foreign manufacturers must demonstrate domestic testing partnerships or establish local calibration facilities. Himalayan infrastructure contractors in Uttarakhand and Himachal Pradesh now specify pre-certified radar units to avoid project delays. The regulation is accelerating joint venture formation between international suppliers and Indian testing laboratories.
Buyers are unbundling after-sales service contracts from initial equipment procurement. Australia's ski resort operators and New Zealand's conservation agencies now negotiate separate multi-year maintenance agreements post-installation. This behavioral shift compresses upfront capital outlays while creating recurring revenue streams for technical service providers. The practice is most visible in Victoria's alpine resorts and Canterbury's mountain parks.
Asia-Pacific Avalanche Radar Market Segmentation
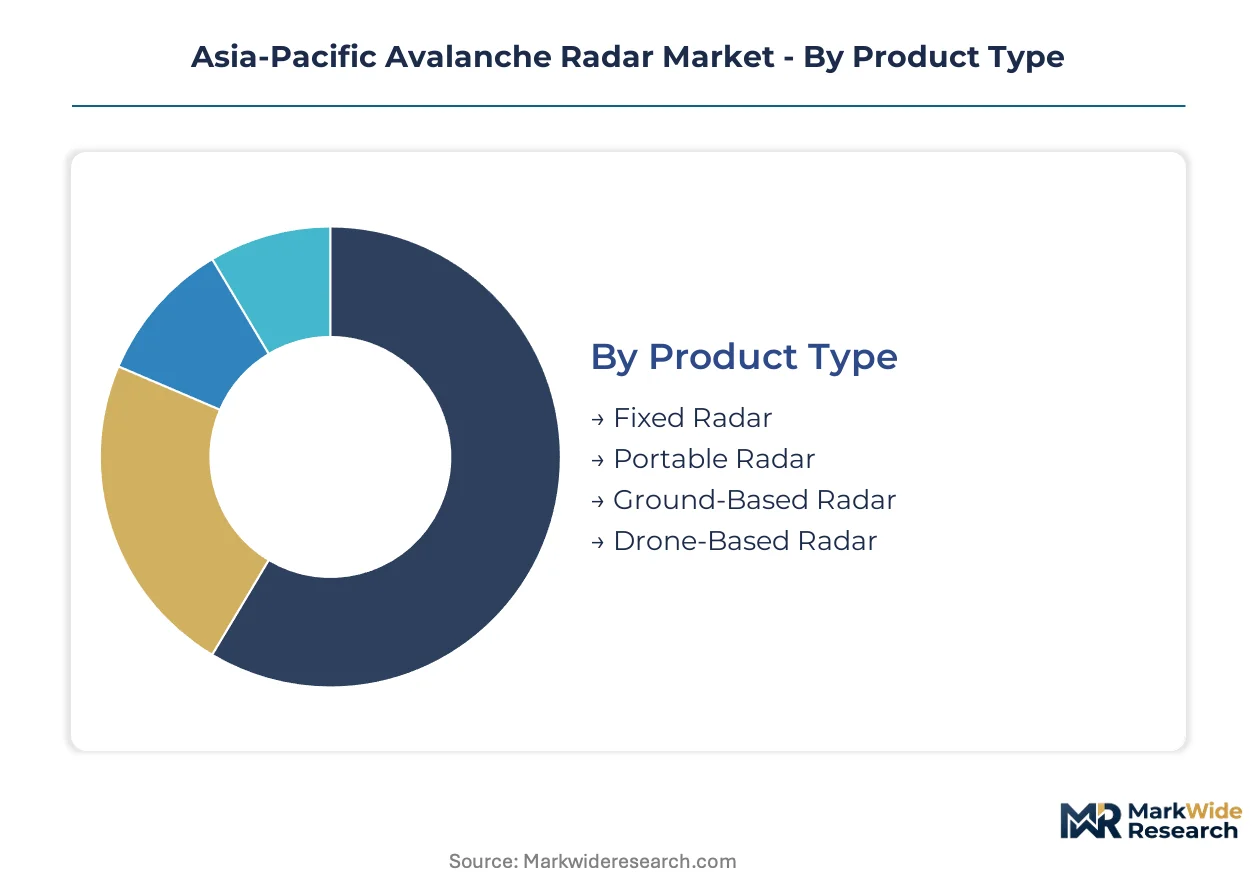
Segmentation in avalanche radar procurement reveals divergent capital allocation patterns across infrastructure permanence, operational mobility, and analytical precision requirements. Buyers optimize specifications against deployment duration, terrain accessibility, and real-time data integration needs.
Product Type:
Margin pools concentrate in fixed installations where long-term service contracts and weather station integration create recurring revenue streams.
- Fixed Radar:Permanent installations emit pulsed signals across designated transport corridors with continuous power and data uplink integration. Japanese railway operators in Nagano and Niigata prefectures mandate these systems for structural safety compliance above highway and rail alignments.
- Portable Radar:Battery-operated units deploy rapidly to seasonal hazard zones without permanent infrastructure. India's Border Roads Organisation procures these for Himalayan road maintenance camps where terrain precludes fixed installation.
- Ground-Based Radar:Trailer-mounted or skid-mounted configurations balance mobility with antenna aperture for intermediate-range detection. Mining operators in Australia's Snowy Mountains region favor these for pit wall surveillance.
- Drone-Based Radar:Miniaturized FMCW units paired with unmanned aerial vehicles enable rapid slope surveying in inaccessible terrain. New Zealand's Department of Conservation trials these for backcountry avalanche forecasting.
Fixed radar holds installed capacity. Drone-based radar is rotating up the share rankings.
End User:
Procurement volumes cluster where public safety mandates intersect with federal budget allocations and multilateral development financing.
- Government Agencies:National transport ministries and border infrastructure authorities dominate capital expenditure through centralized procurement frameworks. Japan's MLIT structural safety mandates directly fund slope monitoring above designated corridors.
- Ski Resorts:Private operators in Niseko, Hakuba, and New Zealand's Southern Alps prioritize powder stability assessment and patron liability mitigation. These buyers lead adoption of FMCW technology for snowpack stratigraphy analysis.
- Research Institutions:Glaciology and cryosphere research centers deploy radar for process understanding rather than operational safety. Himalayan research stations in India and Nepal maintain limited procurement budgets.
- Emergency Services:Fire and civil defense agencies procure portable units for post-event search and rescue operations. Seasonal deployment patterns constrain fleet utilization rates.
Government agencies anchor procurement volume. Ski resorts are climbing the fastest in technology specification influence.
Application:
Demand intensity tracks directly with population exposure and economic asset concentration in hazardous terrain.
- Snow Avalanches:Detection systems monitor surface hoar and depth hoar formation in alpine snowpacks. Japanese ski resort networks and Himalayan transport corridors concentrate procurement for this application.
- Rock Avalanches:Ground-penetrating and surface displacement radar monitors fractured bedrock above infrastructure. Bhutan's hydropower construction pipeline generates concentrated demand for integrated hazard detection in glaciated valleys.
- Landslide Monitoring:Slope stability radar tracks soil moisture and shear surface movement. Australia's Bureau of Meteorology standards accelerate equipment certification for these deployments.
- Snowpack Analysis:Fine-resolution density profiling supports avalanche forecasting and water resource estimation. New Zealand's conservation agencies prioritize this application for backcountry safety management.
Snow avalanche detection holds installed capacity. Rock avalanche monitoring is gaining share fastest.
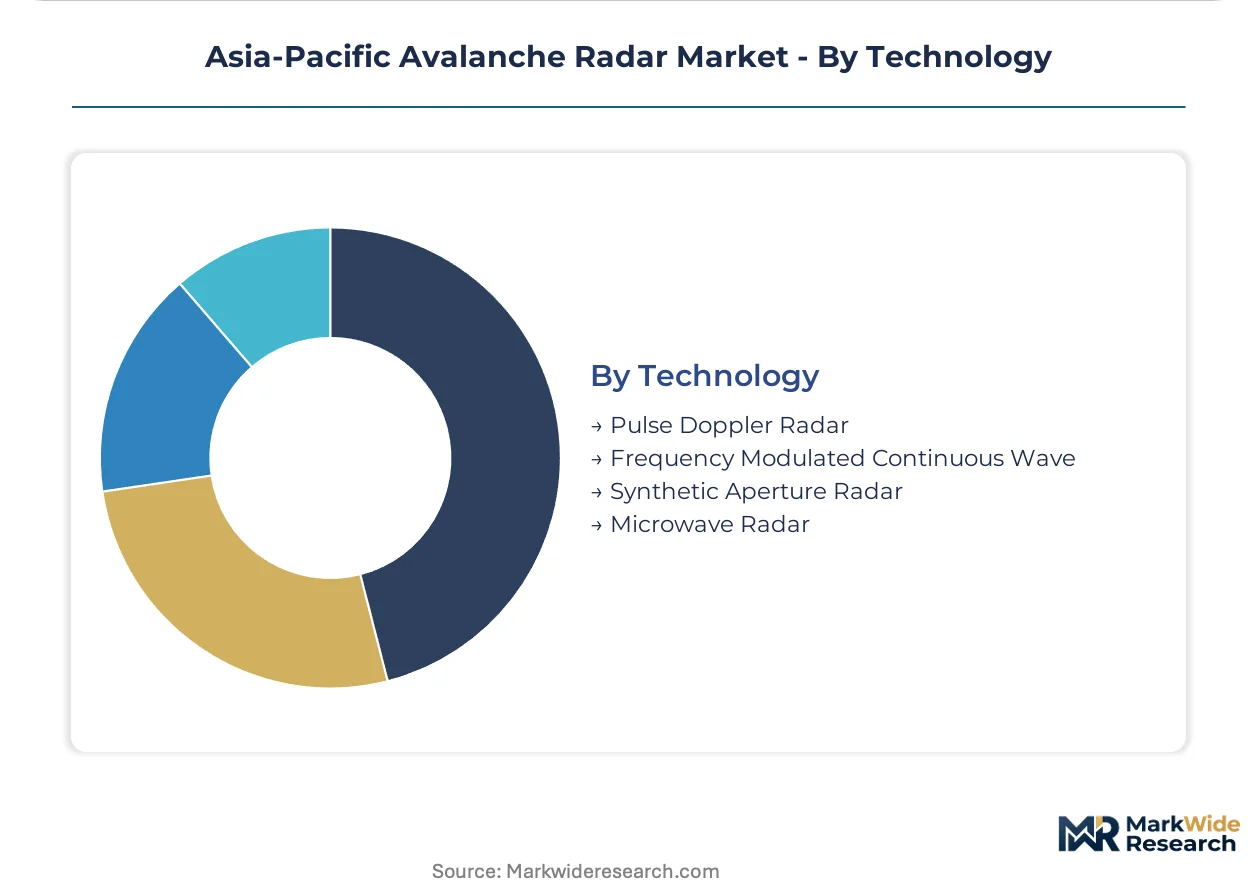
Technology:
Architecture selection trades range resolution against processing complexity and unit cost in procurement decisions.
- Pulse Doppler Radar:Mature technology emits discrete pulses and analyzes Doppler shift for velocity measurement. Dominates current installed base across Japanese railway corridor networks due to proven reliability in precipitation.
- Frequency Modulated Continuous Wave:Continuous emission with frequency modulation enables millimeter-scale range resolution for snowpack stratigraphy. Ski resort operators in New Zealand's Southern Alps and Japan's Niseko region drive adoption despite higher unit costs.
- Synthetic Aperture Radar:Signal processing techniques synthesize large antenna apertures from moving platforms. Drone-mounted deployments in Himalayan terrain trials utilize this architecture for wide-area coverage.
- Microwave Radar:General-purpose designation encompassing non-coherent detection systems at lower frequency bands. Legacy installations in Indian Border Roads Organisation inventory utilize these for basic slope surveillance.
Pulse Doppler radar holds installed capacity. Frequency modulated continuous wave is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for GaN RF front-end components shapes procurement timelines across the Asia-Pacific avalanche radar landscape. Taiwan and South Korean foundry concentration creates vulnerability for Japanese and Indian system integrators. Export flows of finished radar units from European suppliers dominate premium-tier procurement in Himalayan corridor projects.
Japan
Japan's MLIT structural safety mandates drive fixed radar installations above railway corridors in Nagano and Niigata prefectures. Railway operators specify radar-integrated weather stations for continuous slope monitoring compliance. Vaisala Oyj anchors premium positioning across Niseko and Hakuba ski resort networks through Helsinki-rooted atmospheric sensing heritage.
India
India's Border Roads Organisation accelerates portable unit procurement for seasonal Himalayan deployment along Uttarakhand and Himachal Pradesh road maintenance camps. BIS certification requirements for electromagnetic equipment create multi-month testing protocols favoring established suppliers with domestic laboratory partnerships. Himalayan infrastructure contractors now specify pre-certified radar units to avoid project delays.
Australia
Mining operators in Australia's Snowy Mountains region pilot InSAR-based slope monitoring alternatives for pit wall stability surveillance. The Bureau of Meteorology equipment standards accelerate certification timelines for radar systems meeting interoperability protocols. Victoria's alpine resorts unbundle after-sales service contracts from initial equipment procurement.
New Zealand
New Zealand's Department of Conservation prioritizes rapid-deployment capabilities for seasonal hazard zones across Canterbury's mountain parks. The agency trials drone-mounted FMCW units paired with long-endurance unmanned aerial vehicles for backcountry avalanche forecasting. Ski resorts in the Southern Alps lead adoption of frequency modulated continuous wave technology for powder stability assessment.
Bhutan
Bhutan's hydropower construction pipeline through glaciated valleys generates concentrated demand for integrated hazard detection systems. The country's strict environmental impact assessment rules mandate real-time monitoring for dam and transmission line projects. Rock avalanche monitoring applications gain share fastest in this untapped procurement frontier.
Asia-Pacific Avalanche Radar Market Competitive Landscape
Concentration sits with atmospheric sensing heritage players and integrated avalanche control specialists. The vendor base spans three tiers: premium-positioned European heritage suppliers, mid-tier integrated systems providers bundling radar with ordnance deployment, and rockfall-monitoring cross-sellers leveraging Himalayan infrastructure relationships. Strategic moves center on domestic testing partnership formation for BIS compliance and software-defined radar architecture licensing for post-deployment feature upgrade revenue.
Among European heritage suppliers, Vaisala Oyj and Geobrugg AG exemplify divergent positioning archetypes. Vaisala Oyj represents the atmospheric sensing heritage tier anchoring premium pricing across Japanese ski resort networks. Geobrugg AG occupies a position within the rockfall-monitoring cross-seller archetype sustaining footholds via infrastructure corridor relationships. Wyssen Avalanche Control AG sits within the integrated systems tier competing through bundled radar and remote-triggered ordnance deployment offerings.
| Leading Market Players |
|---|
| Vaisala Oyj |
| Recco AB |
| Geobrugg AG |
| Kongsberg Gruppen |
| L.B. Foster Company |
| Wyssen Avalanche Control AG |
| Hexagon AB |
| Leica Geosystems |
| GEOPRAEVENT AG |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Japanese railway operators and European heritage suppliers lock in multi-year supply access while freezing unit pricing visibility across replacement cycles for MLIT-mandated slope monitoring networks.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Asia-Pacific avalanche radar landscape. Premium tier commands certification-grade positioning against Japan's structural safety mandates, while economy tier serves India's Border Roads Organisation seasonal procurement with stripped-down portable configurations. Price differentiation hinges on BIS electromagnetic certification status and after-sales service bundling duration. Cost compression in the standard tier is intensifying because buyers unbundle maintenance contracts from initial hardware procurement. Government agencies exhibit lowest price sensitivity due to multilateral development financing clauses, whereas private ski resort operators in New Zealand demonstrate highest elasticity to upfront capital outlays.
Supply Chain Analysis
Taiwan and South Korea anchor gallium nitride RF front-end fabrication for high-performance radar systems deployed across Himalayan infrastructure corridors. Japanese and Indian system integrators draw from specialized semiconductor foundries concentrated in these geographies for pulsed signal generation components. Raw material dependencies span GaN-on-SiC substrates, precision-machined aluminum antenna housings, and high-frequency coaxial cabling. Single-source vulnerability in Taiwanese wafer processing creates procurement timeline risk for fixed installation projects with rigid completion deadlines. Distribution runs through authorized systems integrators with domestic testing laboratory partnerships, particularly for BIS compliance in Indian mountainous terrain deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined radar architectures fragment procurement patterns by decoupling hardware longevity from functional refresh cycles, creating specialization niches for firmware licensing specialists alongside traditional equipment vendors.
For Market Incumbents: Consolidate around domestic testing partnership networks to defend against BIS certification barriers favoring established suppliers with Indian laboratory relationships. Deepen backward integration into antenna fabrication to offset GaN RF module cost volatility from Taiwanese foundry concentration. Prioritize capacity reservation agreements with South Korean semiconductor suppliers to secure input access for MLIT-mandated Japanese railway corridor deployments. For New Entrants and Emerging Players: Australia's Bureau of Meteorology equipment standards fast-track creates preferred vendor pathways for interoperability-aligned suppliers. Target Bhutan's hydropower construction pipeline as the most penetrable geography, where strict environmental impact assessment rules mandate real-time monitoring systems without entrenched incumbent relationships. Pursue drone-mounted FMCW radar trials with New Zealand's Department of Conservation as the primary go-to-market angle for rapid-deployment capability positioning. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors software-defined architecture specialists over legacy pulse Doppler hardware manufacturers. Long-term viability over the coming decade hinges on recurring revenue streams from post-deployment feature upgrades rather than transactional equipment sales. Acquisition target archetype: mid-tier integrated systems providers bundling radar with remote-triggered ordnance deployment. Watch drone-mounted radar convergence with unmanned aerial vehicle platforms as the signal indicating inflection toward rapid-surveying service models.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Testing Partnership Formation | BIS certification compliance accelerates market access for Indian Himalayan infrastructure procurement. |
| Software-Defined Architecture Licensing | Post-deployment firmware upgrades transform capital equipment vendors into recurring revenue service providers. |
| GaN RF Front-End Supply Agreement | Taiwanese and South Korean foundry relationships secure component access for high-performance radar production. |
| Drone Platform Integration | New Zealand's Department of Conservation trials validate miniaturized FMCW units for backcountry forecasting. |
| After-Sales Service Unbundling | Victoria's alpine resorts demonstrate buyer preference for separate multi-year maintenance negotiations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MLIT structural safety filings, BIS electromagnetic equipment certification protocols, and Bureau of Meteorology interoperability standards. Primary interviews engaged railway infrastructure planners, Himalayan road project engineers, ski resort operations directors, and avalanche control system procurement officers across Japan, India, Australia, New Zealand, and Bhutan. Secondary validation incorporated customs trade data for radar component imports, Asian Development Bank project financing disclosures, and national weather service equipment procurement records. Bottom-up unit shipment estimates triangulated against top-down infrastructure budget allocations across the analysis window.
Segmentation dimensions modeled include product type permanence, technology architecture maturity, end-user procurement framework, and application hazard specificity. CAGRs were derived from infrastructure investment pipeline analysis and replacement cycle timing for legacy geophone networks. Industry-specific forecast inputs encompass MLIT-mandated slope monitoring compliance deadlines and Himalayan corridor multilateral development financing disbursement schedules.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment flows or altered semiconductor supply chain configurations would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and foundry capacity availability. Recalibration cycles align with material shifts in MLIT safety mandate expansion, BIS certification protocol revisions, or GaN RF component supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
Unmanned Combat Aerial Vehicle Market
Aerospace & Defense
Aerospace and Defense Fluid Conveyance Systems Market
Aerospace & Defense
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aerospace & Defense
Europe Cyber Weapons Market
Aerospace & Defense
Aerospace Lightweight Materials Market
Aerospace & Defense
Target Acquisition Systems Market
Aerospace & Defense
Middle East and Africa Aviation Market
Aerospace & Defense
Drone Lens Market
Aerospace & Defense
LEO and GEO Satellite Market
Aerospace & Defense
Europe Tethered Drone Market
Aerospace & Defense
Drone Tethered Stations Market
Aerospace & Defense
Aerospace Pressure Bulkheads Market
Aerospace & Defense
Electric Glider Market
Aerospace & Defense
North America Armored Fighting Vehicles Market
Aerospace & Defense
Police and Military Simulation Training Market
Aerospace & Defense
Electric Aircraft Market