
 Skydiving Equipment Market | 2026-2036
Skydiving Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Skydiving Equipment Market Analysis
Buyer concentration is pivoting as military procurement agencies consolidate volume under fewer approved vendors while civilian drop zones fragment across independent operators and experiential tourism platforms. Performance Designs sustains dominance in competition-grade canopy engineering through proprietary airfoil architectures. Aerodyne Research LLC anchors military contract flows with FAA-certified manufacturing protocols. Sun Path Products Inc. differentiates via integrated harness-container systems that reduce rigging complexity for professional users.
Skydiving equipment encompasses engineered aerial descent systems including ram-air parachutes constructed from zero-porosity ripstop nylon with calibrated cell inflation profiles, precision altimeters utilizing barometric pressure differentials, and anthropometrically fitted harness assemblies designed to distribute opening shock loads across the torso. The equipment serves commercial, military, and recreational users requiring controlled freefall and canopy flight operations. Parachute systems occupy the largest value share given replacement cycles tied to jump counts and reserve repack mandates. Automatic Activation Devices within the technology dimension represent the fastest-expanding segment as regulatory bodies mandate redundant deployment safeguards. Military application channels command premium pricing due to extended qualification testing and custom specification requirements.
FAA Technical Standard Orders govern airworthiness certification for parachute assemblies in the United States, while EASA implements parallel CS-25 and CS-23 standards across European jurisdictions. The EU AI Act introduces emerging compliance considerations for sensor-integrated wearable tech and automated deployment algorithms. ISO 12401 specifies international baseline requirements for personal flotation and descent safety equipment. Stakeholders must monitor evolving interface standards between wearable biometric monitors and automatic activation triggers as regulatory scope broadens beyond mechanical systems into data-driven safety protocols.
Market Dynamics
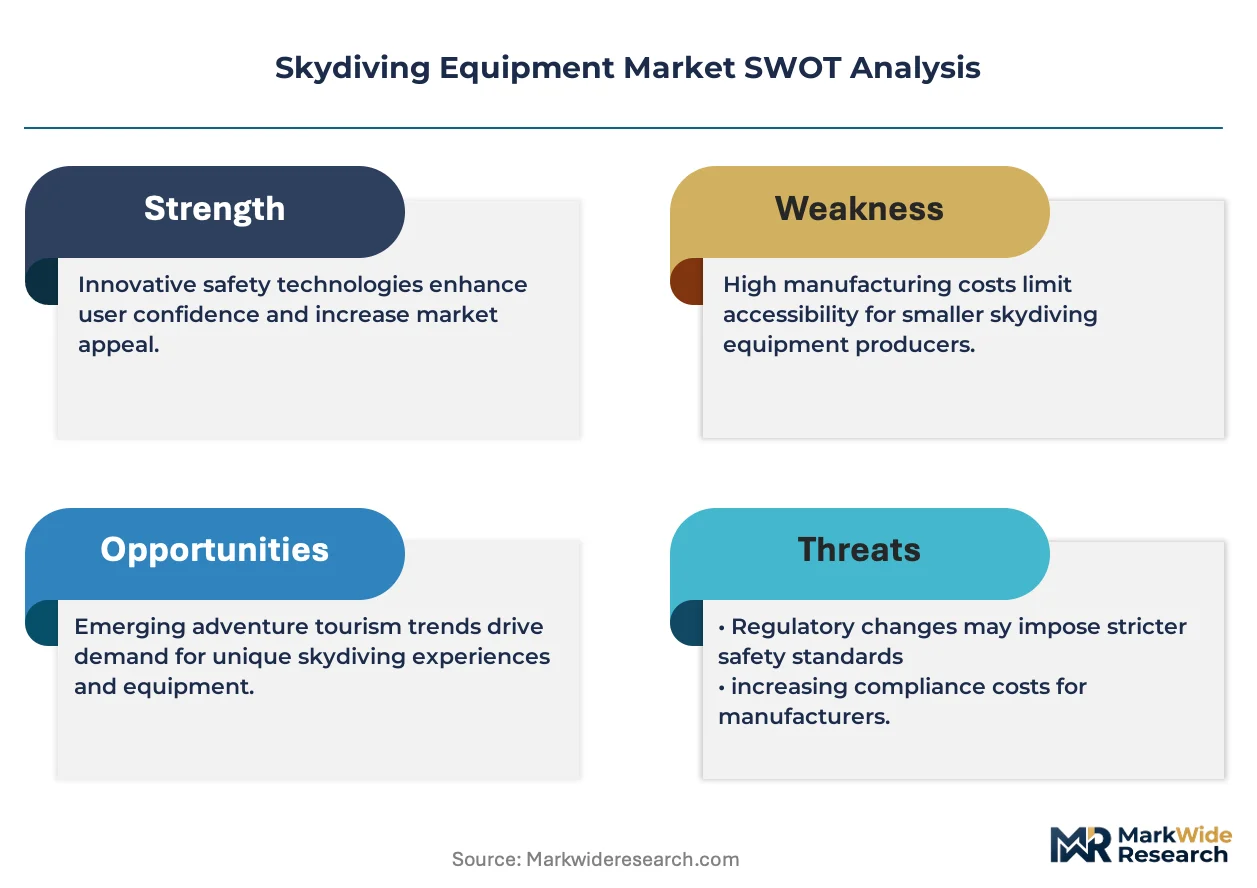
Military procurement consolidation is compressing vendor margins while ram-air canopy innovation and FAA certification mandates for Automatic Activation Devices reshape competitive positioning across both defense and civilian channels.
Growth Catalysts
- Special Operations Training Expansion:NATO member states are scaling precision aerial delivery system acquisitions for tactical insertion missions, with procurement concentrated in Florida, California, and Arizona training corridors.
- FAA TSO-C23d Mandates:Airworthiness certification requirements for reserve parachute systems are accelerating replacement cycles across US drop zones as operators face compliance deadlines.
- Zero-Porosity Ripstop Nylon:Advancements in calibrated cell inflation profiles are elevating glide ratio performance benchmarks for competition-grade canopy systems.
Market Restraints
- Carbon Fiber Composite Input Volatility:Lightweight container system manufacturers face margin pressure from aerospace-grade material pricing fluctuations tied to defense sector demand surges.
- Vendor Concentration Risk:Military contract flows consolidate under FAA-certified manufacturers, creating supply bottlenecks for specialized harness-container assemblies.
- EU AI Act Compliance Friction:Sensor-integrated wearable tech and automated deployment algorithms face emerging regulatory scope expansion beyond mechanical certification protocols.
Strategic Opportunities
- Experiential Tourism Platforms:Independent drop zone operators in Arizona and California are fragmenting demand through tandem jump package aggregation, bypassing traditional equipment procurement channels.
- Biometric-Wearable Convergence:Integration between heart-rate monitors and automatic activation triggers creates white space for data-driven safety protocol vendors.
- Reserve Repack Service Unbundling:Mandatory 180-day repack cycles for reserve parachutes enable recurring revenue models for certified rigging technicians operating outside manufacturer networks.
Industry Challenges
- Master Rigger Certification Scarcity:FAA-certified rigging technicians face 18-24 month training pipelines, constraining service capacity at high-volume drop zones.
- ISO 12401 Harmonization Delays:Divergent international baseline requirements for descent safety equipment complicate cross-border equipment certification for multinational operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skydiving Equipment Market |
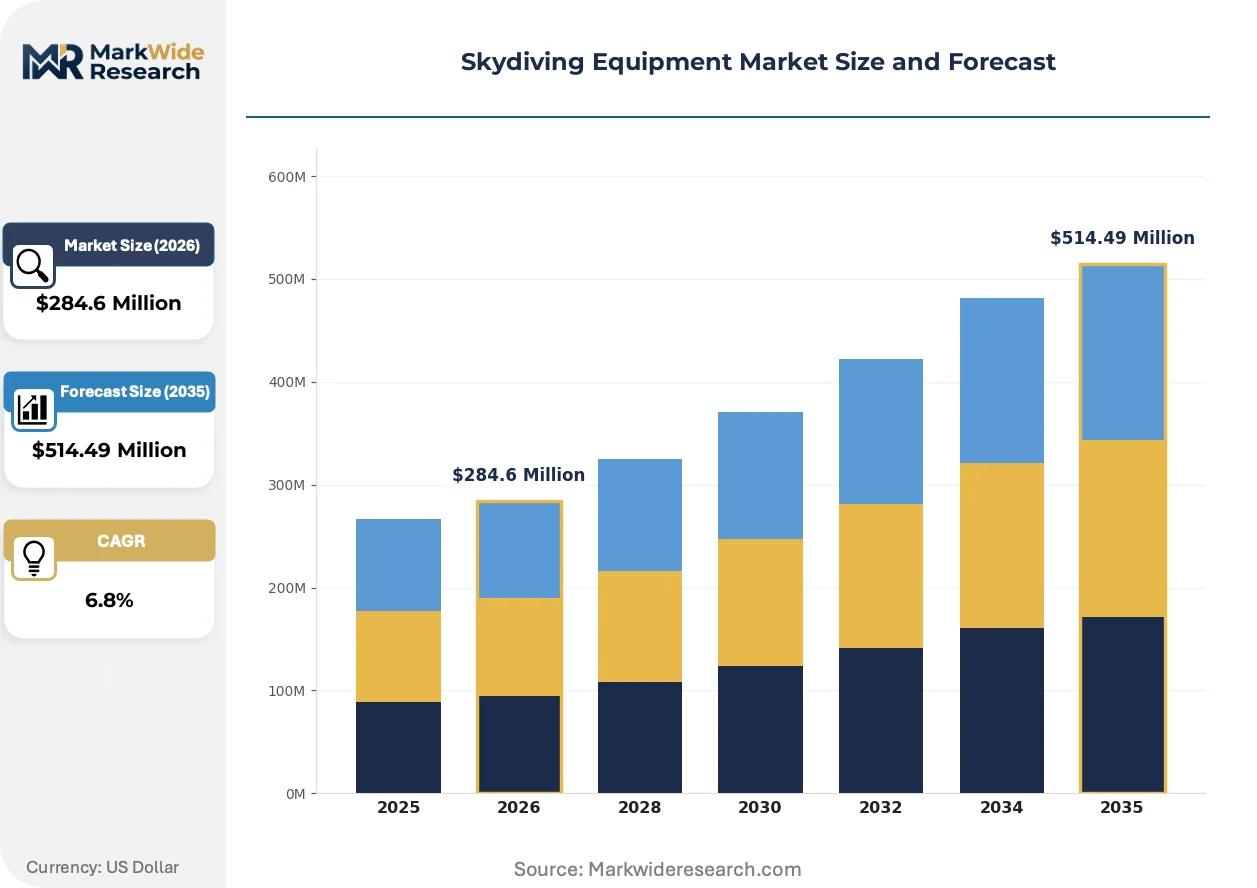
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parachutes, Altimeters, Harnesses, Helmets Application: Recreational, Military, Commercial, Competition End User: Professional Skydivers, Beginners, Military Personnel, Event Organizers Technology: Automatic Activation Devices, Aerial Video Systems, Wearable Tech, Safety Systems |
| Companies Covered | Phoenix Fly, OZONE GLIDERS LTD., Aerodyne Research LLC, Dudek Paragliders, Velocity Sports Equipment, Performance Designs, Sun Path Products Inc., Adrenalin Base, Apco Aviation Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skydiving Equipment Market Emerging Trajectories
Smart deployment systems and biometric integration are displacing mechanical-only safety architectures across both military and civilian procurement specifications, while regulatory scope expands into algorithmic decision-making protocols.
Ram-air canopy engineering is consolidating around proprietary airfoil architectures that optimize cell inflation sequencing for high-performance wingsuit applications. Special operations training facilities are adopting these systems at accelerated procurement cycles. The technology is consolidating vendor differentiation around aerodynamic intellectual property rather than manufacturing scale.
EASA CS-25 and CS-23 standards are tightening certification timelines for sensor-integrated parachute assemblies across European jurisdictions. Manufacturers must now document algorithmic reliability for automated deployment triggers alongside mechanical failure modes. Military application channels face the steepest compliance burden due to extended qualification testing requirements.
Civilian drop zones are fragmenting procurement across independent operators and experiential tourism platforms rather than consolidating under regional equipment lessors. Tandem jump volume aggregators in Florida are displacing traditional bulk purchase agreements with per-jump equipment rental models. This behavioral shift is most visible in Arizona, where tourism-dependent operators prioritize capital-light access over ownership.
Skydiving Equipment Market Segmentation
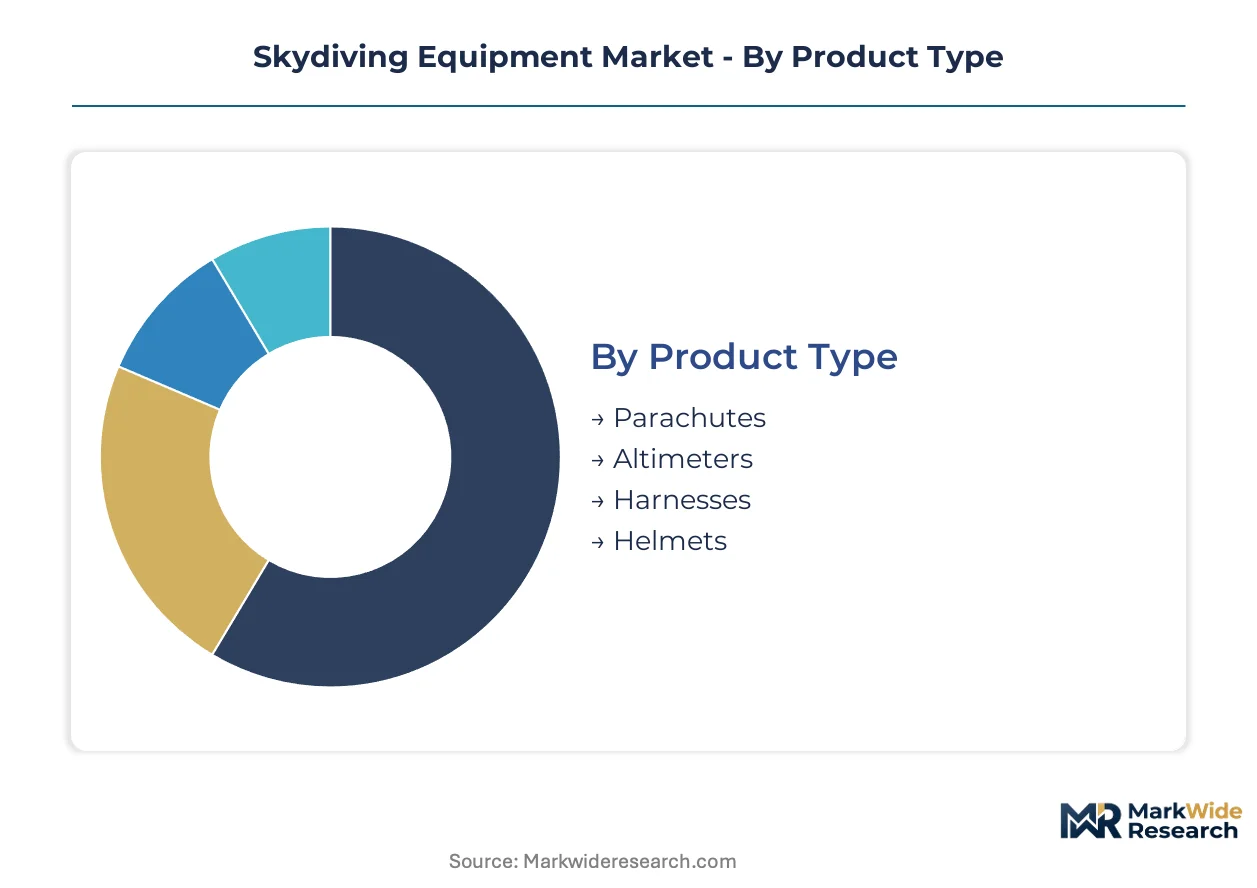
Skydiving equipment segmentation reflects divergent engineering requirements across civilian recreation and precision military operations. Procurement channels fragment by certification tier, with FAA TSO-C23d mandates driving replacement cycles in some categories while experiential tourism platforms reshape volume distribution in others.
Product Type:
Ram-air canopy engineering and container system architecture define performance differentiation across the equipment stack.
- Parachutes:Ram-air canopies constructed from zero-porosity ripstop nylon with calibrated cell inflation profiles dominate procurement volume. Replacement cycles tie directly to jump counts and mandatory 180-day reserve repack intervals, with military contracts in Florida and Arizona demanding extended qualification testing for tactical insertion missions.
- Altimeters:Barometric pressure differential instruments provide altitude awareness for freefall and canopy flight phases. Civilian drop zones in California cluster demand around digital units with integrated audible alerts, while competition-grade analog variants persist among precision canopy piloting specialists.
- Harnesses:Anthropometrically fitted assemblies distribute opening shock loads across the torso.
- Helmets:Impact-resistant shells with integrated communication mounts serve military training corridors.
Parachutes lead on scale; Altimeters lead on momentum as sensor integration accelerates.
Application:
End-use specifications diverge sharply between recreational experience delivery and mission-critical aerial operations.
- Recreational:Tandem jump packages and solo certification programs drive volume through independent operators and experiential tourism platforms. Arizona and Florida tourism corridors prioritize capital-light equipment rental models over ownership, fragmenting traditional procurement channels.
- Military:Precision aerial delivery systems for special operations training command premium pricing. NATO member state procurement concentrates in California, Arizona, and Florida facilities, with custom specification requirements extending vendor qualification timelines.
- Commercial:Professional instruction and equipment leasing operations serve drop zone infrastructure.
- Competition:Canopy piloting and formation skydiving events demand performance-optimized configurations.
Military leads on pricing premium; Recreational leads on volume expansion.
End User:
Skill certification tiers and operational authority determine equipment specification complexity and procurement authority.
- Professional Skydivers:FAA-licensed instructors and demonstration jumpers require competition-grade canopy systems with proprietary airfoil architectures. These users command direct manufacturer relationships and drive innovation adoption for wingsuit applications.
- Military Personnel:Special operations forces and tactical aircrews utilize precision aerial delivery systems with extended qualification protocols.
- Beginners:Tandem students and accelerated freefall candidates access equipment through instructor-mediated rental programs.
- Event Organizers:Competition hosts and exhibition coordinators procure specialized demonstration rigs.
Professional Skydivers lead on specification influence; Military Personnel leads on contract value concentration.
Technology:
Regulatory mandates and safety protocol evolution are displacing mechanical-only architectures with sensor-integrated systems.
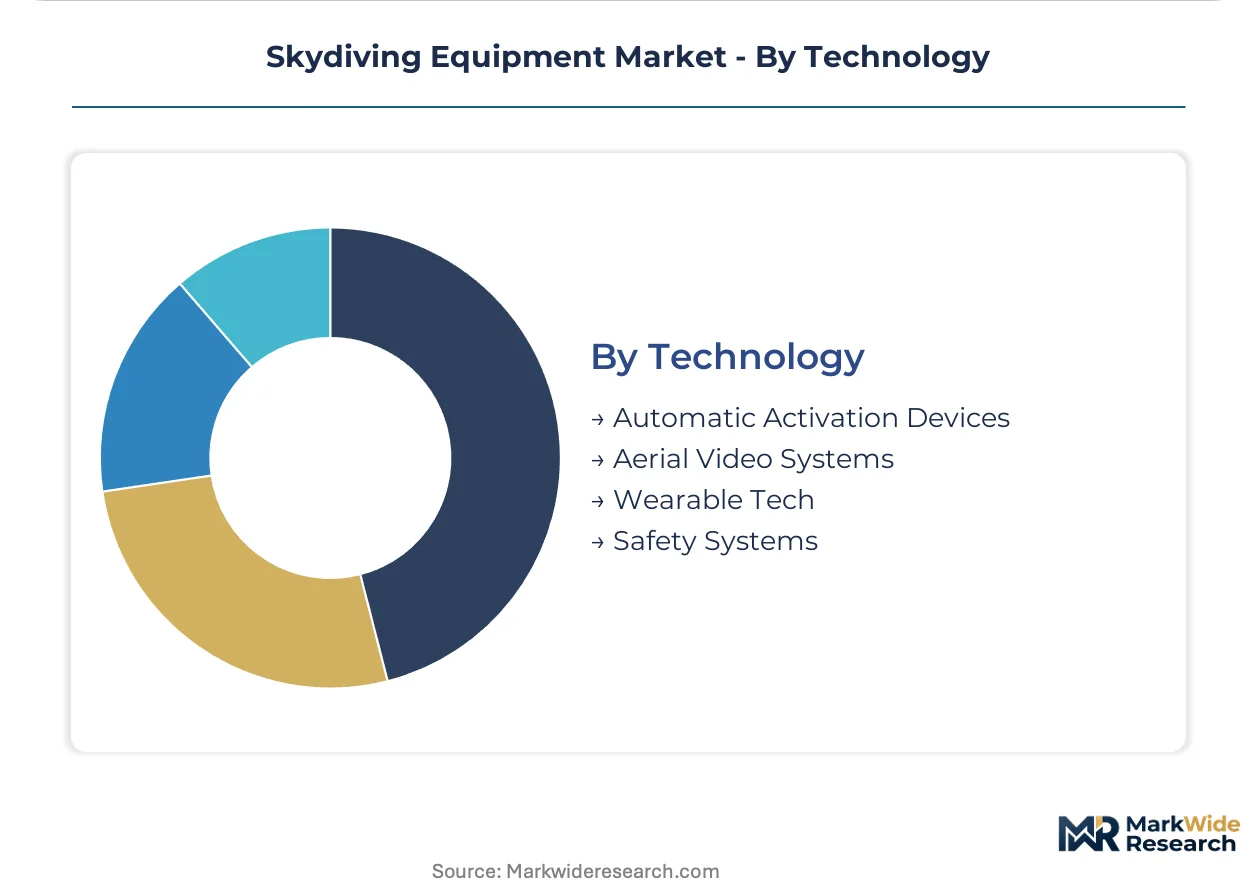
- Automatic Activation Devices:Barometric and inertial sensors trigger reserve deployment when altitude and velocity thresholds indicate main canopy failure. FAA TSO-C23d certification requirements are accelerating replacement cycles across US drop zones as compliance deadlines approach.
- Wearable Tech:Biometric monitors and GPS tracking systems integrate with harness assemblies. EU AI Act compliance friction is emerging for algorithmic decision-making protocols as regulatory scope expands beyond mechanical certification.
- Aerial Video Systems:Helmet and wrist-mounted cameras capture freefall and canopy flight footage.
- Safety Systems:RSLs, AADs, and reserve static lines provide redundant deployment safeguards.
Automatic Activation Devices lead on regulatory tailwinds; Wearable Tech leads on convergence potential with biometric monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States military procurement outpaces European civilian volume, while Asia-Pacific training infrastructure remains nascent. Procurement patterns diverge sharply between NATO defense corridors and experiential tourism clusters. Regulatory frameworks in each jurisdiction reshape equipment certification timelines and vendor qualification protocols.
United States
Special operations training facilities in Florida, California, and Arizona drive precision aerial delivery system demand. FAA TSO-C23d mandates accelerate replacement cycles for reserve parachute systems. Drop zones in the Southwest cluster around Phoenix and Tucson, where independent operators fragment procurement through per-jump rental models.
Germany
Bundeswehr special forces procurement concentrates on ram-air canopy systems for tactical insertion missions. EASA CS-25 and CS-23 standards govern sensor-integrated parachute assembly certification. Manufacturing competence clusters in Bavaria and Baden-Württemberg, where aerospace suppliers adapt commercial aviation protocols to descent systems.
France
Armée de l'Air et de l'Espace training programs sustain demand for extended qualification testing protocols. ANSM and CNIL oversight extends to biometric-wearable convergence products under EU AI Act emerging scopes. The Provence-Alpes-Côte d'Azur corridor hosts drop zone infrastructure serving both military and civilian jumpers.
United Kingdom
Royal Air Force and Army Air Corps procurement flows through Ministry of Defence consolidated vendor frameworks. UK CAA implements parallel airworthiness standards to FAA TSO-C23d for reserve system mandates. Civilian training centers concentrate in East Anglia and the Southwest, where tandem jump tourism aggregates volume.
Australia
Civil Aviation Safety Authority certification requirements align with ISO 12401 baseline standards for personal descent equipment. Recreational skydiving demand concentrates in Queensland and New South Wales, where coastal drop zones serve tourism markets. Military procurement remains limited compared to NATO counterparts, constraining premium pricing capture.
Skydiving Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-tiered procurement channels. Market structure consolidates around FAA-certified manufacturers serving military contracts while fragmenting across independent rigging technicians and regional drop zone operators. Three archetypes dominate: precision canopy engineers with proprietary airfoil intellectual property, integrated harness-container system fabricators, and military-contract anchor vendors with extended qualification protocols. Competitive moves center on M&A consolidation of rigging service networks and technology licensing for sensor-integrated deployment systems.
Among canopy engineering specialists, Performance Designs and Aerodyne Research LLC exemplify divergent strategic positioning. Performance Designs occupies the competition-grade tier through proprietary architectural approaches. Aerodyne Research LLC anchors military-contract flows with certification-heavy manufacturing protocols. Sun Path Products Inc. represents the integrated-system archetype, reducing complexity for professional user segments.
| Leading Market Players |
|---|
| Phoenix Fly |
| OZONE GLIDERS LTD. |
| Aerodyne Research LLC |
| Dudek Paragliders |
| Velocity Sports Equipment |
| Performance Designs |
| Sun Path Products Inc. |
| Adrenalin Base |
| Apco Aviation Ltd. |
| Others |
Supply Flow & Price Mechanics
Master rigger certification scarcity in the Southwest United States widens labor-cost differentials between FAA-certified technicians and independent rigging operators, compressing margins on standard-tier equipment while sustaining premium pricing for military-grade assemblies with extended qualification protocols.
Pricing Analysis
Capacity additions in Arizona and California are reshaping price floors for tandem jump rental fleets as experiential tourism platforms aggregate per-jump demand. Three-tier pricing structure across premium, standard, and economy levels separates military specification systems from competition-grade canopy architectures and recreational rental inventory. Price differentiation rests on FAA TSO-C23d certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because carbon fiber composite input volatility feeds through container system manufacturers. Military procurement agencies exhibit the least price sensitivity; independent drop zone operators in tourism corridors show the highest.
Supply Chain Analysis
Dual-sourcing requirements from NATO procurement agencies mandate multi-supplier qualification for ram-air canopy assemblies, fragmenting volume across FAA-certified manufacturers. Geographic supply concentration centers on the United States, Germany, and France for precision aerial delivery systems. Raw material dependencies draw from zero-porosity ripstop nylon, aerospace-grade carbon fiber composites, and barometric sensor components. Single-source vulnerability persists in specialized harness-container integration where Sun Path Products Inc. anchors proprietary system architectures. Distribution runs through military contract channels, certified rigging technician networks, and direct-to-drop-zone equipment lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skydiving equipment market functions as a stable compounder, with mandatory 180-day reserve repack cycles and FAA TSO-C23d compliance deadlines generating predictable replacement revenue across military and civilian channels.
For Market Incumbents: Anchor military contract flows through accelerated FAA certification investment for sensor-integrated automatic activation devices, countering vendor concentration risk from emerging biometric-wearable convergence vendors. Deepen backward integration into zero-porosity ripstop nylon weaving capacity to offset aerospace-grade material pricing volatility. Prioritize channel control over independent rigging technician networks in Arizona and Florida training corridors. For New Entrants and Emerging Players: Sensor-integrated wearable tech with EU AI Act compliance pathways offers the most penetrable wedge, targeting the biometric-wearable convergence white space where algorithmic reliability documentation exceeds incumbent mechanical certification capabilities. Pursue white-space acquisition in reserve repack service unbundling, establishing certified technician networks outside manufacturer-controlled channels. Go-to-market through experiential tourism platform partnerships in California and Arizona, bypassing traditional bulk procurement relationships. For Investors and Strategic Acquirers: Defense contractors with special operations training mandates are the most active acquirer in this space, consolidating precision aerial delivery system vendors under extended qualification protocols. Long-term viability hinges on regulatory tailwinds from FAA and EASA mandating redundant deployment safeguards. Target acquisition archetype: FAA-certified manufacturers with proprietary airfoil intellectual property and established military contract flows. Watch for EU AI Act enforcement actions against sensor-integrated wearable tech as inflection indicator for compliance-driven vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment Acceleration | FAA TSO-C23d compliance timelines compress vendor qualification windows for reserve system mandates. |
| Biometric-Wearable Integration | EU AI Act algorithmic reliability documentation reshapes competitive barriers beyond mechanical certification. |
| Rigging Service Network Consolidation | Master rigger certification scarcity enables recurring revenue capture through certified technician acquisition. |
| Backward Integration into Materials | Carbon fiber composite input volatility drives captive supply of aerospace-grade container components. |
| Experiential Tourism Platform Partnership | Per-jump rental models in Arizona and California bypass traditional equipment ownership channels. |
Methodological Framework
Direct dialogue with FAA-certified master riggers, military procurement officers at special operations training facilities, drop zone operators in Florida and Arizona, and canopy engineering specialists grounded qualitative findings. Secondary validation drew from FAA Technical Standard Order filings, EASA CS-25 and CS-23 certification databases, NATO precision aerial delivery system procurement records, and ISO 12401 baseline standard documentation. Bottom-up equipment shipment tracking and top-down defense budget allocation analysis enabled triangulation.
Bottom-up modeling segmented volume across parachute systems, automatic activation devices, altimeters, and harness-container assemblies, with cross-validation against top-down military procurement flows and civilian drop zone infrastructure counts. Segmentation dimensions included product type, application channel, end-user certification tier, and technology integration level. CAGRs were derived from replacement cycle analysis tied to jump counts, reserve repack mandates, and regulatory compliance deadlines. Industry-specific forecast inputs incorporated carbon fiber composite pricing indices and master rigger certification pipeline data.
The model holds under steady FAA and EASA regulatory enforcement; deviation in EU AI Act implementation scope or NATO special operations training budget allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Tennis Pole Market
Sports Equipment
Europe Stand-Up Paddleboard Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Sports Fishing Equipment Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Squash Equipment Market