
 Gym Shoes Market | 2026-2036
Gym Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Gym Shoes Market Outlook
ISO 14001 environmental management certification is redrawing competitive boundaries in gym shoes manufacturing, raising capital barriers for smaller suppliers. Nike, Inc. leverages its vertically controlled Asian manufacturing network to sustain margin capture across premium performance tiers. Adidas AG anchors its position through in-house production of Boost midsole compounds, while ASICS Corporation specializes in gait-analysis-driven footwear architectures for dedicated runners.
Gym shoes are engineered footwear systems combining ethylene-vinyl acetate (EVA) or thermoplastic polyurethane (TPU) midsole cushioning with engineered mesh uppers and carbon rubber outsoles, designed to attenuate impact forces and stabilize biomechanical motion during repetitive athletic movements. Running footwear commands the largest revenue pool within footwear type segmentation, though cross-training designs are gaining fastest among hybrid fitness practitioners. Material segmentation shows synthetic compounds overtaking leather in unit volume, as knit uppers and welded overlays reduce pattern waste and labor intensity in final assembly.
REACH chemical restrictions in Europe and California's Proposition 65 disclosure requirements in the United States are tightening permissible substance thresholds for adhesives, dyes, and synthetic leather treatments, forcing reformulation investments across tier-one and tier-two suppliers. China's GB standards for footwear safety and the EU's impending Digital Product Passport regulations will add traceability compliance costs. Stakeholders must weigh near-term margin compression from dual regulatory compliance against longer-term brand equity from verified sustainability credentials.
Market Dynamics
Material transitions toward bio-based synthetics and recycled rubber compounds are compressing legacy supply chains while elevating capital requirements for tier-two manufacturers seeking ISO 14001 certification.
Growth Catalysts
- EU Green Deal mandates:Sustainability requirements under the EU Green Deal are compelling footwear brands to reformulate midsole compounds and outsole materials, creating first-mover advantages for certified suppliers.
- China domestic consumption surge:Rising participation in organized fitness programs among recreational athletes in China is expanding addressable demand beyond competitive runners into casual training segments.
- Fujian manufacturing cluster density:Concentrated domestic sportswear manufacturing in Fujian province is enabling rapid prototyping cycles and shortening lead times for regional brands.
Market Restraints
- Petrochemical feedstock volatility:EVA and TPU resin prices fluctuate with crude oil derivatives, compressing margin predictability for midsole compounders.
- REACH chemical thresholds:ECHA restrictions on adhesives and synthetic leather treatments force reformulation investments that disproportionately burden smaller tier-two suppliers.
- Digital Product Passport compliance costs:Upcoming EU traceability requirements will add per-unit documentation expenses across entire production runs.
Strategic Opportunities
- India organized fitness expansion:Underpenetrated gym culture in tier-two Indian cities offers white-space entry for hybrid cross-training footwear positioned below premium running tiers.
- GB standards alignment:China's evolving footwear safety regulations create openings for domestic brands to capture share from import-dependent competitors.
- Knit upper automation:Computerized knitting convergence with welded overlay technology is reducing pattern waste and enabling micro-factory distributed production models.
Industry Challenges
- Biomechanical engineering talent scarcity:Gait-analysis specialization required for performance running architectures faces limited university pipeline output.
- Dual certification timeline compression:Simultaneous compliance with California Proposition 65 and REACH substance restrictions strains R&D bandwidth.
- Legacy adhesive system replacement:Water-based bonding chemistry integration with existing vulcanization equipment requires substantial line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gym Shoes Market |
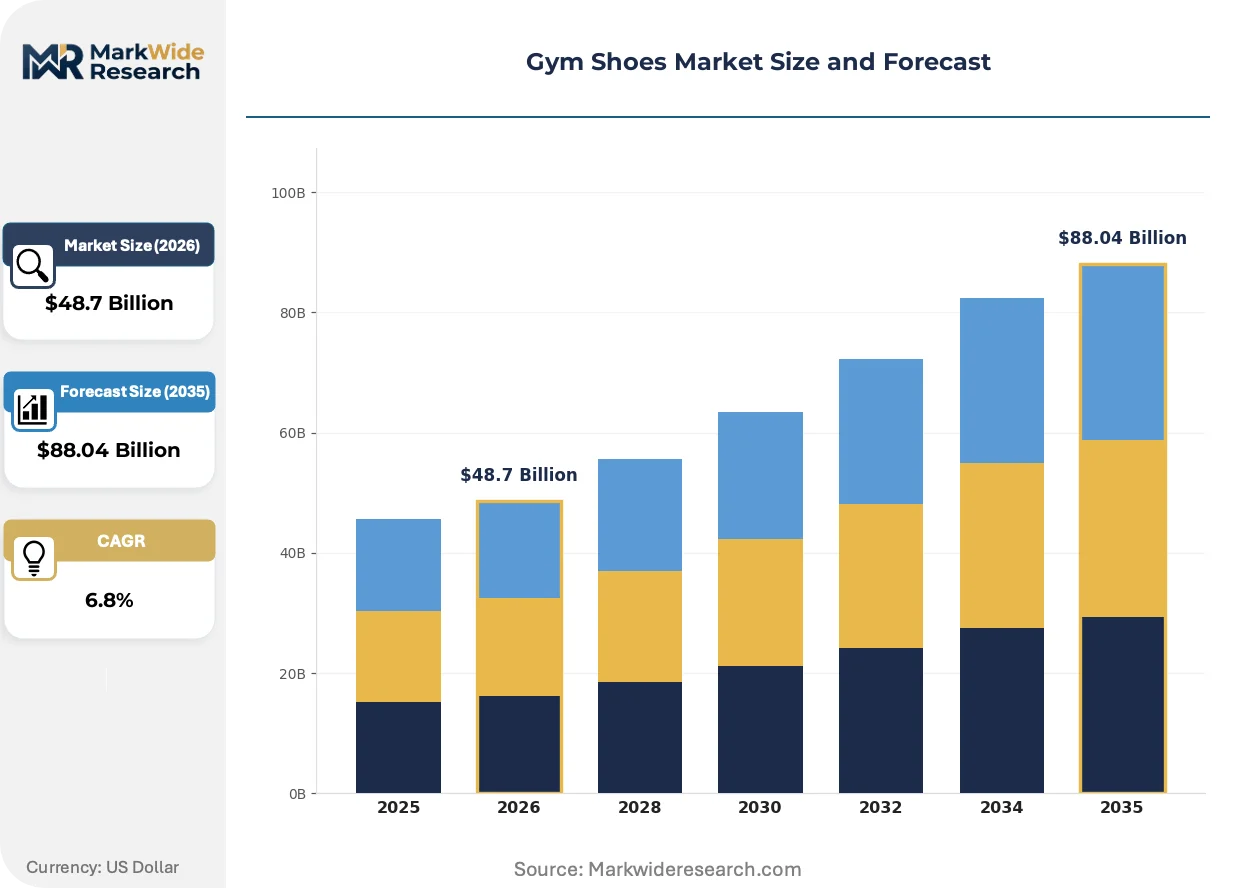
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Footwear Type: Cross-Training, Running, Basketball, Walking Material: Mesh, Leather, Synthetic, Rubber End User: Men, Women, Kids, Athletes Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | Nike, Inc., Adidas AG, ASICS Corporation, New Balance Athletics, Inc., Puma SE, Skechers USA, Inc., Under Armour, Inc., Brooks Sports, Inc., On Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gym Shoes Market Strategic Shifts
Active reshaping of the gym shoes market centers on three vectors: material science substitution, regulatory traceability mandates, and procurement model evolution toward sustainability-verified supply tiers.
Engineered knit uppers constructed from recycled polyester filament yarns are supplanting traditional cut-and-sew synthetic leather constructions in volume production. Dedicated runners and hybrid fitness practitioners are adopting these designs at accelerating rates due to breathability and weight advantages. This material shift is compressing pattern-making labor requirements while elevating capital barriers for suppliers lacking computerized knitting infrastructure.
REACH chemical restrictions administered by ECHA are tightening permissible substance thresholds for dyes, adhesives, and synthetic leather treatments across European supply chains. Footwear manufacturers must now maintain substance documentation through full material hierarchies. Running footwear positioned for EU distribution faces the steepest compliance burden, with brands accelerating water-based adhesive transitions to preempt enforcement actions.
Certification-driven procurement preferences are elevating ISO 14001 and verified recycled content claims into standard vendor qualification criteria. Sporting goods retailers in Germany and the Netherlands are unbundling sustainability credentials from product marketing into standalone procurement filters. This behavioral shift is most visible among multi-brand athletic specialty chains, where verified supply chain transparency now gates shelf access ahead of pure performance metrics.
Gym Shoes Market Segmentation
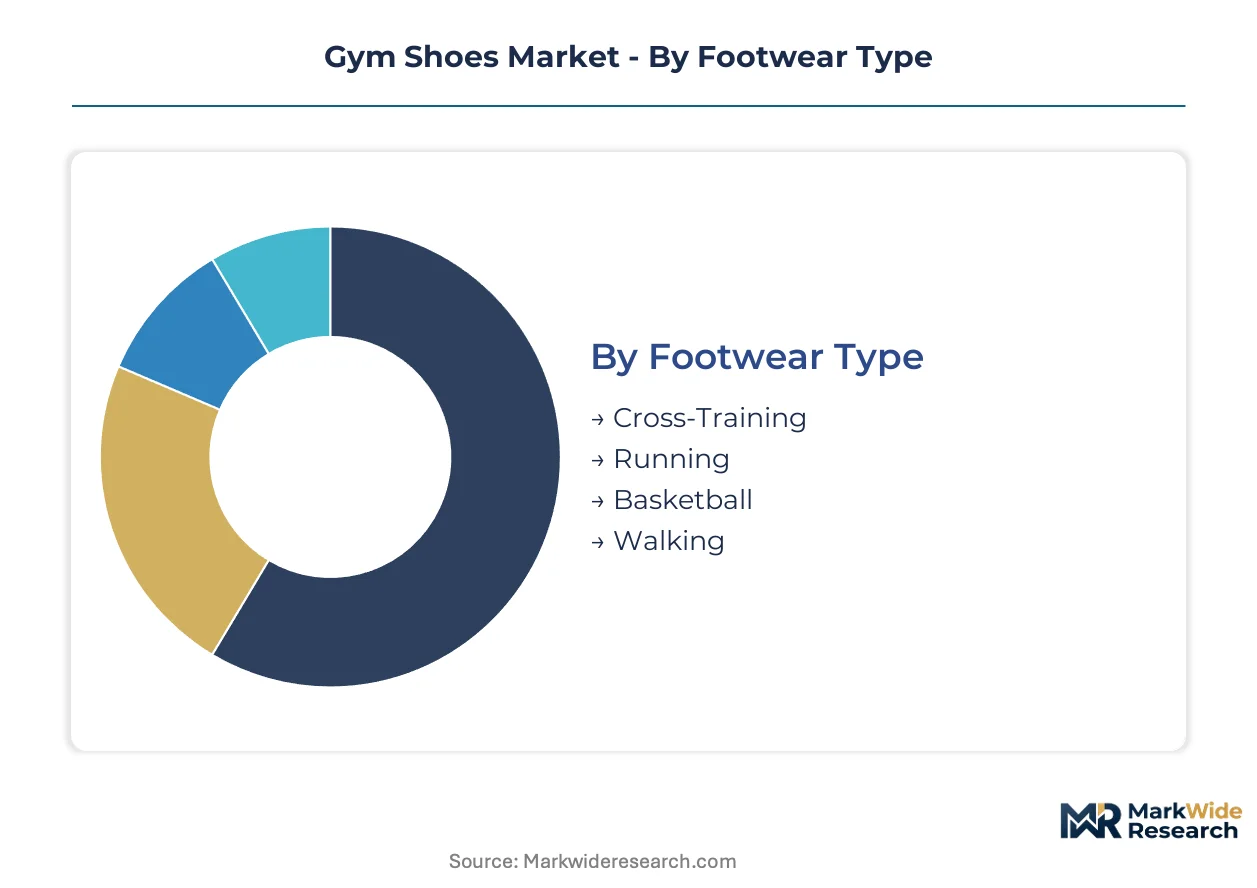
Gym shoes segmentation reflects divergent channel economics and manufacturing complexity. Performance tiers demand specialized biomechanical engineering, while casual segments prioritize cost-efficient material platforms and mass retail placement.
Footwear Type:
Channel-mix patterns separate premium performance from volume casual: specialty athletic retailers stock technical running and cross-training designs, while department stores and supermarkets carry walking and basketball SKUs at lower price points.
- Running:Engineered with EVA or TPU midsole cushioning systems and carbon rubber outsoles calibrated for repetitive impact attenuation. Demand concentrates among dedicated runners in China and Germany, where gait-analysis fitting services drive specialty store traffic and premium price acceptance.
- Cross-Training:Hybrid stability platforms combining lateral support with forefoot flexibility for multi-modal fitness practitioners. This segment is expanding most quickly in India's tier-two cities, where organized gym culture penetration lags metropolitan centers but growth rates exceed established markets.
- Basketball:High-top collar constructions with herringbone traction patterns designed for court surface grip and ankle stabilization. Volume flows through sporting goods chains and team equipment distributors.
- Walking:Simplified cushioning architectures prioritizing all-day comfort over performance metrics. Mass retail placement in supermarkets and value department stores dominates distribution.
By volume, Walking leads through mass-market penetration. By growth pace, Cross-Training is ahead.
Material:
Cost tiers stratify sharply: knit synthetics and mesh command premium positioning, while leather and basic rubber compounds anchor economy segments with thinner margin profiles.
- Mesh:Engineered polyester or nylon filament constructions delivering breathability and weight reduction through computerized knitting. Fujian province manufacturers dominate supply, leveraging automated upper production to compress labor content.
- Synthetic:Thermoplastic polyurethane overlays and welded film constructions replacing stitched leather assemblies. REACH chemical restrictions under ECHA oversight are forcing adhesive reformulation investments that elevate entry barriers for uncertified suppliers.
- Leather:Traditional full-grain or corrected-grain hides requiring cut-and-sew pattern labor. Demand is contracting in performance tiers as knit alternatives displace heritage constructions.
- Rubber:Carbon black reinforced outsole compounds providing abrasion resistance and traction. Recycled content mandates under EU Green Deal specifications are reshaping compounder qualification requirements.
Mesh commands the highest unit margins. Synthetic materials are climbing the fastest as brands accelerate sustainability transitions.
End User:
Customer-type concentration varies by geography: men's technical performance drives revenue in established European markets, while women's casual training and children's replacement cycles dominate volume in emerging consumption centers.
- Men:Technical performance specifications with gait-analysis customization in running categories. Specialty store channel concentration with higher average transaction values.
- Women:Aesthetic-functional hybrid designs emphasizing colorway rotation and studio-to-street versatility. Online retail channels capture disproportionate share through direct-to-consumer subscription models.
- Kids:Rapid size-turnover categories with durability trade-offs against growth-phase replacement frequency. Supermarket and value department store placement dominates.
- Athletes:Elite-tier product placement with sponsorship-driven specification influence. Limited volume but outsized marketing leverage and technology validation signaling.
Men's segments generate highest revenue per unit. Women's categories are expanding most quickly through digital channel migration.
Distribution Channel:
Supply concentration dictates margin capture: vertically integrated brands extract premium through controlled online channels, while wholesale-dependent competitors cede margin to multi-brand specialty retailers.
- Online Retail:Direct-to-consumer platforms enabling customization interfaces and subscription replenishment models. Nike and Adidas deploy proprietary apps with gait-scanning integration to reduce returns and elevate conversion.
- Specialty Stores:Foot Locker and regional athletic chains providing fitting services and brand-exclusive colorways. Shelf access gates on sustainability certification compliance under tightening procurement filters in Germany and the Netherlands.
- Department Stores:Mid-tier brand placement with seasonal promotional calendars compressing margin predictability. Inventory risk shifts to retailers through consignment arrangements.
- Supermarkets:Entry-price-point volume placement with minimal service content and high SKU velocity requirements. Private label penetration is elevating competitive pressure on branded suppliers.
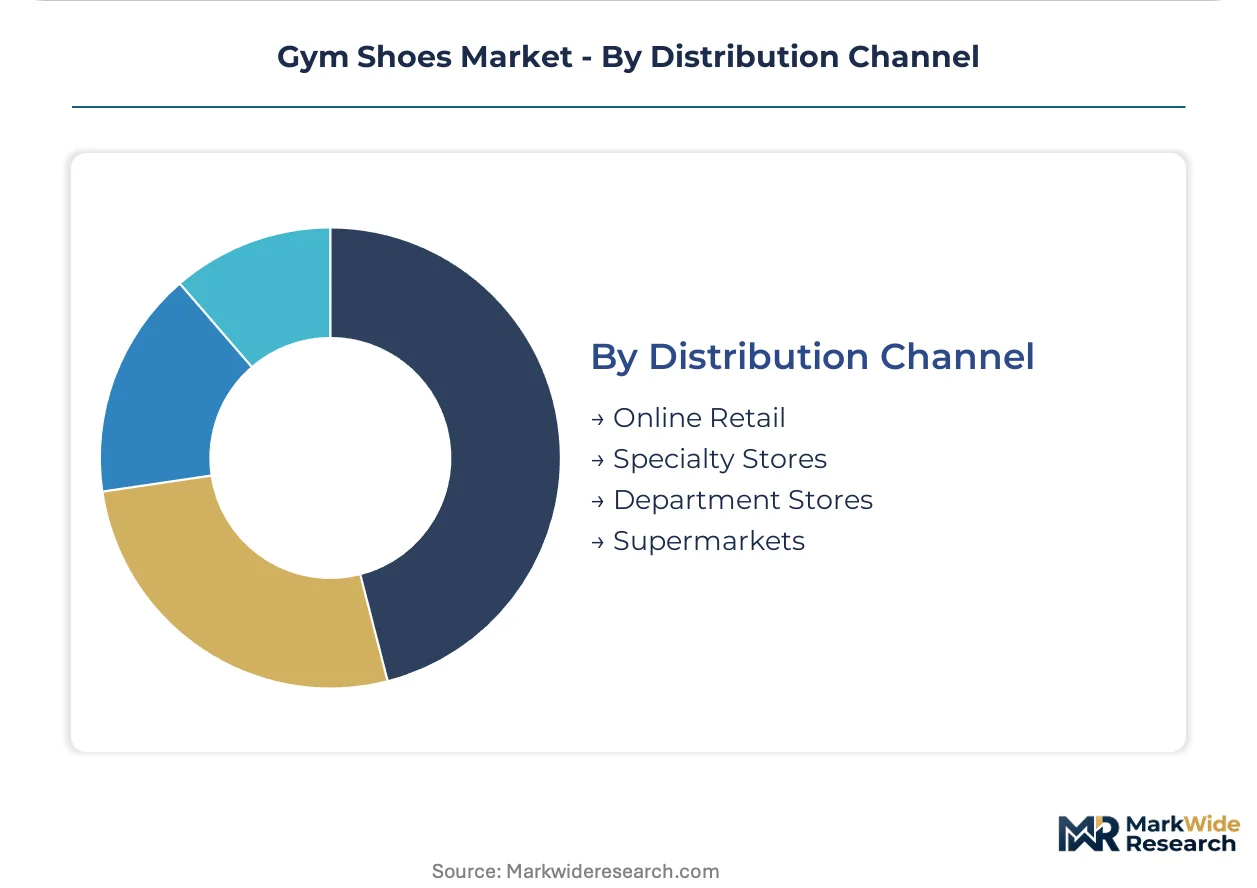
Specialty Stores lead by revenue concentration. Online Retail is gaining share fastest through post-purchase behavioral data monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elite marathon runners and recreational fitness practitioners concentrate demand in Germany, China, and the United States, while hybrid gym-goers in India and Brazil are expanding the casual training segment.
Germany
Specialty running retailers in Berlin and Munich drive premium footwear turnover through gait-analysis fitting services. ECHA REACH enforcement on adhesive formulations compels midsole compounders to maintain substance documentation hierarchies. Bavaria's sporting goods manufacturing corridor hosts sustainability-certified suppliers aligned with EU Green Deal procurement filters.
China
Domestic sportswear consumption in Shanghai and Beijing is shifting from competitive running toward studio fitness and cross-training categories. GB standards for footwear safety are tightening chemical thresholds and traceability requirements for imported materials. Fujian province manufacturing clusters enable rapid prototyping cycles that compress lead times for regional brands competing against multinational incumbents.
United States
Digital-native fitness communities in California and New York Metro sustain direct-to-consumer replenishment models for technical running designs. California Proposition 65 disclosure requirements for synthetic leather treatments and dyes elevate compliance documentation burdens. The Pacific Northwest hosts biomechanical engineering talent pools that supply gait-research capabilities to performance footwear developers.
India
Organized gym culture penetration in Maharashtra and Karnataka is accelerating fastest among tier-two cities where hybrid cross-training footwear occupies white-space positioning below premium running tiers. BIS certification alignment with evolving footwear safety protocols creates procurement advantages for domestic manufacturers. Tamil Nadu's leather processing heritage is converting toward synthetic upper production to serve export-oriented sportswear contracts.
Brazil
Recreational running participation in São Paulo and Rio de Janeiro is expanding the addressable base beyond competitive athletes into mass-market training segments. ANVISA pharmaceutical-adjacent chemical oversight influences imported adhesive and dye substance approvals. Minas Gerais industrial zones are developing recycled rubber compounding capabilities to serve regional footwear brands with EU-bound export ambitions.
Gym Shoes Market Competitive Environment
Player mix skews toward vertically integrated multinational sportswear conglomerates with captive Asian manufacturing networks and specialized biomechanical engineering boutiques. Structure concentrates around three archetypes: scale-driven full-line suppliers controlling end-to-end production, technology-focused midsole compound specialists, and regional challengers leveraging domestic manufacturing clusters for speed-to-market. Dominant competitive moves include backward integration into recycled material feedstocks and strategic partnerships with automated knitting equipment vendors.
Within the scale-driven tier, Nike, Inc. and Adidas AG exemplify archetypes of vertically controlled supply networks that compress lead times and sustain margin capture across premium performance tiers. ASICS Corporation occupies a position among biomechanical engineering specialists, anchoring the gait-analysis-driven footwear architecture segment for dedicated runners. These three entities represent the competitive spectrum from mass-market vertical integration to technical specialization.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| ASICS Corporation |
| New Balance Athletics, Inc. |
| Puma SE |
| Skechers USA, Inc. |
| Under Armour, Inc. |
| Brooks Sports, Inc. |
| On Holding AG |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day production lead times from Fujian province manufacturing clusters concentrate pricing power with vertically integrated brands capable of compressing inventory cycles, while smaller tier-two suppliers absorb margin erosion from dual regulatory compliance burdens.
Pricing Analysis
Cost-plus contracts indexed to ethylene-vinyl acetate resin benchmarks dominate midsole compound procurement, with premium tiers capturing value through ISO 14001 certification and gait-analysis customization while economy segments face acute price sensitivity from supermarket private-label competition. Pricing stratifies across premium performance, standard training, and economy walking tiers, with differentiation driven by certification grade and brand equity. Cost compression in the economy tier intensifies because recycled content mandates elevate material input expenses without corresponding price acceptance. Specialty running retailers exhibit lowest price sensitivity due to fitting-service loyalty, while mass-market supermarket buyers demand maximum unit velocity at entry price points.
Supply Chain Analysis
Just-in-time inventory strategies prevail among vertically integrated multinationals with captive Asian manufacturing networks, whereas regional challengers maintain strategic stockpiles of TPU and carbon rubber compounds to buffer petrochemical feedstock volatility. Supply concentrates in China, Vietnam, and Indonesia, with midsole cushioning systems and engineered knit uppers drawing from specialized chemical and textile inputs. Single-source vulnerability in Fujian province automated knitting infrastructure poses concentrated disruption risk. Distribution runs through direct-to-consumer platforms and multi-brand specialty chains, with sustainability certification increasingly gating shelf access in German and Dutch procurement filters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
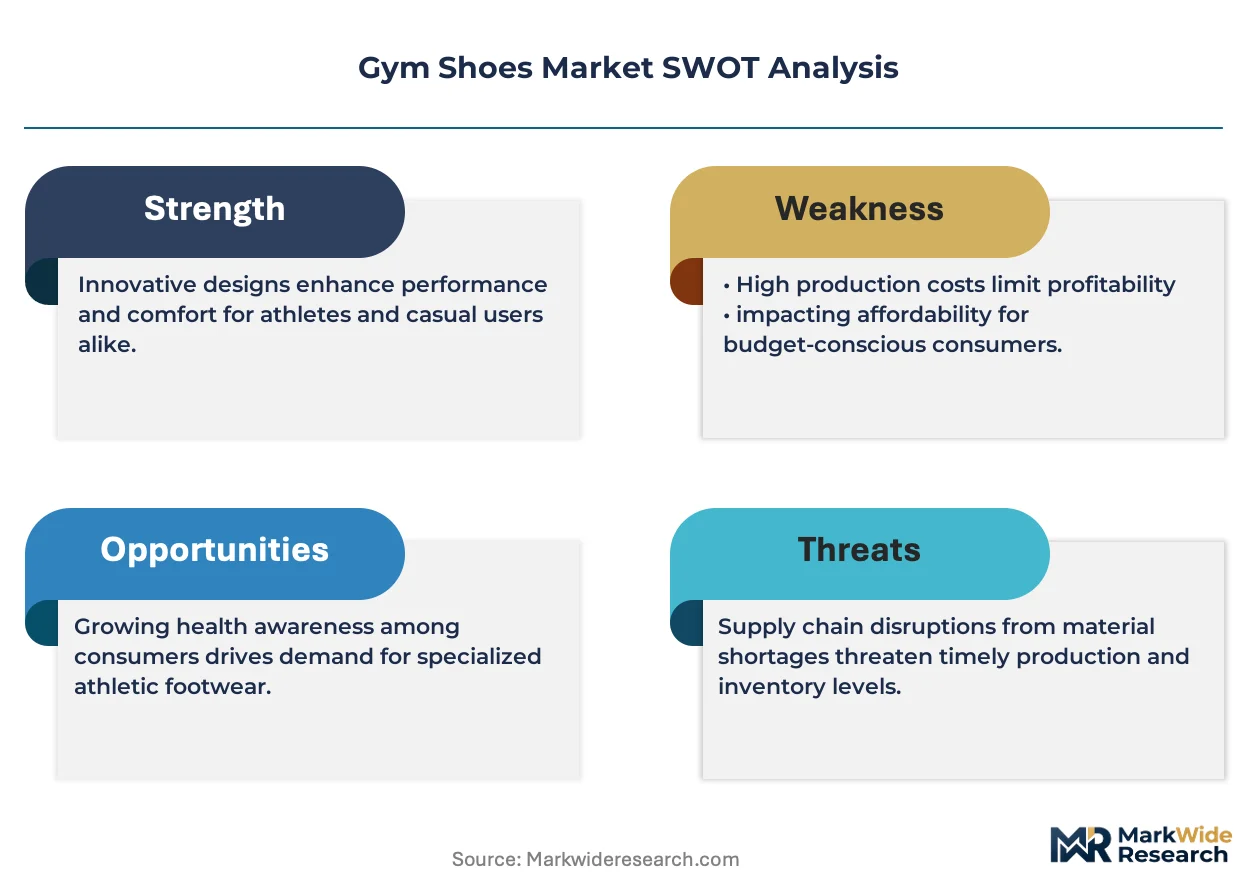
This market requires substitution defense against lifestyle footwear brands repurposing casual designs for light training occasions, threatening technical performance positioning.
For Market Incumbents: Fortify biomechanical engineering capabilities through Pacific Northwest talent acquisition and accelerate water-based adhesive transitions to preempt REACH enforcement actions. Deepen backward integration into recycled polyester feedstocks to secure supply tiers ahead of EU Green Deal mandates. ISO 14001 certification must expand from flagship facilities to full manufacturing networks to defend procurement relationships with sustainability-filtering retailers. For New Entrants and Emerging Players: ISO 14001 certification fast-tracks unlock shelf access with German and Dutch multi-brand athletic chains where verified supply chain transparency now gates distribution ahead of pure performance metrics. Target India's tier-two cities for hybrid cross-training footwear positioned below premium running tiers, where organized gym culture penetration lags but growth rates exceed established markets. Deploy computerized knitting partnerships with Fujian equipment vendors to compress pattern-making labor and enable rapid prototyping cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate sportswear divisions lacking sustainability certification alignment, where stranded assets face procurement exclusion from tightening retailer filters. Five-to-ten year viability hinges on material science substitution capabilities and regulatory traceability infrastructure rather than brand heritage alone. Monitor ECHA enforcement patterns on adhesive formulations as inflection indicator for compliance cost acceleration and tier-two supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Certification Program | ISO 14001 alignment with EU Green Deal procurement filters secures shelf access with German specialty retailers. |
| Backward Integration into Recycled Feedstocks | Captive supply of recycled polyester filament yarns insulates margin from virgin petrochemical price volatility. |
| Automated Knitting Infrastructure Partnership | Computerized upper production with Fujian equipment vendors compresses labor content and pattern waste. |
| Water-Based Adhesive Transition | Reformulation investment ahead of REACH enforcement preempts supply disruption and compliance penalties. |
| Direct-to-Consumer Platform Expansion | Proprietary apps with gait-scanning integration reduce return rates and elevate conversion in technical running tiers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, SEC footwear sector filings, and EU regulatory enforcement databases, combining structured interviews with brand supply chain directors, specialty retailer procurement managers, and midsole compounder technical leads. Bottom-up unit economics triangulate against top-down market sizing from trade association data and production cluster surveys across Fujian province manufacturing zones.
Segmentation dimensions modeled span footwear type, material platform, end-user demographic, and distribution channel, with value projections derived from pricing tier analysis and volume assumptions tied to fitness participation rates across the analysis window. CAGRs incorporate input cost trajectories for EVA and TPU resins, regulatory compliance cost buildups, and channel-mix shifts toward direct-to-consumer platforms.
Underlying assumptions cover sustained EU Green Deal implementation trajectory and China domestic consumption growth, with deviation risk concentrated in petrochemical feedstock volatility and REACH enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Volleyball Shoes Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Global Spikeball Equipment Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Mini Balance Beam Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
BMX Bikes Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Rowing Oars Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Basketball Shooting Machine Market