
 Global Artificial Intelligence (AI) Software Market | 2026-2036
Global Artificial Intelligence (AI) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence (AI) Software Market Foresight
Modular API-first bundling is restructuring how enterprises procure AI capabilities, shifting buyers from monolithic suites toward composable microservices. Microsoft leverages its cloud infrastructure to anchor enterprise distribution of these modular tools. NVIDIA sustains dominance in training infrastructure through its specialized GPU architectures. Google differentiates via tight integration between its foundation models and consumer-facing application layers.
Artificial intelligence software encompasses programs that employ statistical learning algorithms, neural network architectures, and optimization routines to perform tasks requiring pattern recognition, prediction, or autonomous decision-making without explicit rule-based programming. These systems process structured and unstructured data through tensor operations at scale, serving industrial purposes from automated quality inspection to real-time risk scoring. Cloud-based deployment leads in revenue contribution due to elastic compute provisioning, while edge deployment represents the fastest-expanding configuration as latency-sensitive manufacturing and autonomous vehicle applications multiply. Machine learning platforms capture the deepest margin pools because they lock in data pipelines and model development workflows that resist switching.
The EU AI Act, FDA guidance on AI-enabled medical devices, and China's SAMR algorithmic recommendation provisions collectively reshape product standards and market access conditions across three continents. Compliance with these frameworks now determines which vendors qualify for public-sector procurement and regulated industry deployments. Stakeholders must monitor divergence between risk-classification schemes as this fragmentation threatens interoperability and complicates multinational rollout strategies.
Market Dynamics
Modular API-first bundling is restructuring how enterprises procure AI capabilities, shifting buyers from monolithic suites toward composable microservices that integrate through standardized interfaces.
Growth Catalysts
- Healthcare diagnostic imaging:FDA clearance pathways for AI-enabled medical devices are accelerating hospital procurement cycles for radiology and pathology applications.
- EU AI Act compliance demand:High-risk algorithmic system classifications are forcing regulated industries to upgrade software stacks, creating replacement cycles across banking and transportation.
- Edge deployment expansion:Latency-sensitive manufacturing lines and autonomous vehicle fleets are driving inference-optimized software demand outside centralized cloud infrastructure.
Market Restraints
- GPU supply concentration:Training infrastructure dependency on Taiwan-based semiconductor fabrication creates bottleneck risk for model development pipelines.
- Cross-border data friction:China's SAMR algorithmic recommendation provisions and GDPR data localization requirements fragment training dataset access for multinational vendors.
- Energy cost volatility:Large language model training runs face electricity price exposure in markets with renewable transition uncertainty.
Strategic Opportunities
- India enterprise underpenetration:CDSCO regulatory harmonization efforts and domestic cloud infrastructure expansion create whitespace for clinical decision support software.
- Synthetic data generation:Privacy-preserving training methodologies are unblocking financial services and healthcare applications previously constrained by sensitive information restrictions.
- Federal procurement mandates:United States executive orders on responsible AI deployment are channeling public-sector spending toward certified vendor pools.
Industry Challenges
- MLops talent scarcity:Production-grade model monitoring and drift detection capabilities remain concentrated among specialists commanding premium compensation.
- Legacy system integration:Mainframe and on-premise ERP environments in established manufacturing and banking sectors resist API-native AI module insertion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence (AI) Software Market |
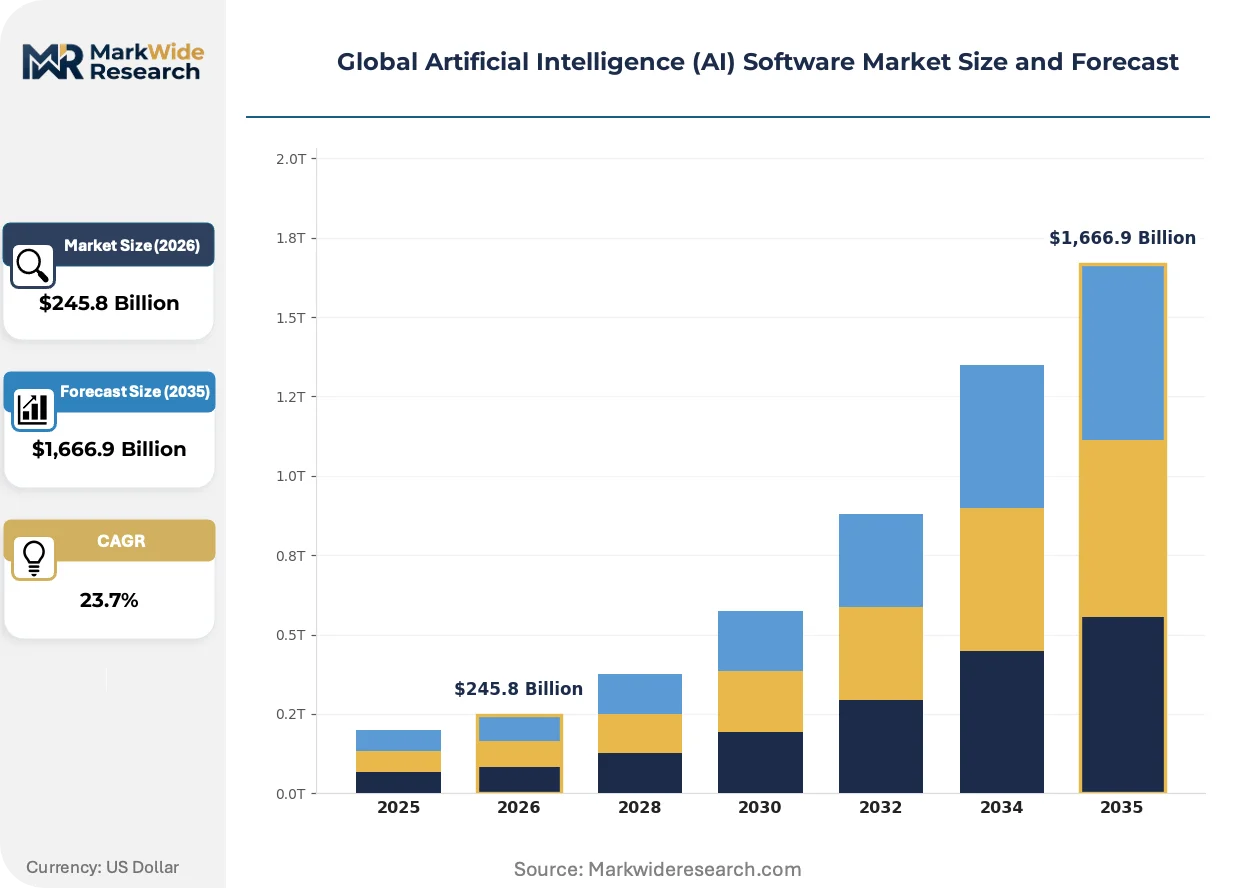
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $1,666.9 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Solution Type: Machine Learning Platforms, NLP Engines, Computer Vision Software, Robotics Process Automation, Speech Recognition Application: Fraud Detection, Predictive Maintenance, Customer Analytics, Supply Chain Optimization, Smart Assistants End User Industry: Banking, Telecommunications, Manufacturing, Transportation, Energy |
| Companies Covered | Microsoft, Google, IBM, Amazon Web Services, NVIDIA, OpenAI, Oracle, Salesforce, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence (AI) Software Market Shifts & Advancements
Foundation model architectures are compressing development timelines while regulatory fragmentation forces vendors to maintain parallel compliance tracks across jurisdictions.
Retrieval-augmented generation is unifying proprietary enterprise knowledge bases with large language model inference. Healthcare systems and legal services firms are deploying these hybrid architectures to ground outputs in verified document corpora. This convergence is collapsing the traditional boundary between search infrastructure and generative interfaces.
The EU AI Act's risk-tier classification system is mandating conformity assessments for high-risk algorithmic systems before market placement. Medical device manufacturers and credit scoring vendors must now maintain audit trails and human oversight documentation. German automotive suppliers and French banking technology divisions are restructuring product development workflows to satisfy notified body requirements.
Enterprise buyers are consolidating vendor relationships around integrated platform contracts rather than point-solution procurement. Financial services institutions in the United States and pharmaceutical conglomerates in Switzerland are negotiating multi-year agreements that bundle compute, models, and application layers. This concentration is squeezing standalone machine learning tool vendors into partnership or acquisition pathways.
Global Artificial Intelligence (AI) Software Market Segmentation
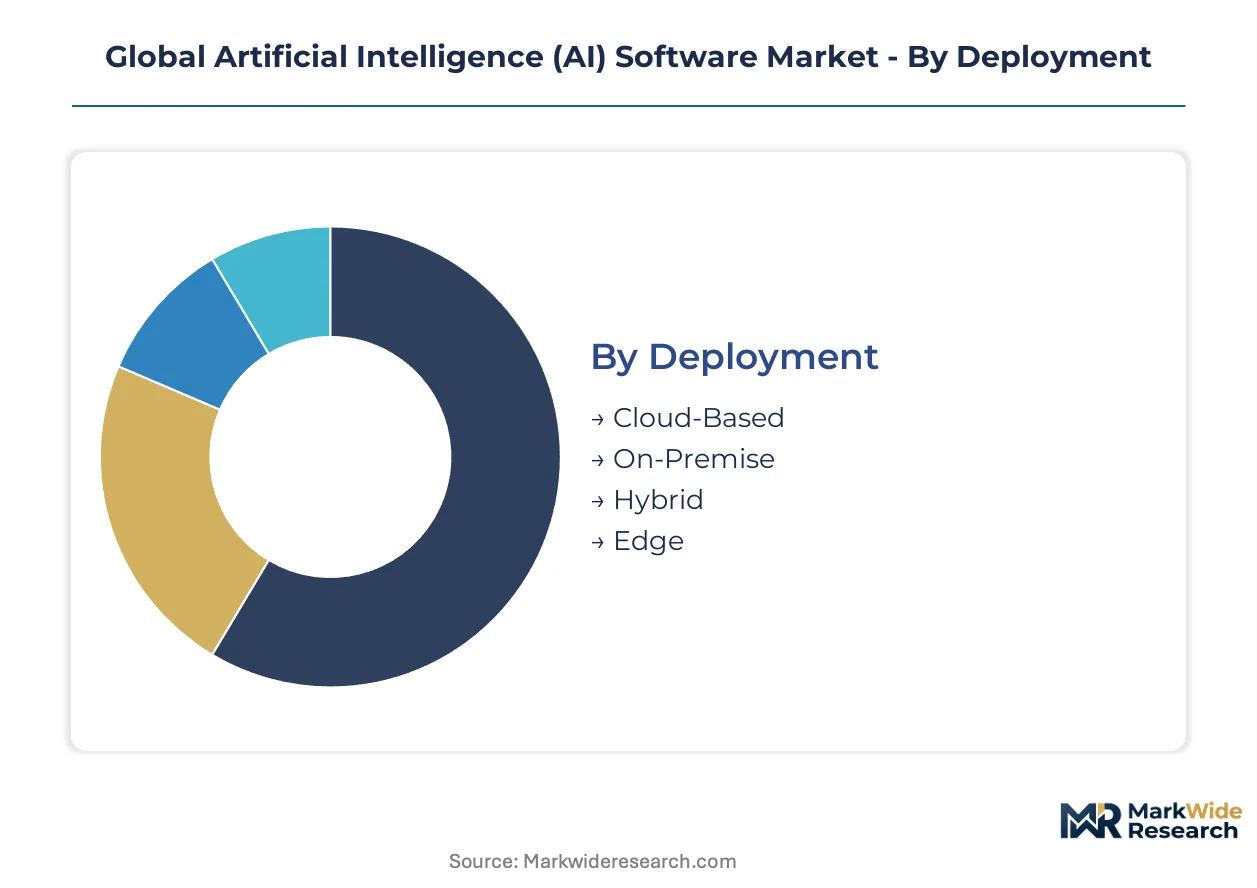
AI software segmentation reveals divergent integration architectures across deployment modes, solution stacks, and industry verticals. Buyers select configurations based on data sovereignty requirements, latency constraints, and existing infrastructure maturity.
Deployment:
Cloud-based systems embed AI as centralized services, while edge deployments integrate inference engines directly into operational hardware.
- Cloud-Based:Elastic compute provisioning supports training workloads and large-scale inference through hyperscaler data centers. Financial services institutions in the United States concentrate procurement here, driven by burst capacity needs for risk model retraining.
- Edge:Localized processing reduces round-trip latency for autonomous vehicle perception stacks and manufacturing quality inspection. German automotive suppliers and Japanese electronics manufacturers anchor demand, constrained by thermal management in embedded form factors.
- On-Premise:Air-gapped installations serve classified government facilities and defense contractors with data residency mandates.
- Hybrid:Orchestrated workloads split training to cloud and inference to local infrastructure for regulated healthcare deployments.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Edge.
Solution Type:
Margin capture varies sharply across the solution stack, with platforms commanding recurring revenue versus point tools facing commoditization.
- Machine Learning Platforms:End-to-end pipelines encompassing data preparation, experiment tracking, and model registry functions lock in enterprise workflows. Swiss pharmaceutical conglomerates and United States healthcare systems drive subscription renewals through embedded MLOps tooling.
- NLP Engines:Transformer-based text processing APIs power document extraction and conversational interfaces. Legal services firms in the United Kingdom and customer service operations in India represent anchor demand segments.
- Computer Vision Software:Convolutional architectures for defect detection and medical imaging interpretation deploy across manufacturing lines and radiology departments.
- Robotics Process Automation:Rule-and-AI hybrid systems automate repetitive administrative tasks in banking back offices.
- Speech Recognition:Acoustic modeling and language decoding for transcription and voice command interfaces.
Revenue concentration sits with Machine Learning Platforms; NLP Engines are climbing the fastest.
Application:
Use-case specificity determines pricing power, with outcomes tied to measurable operational metrics commanding premium positioning.
- Fraud Detection:Real-time transaction scoring employs anomaly detection and graph neural networks to flag synthetic identity and payment fraud. United States card issuers and European neobanks anchor procurement, compelled by PSD2 Strong Customer Authentication and Reg E liability frameworks.
- Smart Assistants:Conversational agents integrate retrieval-augmented generation with enterprise knowledge bases. Healthcare systems and legal services firms in the United States deploy these for clinical documentation and contract review.
- Predictive Maintenance:Sensor data pipelines forecast equipment failures in rotating machinery and electrical infrastructure.
- Customer Analytics:Segmentation and churn prediction models inform marketing automation and retention campaigns.
- Supply Chain Optimization:Demand forecasting and inventory positioning algorithms reduce working capital requirements.
Deployment scale favors Fraud Detection; Smart Assistants show the steepest expansion trajectory.
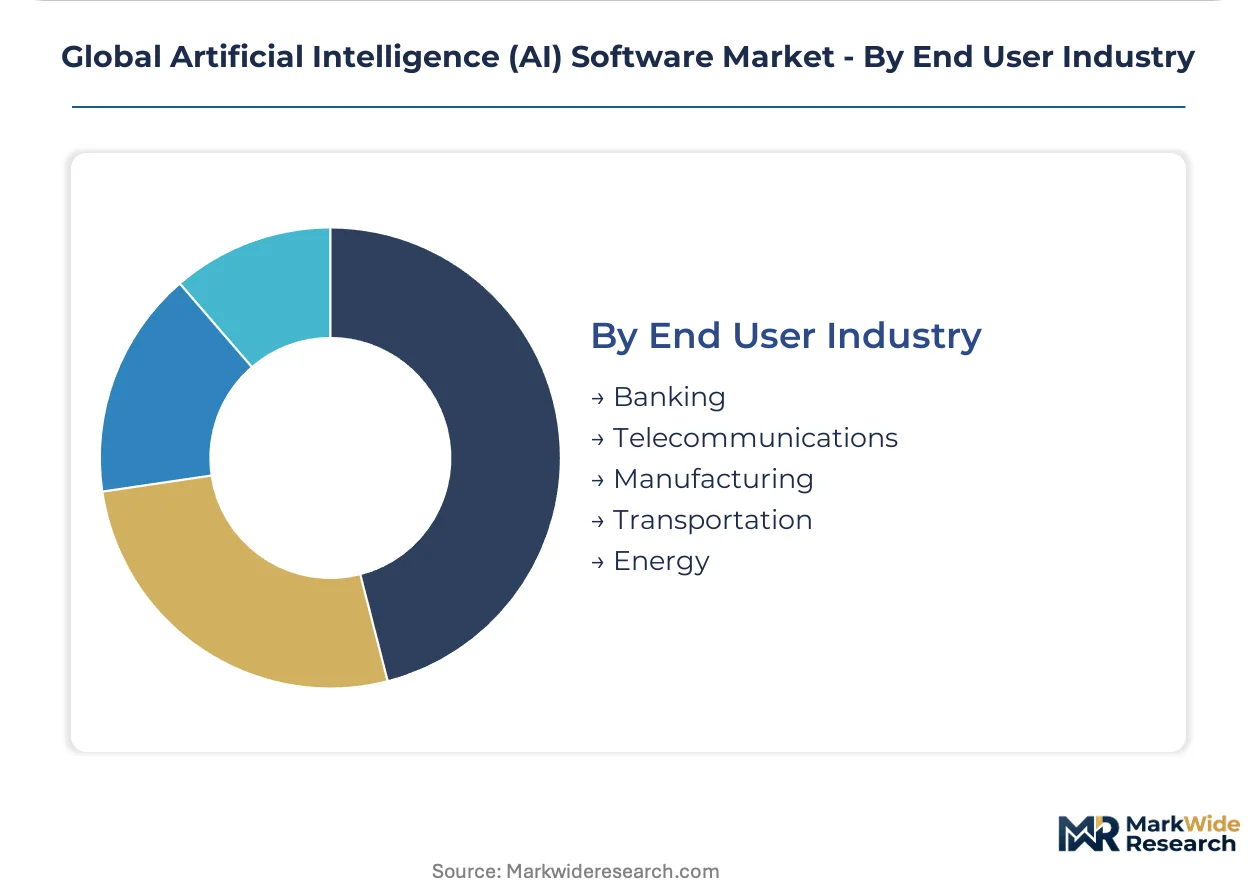
End User Industry:
Regulatory intensity and data asset maturity create divergent adoption timelines across vertical buyers.
- Banking:Credit scoring, anti-money laundering, and algorithmic trading applications face layered oversight from the SEC, OCC, and EU AI Act high-risk system classifications. United States money-center banks and EU systemic institutions drive compliance-mandated procurement cycles.
- Manufacturing:Quality inspection and process optimization deploy across automotive, semiconductor, and industrial equipment production. German automotive suppliers and Japanese precision manufacturers lead edge-AI integration for latency-sensitive visual inspection.
- Telecommunications:Network optimization and customer service automation.
- Transportation:Autonomous vehicle perception and fleet routing optimization.
- Energy:Predictive maintenance for generation assets and grid load forecasting.
Contract values peak in Banking; Manufacturing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises consume the majority of AI software value while Taiwan-based semiconductor fabrication concentrates training infrastructure supply. This production-consumption divide shapes procurement risk profiles across deployment modes.
United States
Financial services institutions and healthcare systems drive enterprise AI spending through FDA-cleared diagnostic tools and SEC-supervised algorithmic trading systems. Executive orders on responsible AI deployment channel federal procurement toward certified vendor pools. Silicon Valley clusters anchor cloud infrastructure expansion while Boston-area healthcare AI specialists concentrate clinical decision support development.
China
Domestic cloud infrastructure expansion and SAMR algorithmic recommendation provisions accelerate regulatory-compliant AI deployment across e-commerce and fintech platforms. NMPA medical device pathways enable imaging AI clearance for hospital procurement. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate computer vision software development for manufacturing quality inspection.
Germany
Automotive suppliers and industrial equipment manufacturers demand edge-optimized inference software for latency-sensitive production lines. EU AI Act high-risk system classifications force conformity assessments for credit scoring and autonomous vehicle perception stacks. Bavaria and Baden-Württemberg engineering clusters integrate KBA-supervised automotive AI into supplier tier restructuring.
India
CDSCO regulatory harmonization efforts and domestic cloud infrastructure expansion create whitespace for clinical decision support software in underpenetrated hospital networks. RBI-supervised neobanks deploy NLP engines for customer service automation. Karnataka and Telangana technology corridors anchor machine learning platform development for export-oriented IT services.
United Kingdom
Legal services firms and financial institutions deploy retrieval-augmented generation systems for contract review and compliance documentation. GDPR data localization requirements fragment training dataset access for multinational vendors. London and Southeast England clusters concentrate conversational AI development for professional services automation.
Global Artificial Intelligence (AI) Software Market Competitive Landscape
The competitive structure tilts toward hyperscaler-dominated platform consolidation. Cloud infrastructure providers and specialized hardware vendors capture disproportionate margin pools through bundled compute-model-application stacks. Three archetypes dominate: hyperscalers anchoring enterprise distribution, semiconductor specialists controlling training infrastructure, and foundation model laboratories driving capability boundaries. Competitive moves concentrate on strategic partnerships binding compute access to model distribution, and vertical integration into specialized chip architectures.
Among hyperscaler-based platform providers, Microsoft and Google exemplify the integrated stack archetype, bundling cloud infrastructure with foundation model access and application-layer tooling. NVIDIA occupies a position as the training infrastructure anchor, with its GPU architectures serving as the substrate for model development pipelines across vendor ecosystems. IBM represents the enterprise services hybrid, combining consulting-led deployment with proprietary model development for regulated industry verticals.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Amazon Web Services |
| NVIDIA |
| OpenAI |
| Oracle |
| Salesforce |
| SAP |
| Others |
Supply & Pricing Matrix
GPU wafer fabrication costs cascade through three distinct pricing tiers for AI software deployment, with Taiwan Semiconductor Manufacturing Company's advanced node capacity constraining supply elasticity for training infrastructure while hyperscaler cloud credits subsidize downstream SaaS pricing for enterprise buyers.
Pricing Analysis
Margin tightening in foundation model APIs reflects concentrated training infrastructure ownership among hyperscalers bundling compute with model access. Three-tier pricing structure across premium enterprise, standard developer, and economy inference levels differentiates by latency guarantees and customization depth. Cost-down pressure on edge deployment software accelerates because automotive and manufacturing buyers negotiate volume commitments against per-unit hardware BOM targets. Financial services institutions exhibit lowest price sensitivity due to compliance-mandated procurement cycles, while mid-market SaaS vendors face highest churn risk from open-source model commoditization.
Supply Chain Analysis
Domestic content mandates in China's cloud procurement and India's government AI programs are reshaping sourcing patterns for data center infrastructure and model training pipelines. Supply concentration rests on Taiwan for GPU fabrication, South Korea for HBM memory, and the United States for hyperscaler orchestration platforms. Raw material dependencies span advanced photoresists, high-purity silicon wafers, and rare earth elements for magnet assemblies in cooling systems. Single-source vulnerability around CoWoS packaging capacity creates bottleneck risk for training chip availability. Distribution runs through direct hyperscaler enterprise contracts and tiered channel partnerships for specialized vertical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model architectures are displacing rules-based automation stacks, compressing development timelines while fragmenting vendor consolidation opportunities across deployment modes.
For Market Incumbents: Anticipate regulatory divergence between the EU AI Act's high-risk system classifications and FDA's software-as-medical-device pathways forcing parallel compliance investments. Anchor defensive positioning through captive GPU allocation agreements with Taiwan-based fabricators. Deepen MLOps tooling integration to lock enterprise data pipelines against modular API substitution. For New Entrants and Emerging Players: Channel partners specializing in healthcare IT integration represent the fastest path to hospital procurement cycles for diagnostic imaging AI. Target India's underpenetrated clinical decision support market where CDSCO harmonization creates first-mover whitespace. Lead with edge-optimized inference pricing against hyperscaler egress cost structures for manufacturing quality inspection deployments. For Investors and Strategic Acquirers: EU AI Act conformity assessment deadlines for high-risk algorithmic systems are the leading indicator that compliance-automation tooling will command acquisition premiums. Frame long-term viability around model-agnostic infrastructure plays rather than foundation model laboratories facing capitalization intensity. Monitor hyperscaler capex disclosure inflections as the signal for training capacity expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling compute, models, and application layers locks enterprise procurement into multi-year contracts. |
| Strategic Partnership | GPU allocation agreements with Taiwan fabricators secure training infrastructure access against supply bottlenecks. |
| Acquisition of Specialist Firm | MLOps tooling vendors capture recurring revenue through embedded workflow integration. |
| Product Launch | Retrieval-augmented generation systems ground outputs in verified document corpora for healthcare and legal services. |
| Geographic Expansion | India's domestic cloud infrastructure expansion creates whitespace for clinical decision support software deployment. |
Research Methodology
Independent corroboration across CTOs at United States financial institutions, platform engineers at German automotive suppliers, and biomedical informatics directors at NHS trusts underwrites the qualitative findings. Secondary validation draws from SEC filings revealing hyperscaler AI capex trajectories, FDA 510(k) clearance databases for diagnostic imaging software, and EU AI Act implementing act drafts. Bottom-up deployment mode sizing triangulates against top-down enterprise IT spending surveys.
Rate-of-change decomposition separates cloud-based expansion from edge deployment acceleration across the analysis window. Segmentation dimensions encompass deployment model, solution stack layer, vertical regulatory intensity, and regional adoption pattern. CAGRs derive from fitted growth curves against historical infrastructure investment cycles and regulatory compliance deadline clustering. Model inputs include GPU supply forecasts from foundry utilization disclosures and enterprise software procurement pipeline data from GPO contracts.
Caveats apply where Taiwan semiconductor fabrication disruption or EU AI Act risk-classification revisions could materially shift the outlook. Forecasts embed assumptions around hyperscaler pricing discipline and edge hardware thermal management advancement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Content Automation AI Tools Market
Artificial Intelligence (AI)
Cognitive Computing Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market