
 North America Glamping Market | 2026-2036
North America Glamping Market Size, Share, and Industry Trends Forecast 2026-2036
North America Glamping Market Insights
Buyer concentration across the North America glamping market is rebalancing from traditional resort travelers toward experience-seeking families and corporate retreat planners. Under Canvas leverages its national park-adjacent portfolio to dominate scenic destination access. Collective Retreats differentiates through urban-adjacent pop-up concepts that anchor proximity to major metropolitan demand. Tentrr competes via a technology-enabled platform that controls landowner partnerships across dispersed rural acreage.
Glamping denotes upscale outdoor hospitality combining semi-permanent shelter structures with hotel-grade amenities and curated natural immersion. Fabric tensile roofing with engineered aluminum or steel framing withstands wind loads exceeding standard recreational camping equipment while providing climate-buffered interior environments. Tents and yurts within the accommodation type category occupy the established volume base, whereas treehouses command premium rate positioning due to elevated construction complexity and scarcity of suitable forest canopy sites. The service type dimension shows luxury and eco-friendly tiers capturing disproportionate margin pools as operators source renewable energy systems and locally contracted provisioning.
The United States Forest Service, National Park Service, and state-level environmental health departments collectively shape site permitting, wastewater disposal standards, and seasonal operating windows across North American jurisdictions. Health Canada and provincial tourism authorities enforce comparable lodging safety and food service protocols in Canadian markets. Stakeholders must monitor evolving accessibility mandates and wildfire risk zoning that could restrict expansion corridors or require structural hardening investments.
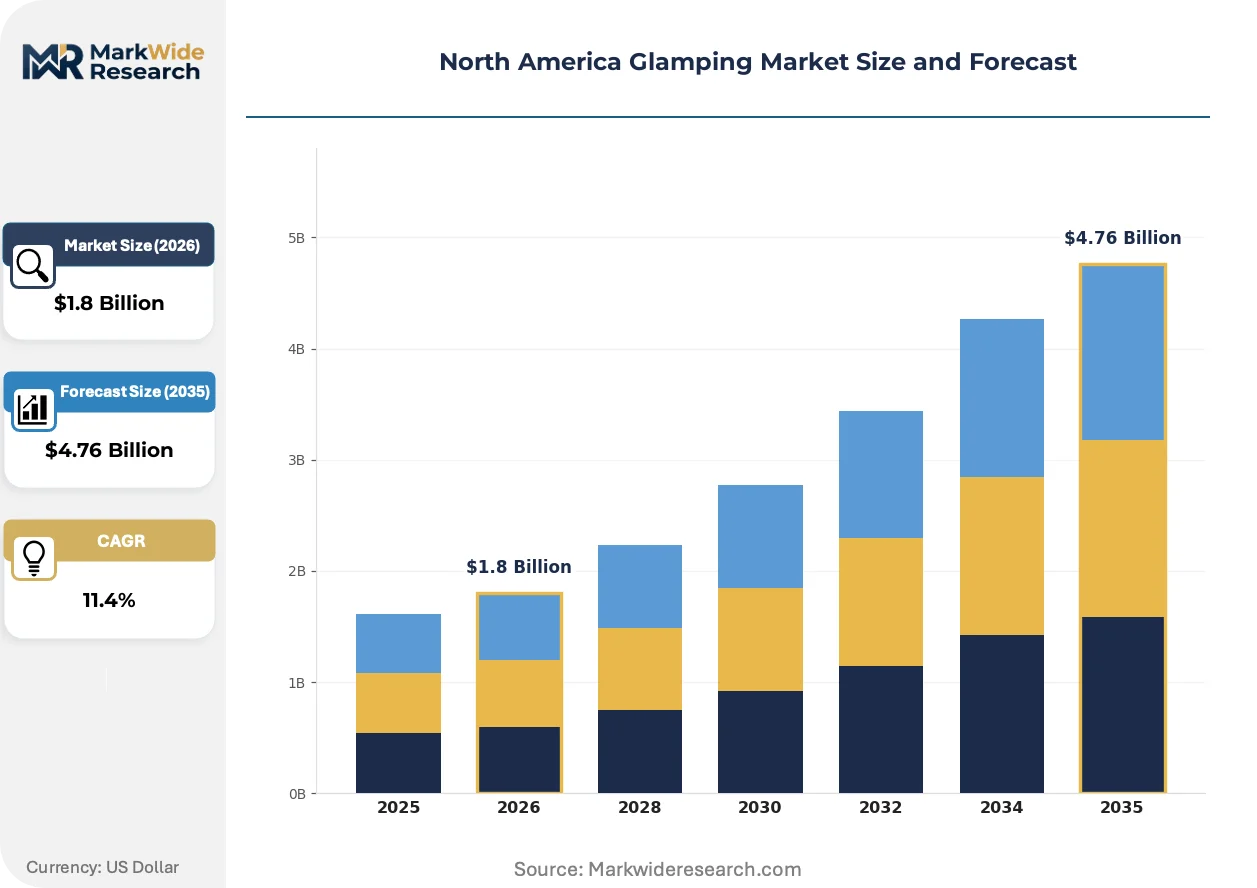
Market Dynamics
The North America glamping market is undergoing structural transformation as experience-seeking families and corporate retreat planners displace traditional resort travelers, forcing operators to reconfigure site amenities and booking platforms around multi-generational group dynamics and curated natural immersion.
Growth Catalysts
- National Park Service accessibility mandates:The 2010 ADA Standards for Accessible Design now enforce wheelchair-accessible pathways and restroom facilities at concession-operated sites, compelling developers to design inclusive infrastructure that expands addressable guest pools.
- Corporate retreat procurement:Fortune 500 human resources departments are routing offsite budgets toward nature-based team experiences, creating predictable group booking volume with higher per-guest ancillary spend.
- Geodesic dome engineering:Tensile membrane structures with aluminum strut framing now withstand snow loads exceeding 50 pounds per square foot, enabling year-round operations in Colorado and Montana mountain corridors.
Market Restraints
- Lumber and engineered timber volatility:Platform decking and structural framing costs fluctuate with Pacific Northwest sawmill capacity, compressing margin predictability for treehouse and elevated cabin developers.
- Septic and wastewater infrastructure:Remote site locations require costly mound or advanced treatment systems per state environmental health codes, extending pre-revenue timelines by 8-14 months in Utah and Arizona jurisdictions.
- Wildfire risk zoning:United States Forest Service seasonal closure protocols and state-level air quality emergency declarations force unplanned operating interruptions across California and Pacific Northwest markets.
Strategic Opportunities
- Canadian provincial tourism incentives:British Columbia and Alberta offer matching grants for indigenous partnership tourism ventures, creating capital-efficient entry paths for operators collaborating with First Nations landholders.
- Dark sky certification:International Dark-Sky Association accreditation commands 15-25% rate premiums in astronomy tourism corridors, with New Mexico and Texas presenting underdeveloped inventory.
- Grid-independent power systems:Solar-battery microgrids paired with propane HVAC eliminate utility connection costs at dispersed rural sites, reducing site selection constraints across Montana ranchland.
Industry Challenges
- Hospitality-operations talent scarcity:Remote locations struggle to recruit experienced general managers and culinary staff willing to accept seasonal or isolated postings, elevating training costs and guest service inconsistency.
- Permitting timeline compression:County-level conditional use permits and state health department food service licenses require sequential approvals that delay revenue recognition, with Colorado and Utah jurisdictions averaging 11-16 month approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Glamping Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Tents, Yurts, Airstreams, Treehouses Service Type: Full-Service, Self-Catering, Luxury, Eco-Friendly Customer Type: Families, Couples, Groups, Solo Travelers Activity Type: Adventure, Relaxation, Nature Exploration, Wellness |
| Companies Covered | Under Canvas, Collective Retreats, Tentrr, Huttopia, KOA, The Resort at Paws Up, Timberline Glamping, Treebones Resort, The Ranch at Rock Creek, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Glamping Market Trends and Innovations
Fabrication methods and guest-facing technology are converging to compress development timelines while elevating the experiential premium that distinguishes glamping from conventional lodging alternatives across North American markets.
Modular prefabrication is unifying off-site manufacturing with rapid on-site assembly. Engineered wall panels with integrated MEP rough-ins arrive via flatbed to rural locations, cutting construction duration from 6 months to 3 weeks. Family travel operators in Utah and Colorado are adopting this approach to accelerate inventory expansion ahead of peak summer booking windows.
Revised USDA Forest Service special use permit guidelines now require comprehensive wildfire mitigation plans including defensible space maintenance and emergency water storage. Operators must submit 10-year vegetation management contracts to secure 20-year permit renewals. Mountain West portfolio holders are responding by hardening structures with ignition-resistant roofing and automated sprinkler systems.
Direct booking platforms are displacing online travel agency dependency. Experience-seeking travelers now research through Instagram and TikTok discovery, then transact on operator-native sites to avoid commission stacking. Corporate retreat planners in Texas and California are negotiating group rates through dedicated sales portals rather than traditional RFP channels, compressing sales cycles and improving yield management precision.
North America Glamping Market Segmentation
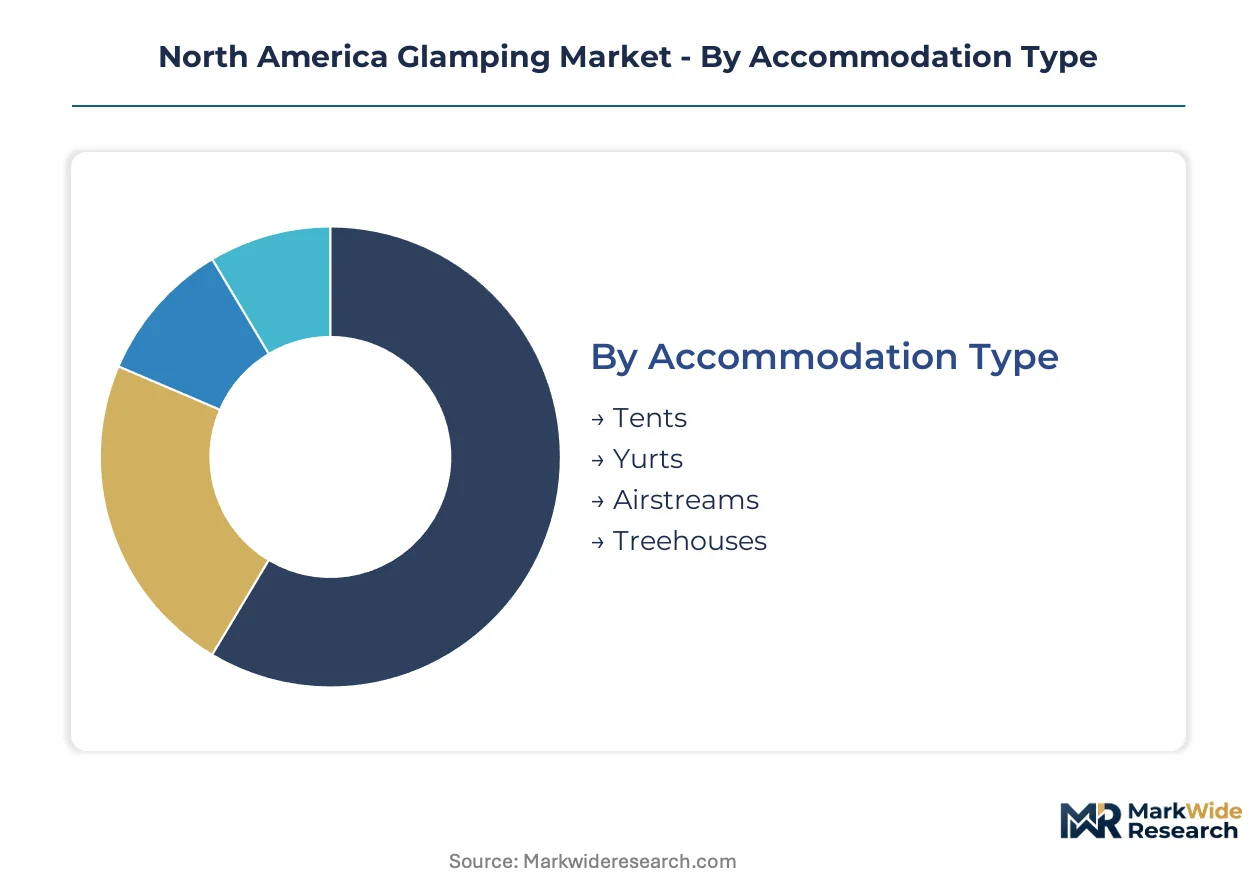
Glamping operators configure inventory and service tiers around distinct capital requirements and guest willingness to pay. Segmentation choices directly determine site development costs, permitting complexity, and revenue per available room across Mountain West and Canadian corridors.
Accommodation Type:
Capital intensity varies dramatically across structure types, with elevated and custom-built options demanding substantially higher upfront investment than ground-based fabric shelters.
- Treehouses:Elevated platforms require engineered timber framing, specialized anchoring systems, and arborist consultations for canopy compatibility. Colorado and Montana operators targeting luxury tiers concentrate demand here, constrained by limited suitable forest sites and extended permitting timelines.
- Tents:Fabric tensile structures with aluminum or steel framing represent the established volume base, offering modular deployment and lower per-unit land preparation costs. Utah corridor developers favor these for rapid inventory scaling ahead of compressed summer booking windows.
- Yurts:Circular lattice frameworks with tension-band roofing merge traditional nomadic design with modern weatherproofing membranes.
- Airstreams:Retrofitted aluminum travel trailers deliver instant inventory without permanent foundations.
Most installed capacity flows through Tents. Expansion is steepest in Treehouses.
Service Type:
Margin profiles diverge sharply based on staffing ratios and amenity provisioning intensity, with premium tiers capturing disproportionate returns through curated experiences.
- Luxury:White-glove service tiers feature on-site culinary teams, guided excursions, and bespoke concierge programming. Corporate retreat planners in Texas and California drive predictable group bookings with elevated ancillary capture rates.
- Eco-Friendly:Renewable energy systems, composting sanitation, and locally sourced provisioning command rate premiums from sustainability-motivated travelers. British Columbia operators leverage indigenous partnership structures to access provincial tourism matching grants.
- Full-Service:Structured meal plans and scheduled activities reduce guest decision friction.
- Self-Catering:Minimal staffing models shift operational burden to guests for cost-sensitive segments.
Revenue per available room peaks in Luxury. Guest acquisition costs compress fastest in Eco-Friendly.
Customer Type:
Booking patterns and length-of-stay economics vary by group composition, with multi-generational parties generating higher per-visit spend than individual travelers.
- Families:Multi-generational groups demand interconnected accommodations, child-safe infrastructure, and activity programming spanning age ranges. Mountain West operators report this segment driving peak summer volume with extended stays averaging three to four nights.
- Groups:Corporate retreat and celebration travel creates predictable midweek demand outside leisure peaks. Texas and California markets show particular concentration as Fortune 500 human resources departments route offsite budgets toward nature-based team experiences.
- Couples:Romance-focused travelers prioritize privacy amenities and premium in-tent features.
- Solo Travelers:Individual guests seek communal programming and safety-assured remote locations.
Booking volume concentrates in Families. Yield management complexity escalates most steeply in Groups.
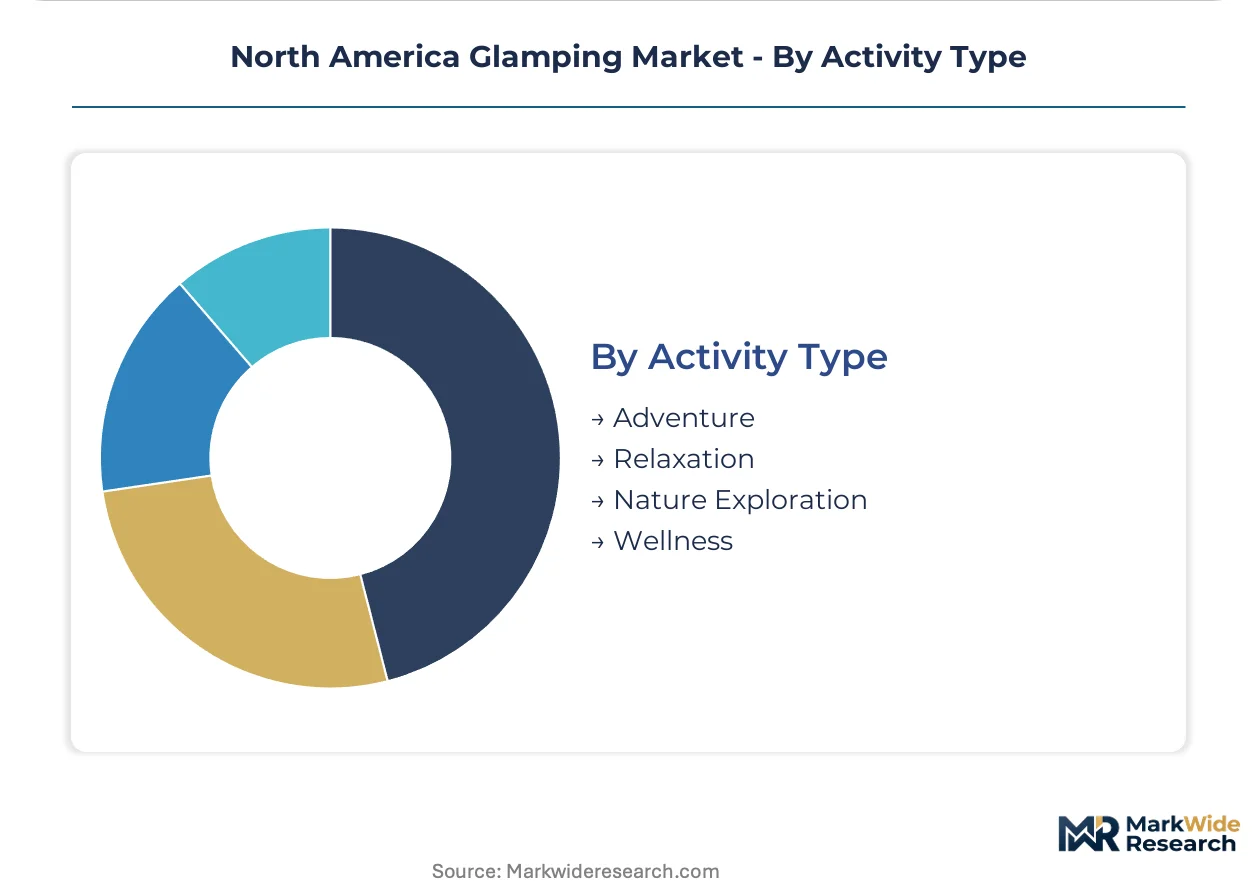
Activity Type:
Experience anchoring determines site selection requirements and seasonal operating windows, with high-exertion options demanding terrain access and liability infrastructure.
- Adventure:Rock climbing, whitewater rafting, and backcountry skiing partnerships require guide certifications, emergency response protocols, and specialized equipment inventories. Colorado and Utah jurisdictions enforce strict operator liability frameworks around these activities.
- Wellness:Yoga programming, spa treatments, and meditation infrastructure attract extended-stay guests with higher ancillary spend on retail and therapeutic services. New Mexico operators pursue International Dark-Sky Association accreditation to command astronomy tourism premiums.
- Nature Exploration:Wildlife viewing and guided hiking access National Park Service concession opportunities.
- Relaxation:Passive experience design minimizes operational complexity and staffing requirements.
Guest retention runs highest in Wellness. Infrastructure investment per booked night peaks in Adventure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality operations talent concentrates in Colorado's resort corridors and California's wine country, with seasonal migration patterns extending staffing reach into Montana and Utah mountain markets during peak summer windows.
United States
Family travel segments drive booking volume across Colorado, Montana, and Utah, with Mountain West corridor operators reporting extended stays averaging three to four nights. The United States Forest Service enforces wildfire mitigation plans including defensible space maintenance and emergency water storage for 20-year permit renewals. Colorado's Front Range and Utah's Wasatch Back host the densest concentration of geodesic dome and luxury tent inventory.
Canada
Indigenous partnership tourism ventures access provincial matching grants in British Columbia and Alberta, creating capital-efficient entry paths for operators collaborating with First Nations landholders. Health Canada and provincial tourism authorities enforce lodging safety and food service protocols comparable to US standards. British Columbia's coastal rainforest zones and Alberta's Rocky Mountain foothills anchor the highest site development activity.
Mexico
Eco-tourism demand from US and Canadian travelers concentrates in Baja California Sur and Quintana Roo coastal corridors, with operators leveraging proximity to dark sky zones and marine reserves. Mexico's federal environmental protection agency SEMARNAT regulates coastal development permits and wastewater discharge standards. The Todos Santos and Valle de Guadalupe wine regions host emerging luxury tent and Airstream inventory targeting cross-border leisure travel.
North America Glamping Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North America glamping market, with hospitality REITs and outdoor recreation platforms controlling capital-intensive inventory while independent operators dominate experience-curation tiers. Market structure shows moderate consolidation at the portfolio level alongside fragmentation in single-site boutique operations. Three archetypes predominate: national park-adjacent concession holders, urban-adjacent pop-up concept developers, and technology-enabled landowner partnership platforms. Competitive moves center on strategic land access negotiations and modular prefabrication adoption to compress development timelines.
Within the national park-adjacent tier, Under Canvas anchors scenic destination access through concession-operated portfolios near protected federal lands. Collective Retreats occupies a position exemplifying urban-adjacent pop-up concepts that leverage proximity to major metropolitan demand centers. Tentrr represents the technology-enabled archetype, controlling dispersed rural acreage through landowner partnership structures rather than direct real estate ownership.
| Leading Market Players |
|---|
| Under Canvas |
| Collective Retreats |
| Tentrr |
| Huttopia |
| KOA |
| The Resort at Paws Up |
| Timberline Glamping |
| Treebones Resort |
| The Ranch at Rock Creek |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists now control the largest glamping portfolios across Colorado and Utah, compressing supplier payment terms while enforcing rate discipline through centralized yield management systems that synchronize pricing across national park-adjacent corridors.
Pricing Analysis
Bundled all-inclusive packages versus unbundled accommodation-only rates split the pricing architecture across the Mountain West. Luxury tiers attach guided excursions and on-site culinary programming to capture corporate retreat budgets from Texas and California planners. Standard tiers compete on base nightly rates with ancillary upsells. Price differentiation rests on dark sky certification status and proximity to National Park Service concessions. Pricing pressure intensifies in the tent category as modular prefabrication lowers competitor entry costs. Families show highest price sensitivity, while corporate groups accept premium positioning for predictable procurement.
Supply Chain Analysis
Single-source vulnerability sits with Pacific Northwest sawmill capacity for engineered timber and structural decking. Fabric tensile roofing membranes draw from specialized manufacturers in the United States and Canada. Aluminum framing extrusions hinge on domestic smelter output. Supply chain risk concentrates in lumber price volatility tied to wildfire season disruption and transportation bottlenecks through mountain corridor highways. Distribution runs through direct-to-operator procurement channels with limited distributor intermediation, compressing lead time visibility for rural site developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in the luxury service tier as corporate retreat procurement shifts toward nature-based programming, while modular prefabrication compresses construction timelines and capital deployment for new inventory.
For Market Incumbents: Acquire geodesic dome and engineered yurt manufacturers to secure captive supply of weather-hardened structures for Colorado and Montana expansion. Lock in 10-year vegetation management contracts required for United States Forest Service permit renewals before competitor bidding escalates land access costs. Vertical integration into renewable energy microgrid installation protects against utility connection delays at remote sites. For New Entrants and Emerging Players: British Columbia and Alberta provincial tourism matching grants for indigenous partnership ventures open a window for capital-efficient land access without direct real estate acquisition. Target underserved astronomy tourism corridors in New Mexico and Texas where International Dark-Sky Association accreditation commands rate premiums with limited existing inventory. Deploy technology-enabled landowner partnership platforms to aggregate dispersed rural acreage without portfolio concentration risk. For Investors and Strategic Acquirers: Valuations sit cheapest among single-site boutique operators with established National Park Service concession relationships but limited brand recognition. Long-term viability favors portfolios with year-round operating capability through geodesic dome engineering that withstands mountain snow loads. Watch corporate retreat procurement budget allocations as the inflection signal for group booking volume sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Adoption | Compresses construction timelines from six months to three weeks for Utah and Colorado summer inventory deployment. |
| Indigenous Partnership Structuring | Unlocks provincial matching grants in British Columbia and Alberta while securing culturally distinctive programming. |
| Dark Sky Certification Pursuit | Commands 15-25% rate premiums in New Mexico and Texas astronomy tourism corridors with underdeveloped supply. |
| Direct Booking Platform Investment | Reduces online travel agency commission stacking as Instagram and TikTok discovery drives native site transactions. |
| Wildfire Mitigation Hardening | Satisfies revised USDA Forest Service special use permit guidelines requiring ignition-resistant roofing and automated sprinkler systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with glamping operators, National Park Service concession coordinators, provincial tourism authority directors, and corporate retreat procurement managers with secondary validation from United States Forest Service permit filings, Health Canada lodging safety protocols, provincial tourism incentive program documentation, and SEC filings of hospitality REITs with outdoor recreation exposure. Bottom-up site inventory counts and top-down addressable demand estimation triangulated market sizing across the analysis window.
Segment-weighting approaches distributed total market value across accommodation type, service tier, customer composition, and activity anchoring dimensions. Growth projections incorporated geodesic dome engineering penetration rates, corporate retreat budget reallocation patterns, and modular prefabrication adoption curves throughout the forecast period. CAGRs derived from historical booking volume trajectories and forward-looking capacity expansion announcements without reliance on single-source extrapolation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended wildfire season closures, lumber price spike persistence, or regulatory acceleration of accessibility mandate enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Short-term Rentals and Vacation Homes
Asia-Pacific Glamping Market
Short-term Rentals and Vacation Homes
Treehouse Glamping Market
Short-term Rentals and Vacation Homes
Short-Term Rental Platform Market
Short-term Rentals and Vacation Homes
Vacation Ownership Market
Short-term Rentals and Vacation Homes
Online Home Rental Services Market
Short-term Rentals and Vacation Homes
Australia Glamping Market
Short-term Rentals and Vacation Homes
Europe Glamping Market
Short-term Rentals and Vacation Homes
Vacation Rentals Market
Short-term Rentals and Vacation Homes
Short-Term Vacation Rental Market
Short-term Rentals and Vacation Homes
Vacation Rental Website Market
Short-term Rentals and Vacation Homes
Vacation Ownership Timeshare Market
Short-term Rentals and Vacation Homes
Luxury Vacation Rental Market
Short-term Rentals and Vacation Homes
RV Rental Market