
 Europe Forensic Accounting Market | 2026-2036
Europe Forensic Accounting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Forensic Accounting Market Insights
United Kingdom-based forensic accounting practices is restructuring service delivery models around digital evidence platforms. KPMG International leverages proprietary data analytics tools to process complex financial irregularities across cross-border disputes. Deloitte anchors its European forensic practice in London and Frankfurt hubs, sustaining deep benches of certified fraud examiners. BDO International competes aggressively in mid-market corporate investigations, differentiating through sector-specific methodologies for manufacturing and telecommunications clients.
Forensic accounting applies specialized investigative techniques to detect financial misstatement, asset misappropriation, and regulatory violations through document analysis, transaction tracing, and digital forensics. Practitioners employ chain-of-custody protocols, statistical sampling, and metadata examination to reconstruct financial events for legal proceedings and compliance remediation. Litigation support services dominate revenue generation across Western Europe, where complex cross-border arbitration drives sustained engagement of expert witnesses. Fraud investigation demand is accelerating fastest in Eastern Europe, where EU accession-related transparency mandates expand corporate due diligence requirements. Regulatory compliance services concentrate margin pools in Northern Europe, where stringent ESG disclosure rules under the EU CSRD compel enhanced forensic verification of sustainability claims.
The EU's Anti-Money Laundering Authority (AMLA) and national financial intelligence units under the Sixth AML Directive are elevating forensic accounting mandates for suspicious transaction reporting and beneficial ownership verification. EMA and national banking supervisors in France, Germany, and Italy embed forensic accountants into pharmaceutical pricing investigations and healthcare fraud probes. GDPR constraints on data processing shape evidentiary protocols, requiring practitioners to navigate cross-border disclosure restrictions. Stakeholders must monitor harmonization gaps between national insolvency codes and EU-wide asset recovery frameworks as enforcement intensity escalates.
Market Dynamics
The Sixth Anti-Money Laundering Directive is compressing investigation timelines across European financial institutions, forcing forensic accounting practices to restructure delivery models around real-time transaction monitoring and automated suspicious activity flagging.
Growth Catalysts
- ESG verification mandates:The EU Corporate Sustainability Reporting Directive compels listed companies to obtain independent assurance on sustainability disclosures. Forensic accountants now audit carbon credit claims and supply chain labor certifications.
- Cross-border insolvency complexity:The European Insolvency Regulation harmonization creates demand for asset tracing across multiple jurisdictions. Practitioners reconstruct financial flows through shell company networks in Eastern European accession states.
- Healthcare fraud prosecution:France's national health insurance fund and Germany's central federal audit office embed forensic specialists into pharmaceutical pricing investigations. Transaction pattern analysis identifies inflated reimbursement claims.
Market Restraints
- GD evidentiary constraints:Cross-border data transfer restrictions under GDPR limit document collection in multi-jurisdictional disputes. Practitioners face procedural delays establishing lawful processing bases for personal financial records.
- Specialist talent scarcity:Certified fraud examiner density concentrates in London, Frankfurt, and Paris. Mid-tier practices in Southern and Eastern Europe struggle to recruit professionals with dual accounting and digital forensics competencies.
- Technology substitution pressure:RegTech automation platforms now handle routine suspicious transaction monitoring. Traditional forensic accounting revenue from compliance documentation faces compression from algorithmic alternatives.
Strategic Opportunities
- Polish and Romanian corporate due diligence:EU cohesion fund disbursement rules and pre-accession transparency frameworks expand forensic verification demand for state-owned enterprise privatizations and infrastructure procurement.
- AI-augmented document review:Natural language processing and machine learning classification tools converge with forensic workflows. Early adopters compress e-discovery timelines in complex litigation support engagements.
- Crypto-asset tracing specialization:The Markets in Crypto-Assets Regulation creates forensic mandates for virtual currency transaction analysis. Distributed ledger investigation capabilities differentiate boutique practices from generalist competitors.
Industry Challenges
- Digital forensics certification bottlenecks:ENFSI accreditation pathways for electronic evidence handling remain underdeveloped. Practitioners face extended credentialing timelines to qualify as expert witnesses in criminal proceedings.
- Legacy system integration friction:Bank and insurance clients operate fragmented data architectures. Forensic teams expend disproportionate effort normalizing transaction records across incompatible core banking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Forensic Accounting Market |
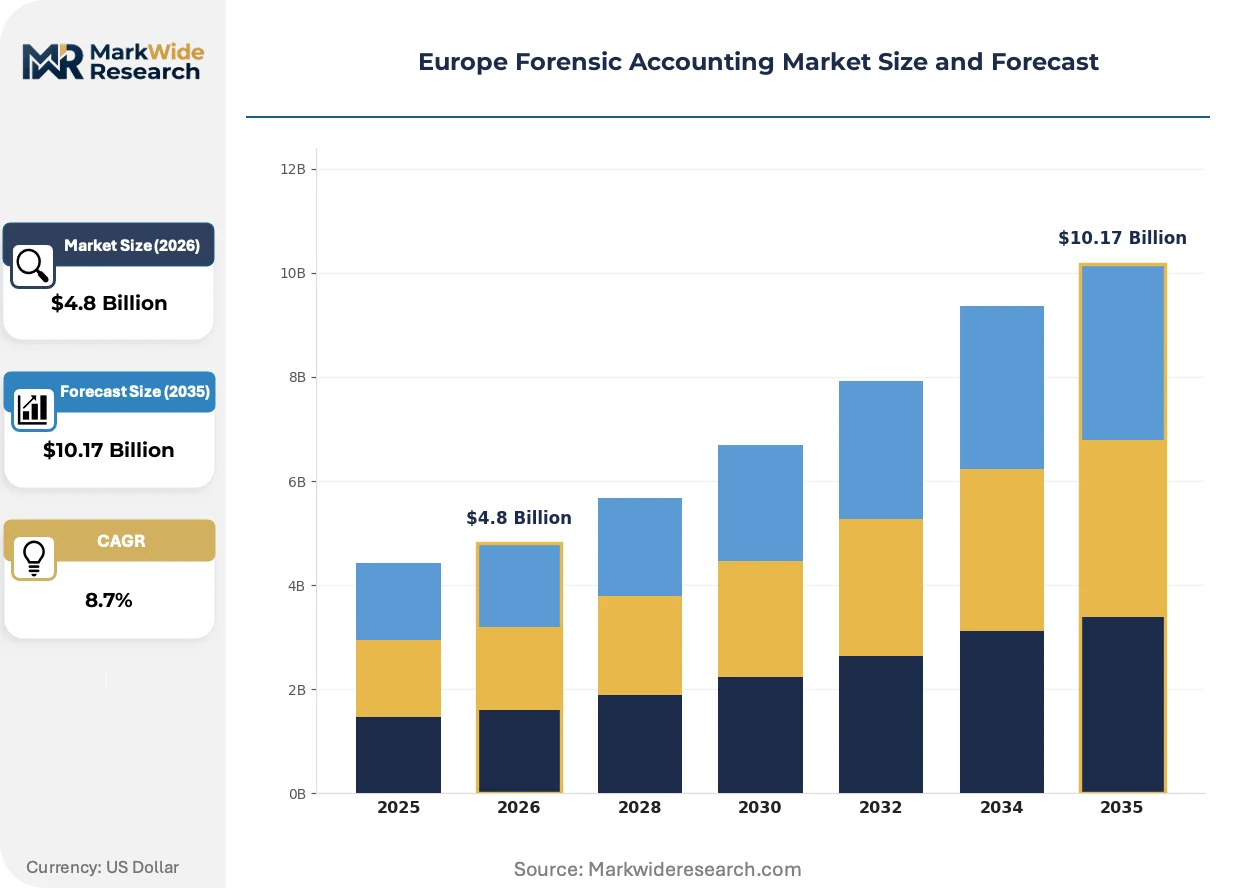
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Litigation Support, Fraud Investigation, Regulatory Compliance, Expert Testimony End User: Government Agencies, Law Firms, Corporations, Non-Profit Organizations Industry Vertical: Finance, Insurance, Manufacturing, Telecommunications Geographical Focus: Western Europe, Northern Europe, Southern Europe, Eastern Europe |
| Companies Covered | KPMG International, Grant Thornton, PwC, FTI Consulting, RSM International, Deloitte, BDO International, Alvarez & Marsal, Ernst & Young, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Forensic Accounting Market Trends and Innovations
Forensic accounting across Europe is pivoting from retrospective investigation toward continuous monitoring architectures. Practitioners embed analytical tools directly into client financial systems, compressing detection latency from months to days.
Continuous auditing technology is integrating machine learning anomaly detection with enterprise resource planning systems. Major banking groups in Germany and the Netherlands deploy these tools for real-time payment screening. The technology is integrating predictive risk scoring into compliance workflows, reducing reliance on periodic manual sampling.
The EU Anti-Money Laundering Authority's 2025 operational launch elevates forensic mandates for beneficial ownership verification. National financial intelligence units in Italy and Spain now require enhanced documentation for complex ownership structures. Asset management and private banking segments face the steepest compliance cost increases as they restructure client onboarding protocols.
Corporate legal departments are unbundling forensic investigation from traditional audit relationships. General counsel in France and Belgium now directly retain specialist boutiques for sensitive internal investigations, bypassing established Big Four channels. This procurement pattern concentrates margin pools with sector-focused practices possessing pharmaceutical, energy, or telecommunications domain expertise.
Europe Forensic Accounting Market Segmentation
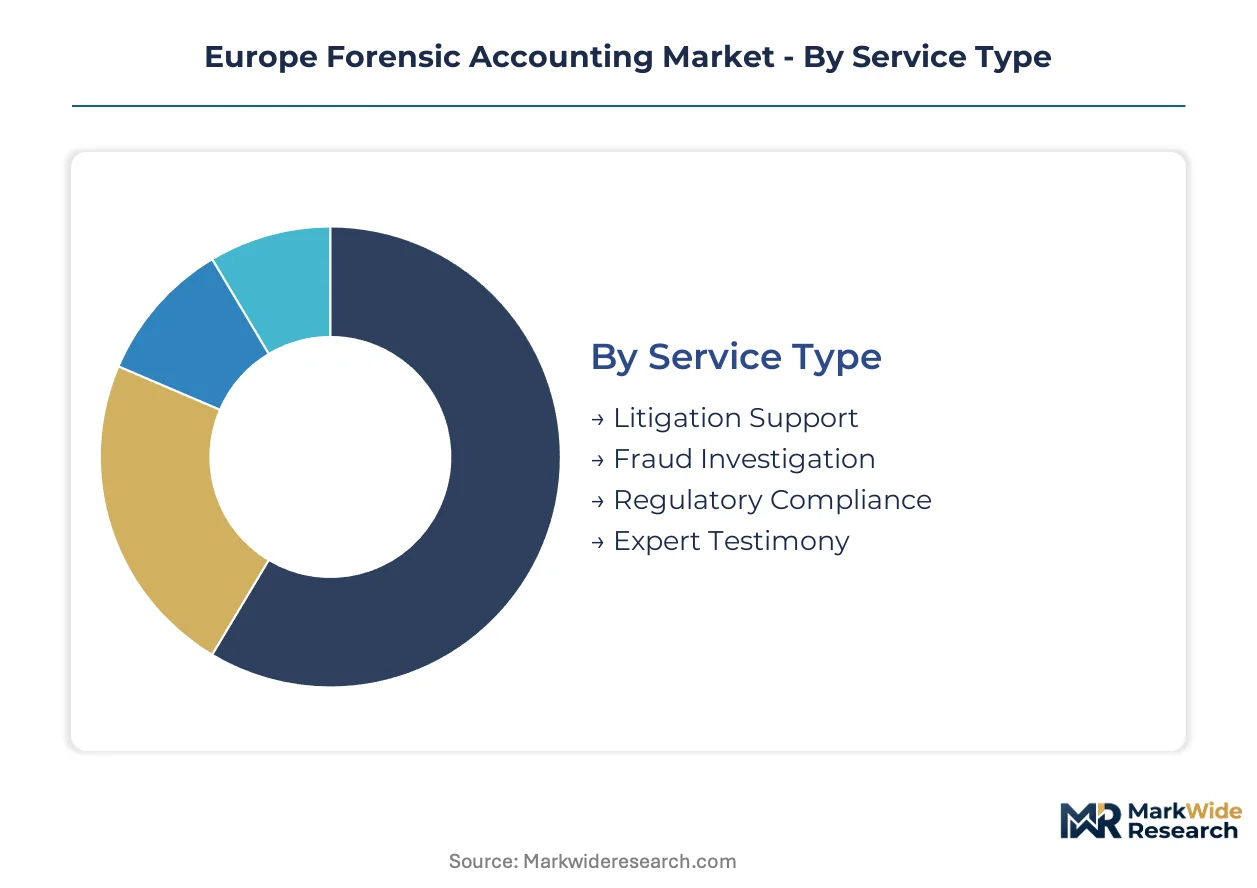
Service specialization and regulatory intensity fragment the Europe Forensic Accounting Market into distinct operational clusters. Each segment demands differentiated capability stacks, from courtroom testimony protocols to real-time transaction monitoring architectures.
Service Type:
Standardized compliance documentation sits at one pole; bespoke litigation support commands premium pricing at the other. The customization spectrum determines staffing ratios, technology investment, and margin profiles across practices.
- Litigation Support:Encompasses expert witness preparation, damage quantification, and arbitration document production for cross-border commercial disputes. Demand concentrates in London and Frankfurt arbitration centers, driven by the European Insolvency Regulation's harmonization of creditor recovery proceedings across member states.
- Fraud Investigation:Asset tracing, financial statement reconstruction, and whistleblower allegation verification form the core mandate. Poland and Romania exhibit the steepest demand acceleration as EU cohesion fund disbursement rules tighten pre-accession transparency requirements for state-owned enterprise transactions.
- Regulatory Compliance:AML documentation, beneficial ownership verification, and suspicious activity report preparation for financial institutions.
- Expert Testimony:Court-appointed forensic accountant services for criminal proceedings and civil fraud trials.
Most installed capacity flows through Litigation Support. Expansion is steepest in Fraud Investigation.
End User:
Procurement sophistication varies sharply across buyer categories, from standardized RFP processes in government agencies to relationship-driven retainers in elite law firms.
- Government Agencies:National financial intelligence units, central federal audit offices, and healthcare fraud prosecutors embed forensic accountants into pharmaceutical pricing investigations. Germany's central federal audit office and France's national health insurance fund sustain the deepest specialist benches.
- Law Firms:Cross-border dispute practices in London, Paris, and Frankfurt directly retain forensic boutiques for sensitive internal investigations, bypassing established audit channels. This procurement pattern concentrates margin pools with sector-focused specialists.
- Corporations:Internal audit functions and legal departments commission forensic verification for M&A due diligence and whistleblower allegations.
- Non-Profit Organizations:Grant compliance verification and donor fund tracing for international development organizations.
Government Agencies anchor volume demand. Law Firms are gaining share fastest as procurement unbundles from traditional audit relationships.
Industry Vertical:
Regulatory density and transaction complexity determine vertical penetration rates, with financial services commanding disproportionate specialist attention.
- Finance:Banking groups in Germany and the Netherlands deploy continuous auditing technology for real-time payment screening. The Sixth Anti-Money Laundering Directive compresses investigation timelines, forcing restructuring around automated suspicious activity flagging.
- Insurance:Claims verification, premium fraud detection, and reinsurance dispute resolution dominate service portfolios. Italian and Spanish national financial intelligence units now require enhanced documentation for complex ownership structures in asset management client onboarding.
- Manufacturing:Supply chain financial verification and procurement fraud investigation for industrial conglomerates.
- Telecommunications:Revenue assurance and intercarrier settlement dispute resolution.
Finance commands the deepest specialist deployment. Insurance is climbing the fastest as AMLA operational launch elevates beneficial ownership verification mandates.
Geographical Focus:
Maturity gradients and regulatory enforcement intensity create distinct capability requirements across European sub-regions.
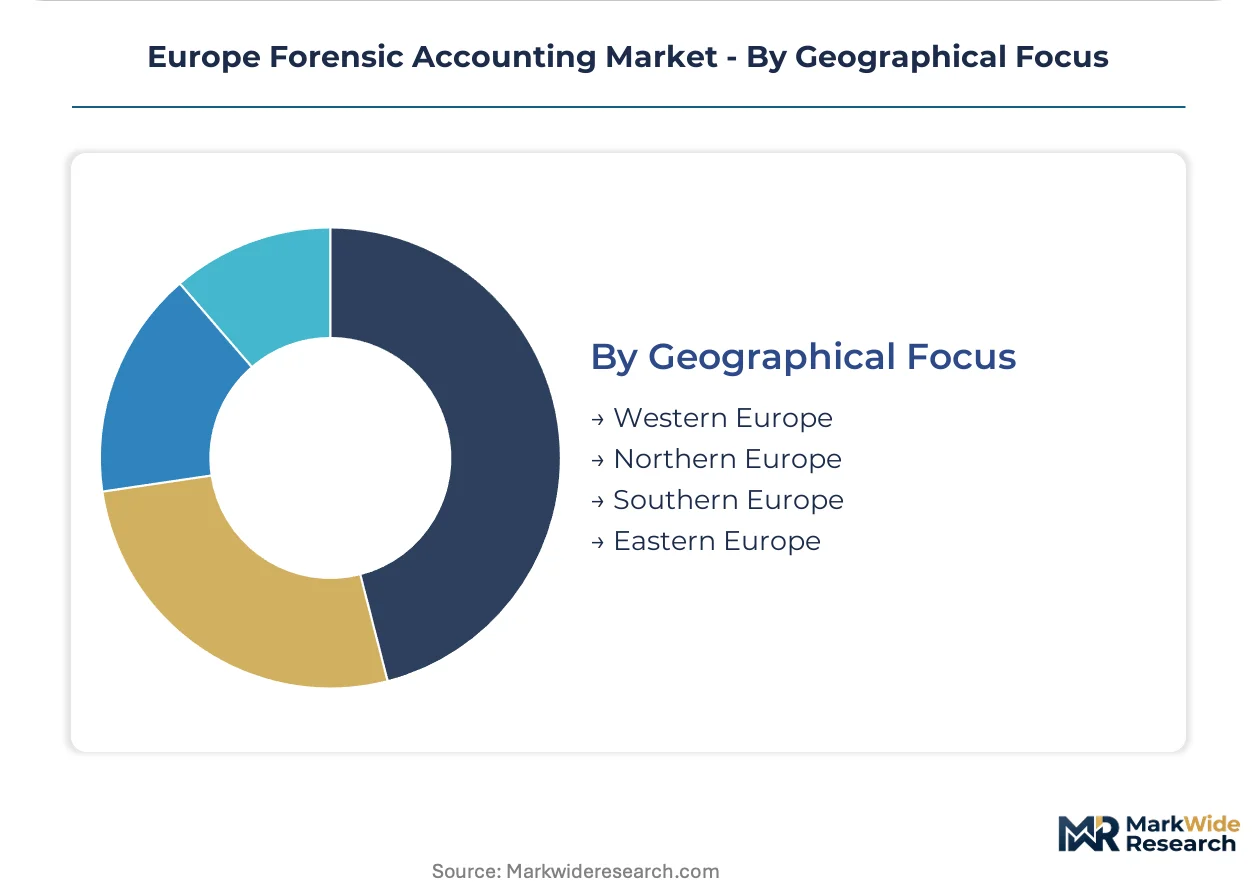
- Western Europe:Complex cross-border arbitration drives sustained expert witness engagement in London and Frankfurt hubs. GDPR constraints on data processing shape evidentiary protocols, requiring practitioners to navigate cross-border disclosure restrictions in multi-jurisdictional disputes.
- Northern Europe:Stringent ESG disclosure rules under the EU CSRD compel enhanced forensic verification of sustainability claims and carbon credit audits. Denmark and Sweden lead in regulatory technology adoption for compliance automation.
- Southern Europe:Healthcare fraud prosecution and pharmaceutical pricing investigations concentrate forensic specialist deployment.
- Eastern Europe:EU accession-related transparency mandates expand corporate due diligence requirements for infrastructure procurement and privatization transactions.
Western Europe retains the largest installed specialist base. Eastern Europe exhibits the steepest expansion trajectory as pre-accession frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates deeper forensic accounting expertise than France, while the United Kingdom sustains more cross-border arbitration demand than either. Regulatory enforcement intensity and litigation sophistication create distinct capability requirements across European sub-regions.
Germany
Frankfurt anchors the continent's deepest bench of certified fraud examiners and regulatory technology investment. The Federal Financial Supervisory Authority (BaFin) embeds forensic specialists into banking supervision protocols under the Sixth Anti-Money Laundering Directive. Munich and Hamburg sustain specialist boutiques for pharmaceutical pricing investigations and healthcare fraud reconstruction.
United Kingdom
London arbitration centers drive sustained expert witness engagement for complex cross-border commercial disputes. GDPR constraints on data processing shape evidentiary protocols, requiring practitioners to navigate disclosure restrictions in multi-jurisdictional cases. The Financial Conduct Authority's enforcement division contracts forensic accountants for market abuse investigations.
France
Paris-based practices concentrate on healthcare fraud prosecution and pharmaceutical pricing investigations. The national health insurance fund embeds forensic specialists into transaction pattern analysis for inflated reimbursement claims. Lyon and Marseille sustain mid-tier boutiques serving manufacturing supply chain verification.
Poland
Warsaw exhibits the steepest demand acceleration as EU cohesion fund disbursement rules tighten pre-accession transparency requirements. Forensic verification expands for state-owned enterprise privatizations and infrastructure procurement. Kraków and Wrocław develop specialist capacity for asset tracing through shell company networks.
Netherlands
Amsterdam and Rotterdam banking groups deploy continuous auditing technology for real-time payment screening. The Dutch Central Bank elevates forensic mandates for beneficial ownership verification in asset management client onboarding. Eindhoven sustains boutiques serving technology sector intellectual property disputes.
Europe Forensic Accounting Market Competitive Landscape
London and Frankfurt producers anchor one tier; Amsterdam and Paris specialists hold differentiated positions in sector-specific niches. The market structures around a consolidated top tier of full-service networks and a fragmented mid-market of boutiques. Three archetypes dominate: global audit-origin practices, litigation-focused independents, and sector-specialist boutiques. Competitive moves concentrate on geographic hub expansion and technology platform licensing.
Within the global audit-origin tier, KPMG International, Deloitte, and BDO International exemplify the scale-driven model. These entities occupy positions defined by cross-border infrastructure and proprietary data analytics deployment. KPMG International represents the network-origin archetype with London and Frankfurt hub concentration. Deloitte anchors a similar positioning with deep benches of certified fraud examiners. BDO International exemplifies the mid-market competitive vector, differentiating through sector-specific methodologies rather than scale alone.
| Leading Market Players |
|---|
| KPMG International |
| Grant Thornton |
| PwC |
| FTI Consulting |
| RSM International |
| Deloitte |
| BDO International |
| Alvarez & Marsal |
| Ernst & Young |
| Others |
Pricing and Supply Chain Analysis
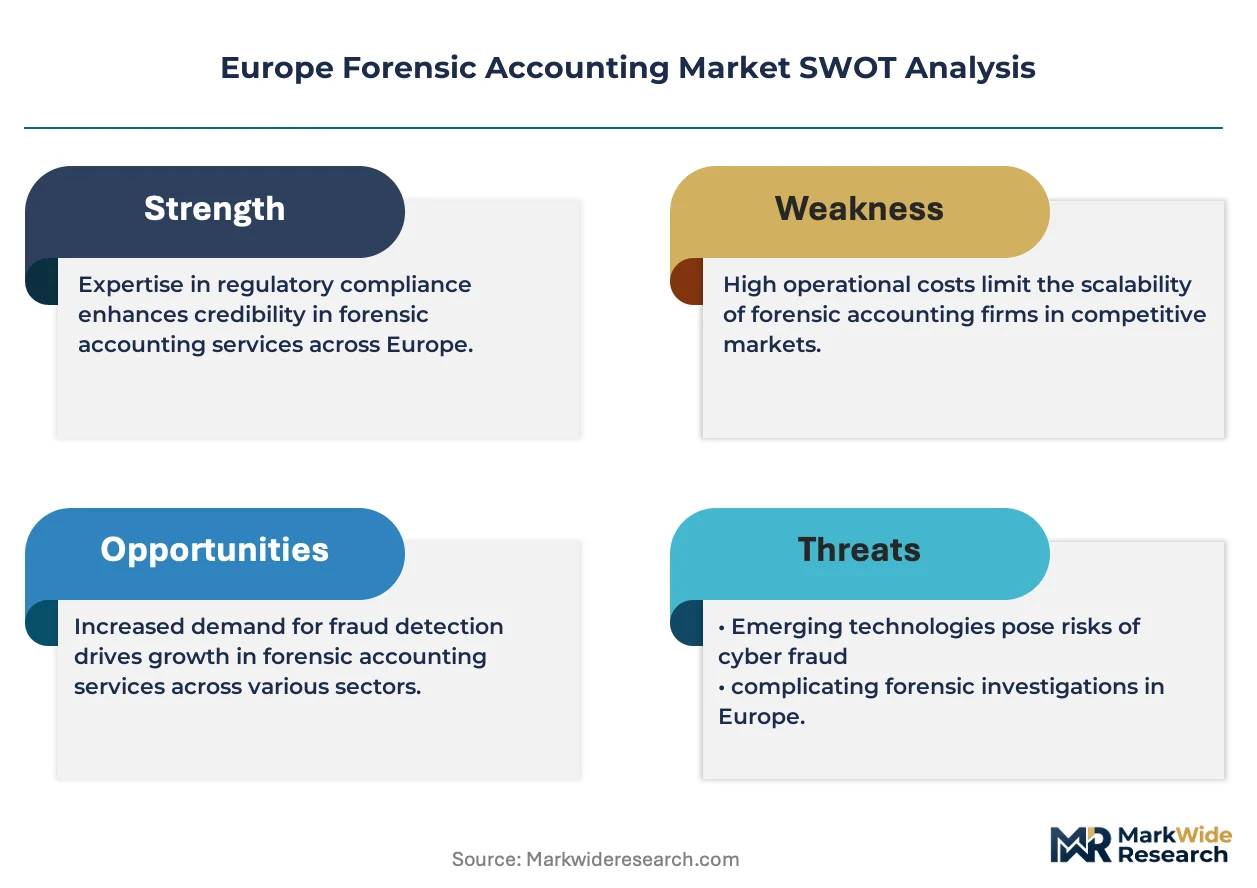
Certification-tier divergence between ENFSI-accredited digital forensics specialists and generalist practitioners splits both pricing power and talent sourcing configurations across European markets. Premium-tier engagements command threefold rate multiples as BaFin and France's national health insurance fund mandate accredited expert witnesses for criminal proceedings, while commodity compliance documentation faces algorithmic substitution from RegTech platforms.
Pricing Analysis
Direct-to-corporate engagements bypass traditional law firm markups and capture margin pools previously absorbed by intermediary channels. Project-based fee structures dominate litigation support, with pricing stratifying across premium, standard, and economy tiers based on certification level and sector specialization depth. Pricing pressure stems from RegTech automation compressing routine AML documentation margins. Mid-market manufacturing clients exhibit highest price sensitivity, while asset management and private banking segments absorb premium rates for beneficial ownership verification.
Supply Chain Analysis
Freight costs for cross-border document transport and physical evidence handling concentrate supply chain friction in multi-jurisdictional disputes. Specialist talent concentrates in the United Kingdom, Germany, and France, with secondary capacity emerging in Poland and Romania. Raw material dependencies include proprietary data analytics software licenses, ENFSI accreditation training programs, and chain-of-custody documentation systems. Single-source vulnerability sits with London and Frankfurt arbitration centers for expert witness qualification. Distribution runs through law firm procurement channels and direct corporate legal department retainers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunity opens between Western Europe's saturated specialist labor pools and Eastern Europe's pre-accession compliance demand, where regulatory intensity lags salary inflation by 40-60 percent.
For Market Incumbents: Lock in certified fraud examiner pipelines through captive training partnerships with Frankfurt School of Finance and Management and London Business School executive programs. Consolidate mid-market boutiques in Warsaw and Bucharest before EU cohesion fund disbursement peaks. Threat of Big Four technology platform licensing erodes boutique differentiation; counter through sector-specific pharmaceutical and energy methodologies that resist standardization.
For New Entrants and Emerging Players: AI-augmented document review capabilities offer entry wedge against incumbent hourly-rate models. Target Polish state-owned enterprise privatization advisory and Romanian infrastructure procurement verification as penetrable white-space segments. Go-to-market angle: fixed-fee e-discovery compression versus traditional time-and-materials litigation support.
For Investors and Strategic Acquirers: Consolidation pressure builds where ENFSI accreditation bottlenecks constrain expert witness supply against accelerating AMLA enforcement mandates. Long-term viability favors sector-specialist boutiques with pharmaceutical pricing investigation or crypto-asset tracing capabilities over generalist compliance documentation practices. Acquisition target archetype: boutiques with 15-25 professionals holding dual accounting and digital forensics competencies. Signal to watch: Dutch Central Bank and BaFin harmonization of beneficial ownership verification standards.
| Strategic Initiative | Industry Significance |
|---|---|
| ENFSI Accreditation Investment | Qualifies practitioners as expert witnesses in German and French criminal proceedings under Sixth AML Directive. |
| AI-Augmented Document Review Platform | Compresses e-discovery timelines for London arbitration centers handling cross-border insolvency disputes. |
| Eastern European Hub Expansion | Captures EU cohesion fund-related forensic verification demand in Warsaw and Bucharest privatization markets. |
| Crypto-Asset Tracing Specialization | Differentiates boutiques under Markets in Crypto-Assets Regulation virtual currency investigation mandates. |
| Continuous Auditing Technology Licensing | Enables real-time payment screening for Dutch and German banking groups facing compressed investigation timelines. |
Research Methodology
Coverage spans Western Europe, Northern Europe, Southern Europe, and Eastern Europe, with primary inputs from each regulatory cluster. Primary interviews combined with secondary validation sourced forensic accounting partners at Big Four networks, boutique practice managing directors, in-house legal counsel at German banking groups, and enforcement officials at France's national health insurance fund. Secondary data drew from BaFin supervision reports, EMA pharmaceutical pricing investigation disclosures, EU Anti-Money Laundering Authority operational frameworks, and ENFSI electronic evidence handling standards. Bottom-up service-line buildups triangulated against top-down regulatory spend estimates.
Rate-of-change decomposition separated volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include service type specialization, end-user procurement sophistication, industry vertical regulatory density, and geographic enforcement intensity. CAGRs derived from regression against AMLA staffing plans, EU CSRD assurance mandate rollouts, and Eastern European accession framework implementation schedules. Industry-specific inputs incorporated pharmaceutical pricing investigation caseload projections and continuous auditing technology adoption curves.
The model holds under steady AMLA operational ramp and sustained EU cohesion fund disbursement; deviation in regulatory harmonization delays or RegTech substitution acceleration would shift trajectory. Forecasts embed assumptions about ENFSI accreditation pathway development and GDPR cross-border disclosure friction persistence. Stakeholders should weight assumptions against their own operating context and client concentration profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Spain Accounting Software Market
Accounting and Taxation Services
Tax Management Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Tax Preparation Services Market
Accounting and Taxation Services
Tax Management Software Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
Finance and Accounting Outsourcing (FAO) Market
Accounting and Taxation Services
Sales Tax Software Market
Accounting and Taxation Services
Canada Accounting Software Market
Accounting and Taxation Services
China Forensic Accounting Market
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
AI in Accounting Market
Accounting and Taxation Services
Construction Accounting Software Market
Accounting and Taxation Services
Accounting Services Market
Accounting and Taxation Services
Tax Compliance Services Market