
 Trust Accounting Software Market | 2026-2036
Trust Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Trust Accounting Software Market Insights
Market Context
Legacy server infrastructure is pivoting toward cloud-native architectures, compressing implementation timelines and reshaping total cost of ownership for legal technology procurement. Clio leverages subscription economics to dominate mid-market law office deployments across North America. Sage Intacct anchors enterprise-grade trust administration with deep financial reporting integration. TrustBooks specializes in solo practitioner workflows, occupying a defensible niche against broader platform competition.
Technical Definition and Segment Structure
Trust accounting software constitutes a specialized financial management application engineered to segregate client funds from operating accounts, enforce three-way reconciliation protocols, and generate court-auditable transaction ledgers for fiduciary oversight. Cloud-based deployment leads segment value generation as law offices prioritize remote accessibility and automatic regulatory update propagation, while on-premise installations retain share among banking institutions with stringent data sovereignty mandates. Subscription licensing captures recurring revenue pools, though usage-based models are gaining traction among escrow services with variable transaction volumes.
Regulatory Framework and Outlook
The American Bar Association Model Rules of Professional Conduct govern client fund handling standards, with state bar associations enforcing disciplinary frameworks that mandate specialized accounting controls. HIPAA intersects trust accounting where health law practices manage settlement proceeds containing protected health information. Stakeholders must monitor evolving state-level fiduciary technology mandates and assess whether hybrid deployment architectures satisfy both accessibility demands and emerging data localization requirements.
Market Dynamics
Cloud-native architecture migration is compressing implementation timelines for legal technology procurement while simultaneously elevating compliance automation requirements across fiduciary practice management.
Growth Catalysts
- State Bar Association Enforcement Intensification:Mandatory three-way reconciliation protocols are driving specialized software procurement across United States jurisdictions. Law offices face disciplinary frameworks that elevate audit-ready transaction ledgers from preference to operational necessity.
- HIPAA Settlement Fund Management:Health law practices managing protected health information within client trust accounts require integrated compliance controls. This intersection creates specialized demand for software with dual regulatory coverage.
- Remote Accessibility Imperatives:Distributed legal workforces require cloud-based deployment architectures that enable secure fund management outside traditional office infrastructure. This operational shift accelerates displacement of on-premise legacy installations.
Market Restraints
- Data Sovereignty Compliance Costs:Banking institutions with stringent jurisdictional data localization mandates face elevated infrastructure expenditure for hybrid deployment architectures. These requirements fragment vendor addressable markets.
- Legacy System Integration Complexity:On-premise accounting platforms with decades of transaction history impose substantial technical debt during cloud migration. Data migration risks and reconciliation continuity requirements extend implementation timelines.
- Substitution by Generalized Financial Platforms:Enterprise resource planning systems with configurable fund segregation modules present competitive pressure for mid-market legal practices with simpler fiduciary structures.
Strategic Opportunities
- Underpenetrated Solo Practitioner Segment:Individual attorneys managing modest trust account volumes represent substantial whitespace for purpose-built solutions with simplified workflow automation. Current generalized tools overserve this demographic.
- Escrow Service Variable Volume Pricing:Usage-based licensing models align software costs with transaction velocity for real estate and corporate escrow providers. This structure captures revenue from previously price-excluded segments.
- API-First Architecture Convergence:Open banking standards and automated clearing house integration enable real-time fund verification workflows. Early movers in embedded financial connectivity will capture workflow centralization benefits.
Industry Challenges
- Fiduciary Accounting Specialization Shortage:Software implementation teams with dual expertise in legal compliance frameworks and cloud architecture command premium compensation. Talent scarcity extends deployment timelines for complex multi-jurisdiction configurations.
- Certification Timeline Variability:State-by-state bar association technology approval processes lack standardization. Vendors must navigate fragmented regulatory validation requirements that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trust Accounting Software Market |
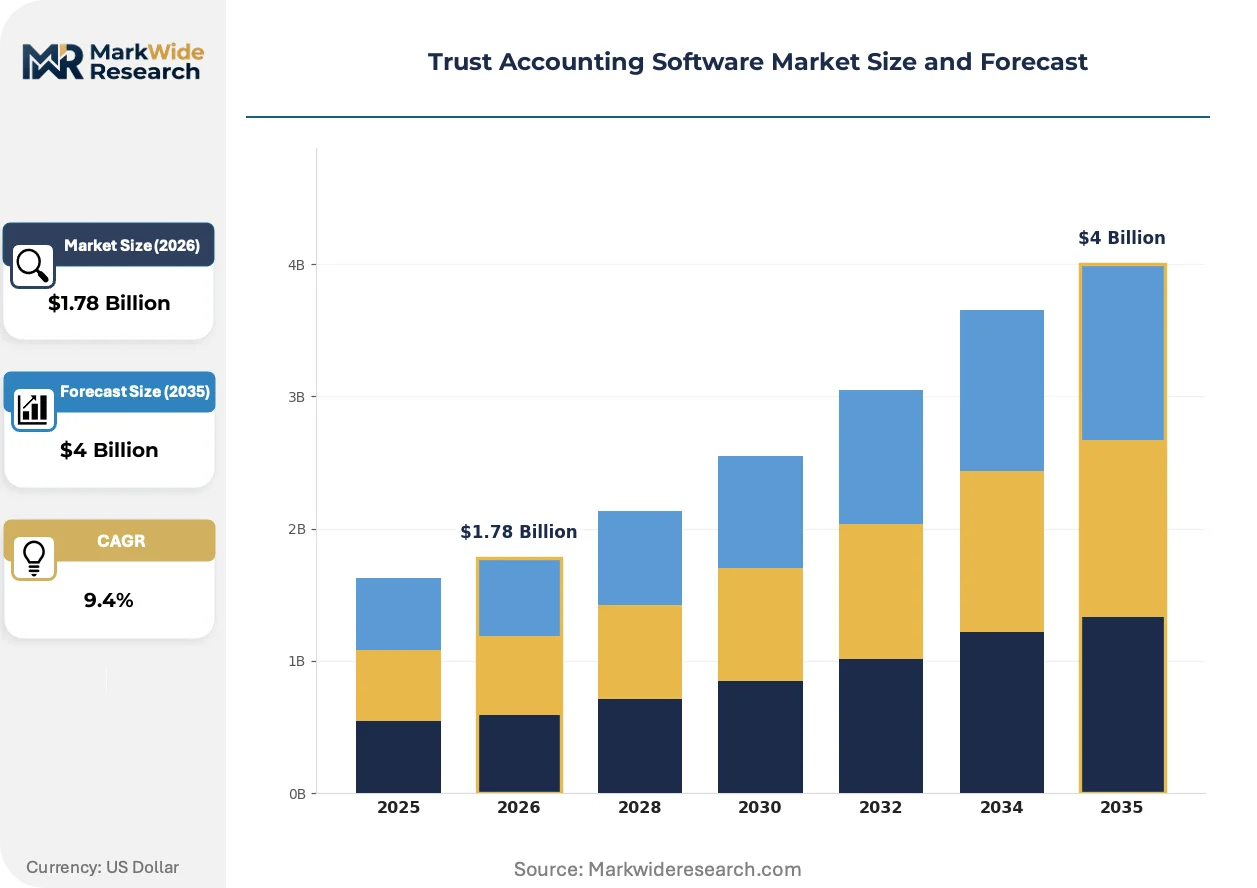
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $4 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based Application: Legal Firms, Financial Advisors, Escrow Services, Estate Planning, Real Estate Management End User: Law Offices, Wealth Management Firms, Title Companies, Banking Institutions, Trust Administrators License Type: Subscription, Perpetual, Usage-Based, Freemium |
| Companies Covered | Clio, TrustBooks, CosmoLex, PracticePanther Legal Software, Zoho Books, Sage Intacct, Tabs3, Centerbase, Delta Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trust Accounting Software Market Trends and Innovations
Artificial intelligence and machine learning capabilities are embedding into core reconciliation engines, transforming exception handling from manual review to automated classification while raising new audit trail documentation requirements.
Embedded banking APIs are integrating directly into trust accounting platforms, enabling real-time balance verification and automated transaction posting without manual bank portal reconciliation. Mid-sized law offices in the United States are adopting these connections fastest, compressing monthly reconciliation cycles from days to hours and reducing overdraft exposure through proactive low-balance alerts.
The American Bar Association Model Rules amendments regarding technology competence are compelling state bar associations to issue specific guidance on automated fund handling systems. This regulatory momentum is elevating software procurement from operational discretion to ethical obligation, with California and New York bar committees issuing the most prescriptive technology competency frameworks.
Subscription licensing fatigue is prompting mid-market legal practices to evaluate total cost of ownership more rigorously against perpetually licensed alternatives with modernized support structures. Buyers are unbundling implementation services from core software fees and negotiating data portability guarantees upfront, with this behavior most visible among multi-office regional firms consolidating disparate legacy systems.
Trust Accounting Software Market Segmentation
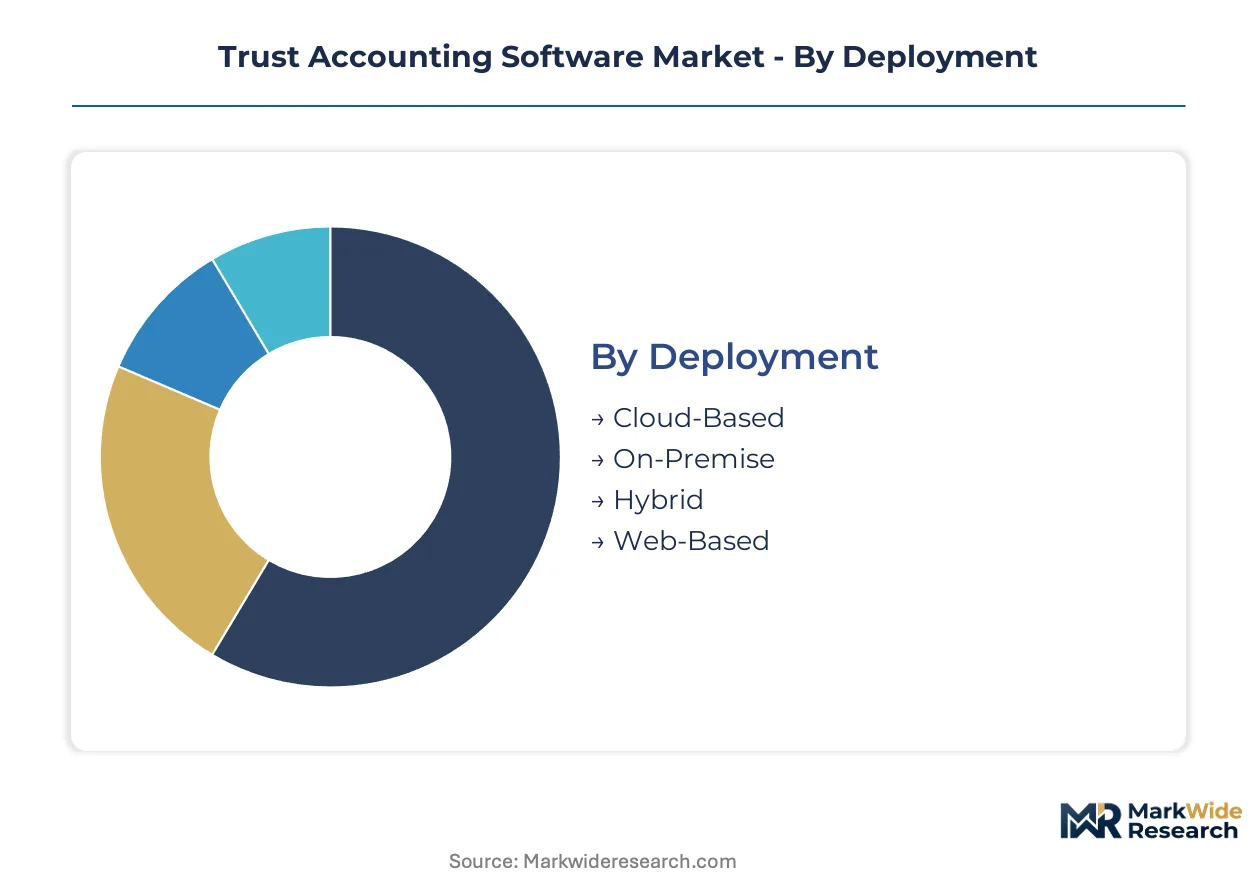
Deployment architecture fundamentally determines compliance automation capabilities and total cost of ownership for fiduciary practitioners. Application focus shapes regulatory coverage requirements and integration complexity. License economics directly influence vendor selection criteria across practice size tiers.
Deployment:
Cloud-native infrastructure dominates new procurement as remote accessibility requirements reshape legal technology procurement patterns.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic regulatory update propagation and eliminate server maintenance overhead. Law offices across the United States legal technology corridor prioritize these deployments for distributed workforce enablement and compressed implementation timelines.
- On-Premise:Dedicated server installations within client-controlled data centers satisfy stringent data sovereignty mandates. Banking institutions with jurisdictional localization requirements retain this architecture despite elevated capital expenditure and extended procurement cycles.
- Hybrid:Split configurations maintain sensitive transaction processing on local infrastructure while leveraging cloud accessibility for reporting functions. Title companies navigating state-by-state data residency rules adopt this model to balance compliance with operational flexibility.
- Web-Based:Browser-accessible platforms without full cloud backend integration serve cost-sensitive solo practitioners. These lightweight deployments sacrifice advanced automation for accessibility and minimal setup requirements.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
Application:
Regulatory complexity varies dramatically across fiduciary use cases, driving specialized feature requirements and certification priorities.
- Legal Firms:Matter-based fund segregation with three-way reconciliation protocols and court-auditable ledgers. State bar association disciplinary frameworks mandate specialized controls, with HIPAA intersecting health law practices managing settlement proceeds containing protected health information.
- Financial Advisors:Investment advisory custody account management with SEC compliance documentation. Fee-based advisory practices require automated billing allocation from pooled trust structures.
- Escrow Services:Transaction-specific fund holding with milestone-based release automation. Real estate and corporate escrow providers demand usage-based pricing alignment with variable transaction volumes.
- Estate Planning:Multi-generational asset distribution tracking with beneficiary notification workflows. Complex probate timelines require long-term record retention beyond standard accounting periods.
- Real Estate Management:Tenant security deposit handling with jurisdiction-specific interest calculation requirements. Property managers navigate fragmented state landlord-tenant regulations governing fund segregation.
Established compliance sits with Legal Firms. Expanding most quickly is Escrow Services.
End User:
Organization scale determines workflow complexity tolerance and integration depth requirements across the fiduciary ecosystem.
- Law Offices:Solo practitioners through multi-office regional firms managing client retainer and settlement funds. The American Bar Association Model Rules enforcement elevates software procurement from preference to ethical obligation.
- Wealth Management Firms:High-net-worth custody operations requiring consolidated reporting across multiple fiduciary structures. Family office complexity demands multi-currency and multi-jurisdictional capabilities.
- Title Companies:Real estate closing fund management with lender integration requirements. Underwriters mandate specific reconciliation frequencies and error resolution protocols.
- Banking Institutions:Corporate trust departments with legacy core system integration challenges. Decades of transaction history impose substantial technical debt during platform migration.
- Trust Administrators:Independent fiduciary service providers managing diverse account types for multiple beneficiaries. Operational efficiency pressures drive automation prioritization over customization depth.
Deep integration sits with Banking Institutions. Workflow simplification demand concentrates in Law Offices.
License Type:
Commercial models align vendor revenue with customer value realization across transaction volume predictability spectrums.
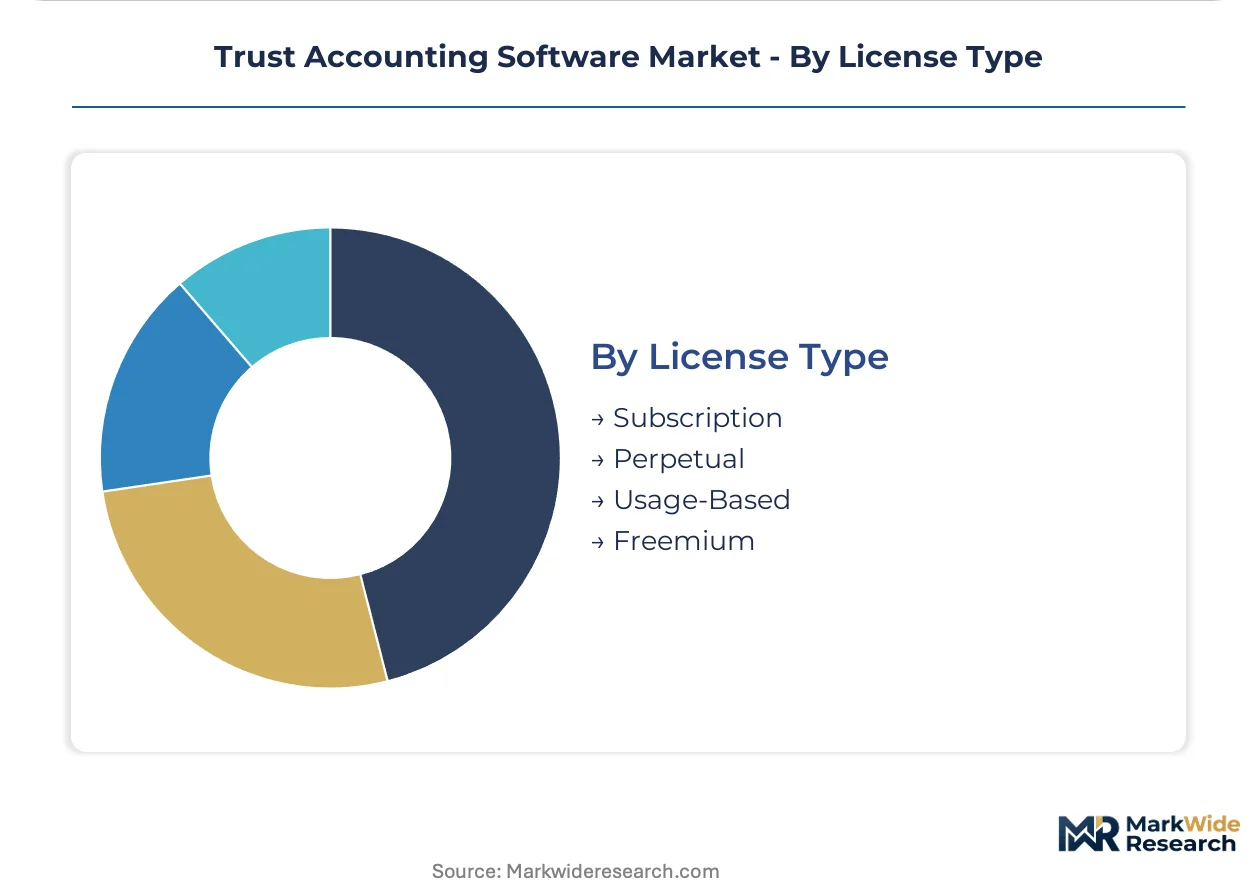
- Subscription:Recurring annual or monthly fees with inclusive updates and support. Mid-market legal practices dominate this segment, though subscription fatigue is prompting total cost of ownership reevaluation.
- Perpetual:One-time license purchase with separate maintenance agreements. Regional firms consolidating disparate legacy systems negotiate data portability guarantees upfront with these arrangements.
- Usage-Based:Transaction-volume or account-count pricing scales with operational activity. Escrow services with seasonal fluctuation capture revenue from previously price-excluded segments through this structure.
- Freemium:Core functionality at no cost with premium feature upgrades. Solo practitioners with modest trust account volumes represent substantial whitespace for purpose-built solutions against generalized tools.
Revenue concentration sits with Subscription. Emerging model traction is concentrated in Usage-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States law offices generate the dominant share of demand for fiduciary compliance technology, with cloud deployment architectures displacing legacy infrastructure across major legal corridors. State bar association enforcement intensification drives procurement urgency in jurisdictions with active disciplinary frameworks.
United States
HIPAA intersects trust accounting where health law practices manage settlement proceeds containing protected health information. The American Bar Association Model Rules of Professional Conduct govern client fund handling standards, with state bar associations enforcing specialized accounting controls. California and New York bar committees issue the most prescriptive technology competency frameworks, elevating software procurement from operational discretion to ethical obligation.
United Kingdom
English and Welsh law firms navigate Solicitors Regulation Authority client money rules alongside GDPR data protection requirements for beneficiary information. The SRA Accounts Rules mandate three-way reconciliation protocols that mirror American fiduciary standards. London's financial-legal district concentrates demand for multi-currency trust administration among international practices managing cross-border settlements.
Germany
German Rechtsanwälte face Bundesrechtsanwaltsordnung custody account regulations with strict documentation requirements for client fund segregation. The Federal Bar Association enforces disciplinary frameworks that elevate audit-ready transaction ledgers to operational necessity. Frankfurt's banking-legal nexus drives demand for hybrid deployment architectures that satisfy data localization mandates while enabling remote accessibility.
Canada
Canadian law societies enforce provincial trust accounting guidelines with varying reconciliation frequency requirements across Ontario, British Columbia, and Quebec. The Law Society of Ontario mandates specialized software controls for client fund handling that align with American Bar Association standards. Toronto's legal technology corridor concentrates cloud-native procurement among mid-market firms consolidating legacy practice management systems.
Australia
Australian legal practices navigate Law Society uniform rules for trust money management with state-level variation in compliance automation requirements. The Australian Solicitors' Conduct Rules mandate segregation protocols that drive specialized software procurement. Sydney and Melbourne legal districts concentrate demand for subscription-based deployment among distributed law firms prioritizing remote workforce enablement.
Trust Accounting Software Market Competitive Landscape
Strategic partnership formation dominates the current landscape as vendors integrate embedded banking APIs and compliance automation modules. The vendor base stratifies across three tiers: cloud-native specialists with legal workflow expertise, enterprise financial platforms with configurable fiduciary modules, and generalized accounting software with trust segregation add-ons. Competitive positioning depends on bar association certification velocity and implementation timeline compression. M&A activity and API-first architecture development represent the dominant competitive vectors reshaping market structure.
Within the cloud-native specialist tier, Clio and TrustBooks exemplify divergent scale strategies. Clio leverages subscription economics to anchor mid-market law office deployments across North America. TrustBooks occupies a defensible niche against broader platform competition through solo practitioner workflow specialization. Sage Intacct represents the enterprise financial platform archetype, anchoring trust administration with deep financial reporting integration for complex multi-entity structures.
| Leading Market Players |
|---|
| Clio |
| TrustBooks |
| CosmoLex |
| PracticePanther Legal Software |
| Zoho Books |
| Sage Intacct |
| Tabs3 |
| Centerbase |
| Delta Data |
| Others |
Pricing and Supply Chain Analysis
State bar association technology certification mandates gate qualified vendor participation and premium-tier pricing access for law offices seeking compliant fiduciary management platforms. Banking institutions with data sovereignty requirements face elevated infrastructure expenditure that fragments addressable supply tiers.
Pricing Analysis
Volume concentration in subscription licensing competes against margin capture in usage-based models for escrow services with variable transaction profiles. Pricing stratifies across premium, standard, and economy tiers based on bar association certification velocity and integration complexity with legacy practice management systems. Cost compression in mid-market SaaS tiers intensifies as generalized financial platforms introduce configurable fund segregation modules. Solo practitioners exhibit highest price sensitivity, while enterprise banking institutions prioritize compliance automation over licensing expenditure.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate multi-region qualification among United States, Ireland, and Singapore data center operators serving legal technology vendors. Software development draws from specialized compliance engineering talent pools concentrated in California, New York, and London financial-legal corridors. Single-source vulnerability sits with embedded banking API providers where real-time transaction verification hinges on proprietary clearing house connections. Distribution runs through direct sales teams for enterprise deployments and channel partners for mid-market law office penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architecture migration is displacing legacy on-premise installations across fiduciary practice management, compressing implementation timelines while elevating compliance automation requirements.
For Market Incumbents: Hedge against substitution pressure from generalized ERP platforms by deepening vertical integration into state-level bar association certification workflows. Accelerate API-first architecture development to capture embedded banking connectivity advantages before open banking standards commoditize transaction verification layers. For New Entrants and Emerging Players: Launch via freemium distribution targeting solo practitioners with purpose-built workflow automation that generalized tools overserve. Capture whitespace in real estate escrow services with usage-based pricing alignment to seasonal transaction fluctuation patterns. For Investors and Strategic Acquirers: State bar association technology competency framework amendments are the leading indicator that procurement urgency will concentrate in jurisdictions with active disciplinary enforcement. Long-term viability favors acquisition targets with multi-jurisdiction certification velocity and compressed implementation timeline capabilities. Monitor HIPAA settlement fund management specialization as signal for dual regulatory coverage premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Open banking standards enable real-time fund verification workflows that compress monthly reconciliation cycles. |
| Bar Association Certification Investment | California and New York prescriptive frameworks elevate software procurement from preference to ethical obligation. |
| Embedded Banking Partnership | Automated clearing house integration reduces overdraft exposure through proactive low-balance alerts. |
| Solo Practitioner Workflow Specialization | Freemium models capture substantial whitespace against generalized tools that overserve modest trust account volumes. |
| Hybrid Deployment Architecture | Split configurations satisfy data localization mandates while enabling remote accessibility for title companies. |
Research Methodology
SEC filings, state bar association disciplinary records, and cloud infrastructure expenditure disclosures formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with trust accounting software product managers, legal technology procurement officers at mid-market law firms, state bar association technology committee members, and embedded banking API integration specialists validated segmentation assumptions and pricing dynamics. Bottom-up deployment model penetration estimates triangulated against top-down legal technology corridor expenditure analysis.
Historical trendline analysis across cloud adoption curves and regulatory enforcement intensity patterns anchored projection modeling throughout the forecast period. Segmentation dimensions included deployment architecture, application focus, organization scale tier, and license economics. CAGRs derived from technology substitution rate analysis and compliance automation penetration benchmarks. Industry-specific inputs incorporated bar association certification timeline variability and HIPAA intersection demand for health law practices.
Regulatory mandate acceleration, embedded banking API standardization delays, and generalized ERP platform substitution are the dominant revision risks to current outlook assumptions. Deviation in state-level fiduciary technology enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Cloud Accounting Software Market
Accounting and Taxation Services
US Accounting Software Market
Accounting and Taxation Services
France Forensic Accounting Market
Accounting and Taxation Services
Tax Automation Software Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Accounting Services Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
Asia-Pacific Accounting & Budgeting Software Market
Accounting and Taxation Services
UK Forensic Accounting Market
Accounting and Taxation Services
Saudi Arabia Forensic Accounting Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
United Kingdom Accounting Software Market
Accounting and Taxation Services
Tax Management Software Market