
 Europe Accounting Software Market | 2026-2036
Europe Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Accounting Software Market Analytics
Cloud-native architecture is broadening the addressable base for accounting software vendors across Europe. SAP leverages its deep ERP integration to anchor enterprise deployments in German-speaking markets. Sage competes through specialized offerings for mid-market British and Irish businesses. Xero sustains growth by dominating cloud-based subscriptions among smaller European traders seeking multi-entity consolidation.
Europe accounting software encompasses systems that automate general ledger maintenance, accounts payable and receivable processing, tax computation, and regulatory reporting through configurable rule engines and API-connected bank feeds. These platforms serve chiefly to reduce manual reconciliation effort and ensure compliance with jurisdiction-specific VAT and corporate filing requirements. Cloud-based deployment leads volume growth as real-time analytics and mobile access features reshape buyer expectations, while on-premises solutions retain share among large corporations with stringent data residency policies. Payroll management and tax management functionality command premium pricing due to the complexity of cross-border European labor and fiscal regulations.
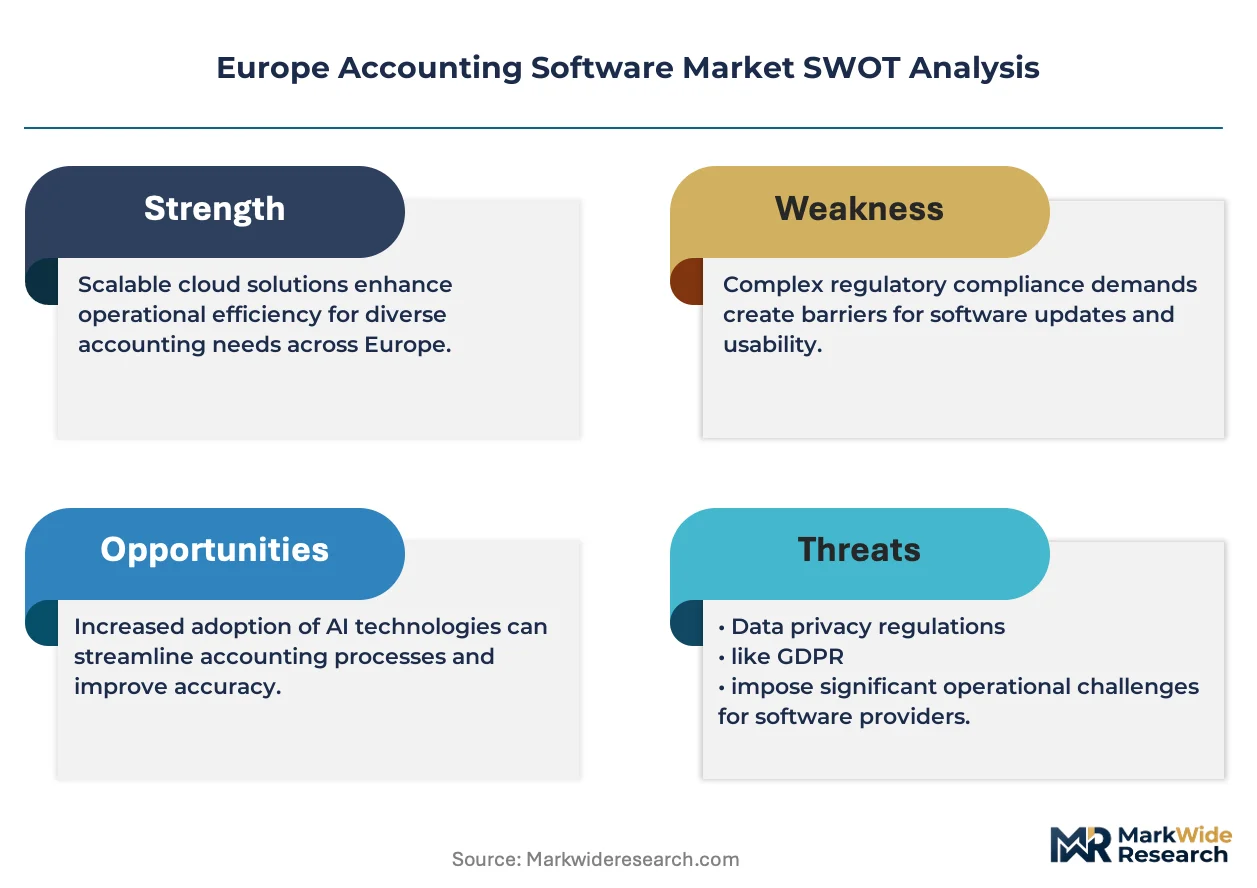
The EU AI Act and GDPR impose algorithmic transparency and data processing constraints on automated accounting systems, while DORA mandates operational resilience testing for financial software providers. EMA and national banking supervisors in Frankfurt, Paris, and London coordinate scrutiny of software used in regulated financial reporting. Stakeholders must monitor how the European Commission's forthcoming standardization mandates for e-invoicing and real-time reporting will reshape product roadmaps and customer migration timelines.
Market Dynamics
The EU's Digital Operational Resilience Act (DORA) is compelling accounting software vendors to rearchitect platforms for continuous availability and granular audit trails, reshaping competitive positioning across German, French, and British procurement cycles.
Growth Catalysts
- Cross-border e-invoicing mandates:The European Commission's standardization push for real-time VAT reporting is forcing mid-sized enterprises to upgrade from spreadsheet-based workflows to API-connected platforms.
- Cloud migration tailwinds:German automotive suppliers and French pharmaceutical distributors are replacing on-premises SAP installations with modular SaaS alternatives to reduce IT overhead.
- GDPR-compliant automation:Demand for consent-aware data processing in payroll and tax modules is pulling specialized vendors into the mid-market segment.
Market Restraints
- Data residency requirements:French and German banking supervisors mandate local server presence for financial reporting software, fragmenting vendor infrastructure investments.
- Legacy ERP entrenchment:SAP's captive base in DACH markets creates switching friction exceeding 18-24 months for full cloud migration.
- Skills scarcity:Shortage of accountants fluent in both IFRS and national GAAP variants limits adoption of automated consolidation tools.
Strategic Opportunities
- Polish and Romanian mid-market penetration:Under-served manufacturing clusters in these markets lack localized payroll functionality, creating white space for compliant entrants.
- AI-embedded reconciliation:Convergence of machine learning with open banking APIs enables real-time anomaly detection for multi-entity traders.
- CSRD reporting modules:The Corporate Sustainability Reporting Directive creates premium pricing power for vendors integrating carbon accounting with financial statements.
Industry Challenges
- Interoperability with legacy ledgers:Mid-market buyers in Italy and Spain operate heterogeneous ERP estates that resist standardized API connections.
- DORA compliance timelines:Operational resilience testing deadlines compress vendor development roadmaps while straining QA resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Accounting Software Market |
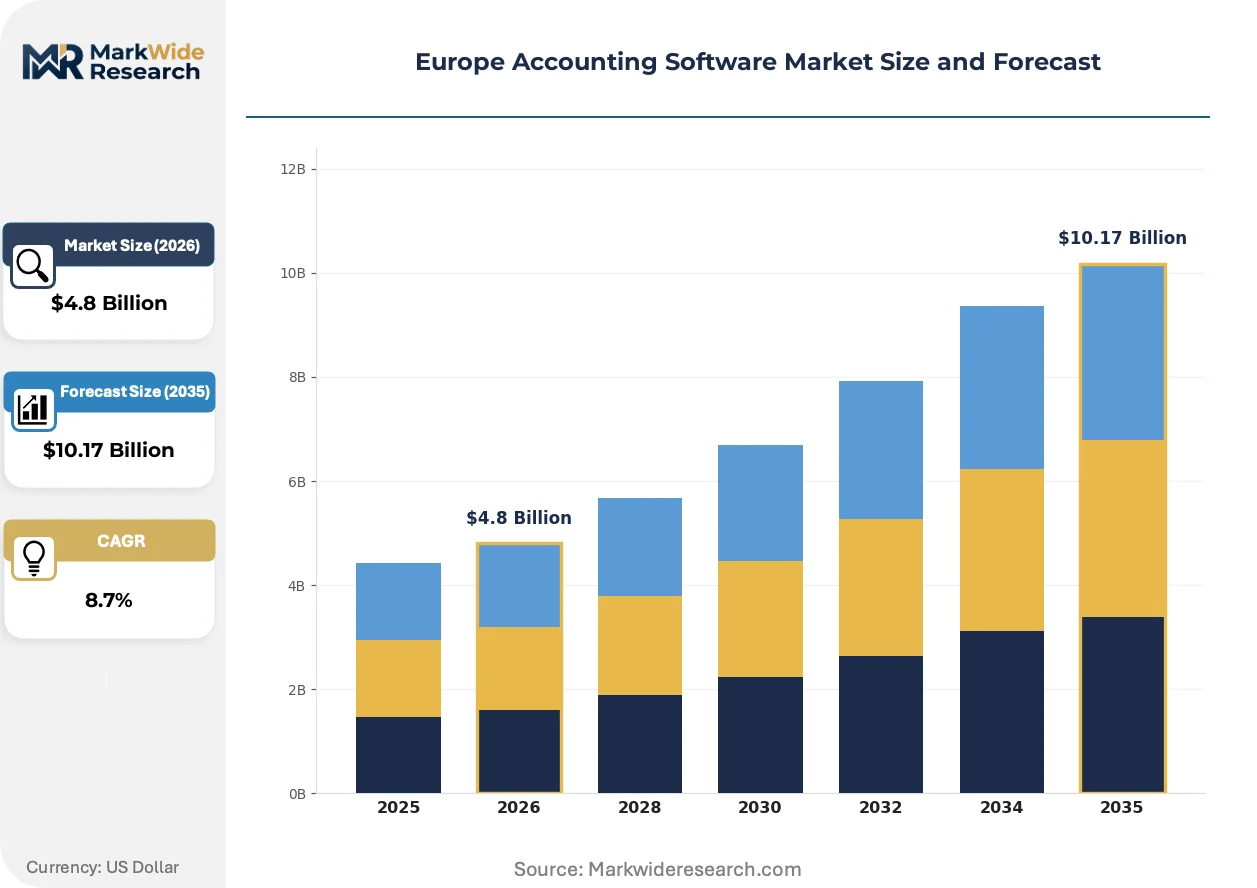
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Small Businesses, Medium Enterprises, Large Corporations, Freelancers Solution: Invoicing, Expense Tracking, Payroll Management, Financial Reporting Feature: Multi-Currency Support, Tax Management, Real-Time Analytics, Mobile Access |
| Companies Covered | SAP, Xero, Sage, Microsoft, Intuit, Wolters Kluwer, Oracle NetSuite, Workday, Unit4, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Accounting Software Market Evolving Landscape
Real-time data architectures and embedded regulatory compliance are compressing implementation cycles and reshaping how European finance teams evaluate software procurement.
API-first cloud platforms are overtaking monolithic on-premises deployments as the default architecture for new accounting software procurement. Mid-sized British and Irish professional services firms are adopting these systems within 90-day implementation windows. This shift is compressing addressable market definitions, as vendors without native bank connectivity lose RFP consideration.
The EU AI Act's algorithmic transparency requirements are mandating explainable automation in tax computation modules. Vendors must now document decision pathways for VAT classification engines. German-speaking enterprise buyers are prioritizing vendors with pre-certified AI governance frameworks, creating procurement segmentation between compliant and non-compliant suppliers.
Subscription unbundling is fragmenting traditional software bundles into component purchases. French and Dutch accounting practices are procuring reconciliation, payroll, and reporting modules from separate specialists rather than single-suite vendors. This pattern is most visible in the Benelux region, where multi-entity structures favor best-of-breed integration over unified platforms.
Europe Accounting Software Market Segmentation
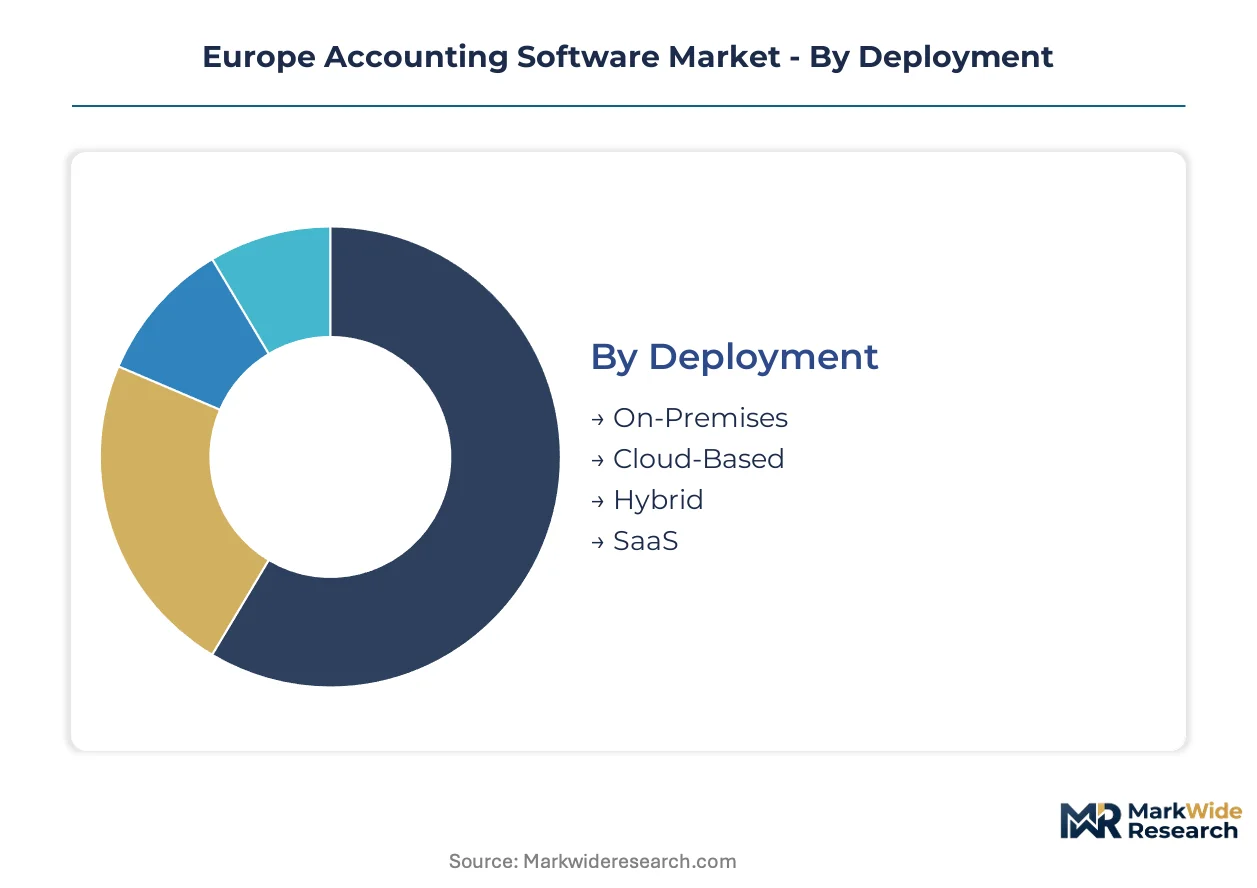
Segmentation in the Europe accounting software market reveals how deployment architecture, user scale, and functional depth determine vendor go-to-market strategies. Procurement patterns diverge sharply between standalone cloud subscriptions and ERP-embedded modules.
Deployment:
Integration depth varies dramatically across deployment modes, with standalone cloud platforms serving agile mid-market buyers while hybrid architectures preserve legacy ledger connectivity.
- On-Premises:Perpetual-license software installed within client data centers, governed by strict data residency policies from German and French banking supervisors. Large automotive manufacturers in Stuttgart and Wolfsburg retain these systems for audit trail sovereignty despite higher total cost of ownership.
- Cloud-Based:Fully hosted multi-tenant platforms with API-native bank connectivity and automatic regulatory updates. British professional services firms in London and Manchester are migrating to these systems within compressed 90-day implementation windows to satisfy real-time VAT reporting mandates.
- Hybrid:Split architectures keeping sensitive payroll data on local servers while routing transactional workflows through cloud gateways. French pharmaceutical distributors favor this model for GDPR-compliant workforce data processing.
- SaaS:Subscription-priced modular platforms with granular feature toggles and usage-based scaling. Dutch accounting practices procure reconciliation and tax modules separately through this delivery model.
Cloud-based deployments lead volumes today; SaaS is gaining share fastest as subscription unbundling fragments traditional suite purchases.
End User:
Cost tier segmentation separates commodity self-service tools from premium enterprise platforms with dedicated implementation support.
- Small Businesses:Owner-operated traders with simplified VAT obligations and single-entity structures. Polish and Romanian manufacturing clusters show rising demand for localized payroll functionality in this bracket.
- Medium Enterprises:Multi-entity organizations with cross-border consolidation needs and dedicated finance teams. German automotive suppliers and French pharmaceutical distributors are replacing legacy SAP installations with modular alternatives here.
- Large Corporations:Complex groups with heterogeneous ERP estates and stringent operational resilience requirements under DORA. These buyers command premium pricing for CSRD-integrated carbon accounting modules.
- Freelancers:Solo practitioners requiring basic invoicing, expense capture, and simplified tax filing. Mobile-first platforms with bank feed automation dominate this price-sensitive segment.
Medium enterprises anchor current revenue; large corporations are expanding most quickly as DORA compliance deadlines accelerate replacement cycles.
Solution:
Application-focused segmentation tracks which functional modules command standalone procurement versus bundled suite inclusion.
- Invoicing:Core AR automation with e-invoice generation and PEPPOL network connectivity. Spanish and Italian mid-market buyers prioritize solutions interoperable with heterogeneous legacy ledgers.
- Expense Tracking:Receipt capture, mileage logging, and policy enforcement workflows. Real-time analytics integration is reshaping buyer expectations in British and Irish professional services.
- Payroll Management:Cross-border labor compliance with jurisdiction-specific social contribution calculations. Complexity of French and German labor regulations supports premium pricing in this module.
- Financial Reporting:Automated consolidation, audit trail generation, and regulator-ready disclosure packages. EU AI Act algorithmic transparency requirements are mandating explainable automation here.
Financial reporting leads module revenues today; payroll management is climbing the fastest as cross-border workforce expansion intensifies.
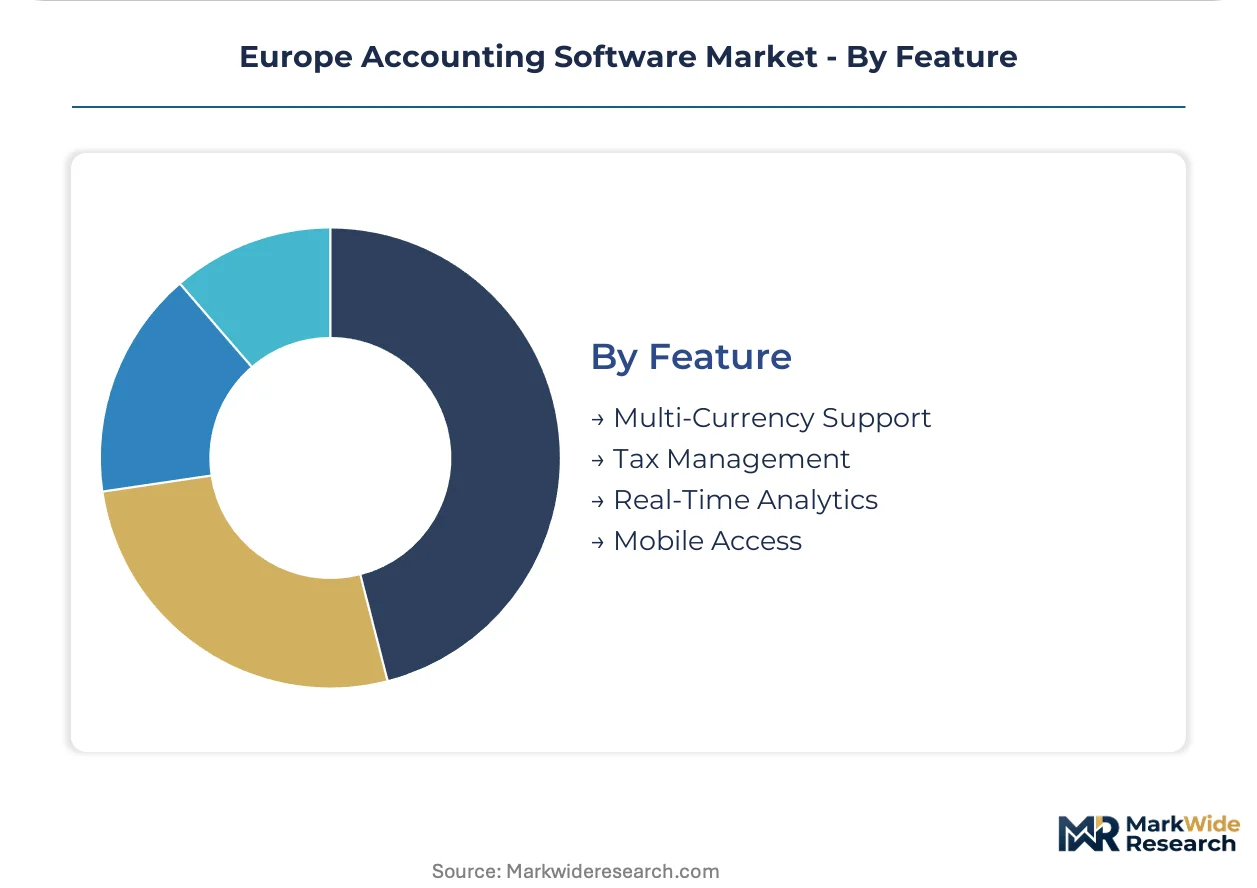
Feature:
Maturity differentiation separates baseline functionality from advanced capabilities that reshape competitive RFP outcomes.
- Multi-Currency Support:Automated exchange rate feeds, hedge accounting, and consolidated reporting across functional currencies. Essential for Benelux multi-entity structures with extensive cross-border trade.
- Tax Management:Jurisdiction-specific VAT engines with real-time classification and filing deadline tracking. German-speaking enterprise buyers prioritize vendors with pre-certified AI governance frameworks here.
- Real-Time Analytics:Continuous close capabilities, anomaly detection, and predictive cash flow forecasting. Open banking API convergence enables machine-learning-embedded reconciliation in this feature set.
- Mobile Access:Native iOS and Android applications for approval workflows, receipt capture, and dashboard monitoring. Reshapes buyer expectations among smaller European traders seeking operational flexibility.
Tax management leads feature-driven purchasing today; real-time analytics shows the steepest expansion trajectory as continuous close methodologies spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters and French pharmaceutical distributors anchor software procurement volumes across the continent. Cross-border trade intensity and regulatory fragmentation create divergent national adoption patterns. The EU's harmonization push for e-invoicing and real-time reporting accelerates upgrade cycles unevenly.
Germany
Stuttgart and Wolfsburg automotive manufacturers drive demand for ERP-integrated financial modules with audit trail sovereignty. DORA operational resilience testing mandates from the Federal Financial Supervisory Authority compress vendor certification timelines. Bavarian mid-market suppliers are replacing legacy SAP installations with modular SaaS alternatives to reduce IT overhead.
France
Parisian banking supervisors enforce data residency requirements for payroll processing systems handling cross-border workforce data. The CNIL mandates GDPR-compliant consent frameworks for automated tax classification engines. Lyon and Marseille pharmaceutical distributors favor hybrid architectures keeping sensitive workforce data on local servers.
United Kingdom
London and Manchester professional services firms migrate to cloud-native platforms within 90-day implementation windows. HMRC's Making Tax Digital program forces mid-sized enterprises to abandon spreadsheet-based workflows. British accounting practices are unbundling subscriptions to procure reconciliation and reporting modules from separate specialists.
Netherlands
Amsterdam and Rotterdam multi-entity trading houses require multi-currency consolidation tools for extensive cross-border commerce. The Dutch Tax Administration's real-time VAT reporting mandates pull mid-market buyers toward API-connected platforms. Randstad region accounting firms lead adoption of subscription-unbundled procurement patterns.
Poland
Warsaw and Krakow manufacturing clusters show rising demand for localized payroll functionality in underserved mid-market segments. Polish Labour Code complexity creates white space for compliant entrants with jurisdiction-specific social contribution engines. These industrial centers lack the localized functionality that Western European vendors have built over decades.
Europe Accounting Software Market Competitive Landscape
Global majors compete with regional champions across deployment architecture and regulatory specialization. The vendor base splits between ERP-anchored incumbents and cloud-native challengers. Two strategic archetypes dominate: enterprise suite providers with deep integration capabilities, and modular specialists with rapid implementation velocity. M&A activity concentrates on acquiring compliance-certified modules, while geographic expansion targets under-served Central European markets.
Within the enterprise suite tier, SAP and Oracle NetSuite occupy positions anchored by ERP integration depth. Sage and Xero exemplify the modular specialist archetype with cloud-native delivery models. These four companies represent the competitive poles shaping procurement segmentation between integrated platforms and best-of-breed alternatives.
| Leading Market Players |
|---|
| SAP |
| Xero |
| Sage |
| Microsoft |
| Intuit |
| Wolters Kluwer |
| Oracle NetSuite |
| Workday |
| Unit4 |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure costs cascade through subscription tiers as vendors pass through hyperscaler compute and storage expenses to German automotive suppliers and British professional services firms purchasing modular SaaS licenses.
Pricing Analysis
Input-cost pass-through from AWS and Azure hyperscaler contracts shapes SaaS subscription tiers across the European market. Pricing stratifies across premium compliance-certified suites, standard mid-market packages, and economy self-service tools based on DORA certification status and implementation support depth. Pricing pressure stems from Polish and Romanian manufacturing clusters demanding localized payroll functionality at lower price points. Freelancers and small Polish manufacturers exhibit the highest price sensitivity, while large German automotive groups under DORA mandates show the lowest.
Supply Chain Analysis
Logistics and freight costs for on-premises hardware shipments concentrate supply chain leverage among German, Irish, and Dutch distribution hubs serving continental deployment. The vendor ecosystem draws from cloud infrastructure providers, specialized compliance certification auditors, and API banking connectivity specialists concentrated in London, Frankfurt, and Amsterdam. Single-source vulnerability sits with hyperscaler concentration for cloud-native platforms. Distribution runs through direct vendor sales teams for enterprise accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe accounting software market compounds steadily as regulatory compliance mandates force recurring upgrade cycles across German, French, and British procurement offices.
For Market Incumbents: Deploy DORA pre-certification as a competitive moat against modular challengers. SAP and Oracle NetSuite should deepen ERP integration investments to extend switching friction beyond 24 months in DACH markets. Incumbents must acquire Polish and Romanian payroll specialists before regional champions consolidate localized compliance engines.
For New Entrants and Emerging Players: Begin with CSRD carbon accounting modules for large French pharmaceutical distributors seeking integrated sustainability reporting. Polish manufacturing clusters present the most penetrable white space due to decades of underinvestment in localized labor code functionality. A channel partnership strategy with Randstad region accounting firms accelerates Benelux market entry.
For Investors and Strategic Acquirers: Consolidation pressure builds where compliance certification costs exceed standalone vendor R&D budgets. The market supports a 5-10 year compounder thesis anchored by recurring regulatory upgrade cycles. Target acquisition archetypes include Polish payroll specialists with jurisdiction-specific social contribution engines and British open banking API connectivity providers. Watch for EU e-invoicing standardization mandates as the signal triggering accelerated M&A timing.
| Strategic Initiative | Industry Significance |
|---|---|
| DORA Compliance Certification | Pre-certification with BaFin and ACPR creates procurement preference in German and French RFPs. |
| Acquisition of Payroll Specialist | Polish and Romanian labor code expertise unlocks under-served Central European manufacturing clusters. |
| Open Banking API Integration | Native connectivity with ECB and Bank of England payment rails compresses implementation windows. |
| CSRD Module Development | Carbon accounting integration with financial statements commands premium pricing from Parisian enterprise buyers. |
| Channel Partnership Expansion | Alliance with Dutch accounting practices accelerates subscription unbundling adoption in Benelux markets. |
Research Methodology
Multiple input streams — primary interviews with CFOs and finance directors, technical consultations with platform engineers, and structured surveys of IT procurement officers — were reconciled against regulatory filings from BaFin, ACPR, and the Dutch Central Bank. Secondary validation incorporated SEC filings from listed software vendors, EU Digital Finance Platform disclosures, and trade data from Eurostat ICT sector reports. Bottom-up vendor revenue aggregation and top-down IT spending allocation were triangulated to cross-check segment sizing.
Data-stream reconciliation across deployment models, organization size tiers, and solution modules shaped the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory mandate timing. Forecast inputs included DORA compliance deadline schedules, EU e-invoicing standardization progress, and cross-border workforce expansion patterns tracked through Eurostat labor mobility statistics.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments, hyperscaler pricing discontinuities, and geopolitical disruptions to cloud infrastructure access. Forecasts reflect assumptions about steady regulatory enforcement and continuous open banking API expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
Global Sales Tax Compliance Software Market
Accounting and Taxation Services
Global Auditing Services Market
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
China Forensic Accounting Market
Accounting and Taxation Services
Tax Compliance Services Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Tax Management Software Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
UAE Forensic Accounting Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
Cloud Accounting Software Market
Accounting and Taxation Services
Finance and Accounting Outsourcing (FAO) Market
Accounting and Taxation Services
Hydrocarbons Accounting Solution Market
Accounting and Taxation Services
Tax Software Market