
 Germany Accounting Software Market | 2026-2036
Germany Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Accounting Software Market Insights
The reseller and advisor channel is reshaping how accounting software reaches German businesses. sevDesk leverages its domestic origin to sustain strong relationships with tax consultants who recommend solutions to clients. Odoo competes through open-source modularity that extends across ERP-adjacent functions. Xero positions its cloud-native architecture to occupy the mid-market segment where legacy migrations accelerate.
Germany accounting software encompasses digital platforms that automate bookkeeping, tax preparation, payroll, and financial reporting in compliance with local commercial and tax codes, typically supporting DATEV-compatible data formats and GoBD-conformant archiving. Cloud-based software leads deployment preferences as German businesses prioritize remote accessibility and automatic regulatory updates over on-premise maintenance burdens. SaaS solutions capture expanding margin pools through recurring revenue models, while desktop software retains footholds among established accounting firms with legacy infrastructure investments. API integration grows fastest as enterprises demand seamless connectivity between accounting platforms and banking, e-commerce, and tax authority systems.
The Federal Ministry of Finance enforces GoBD requirements that dictate digital document integrity and audit-proof storage, directly shaping product development roadmaps for compliance features. DATEV standards and BSI IT-Grundschutz cybersecurity guidelines further constrain market access for non-compliant vendors. Stakeholders must monitor how Germany's e-invoicing mandates and real-time reporting pilots redefine integration requirements and procurement criteria across buyer segments.
Market Dynamics
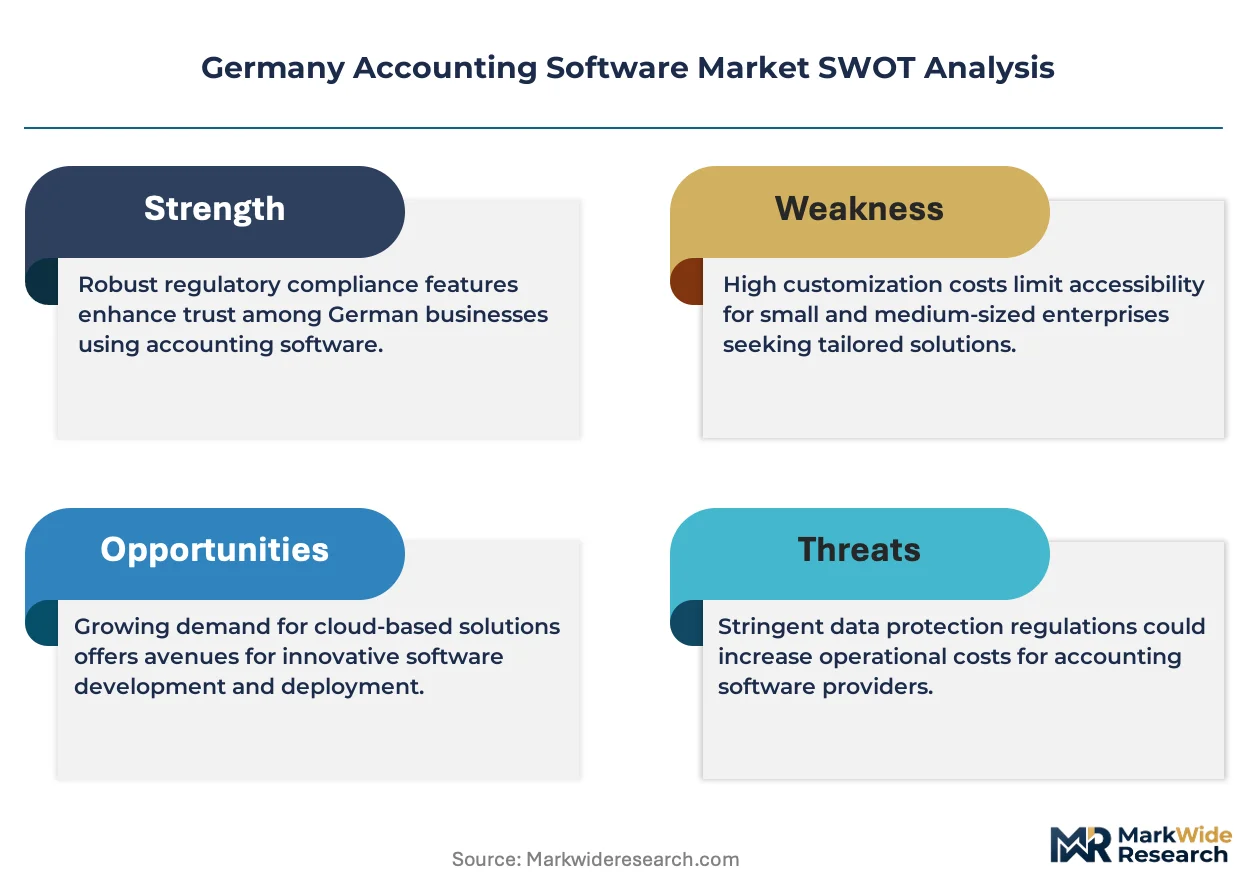
The Mittelstand's migration from desktop legacy systems to cloud-native architectures constitutes the dominant structural force reshaping competitive positioning in Germany's accounting software sector. This transition compresses implementation cycles while elevating compliance automation from feature to purchase prerequisite.
Growth Catalysts
- GoBD Mandate:The Federal Ministry of Finance's digital audit trail requirements force software procurement decisions toward vendors with native compliance architectures, eliminating non-conforming alternatives from consideration sets.
- SME Cloud Migration:German small and medium enterprises prioritize subscription models that externalize regulatory update maintenance, converting capital expenditure into predictable operational outflows.
- DATEV Integration:Tax consultant workflows demand seamless data handoffs between client bookkeeping systems and the dominant tax preparation infrastructure, privileging software with certified interoperability.
Market Restraints
- BSI IT-Grundschutz Certification:Federal cybersecurity standards impose multi-quarter validation timelines that delay product launches and elevate development overhead for non-domestic vendors.
- Legacy Infrastructure Lock-in:Established accounting firms with decades of on-premise data accumulation face prohibitive migration costs that suppress replacement demand in the professional services segment.
- Specialized Talent Scarcity:The intersection of German commercial code expertise and cloud engineering capability concentrates in North Rhine-Westphalia, creating recruitment bottlenecks for vendors outside that corridor.
Strategic Opportunities
- E-Invoicing Mandate Expansion:Federal pilots for real-time tax authority reporting will require API-first architectures that incumbent desktop vendors cannot retrofit, opening substitution windows.
- Baden-Württemberg Manufacturing Belt:Industrial clusters with complex multi-entity structures remain underpenetrated by standardized SaaS offerings, rewarding configurable platform approaches.
- Embedded Finance Convergence:Integration between accounting platforms and banking APIs creates new revenue pools through payment processing and working capital products adjacent to core bookkeeping.
Industry Challenges
- GoBD Interpretation Variance:Regional tax offices apply document integrity standards inconsistently, forcing vendors to maintain multiple compliance pathways and support documentation.
- Mid-Market Expectation Compression:Buyers in the 50-500 employee segment demand enterprise-grade functionality at SMB price points, squeezing margin structures across the vendor base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Accounting Software Market |
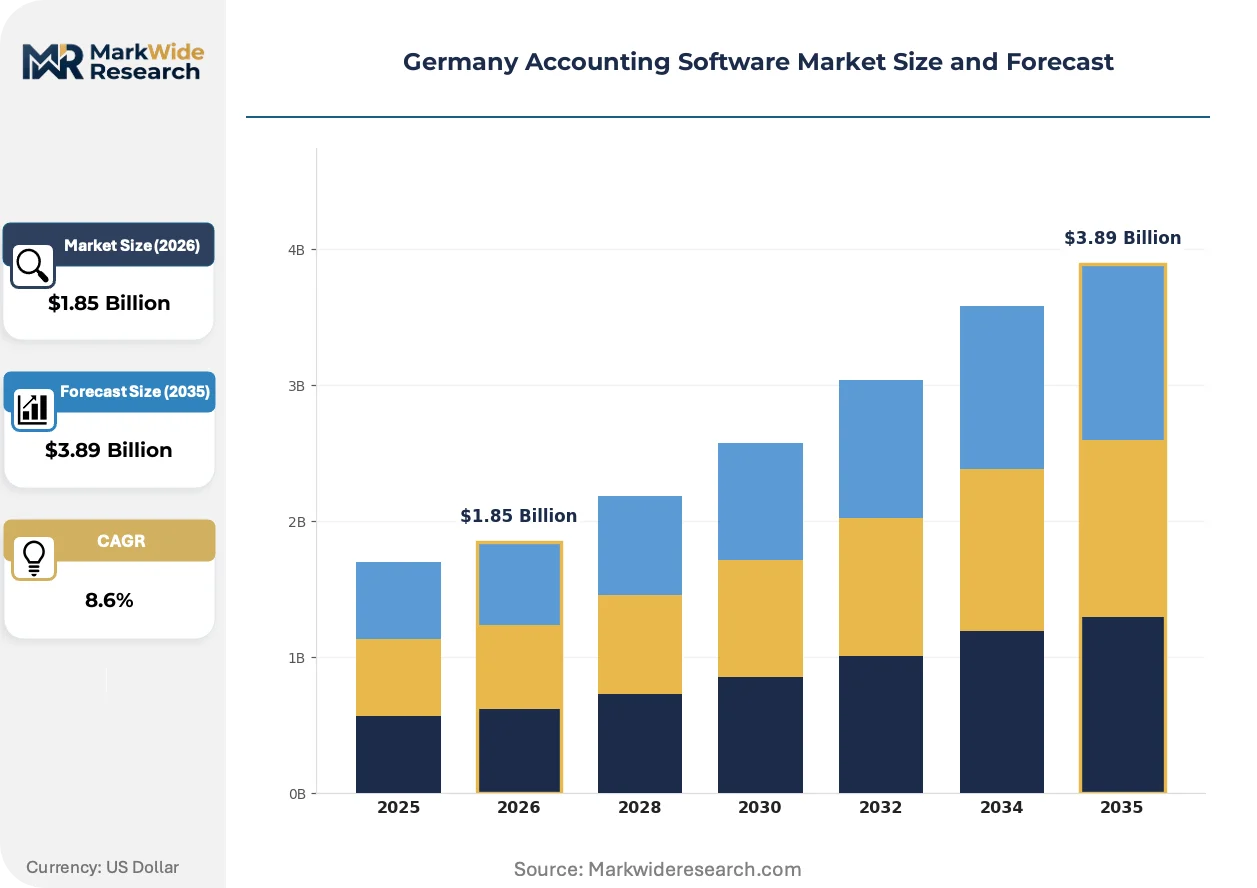
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Cloud-based Software, SaaS Solutions, Mobile Applications Deployment Model: On-premise, Private Cloud, Public Cloud, Hybrid Cloud End User: SMEs, Large Enterprises, Freelancers, Accounting Firms Integration Level: API Integration, Third-party Integration, Native Integration, Others |
| Companies Covered | Sage 50cloud, sevDesk, Xero, Candis, FastBill, FreshBooks, Odoo, Epicor Software, Zoho Books, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Accounting Software Market Trends and Innovations
Artificial intelligence is penetrating core bookkeeping functions, compressing the traditional role of manual data entry while elevating anomaly detection and predictive analytics to standard features. This technological insertion redefines skill requirements for accounting professionals and procurement criteria for software selection.
Machine learning algorithms trained on German commercial code patterns are virtualizing the reconciliation and categorization workflows that previously consumed the majority of bookkeeper hours. Mid-sized manufacturing enterprises in the Mittelstand belt are adopting these capabilities fastest, driven by labor cost pressures and the complexity of multi-currency operations. The technology is virtualizing the distinction between transactional processing and analytical finance, forcing vendors to reposition core offerings around advisory enablement rather than automation alone.
Germany's advancing e-invoicing requirements under EU VAT reform directives are mandating structured data exchange formats between trading partners and tax authorities. The Federal Ministry of Finance's phased rollout creates compliance cliffs that synchronize replacement cycles across buyer segments. Software vendors with pre-built Peppol network connectivity and ZUGFeRD format support capture disproportionate consideration in public sector and large enterprise procurement processes.
Channel relationships between software vendors and tax consulting practices are restructuring how purchasing decisions occur in the SME segment. Traditional direct sales models yield to advisor-mediated recommendations where Steuerberater function as gatekeepers with concentrated influence over client technology stacks. This pattern concentrates most intensely in Bavaria and Hesse, where dense networks of independent tax practices maintain strong client loyalty and technology advisory roles.
Germany Accounting Software Market Segmentation
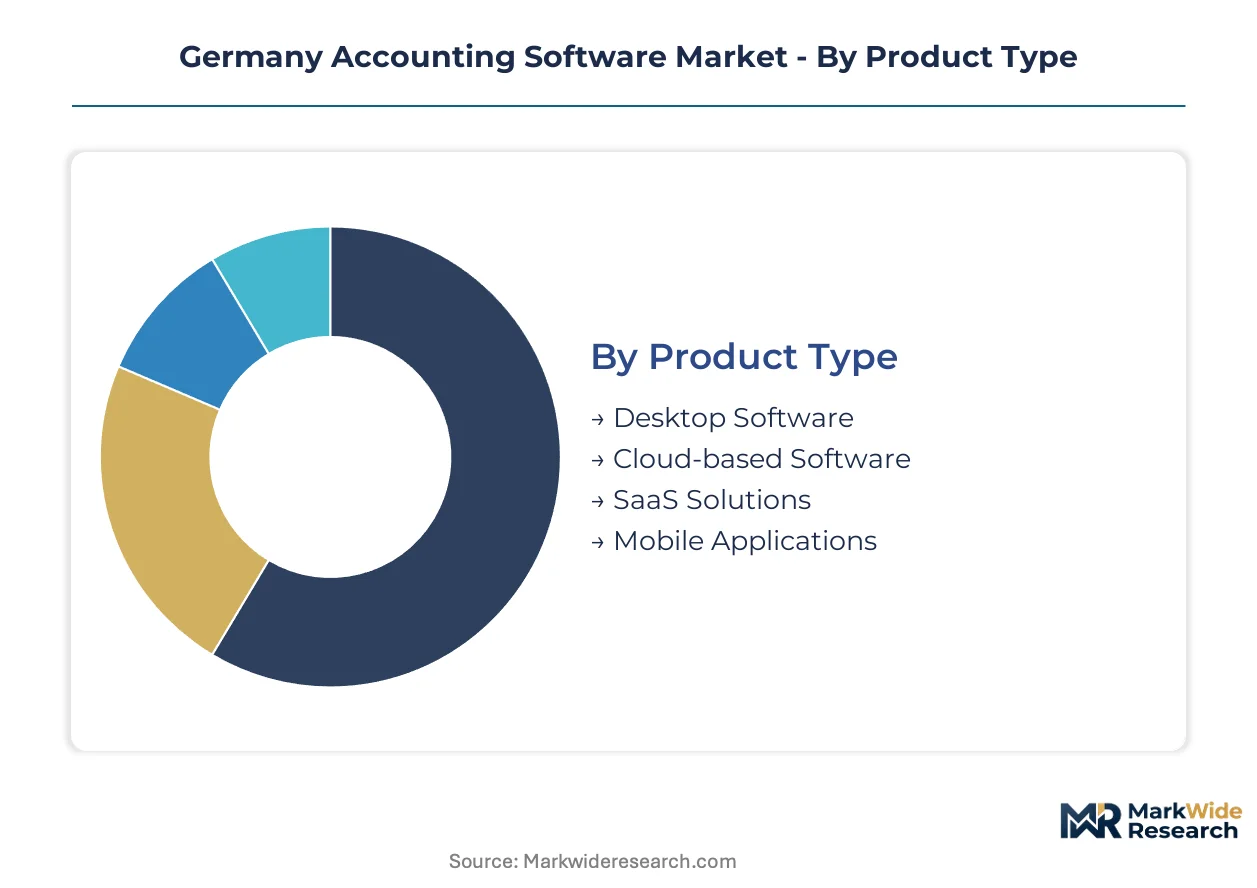
Germany's accounting software market fragments across product architectures, infrastructure choices, and buyer sophistication levels. Segmentation reveals where GoBD compliance investments concentrate and which deployment models capture Mittelstand migration budgets.
Product Type:
The use-case spectrum spans legacy desktop installations through mobile-first expense capture, with compliance architecture determining viability across buyer tiers.
- Cloud-based Software:Browser-accessible platforms with automatic regulatory updates and multi-user collaboration. North Rhine-Westphalia manufacturing SMEs prioritize these for remote accessibility and GoBD-conformant archiving without on-premise server maintenance.
- SaaS Solutions:Subscription-delivered applications with tiered feature access and API extensibility. Baden-Württemberg industrial clusters favor configurable platforms that scale across multi-entity structures without custom development.
- Desktop Software:Locally installed applications retaining footholds among established Steuerberater practices with decades of legacy data accumulation.
- Mobile Applications:Receipt capture and expense logging tools extending core platforms into field workflows.
Established volume favors Desktop Software; emerging adoption favors Cloud-based Software.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premise ownership from operational expenditure models externalizing compliance maintenance.
- Public Cloud:Shared infrastructure with automatic scaling and vendor-managed security patching. Freelancers and micro-enterprises in Hesse select these for minimal upfront investment and DATEV-compatible backup automation.
- Private Cloud:Dedicated tenant environments with customizable security controls. Bavarian accounting firms handling sensitive client data mandate these for BSI IT-Grundschutz alignment and audit trail isolation.
- Hybrid Cloud:Mixed architectures preserving sensitive operations on-premise while leveraging cloud elasticity for reporting workloads.
- On-premise:Fully self-managed installations retaining relevance where data sovereignty requirements block external hosting.
Public Cloud captures fastest volume expansion; Private Cloud commands highest per-seat pricing.
End User:
Customer type determines feature complexity requirements and sales channel strategy across Germany's fragmented buyer landscape.
- SMEs:50-500 employee businesses requiring automated tax calculation, payroll integration, and multi-bank reconciliation. These buyers concentrate procurement decisions through Steuerberater recommendations in Bavaria and North Rhine-Westphalia.
- Accounting Firms:Steuerberater and Buchhaltung practices demanding batch client management, DATEV export standardization, and white-label reporting capabilities.
- Large Enterprises:Complex multi-subsidiary structures with custom ERP integration requirements and dedicated compliance teams.
- Freelancers:Solo operators prioritizing simplified invoicing, mileage tracking, and ELSTER tax portal connectivity.
SMEs generate highest absolute seat volume; Accounting Firms drive ecosystem standardization.
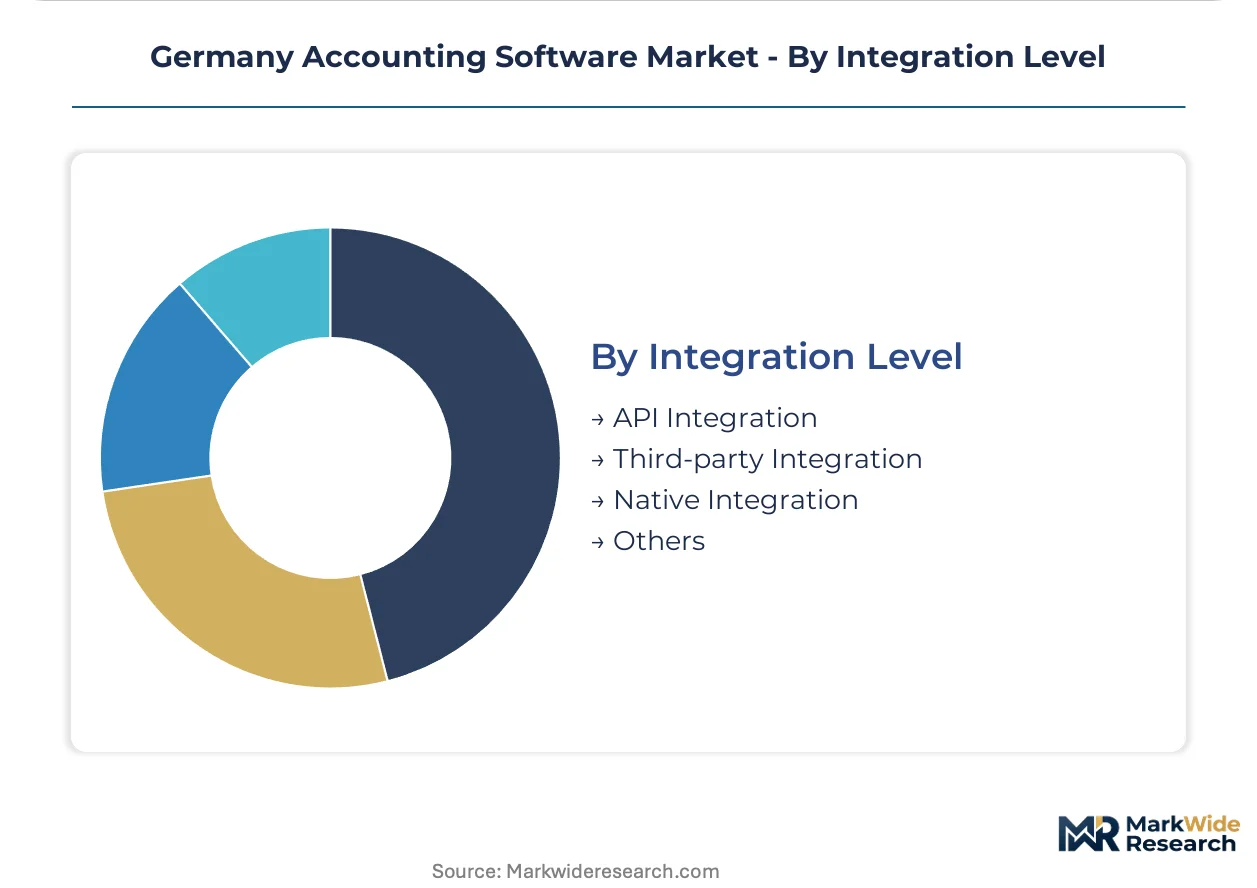
Integration Level:
Connectivity maturity separates basic data import tools from real-time API architectures enabling embedded finance convergence.
- API Integration:Real-time programmatic connections between accounting platforms and banking, e-commerce, and tax authority systems. Manufacturing enterprises in Baden-Württemberg require these for automated payment reconciliation and inventory valuation synchronization.
- Third-party Integration:Pre-built connectors to common business applications reducing custom development requirements.
- Native Integration:Vendor-proprietary module extensions within unified platform ecosystems.
- Others:Manual file import workflows and legacy format conversions.
Third-party Integration represents current procurement default; API Integration is climbing the fastest as e-invoicing mandates advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region's dense fiber backbone and data center concentration underwrites North Rhine-Westphalia's dominance in German accounting software demand. This infrastructure asset positions the state as the primary gateway for cloud-native financial tool deployment across the industrial Mittelstand belt.
North Rhine-Westphalia
Manufacturing SMEs in the Ruhr industrial corridor drive concentrated procurement of GoBD-compliant cloud platforms. The Federal Ministry of Finance's digital audit trail requirements synchronize replacement cycles among engineering subcontractors. Dortmund and Essen host dense clusters of metalworking and machinery firms migrating from DATEV-compatible desktop legacy systems to browser-accessible architectures with automatic regulatory updates.
Bavaria
Munich's technology sector and Nuremberg's manufacturing base generate bifurcated demand patterns across enterprise and mid-market segments. Steuerberater networks in Bavaria maintain exceptional influence over client technology selections, privileging vendors with certified tax consultant channel programs. The state's automotive supply chain concentrates in Ingolstadt and Regensburg, where multi-entity manufacturers require configurable platforms for complex consolidation workflows.
Baden-Württemberg
Stuttgart's machinery builders and Karlsruhe's software ecosystem create distinctive procurement criteria around ERP-adjacent integration. The state's Mittelstand manufacturers prioritize API-first architectures that synchronize inventory valuation with financial reporting. GoBD interpretation variance across regional tax offices forces vendors to maintain multiple compliance documentation pathways for industrial clients in the Black Forest precision engineering cluster.
Hesse
Frankfurt's financial services density and Wiesbaden's administrative concentration shape demand for BSI IT-Grundschutz-aligned private cloud deployments. Freelancers and micro-enterprises in the Rhine-Main metropolitan area select public cloud solutions for minimal upfront investment and ELSTER portal connectivity. The state's position as Germany's banking hub elevates embedded finance convergence as a procurement priority for fintech-adjacent professional services firms.
Berlin-Brandenburg
The capital region's startup ecosystem and government agency procurement generate divergent demand profiles across innovative and compliance-heavy segments. E-invoicing mandate pilots from the Federal Ministry of Finance accelerate API integration requirements among SaaS-native businesses in Berlin's technology corridor. Potsdam's public sector concentration sustains demand for on-premise installations where data sovereignty requirements block external hosting arrangements.
Germany Accounting Software Market Competitive Landscape
On the supply side, the industry is fragmented across domestic specialists, international SaaS platforms, and open-source modular providers competing through differentiated channel strategies. Three archetypes dominate: tax consultant-aligned domestic vendors, cloud-native international entrants, and ERP-integrated platform specialists. Competitive moves concentrate on advisor relationship cultivation and API ecosystem expansion rather than direct price confrontation.
Within the domestic specialist tier, sevDesk leverages its German origin to anchor tax consultant-mediated distribution. Xero occupies the cloud-native mid-market position where legacy migration accelerates. Odoo exemplifies the open-source modular approach extending across ERP-adjacent functions. These three represent distinct strategic postures rather than direct substitutes, with sevDesk emphasizing Steuerberater relationships, Xero prioritizing remote accessibility, and Odoo delivering configurability for multi-entity structures.
| Leading Market Players |
|---|
| Sage 50cloud |
| sevDesk |
| Xero |
| Candis |
| FastBill |
| FreshBooks |
| Odoo |
| Epicor Software |
| Zoho Books |
| Others |
Pricing and Supply Chain Analysis
North Rhine-Westphalia's data center concentration and tax consultant network density anchor pricing power for GoBD-compliant platforms serving the Mittelstand belt. Vendors with certified DATEV interoperability command premium positioning through advisor-mediated distribution channels that externalize compliance validation costs.
Pricing Analysis
Volume-discount tiering structures separate enterprise multi-seat deployments from freelancer entry points, with per-seat pricing compressing as organization scale increases. Price differentiation rests on GoBD certification depth and API integration maturity, with BSI IT-Grundschutz-aligned private cloud offerings capturing 40-60% premiums over public cloud equivalents. Pricing pressure stems from mid-market buyers demanding enterprise functionality at SMB price points, squeezing margin structures across the vendor base. Freelancers and micro-enterprises exhibit highest price sensitivity, while Bavarian manufacturing SMEs with multi-entity complexity demonstrate lowest elasticity for configurable platforms.
Supply Chain Analysis
Export-control regimes around cryptographic modules and data residency technologies constrain cross-border software licensing flows into German financial services deployments. Core development capacity concentrates in Germany, Ireland, and Estonia, with cloud infrastructure provisioning drawing from Frankfurt, Amsterdam, and Stockholm hyperscaler regions. Supply chain risk centers on single-source vulnerability for DATEV-certified interoperability modules that gate market access. Distribution runs through Steuerberater-mediated recommendations rather than direct vendor sales, concentrating channel control among Bavarian and Hesse tax consultant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's accounting software sector sits at a platform-economics inflection where API-first architectures displace legacy desktop distribution, with e-invoicing mandate convergence and embedded finance integration redefining competitive moats around ecosystem lock-in rather than feature depth.
For Market Incumbents: Pre-empt substitution threats from modular ERP platforms by deepening DATEV channel exclusivity through co-developed compliance automation tools. Anchor defensive positioning with backward integration into tax authority API infrastructure, capturing real-time reporting pilot participation before open-banking entrants replicate connectivity. Prioritize Bavarian and North Rhine-Westphalia advisor network lock-in as the primary retention lever against cloud-native challengers. For New Entrants and Emerging Players: Build out white-space penetration in Baden-Württemberg's precision engineering cluster, where multi-entity manufacturers remain underserved by standardized SaaS offerings lacking API synchronization with inventory systems. Target the 50-200 employee manufacturing segment with pre-configured GoBD compliance pathways that regional tax offices accept without interpretation variance. Establish go-to-market through embedded finance partnerships with cooperative banks serving the Black Forest industrial belt. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with pre-built Peppol network connectivity and ZUGFeRD format support that capture disproportionate consideration in public sector procurement. Long-term viability across the analysis window hinges on regulatory update automation capabilities that externalize compliance maintenance for SME buyers. Watch for e-invoicing mandate acceleration signals from the Federal Ministry of Finance as the inflection indicator for replacement cycle synchronization across buyer segments.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Pre-built Peppol connectivity captures public sector procurement preference under advancing e-invoicing mandates. |
| Tax Consultant Channel Partnership | Steuerberater-mediated distribution externalizes compliance validation costs in Bavaria and Hesse networks. |
| Embedded Finance Convergence | Banking API integration creates adjacent revenue pools through payment processing and working capital products. |
| GoBD Compliance Automation Investment | Native audit trail architectures eliminate non-conforming alternatives from SME consideration sets. |
| Multi-Entity Configuration Expansion | Baden-Württemberg manufacturing clusters reward platforms scaling across complex consolidation workflows. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, DATEV certification registries, and Federal Ministry of Finance regulatory bulletins. Interviews with CTOs at Mittelstand manufacturers, Steuerberater practice partners, IT procurement officers, and platform integration specialists informed demand-side validation. Bottom-up seat deployment estimates triangulate against top-down SaaS revenue aggregation across the analysis window.
Forecast inputs incorporate deployment model segmentation by organization size, vertical concentration in manufacturing belts, integration complexity tiers, and regional adoption patterns shaped by tax office interpretation variance. CAGRs derive from modeled replacement cycle synchronization around compliance mandate cliffs and elasticity-adjusted pricing trajectories. E-invoicing pilot progression and BSI IT-Grundschutz certification timelines anchor scenario-weighted projections.
Practitioners should monitor Federal Ministry of Finance e-invoicing mandate acceleration, regional GoBD interpretation convergence, and embedded finance partnership announcements for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Global Tax and Accounting Software Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
China Accounting & Budgeting Software Market
Accounting and Taxation Services
Europe Forensic Accounting Market
Accounting and Taxation Services
Construction Accounting Software Market
Accounting and Taxation Services
Saudi Arabia Forensic Accounting Market
Accounting and Taxation Services
Global Business Accounting Software Market
Accounting and Taxation Services
Small Business Accounting Software Market
Accounting and Taxation Services
Canada Forensic Accounting Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Sales Tax Software Market