
 Israel Telecom Market | 2026-2036
Israel Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Telecom Market Outlook
A capital-intensity divergence between fiber-rich incumbents and lean mobile challengers is redrawing the competitive map of Israeli telecommunications. Bezeq The Israel Telecommunication Corp Ltd leverages its legacy copper-to-fiber footprint to dominate fixed-line broadband economics. Cellcom Israel Ltd sustains aggressive 5G rollout spending to anchor wireless market relevance. Partner Communications differentiates through enterprise-focused managed service bundles that command higher contract values.
Israeli telecom encompasses the transmission of voice, data, and video across wired and wireless infrastructure operating at frequencies from 700 MHz to 28 GHz and fiber wavelengths of 1310–1550 nm, serving as the backbone for national commerce, defense communication, and digital government services. Mobile Services and 5G technology together capture the fastest expansion as spectrum efficiency gains and low-latency requirements reshape enterprise procurement criteria. Fiber Optics deployment to residential and Large Enterprise end users commands the deepest margin pools due to long contract tenures and lower churn propensity relative to wireless-only provisioning.
The Ministry of Communications governs licensing and spectrum allocation, while the Israel Securities Authority oversees financial disclosures for publicly traded carriers, and the National Cyber Directorate mandates security standards for critical infrastructure operators. These frameworks shape demand by conditioning market entry on cybersecurity certification and requiring universal service obligations in peripheral regions. Stakeholders must monitor spectrum auction timing and wholesale access rulings that will determine whether challenger operators can sustain price pressure on established players.
Market Dynamics
The Ministry of Communications' 5G spectrum allocation framework is compressing infrastructure modernization timelines, forcing carriers to accelerate capex cycles while cybersecurity mandates from the National Cyber Directorate raise operational complexity for critical infrastructure operators.
Growth Catalysts
- Cybersecurity Enterprise Demand:Israeli firms deploying zero-trust architectures into communications infrastructure are expanding managed service contract values and extending fiber deployment timelines.
- Spectrum Efficiency Mandates:The Ministry of Communications' allocation framework is accelerating 5G base station densification requirements in metropolitan corridors.
- Startup Density Concentration:Tel Aviv's metropolitan technology corridor generates premium connectivity procurement that outpaces national average spending per endpoint.
Market Restraints
- Fiber Deployment Cost Structure:Last-mile trenching expenses in dense urban zones and rocky peripheral terrain constrain challenger operator expansion economics.
- Spectrum Concentration Risk:Limited 3.5 GHz and 26 GHz license availability creates asymmetric capacity allocation between incumbent and mobile-first challengers.
- Copper Legacy Technical Limitation:Bezeq's aging DSL infrastructure in peripheral towns caps achievable speeds below fiber-competitive thresholds.
Strategic Opportunities
- Peripheral Region Underpenetration:Negev and Galilee sub-regions exhibit sub-40% fiber-to-the-home coverage, creating whitespace for infrastructure co-investment models.
- Defense Communication Convergence:Dual-use 5G private networks integrating military-grade encryption standards with commercial spectrum are opening classified contract channels.
- Wholesale Access Regulatory Tailwind:Pending infrastructure unbundling rulings from the Ministry of Communications may force fiber incumbent network sharing.
Industry Challenges
- 5G Radio Frequency Engineering Talent Gap:mmWave propagation modeling and massive MIMO optimization skills command premium wages that strain challenger R&D budgets.
- Legacy Billing Integration Complexity:Migration from circuit-switched voice accounting to cloud-native subscription platforms requires multi-year system reconciliation.
- Cybersecurity Certification Timeline:National Cyber Directorate critical infrastructure audits extend 14-18 months, delaying service launches for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Telecom Market |
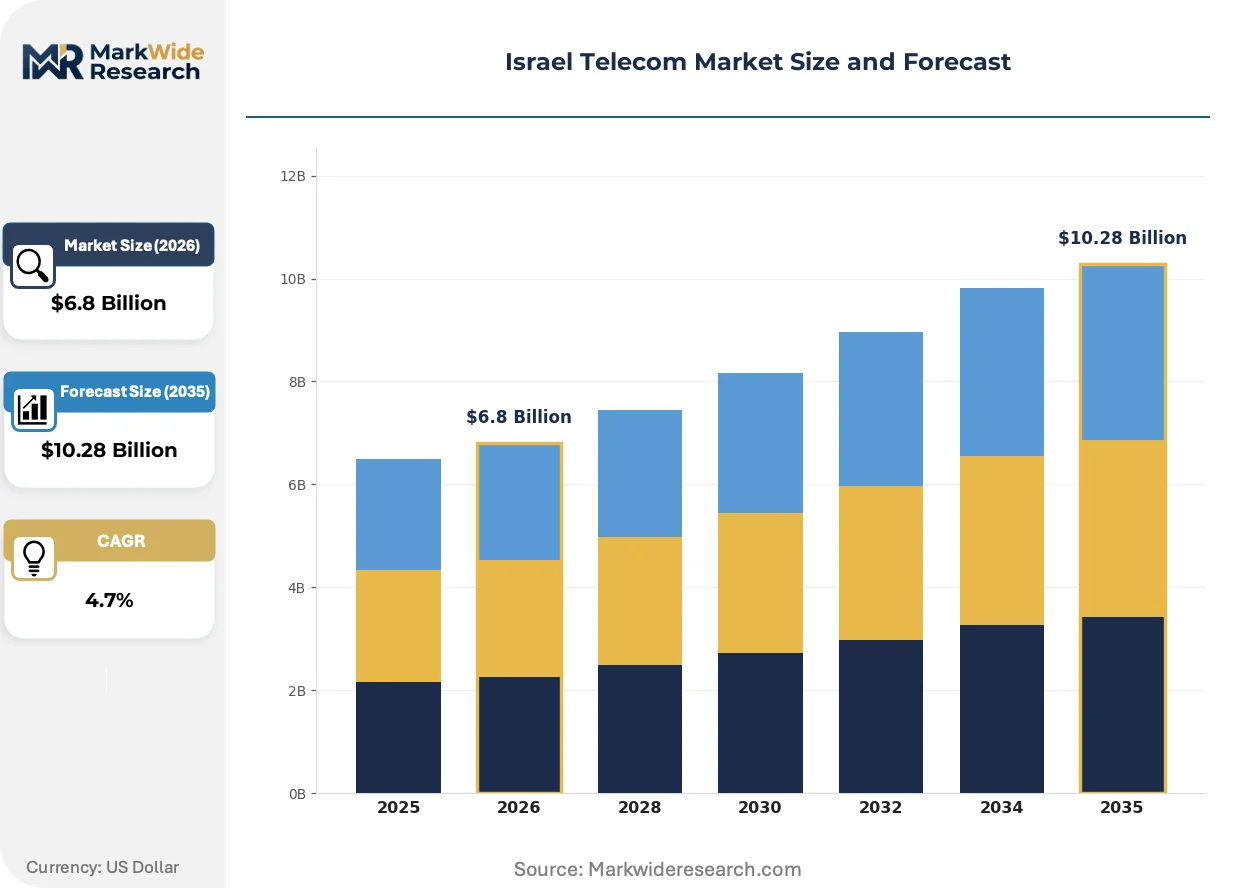
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-Line Services, Internet Services, VoIP Services Technology: 4G LTE, 5G, Fiber Optics, Satellite End User: Residential, Small Business, Large Enterprise, Government Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Bezeq The Israel Telecommunication Corp Ltd, Cellcom Israel Ltd, Pelephone, Partner Communications, Hot Mobile, Golan Telecom, Bezeq International, B Communications Ltd, 012 Smile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Telecom Market Strategic Shifts
Open RAN architectures are fragmenting vendor lock-in structures, enabling multi-supplier base station deployments that reduce single-source dependency for Israeli mobile operators.
Virtualized radio access networks using containerized baseband processing is displacing proprietary hardware-centric deployment models. Cellcom and Partner Communications are piloting multi-vendor open interfaces in Tel Aviv metro cells. This shift is compressing equipment procurement cycles from 36-month refresh windows to 18-month software iteration schedules.
The National Cyber Directorate's critical infrastructure security standards are mandating encryption-at-rest for all carrier-grade voice and data transit. Equipment vendors must now certify hardware through Israeli-approved laboratories before Ministry of Communications licensing approval. Mobile operators are responding by segmenting network functions into air-gapped domains with independent security boundaries.
Enterprise buyers are consolidating communications procurement under single managed service agreements rather than discrete connectivity contracts. System integrators and carrier direct sales teams are displacing traditional telecom resellers in large-account acquisition. This pattern concentrates most visibly in Tel Aviv's cybersecurity and fintech verticals where compliance requirements favor unified vendor accountability.
Israel Telecom Market Segmentation
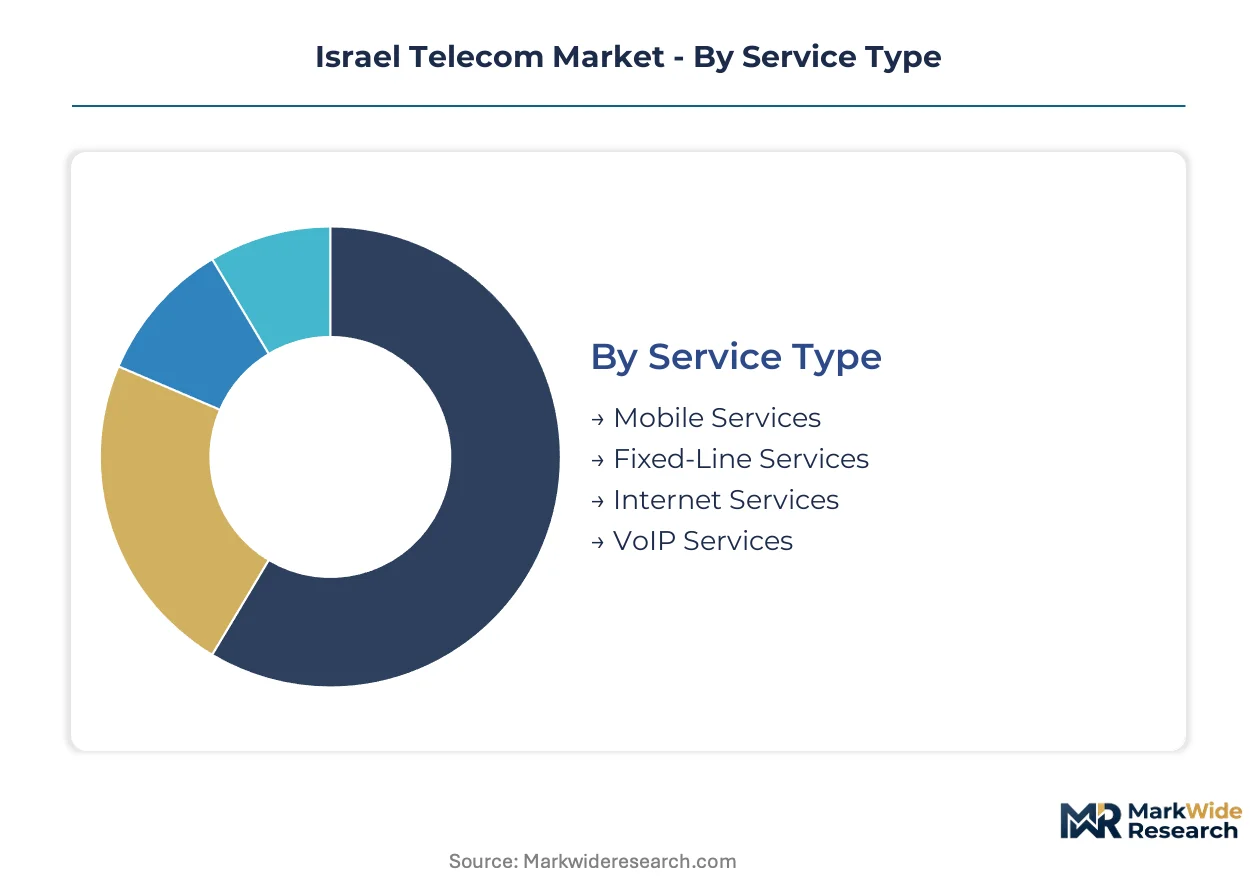
Segmentation in the Israeli telecom market reveals distinct margin architectures across service layers. Infrastructure-heavy categories command premium economics, while service-overlay segments compete on operational agility and cybersecurity integration.
Service Type:
Margin pools concentrate in subscription bundles that combine connectivity with managed security layers, particularly where enterprise procurement consolidates under single-vendor accountability.
- Mobile Services:Wireless voice and data transmission operating across 700 MHz to 28 GHz spectrum bands. Demand concentrates in Tel Aviv's technology corridor where startup density drives premium 5G procurement and zero-trust mobile security requirements.
- Fixed-Line Services:Copper and fiber-based voice connectivity delivered through legacy PSTN and modern IP infrastructure. The Negev and Galilee sub-regions exhibit sub-40% fiber-to-the-home penetration, creating whitespace for infrastructure co-investment models in peripheral towns.
- Internet Services:Broadband access provisioning across DSL, cable, and fiber technologies.
- VoIP Services:Packet-switched voice transmission replacing circuit-switched legacy systems.
The dominant share belongs to Mobile Services, while Internet Services is closing the gap fastest through fiber migration acceleration.
Technology:
Technology selection determines capital intensity trajectories and regulatory compliance burdens for Israeli carriers.
- 5G:New radio access technology enabling massive MIMO and network slicing for enterprise private networks. The Ministry of Communications' spectrum allocation framework is compressing base station densification timelines in metropolitan corridors.
- Fiber Optics:Glass-core transmission at 1310–1550 nm wavelengths delivering symmetric gigabit speeds. Large Enterprise end users in Tel Aviv's cybersecurity vertical command the deepest margin pools due to long contract tenures and encryption-at-rest compliance requirements.
- 4G LTE:Mature wireless standard providing coverage continuity during 5G transition.
- Satellite:Geostationary and low-earth orbit connectivity for remote coverage extension.
Fiber Optics holds the dominant share, while 5G is expanding most quickly through enterprise private network deployments.
End User:
End user segmentation maps directly to contract value tiers and cybersecurity certification requirements.
- Large Enterprise:National and multinational organizations with unified communications procurement. Demand clusters in Tel Aviv's fintech and cybersecurity verticals where compliance requirements favor single-vendor accountability.
- Government:Public sector and defense communication networks with classified security mandates. The National Cyber Directorate mandates encryption-at-rest and air-gapped network domains for critical infrastructure operators.
- Residential:Individual households consuming bundled connectivity and entertainment services.
- Small Business:SMEs with standardized connectivity needs and limited IT staff.
Large Enterprise captures the dominant share, while Government is gaining share fastest through dual-use 5G private network convergence.
Deployment Model:
Deployment architecture determines operational control distribution and capital expenditure timing for Israeli operators.
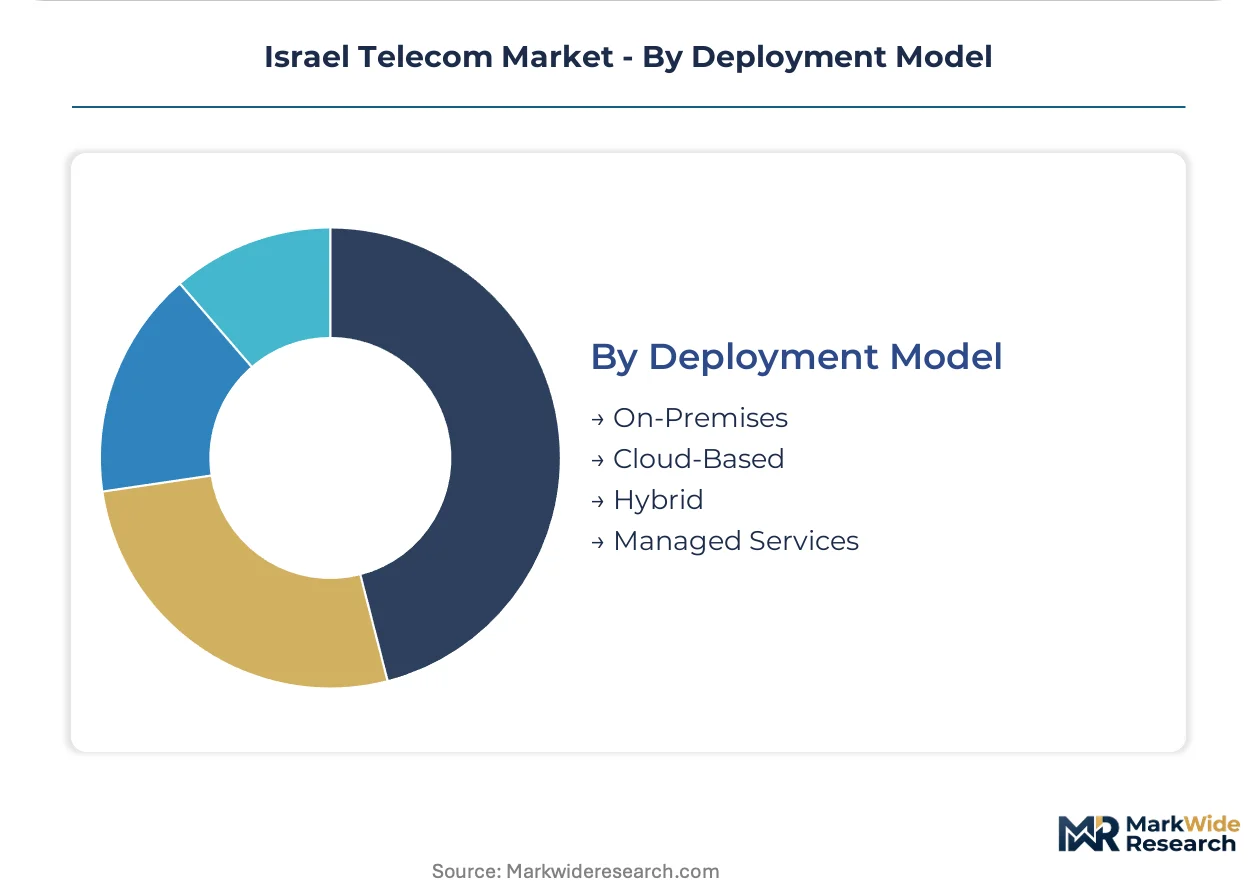
- Managed Services:Outsourced network operation and security monitoring under long-term contracts. Enterprise buyers in Tel Aviv's technology corridor are consolidating procurement under these agreements rather than discrete connectivity contracts.
- Hybrid:Mixed on-premises and cloud infrastructure with workload-specific placement. Cellcom and Partner Communications are piloting multi-vendor open interfaces in metro cells using this architecture.
- On-Premises:Customer-owned equipment with direct operational responsibility.
- Cloud-Based:Fully virtualized network functions delivered as subscription services.
Managed Services holds the dominant share, while Hybrid is climbing the fastest as Open RAN architectures fragment vendor lock-in structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Israeli sub-regions. Tel Aviv's technology corridor exhibits price-inelastic procurement for premium connectivity, while peripheral towns in the Negev and Galilee remain highly sensitive to subscription costs and infrastructure availability.
Tel Aviv Metropolitan Area
Cybersecurity and fintech enterprises drive premium 5G and fiber procurement with zero-trust architecture requirements. The Ministry of Communications enforces base station densification mandates in this corridor. Tel Aviv's startup density concentrates demand for managed service bundles with encryption-at-rest compliance.
Central District
Industrial zones and logistics hubs generate steady demand for private 5G networks and symmetric fiber connectivity. National Cyber Directorate audits apply to critical infrastructure operators in this region. Modi'in and Rehovot technology parks anchor enterprise connectivity procurement with long contract tenures.
Haifa and Northern District
Defense contractors and port logistics operations create specialized demand for dual-use communication networks. The Ministry of Communications' universal service obligations extend fiber deployment timelines to peripheral towns. Haifa's metropolitan cluster sustains above-average spending per endpoint for classified communication channels.
Jerusalem District
Government and educational institutions dominate procurement with security-certified connectivity requirements. National Cyber Directorate mandates air-gapped network domains for critical infrastructure in the capital. Jerusalem's technology corridor exhibits growing startup density driving premium service adoption.
Southern District and Negev
Sub-40% fiber-to-the-home coverage creates infrastructure whitespace with cost-sensitive residential demand. The Ministry of Communications' peripheral deployment incentives support challenger operator entry. Be'er Sheva's cybersecurity research cluster generates localized premium connectivity demand amid broader price sensitivity.
Israel Telecom Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Israeli telecom sector. Incumbent operators with legacy infrastructure dominate fixed-line economics through fiber-rich footprints, while mobile-first challengers compete on lean cost structures and aggressive 5G rollout speed. Three archetypes define competitive positioning: infrastructure-heavy incumbents, mobile-centric challengers, and enterprise-focused managed service specialists. Dominant competitive moves include spectrum acquisition at Ministry of Communications auctions and fiber infrastructure co-investment partnerships in underpenetrated regions.
Within the incumbent tier, Bezeq The Israel Telecommunication Corp Ltd anchors fixed-line market positioning through its copper-to-fiber infrastructure legacy. Cellcom Israel Ltd and Partner Communications occupy challenger positions, with the former exemplifying aggressive wireless capital deployment and the latter representing enterprise-managed service bundling. These three companies collectively illustrate the sector's divergence between infrastructure ownership and service-layer specialization.
| Leading Market Players |
|---|
| Bezeq The Israel Telecommunication Corp Ltd |
| Cellcom Israel Ltd |
| Pelephone |
| Partner Communications |
| Hot Mobile |
| Golan Telecom |
| Bezeq International |
| B Communications Ltd |
| 012 Smile |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month National Cyber Directorate certification timelines compress equipment procurement windows and concentrate pricing power among pre-approved vendor pools. This lead-time compression reinforces incumbent carrier advantages while forcing challenger operators to absorb premium costs for expedited security validation.
Pricing Analysis
Managed service contract extensions drive lifetime value capture in the Israeli telecom sector. Three-tier pricing structure across premium, standard, and economy levels segments enterprise buyers by cybersecurity certification requirements and fiber penetration depth. Price differentiation rests on National Cyber Directorate audit status and Ministry of Communications spectrum license tier. Cost compression in challenger mobile tiers is intensifying because Open RAN equipment procurement cycles have halved from thirty-six to eighteen months. Small businesses in peripheral Negev and Galilee sub-regions exhibit highest price sensitivity, while Tel Aviv cybersecurity enterprises demonstrate least sensitivity due to compliance-mandated procurement consolidation.
Supply Chain Analysis
China, South Korea, and Taiwan anchor baseband processor and optical transceiver manufacturing for Israeli carrier infrastructure. Equipment procurement draws from containerized radio access network hardware, fiber optic cable assemblies, and millimeter-wave antenna modules. Single-source vulnerability concentrates in 5G massive MIMO chipset supply where three vendors dominate global fabrication. Distribution runs through Ministry of Communications-licensed equipment integrators who manage National Cyber Directorate laboratory certification before network deployment authorization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Israeli telecom market functions as a regulatory-entrenchment defensive moat where Ministry of Communications licensing and National Cyber Directorate certification create asymmetric barriers to challenger expansion.
For Market Incumbents: Shield fiber-rich metropolitan footprints through accelerated copper-to-fiber migration in Tel Aviv's technology corridor before wholesale access rulings materialize. Deepen backward integration into optical cable manufacturing to offset equipment cost inflation from Asian supply concentration. Prioritize National Cyber Directorate pre-certification for network hardware to extend procurement lead-time advantages over mobile-first challengers.
For New Entrants and Emerging Players: Differentiate on Open RAN multi-vendor architectures that fragment incumbent supplier relationships and compress equipment refresh cycles. Target peripheral region fiber co-investment models in Negev and Galilee sub-regions where sub-forty-percent penetration creates whitespace outside incumbent universal service obligations. Pursue defense communication convergence contracts requiring dual-use 5G private networks with military-grade encryption standards.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because fiber-to-the-home deployment generates decade-plus contract tenures with lower churn propensity than wireless-only provisioning. Acquisition target archetype: enterprise-managed service specialists with National Cyber Directorate-certified operations and Tel Aviv cybersecurity vertical concentration. Monitor Ministry of Communications wholesale access rulings as inflection signal for challenger operator viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Multi-Vendor Deployment | Fragmenting vendor lock-in structures reduces single-source dependency for Israeli mobile operators. |
| Peripheral Fiber Co-Investment | Negev and Galilee sub-regions offer whitespace for infrastructure partnerships outside incumbent footprints. |
| Defense Communication Convergence | Dual-use 5G private networks integrate military-grade encryption with commercial spectrum allocation. |
| National Cyber Directorate Pre-Certification | Pre-approved equipment pools compress challenger procurement timelines and extend incumbent advantages. |
| Enterprise Managed Service Bundling | Single-vendor accountability contracts displace discrete connectivity procurement in Tel Aviv verticals. |
Study Parameters
Operator-level perspectives from network engineering directors, Ministry of Communications regulatory affairs leads, National Cyber Directorate security auditors, enterprise IT procurement managers, and fiber infrastructure project developers anchored the qualitative base. Primary interview findings triangulated against secondary sources including Ministry of Communications spectrum auction records, National Cyber Directorate security standard publications, Israel Securities Authority carrier financial disclosures, and equipment vendor certification databases. Bottom-up service revenue modeling and top-down national connectivity penetration estimates converged through iterative validation.
Sensitivity analysis tested forecast outputs against alternative spectrum allocation timelines and cybersecurity certification backlog scenarios across the analysis window. Segmentation dimensions modeled include service type, technology layer, end-user category, and deployment architecture complexity. CAGRs derived from subscriber growth trajectories, average revenue per user migration patterns, and infrastructure capital intensity curves specific to Israeli regulatory conditions and geographic deployment economics.
The analysis sits within stated boundaries; outcomes outside Ministry of Communications wholesale access rulings or National Cyber Directorate certification timeline shifts would require recalibration. Forecasts reflect documented assumptions regarding spectrum efficiency gains, fiber deployment cost curves, and enterprise procurement consolidation patterns. Recalibration cycles align with material shifts in regulatory framework timing or cybersecurity mandate evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market